
 Engineered Cell Therapy Market | 2026-2036
Engineered Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Engineered Cell Therapy Market Foresight
Asset-light contract development and manufacturing organization (CDMO) partnerships is narrowing the capital barrier for mid-stage biotech firms seeking commercial-scale cell therapy production. Novartis AG leverages its established Kymriah manufacturing footprint to sustain European and North American supply chains. Legend Biotech Corporation anchors its competitive position through vertical integration into plasmid and viral vector production. Bristol Myers Squibb Company differentiates via its diversified CAR T and TCR pipeline breadth across hematologic and solid tumor indications.
Engineered cell therapy comprises living therapeutic products manufactured through ex vivo genetic modification of autologous or allogeneic cells, typically involving lentiviral or electroporation-based gene transfer followed by expansion in bioreactor systems to achieve doses exceeding one hundred million cells per patient. CAR T-cell therapy occupies the dominant revenue position given established reimbursement for diffuse large B-cell lymphoma and acute lymphoblastic leukemia, while natural killer cell therapy represents the fastest-expanding segment as off-the-shelf manufacturing protocols reduce patient-matching complexity and production lead times. Oncology commands the primary application focus, though autoimmune disorders are attracting expanded clinical investment as CD19-directed cell therapies demonstrate durable responses in systemic lupus erythematosus.
The FDA's regenerative medicine advanced therapy (RMAT) designation and the EMA's priority medicines (PRIME) scheme compress development timelines and shape trial design requirements for sponsors targeting hematologic malignancies. The EU's Good Manufacturing Practice Annex 1 revision and the FDA's guidance on chemistry, manufacturing, and controls for gene therapy impose escalating cleanroom and vector qualification standards that favor firms with captive manufacturing infrastructure. Stakeholders must monitor allogeneic platform durability data and payer willingness to cover outpatient administration models as these variables determine the addressable patient pool beyond refractory hematologic cancers.
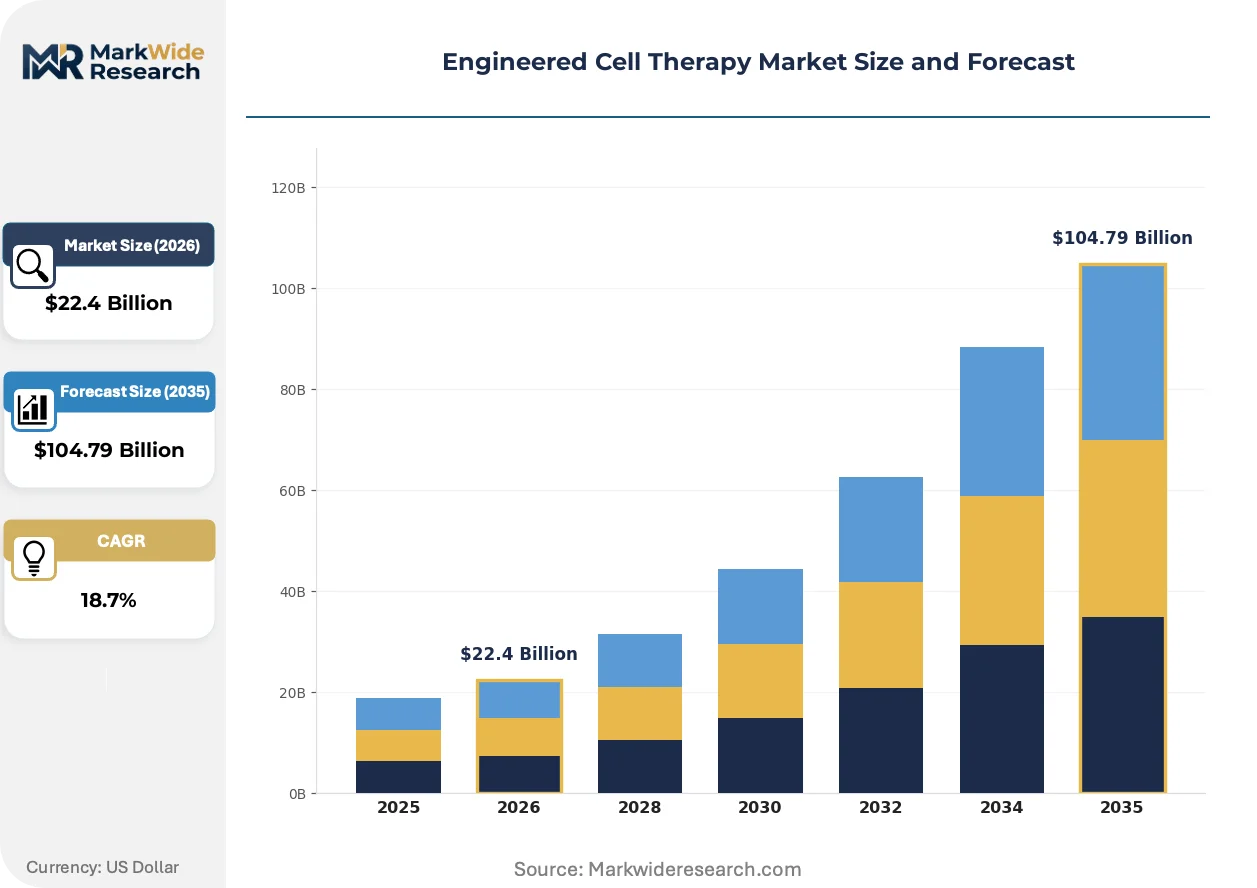
Market Dynamics
Allogeneic manufacturing platforms are compressing production timelines from weeks to days, forcing autologous-dependent firms to restructure supply chains or cede share in outpatient treatment settings.
Growth Catalysts
- RMAT Designation Acceleration:The FDA's regenerative medicine advanced therapy pathway compresses Phase 2-to-approval timelines for hematologic malignancy candidates, incentivizing sponsors to prioritize CAR T-cell submissions.
- Electroporation Equipment Diffusion:Non-viral gene transfer systems are displacing lentiviral dependency in clinical-scale manufacturing, reducing cleanroom qualification burdens and vector supply bottlenecks.
- Germany Manufacturing Clustering:Heidelberg and Munich treatment centers concentrate specialized apheresis capacity and GMP-compliant expansion facilities, anchoring EU patient access infrastructure.
Market Restraints
- Plasmid Supply Concentration:Three North American CDMOs control majority GMP-grade plasmid capacity, creating single-source vulnerability for viral vector producers.
- Annex 1 Compliance Escalation:The EU's revised Good Manufacturing Practice standards mandate continuous viable particle monitoring and barrier technology upgrades, raising facility capital requirements.
- Allogeneic Durability Uncertainty:Limited five-year follow-up data for off-the-shelf T-cell products constrains payer willingness to extend reimbursement beyond hematologic rescue indications.
Strategic Opportunities
- Japan Solid Tumor Expansion:PMDA's Sakigake designation offers priority review for CAR T-cell candidates targeting gastric and pancreatic cancers, opening Asia-Pacific oncology volume.
- Autoimmune Application Migration:CD19-directed therapy demonstrates durable remission in systemic lupus erythematosus, creating addressable patient pools outside oncology reimbursement frameworks.
- Point-of-Care Manufacturing:Decentralized bioreactor systems enable same-day vein-to-vein protocols, eliminating cryopreservation logistics and cold-chain infrastructure.
Industry Challenges
- Vector Bioprocess Talent Scarcity:GMP-grade lentiviral production requires hybrid skill sets spanning molecular virology and large-scale cell culture, with limited training pipeline capacity.
- Multi-Site IND Coordination:Sponsors running parallel US and EU trials face divergent chemistry-manufacturing-controls documentation requirements, extending regulatory submission preparation.
- Legacy Hospital Integration:Academic medical centers with established transplant infrastructure struggle to adapt workflows for outpatient CAR T-cell monitoring, delaying site activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineered Cell Therapy Market |
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $104.79 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAR T-Cell Therapy, TCR Therapy, Stem Cell Therapy, Natural Killer Cell Therapy End User: Hospitals, Research Institutions, Biotech Companies, Pharmaceutical Firms Application: Oncology, Autoimmune Disorders, Infectious Diseases, Cardiovascular Diseases Technology: Gene Editing, Cell Isolation, Cell Culture, Bioprocessing |
| Companies Covered | Novartis AG, Gilead Sciences, Inc., Bristol Myers Squibb Company, Legend Biotech Corporation, CRISPR Therapeutics AG, Bluebird Bio Inc., Allogene Therapeutics Inc., Atara Biotherapeutics, Inc., Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineered Cell Therapy Market Shifts & Advancements
Manufacturing modality competition is fragmenting competitive advantage sources, with viral vector efficiency, non-viral delivery precision, and allogeneic scale economics diverging as distinct capability axes.
Non-viral electroporation systems for mRNA and transposon delivery are rendering obsolete lentiviral dependency in clinical-scale T-cell engineering. Mid-stage biotech firms are adopting MaxCyte and Lonza platforms to circumvent GMP viral vector shortages. This shift compresses lead times from vector procurement to final product release by eliminating biosafety level 2 handling requirements.
The FDA's 2024 guidance on long-term follow-up for gene therapy products extends patient monitoring obligations to fifteen years post-treatment. Sponsors must now budget for registry infrastructure and adverse event surveillance systems. Hematologic oncology programs with established real-world evidence platforms are absorbing these costs more efficiently than solid tumor entrants.
Hospital procurement committees are unbundling CAR T-cell acquisition from inpatient bed-day packaging, forcing manufacturers to justify standalone pricing against alternative salvage regimens. US payers at centers in Texas and Florida are piloting episode-based reimbursement that excludes unrelated complication costs. This model rewards outpatient administration protocols and penalizes extended hospitalization.
Engineered Cell Therapy Market Segmentation
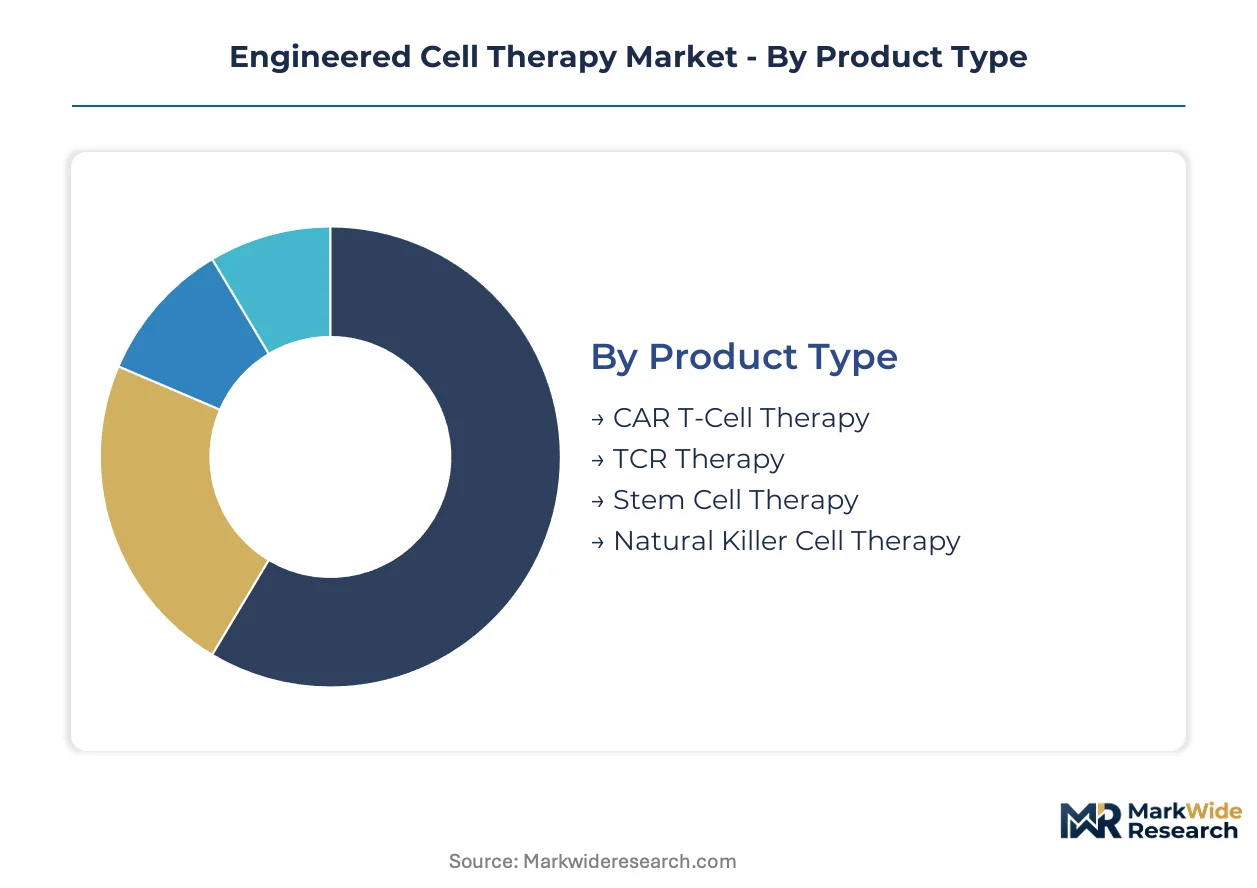
Segmentation in engineered cell therapy reveals divergent margin profiles and facility investment requirements across product modalities. Each category exposes distinct regulatory pathways, manufacturing scale economies, and customer concentration patterns that determine competitive positioning.
Product Type:
After-sales service intensity varies dramatically across modalities, with autologous platforms demanding patient-specific logistics support while allogeneic products shift burden toward quality assurance and batch release documentation.
- CAR T-Cell Therapy:Autologous chimeric antigen receptor T-cells require lentiviral or electroporation-based genetic modification followed by patient-matched expansion. Demand concentrates in the United States and Germany where specialized apheresis centers and FDA/EMA-accredited manufacturing facilities cluster around academic medical centers treating diffuse large B-cell lymphoma.
- Natural Killer Cell Therapy:Allogeneic NK cell platforms bypass patient-matching complexity through off-the-shelf manufacturing from umbilical cord blood or induced pluripotent stem cell banks. Momentum is accelerating in Japan and South Korea where PMDA and MFDS fast-track designations reward reduced cryopreservation logistics and same-day administration protocols.
- TCR Therapy:T-cell receptor engineering targets intracellular tumor antigens through HLA-restricted recognition mechanisms.
- Stem Cell Therapy:Hematopoietic and pluripotent stem cell products span gene-corrected autologous grafts to universal donor cell banks.
CAR T-Cell Therapy holds the largest share; momentum sits with Natural Killer Cell Therapy.
End User:
Customer procurement sophistication determines contract structure complexity, with hospital systems negotiating bundled episode payments while pharmaceutical firms prioritize technology access fees and milestone-based partnerships.
- Hospitals:Academic medical centers and specialized cancer hospitals administer infused cell products through inpatient oncology units with ICU backup for cytokine release syndrome management. Demand concentrates in the United States, Germany, and Japan where CAR T-cell certification programs and FDA/EMA/PMDA treatment site approvals create concentrated access points.
- Pharmaceutical Firms:Large-cap sponsors acquire cell therapy platforms through asset purchases and platform licensing to fill pipeline gaps in hematologic malignancies. Investment is accelerating in Switzerland and the United Kingdom where Swissmedic and MHRA early access schemes reward novel manufacturing technologies.
- Biotech Companies:Venture-backed developers outsource GMP manufacturing to CDMO partners while retaining process development and analytical capabilities.
- Research Institutions:University-affiliated centers conduct investigator-initiated trials and preclinical proof-of-concept studies.
Hospitals dominate current volume; pharmaceutical firms are expanding most quickly through platform acquisitions.
Application:
Reimbursement pathway maturity separates segments, with oncology commanding established DRG and episode-based payment codes while autoimmune applications navigate experimental therapy designation complexities.
- Oncology:Hematologic malignancies—acute lymphoblastic leukemia, multiple myeloma, and non-Hodgkin lymphoma—represent the commercial core with established CMS and private payer coverage policies. Demand concentrates in the United States and Germany where FDA and EMA accelerated approvals have created precedent-based access.
- Autoimmune Disorders:CD19-directed CAR T-cells demonstrate durable B-cell depletion and clinical remission in systemic lupus erythematosus and systemic sclerosis. Clinical investment is accelerating in France and the Netherlands where ANSM and the Dutch Healthcare Institute support innovative therapy reimbursement pilots.
- Infectious Diseases:Engineered T-cells targeting HIV reservoir cells and hepatitis B surface antigen present curative intent approaches.
- Cardiovascular Diseases:Cardiac regeneration through cardiomyocyte replacement and vascular endothelial progenitor engineering remains preclinical.
Oncology commands revenue concentration; autoimmune disorders show the steepest expansion trajectory.
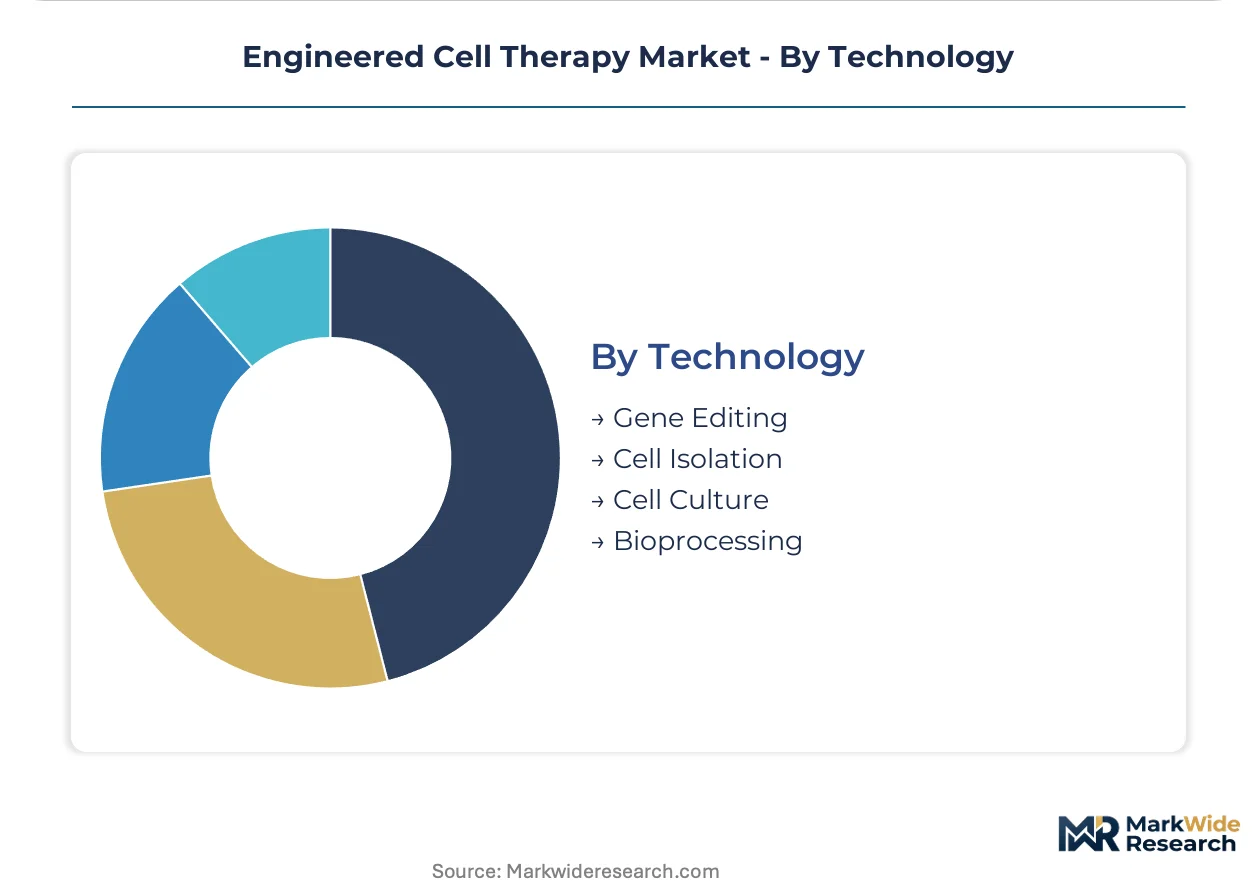
Technology:
Capital equipment requirements and technical talent scarcity create tiered competitive barriers, with gene editing platforms demanding specialized bioinformatics capabilities while bioprocessing scale-up requires hybrid engineering-biology skill sets.
- Gene Editing:CRISPR-Cas9, base editing, and prime editing systems enable precise genetic modifications without viral vector integration. Adoption is accelerating in the United States and China where FDA and NMPA guidance documents clarify off-target analysis requirements for investigational new drug submissions.
- Bioprocessing:Closed-system bioreactors, automated cell expansion platforms, and continuous manufacturing workflows compress production timelines from weeks to days. Investment concentrates in Germany and Singapore where EMA Annex 1 compliance and HSA regulatory alignment create GMP infrastructure hubs.
- Cell Isolation:CliniMACS and similar immunomagnetic separation systems enable GMP-compliant T-cell and NK-cell enrichment.
- Cell Culture:Serum-free media formulations and defined culture conditions support regulatory submission consistency.
Gene editing captures development-stage investment; bioprocessing is gaining share fastest through manufacturing efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where CMS reimbursement codes anchor premium capture, while German procurement through hospital networks enforces tighter cost discipline on manufacturers.
United States
FDA's RMAT designation compresses Phase 2-to-approval timelines for hematologic malignancy candidates, concentrating clinical trial investment in Boston and San Francisco where academic medical centers cluster CAR T-cell certification programs. The National Cancer Institute's manufacturing partnerships expand GMP capacity in Maryland and North Carolina.
Germany
EMA's PRIME scheme and Annex 1 GMP revisions drive Heidelberg and Munich treatment centers to consolidate specialized apheresis capacity. Hospital procurement committees unbundle CAR T-cell acquisition from inpatient packaging, forcing standalone pricing justification against salvage regimens.
Japan
PMDA's Sakigake designation offers priority review for gastric and pancreatic cancer candidates, opening Asia-Pacific oncology volume. Tokyo and Osaka academic centers anchor patient access infrastructure with MFDS-aligned GMP standards for regional export.
Switzerland
Swissmedic early access schemes reward novel manufacturing technologies, drawing platform licensing investment to Basel and Zurich. The country's pharmaceutical heritage supports CDMO partnerships that bridge EU and US regulatory requirements.
United Kingdom
MHRA's innovative licensing pathway accelerates cell therapy access post-Brexit, with London and Cambridge biotech clusters specializing in gene editing platforms. NHS England's Cancer Drugs Fund creates precedent-based reimbursement for hematologic indications.
Engineered Cell Therapy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in vector production and electroporation equipment. The market structures around three tiers: large-cap pharmaceutical sponsors with approved products, mid-stage biotech firms with clinical assets, and asset-light CDMOs providing manufacturing capacity. Consolidation pressure favors backward integration into plasmid and viral vector supply. Capacity expansion and strategic partnerships dominate competitive moves as firms secure GMP infrastructure ahead of regulatory submissions.
Within the large-cap integrator tier, Novartis AG and Bristol Myers Squibb Company exemplify platform breadth across hematologic and solid tumor pipelines. Legend Biotech Corporation occupies a position emphasizing manufacturing control. These three anchors represent distinct strategic postures: established commercial infrastructure, diversified indication coverage, and vertical manufacturing integration.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences, Inc. |
| Bristol Myers Squibb Company |
| Legend Biotech Corporation |
| CRISPR Therapeutics AG |
| Bluebird Bio Inc. |
| Allogene Therapeutics Inc. |
| Atara Biotherapeutics, Inc. |
| Johnson & Johnson Services, Inc. |
| Others |
Supply & Pricing Matrix
GMP-grade plasmid production clustering across three North American CDMOs concentrates upstream margin capture, forcing viral vector producers to absorb pass-through cost volatility or invest in captive supply infrastructure. This feedstock bottleneck compresses downstream pricing flexibility for autologous CAR T-cell manufacturers competing against allogeneic platforms with reduced patient-matching logistics.
Pricing Analysis
The customization-premium spread separates patient-matched autologous protocols from off-the-shelf allogeneic products, with the former commanding episode-based reimbursement bundles that include inpatient monitoring while the latter shift toward standalone product pricing. Price differentiation hinges on manufacturing modality complexity and FDA RMAT designation status, which accelerates market access timelines. Cost compression in autologous tiers is intensifying because hospital procurement committees unbundle cell acquisition from bed-day packaging. Academic medical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while pharmaceutical firms licensing platform technologies demonstrate lowest sensitivity to upfront access fees.
Supply Chain Analysis
Upstream feedstock for viral vector production draws from GMP plasmid banks concentrated in the United States, with lentiviral packaging cell lines sourced from specialized CDMOs in Germany and Switzerland. Electroporation equipment and mRNA reagents represent critical non-viral inputs, with manufacturing hardware anchored in Singapore and Japanese supply chains. Single-source vulnerability pervades plasmid supply tiers, creating regulatory submission delays if contamination events trigger batch disqualification. Distribution runs through cryogenic logistics networks terminating at hospital-based apheresis centers and centralized GMP facilities, with cold-chain integrity determining final product release windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Allogeneic manufacturing platforms threaten to displace autologous-dependent incumbents through compressed vein-to-vein timelines, forcing established players to defend substitution risk through supply chain restructuring or indication expansion into solid tumors.
For Market Incumbents: Build manufacturing moats through backward integration into plasmid and viral vector production, eliminating CDMO dependency that exposes margin erosion during supply crunches. Novartis AG demonstrates this posture through its Kymriah captive infrastructure. Anchor capacity expansion in Germany and Japan where EMA Annex 1 compliance and PMDA Sakigake designation create regulatory acceleration advantages. Diversify pipeline breadth across TCR and NK modalities to offset allogeneic durability uncertainty constraining payer willingness.
For New Entrants and Emerging Players: Mid-market autoimmune applications in France and the Netherlands represent the most penetrable entry point, where ANSM reimbursement pilots and Dutch Healthcare Institute innovative therapy frameworks bypass oncology pricing benchmarks. CD19-directed lupus and systemic sclerosis programs face reduced competitive density compared to saturated hematologic malignancy indications. Pursue asset-light CDMO partnerships rather than vertical infrastructure investment, preserving capital for clinical trial execution and regulatory submission preparation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CDMO platforms possessing GMP viral vector capacity and electroporation equipment fleets, positioned for consolidation as mid-stage biotech firms prioritize manufacturing outsourcing. Long-term viability centers on allogeneic durability data maturation and outpatient administration reimbursement precedent expansion. Watch FDA long-term follow-up guidance enforcement as the inflection signal determining registry infrastructure cost absorption capacity across sponsor portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive GMP capacity in Maryland and North Carolina anchors FDA RMAT-designated product supply security. |
| Regulatory Approval Pathway | EMA PRIME scheme compression accelerates Heidelberg and Munich treatment center activation timelines. |
| Pipeline Diversification | TCR and NK modality expansion offsets allogeneic durability uncertainty in solid tumor indications. |
| Licensing Agreement | Platform technology access fees with Swissmedic-aligned CDMOs bridge EU and US chemistry-manufacturing-controls requirements. |
| Clinical Trial Advancement | CD19-directed autoimmune protocols in France and the Netherlands establish precedent outside oncology reimbursement frameworks. |
Research Methodology
A spread of perspectives from cell therapy manufacturing executives, regulatory affairs leads at FDA and EMA, hospital formulary directors, and payer access specialists converged on the working assumptions shaping demand projections. Secondary validation drew from FDA RMAT designation filings, EMA PRIME scheme submissions, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up patient-flow modeling and top-down revenue triangulation anchored segmentation splits across product modalities and geographic regulatory clusters.
Demand-supply-balance framing structured the analytical approach, with patient eligibility flows, treatment center capacity constraints, and manufacturing batch release timelines modeled across the projection horizon. Segmentation dimensions spanned autologous versus allogeneic modality, hematologic versus solid tumor indication, and inpatient versus outpatient administration setting. CAGRs derived from iterative convergence between epidemiology-based demand ceilings and supply-side capacity buildout schedules, with electroporation equipment diffusion rates and allogeneic platform durability data serving as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in CMS reimbursement policy, EMA Annex 1 enforcement intensity, or Japanese PMDA Sakigake expansion scope would shift the trajectory. Cross-checking against real-world evidence registry data and hospital episode-based payment pilot outcomes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market