
 Global Duchenne Muscular Dystrophy Therapeutics Market | 2026-2036
Global Duchenne Muscular Dystrophy Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Duchenne Muscular Dystrophy Therapeutics Market Analysis
Synthetic oligonucleotide chemistry is hardening as the backbone of exon-skipping production economics, displacing earlier phosphorothioate formulations that carried higher synthesis costs and purification burdens. Sarepta Therapeutics dominates the exon-skipping segment with established intravenous delivery infrastructure. PTC Therapeutics leverages its European regulatory footprint to sustain access across EMA jurisdictions. BioMarin Pharmaceutical anchors gene therapy development through its manufacturing scale in viral vector production.
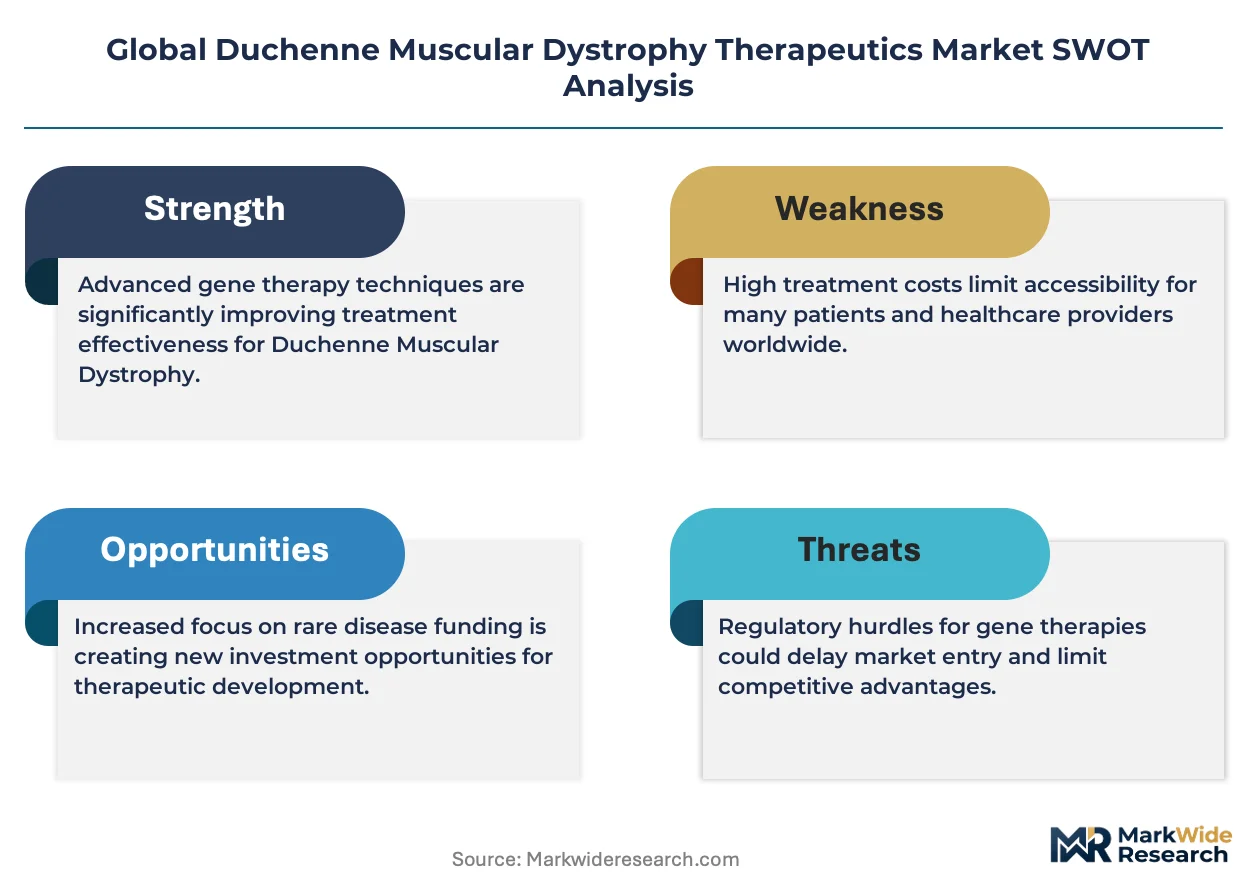
Duchenne muscular dystrophy therapeutics comprise pharmacological and biologic interventions designed to modify disease progression, restore dystrophin expression, or manage secondary complications in patients with mutations in the DMD gene; these treatments span small-molecule corticosteroids, antisense oligonucleotides for exon skipping, recombinant adeno-associated viral vectors for gene replacement, and oral utrophin modulators, with dosing regimens calibrated to patient weight and mutation amenable population. Corticosteroids occupy the largest volume share as the chronic standard-of-care backbone, though margin pools are thinning due to generic prednisone competition. Gene therapies represent the fastest-growing value segment, concentrated in advanced-stage patients eligible for single-administration protocols. Exon-skipping therapies differentiate through mutation-specific labeling, creating narrow but defensible therapeutic niches.
The FDA's accelerated approval pathway and orphan drug exclusivity framework shape development economics, compressing timelines for mutation-specific therapies while requiring confirmatory post-market trials. EMA's PRIME designation and European reference pricing systems govern reimbursement access across Germany, France, and Italy. Stakeholders must monitor FDA confirmatory trial outcomes and EMA health technology assessment decisions to calibrate portfolio prioritization between broad corticosteroid platforms and narrow mutation-addressable modalities.
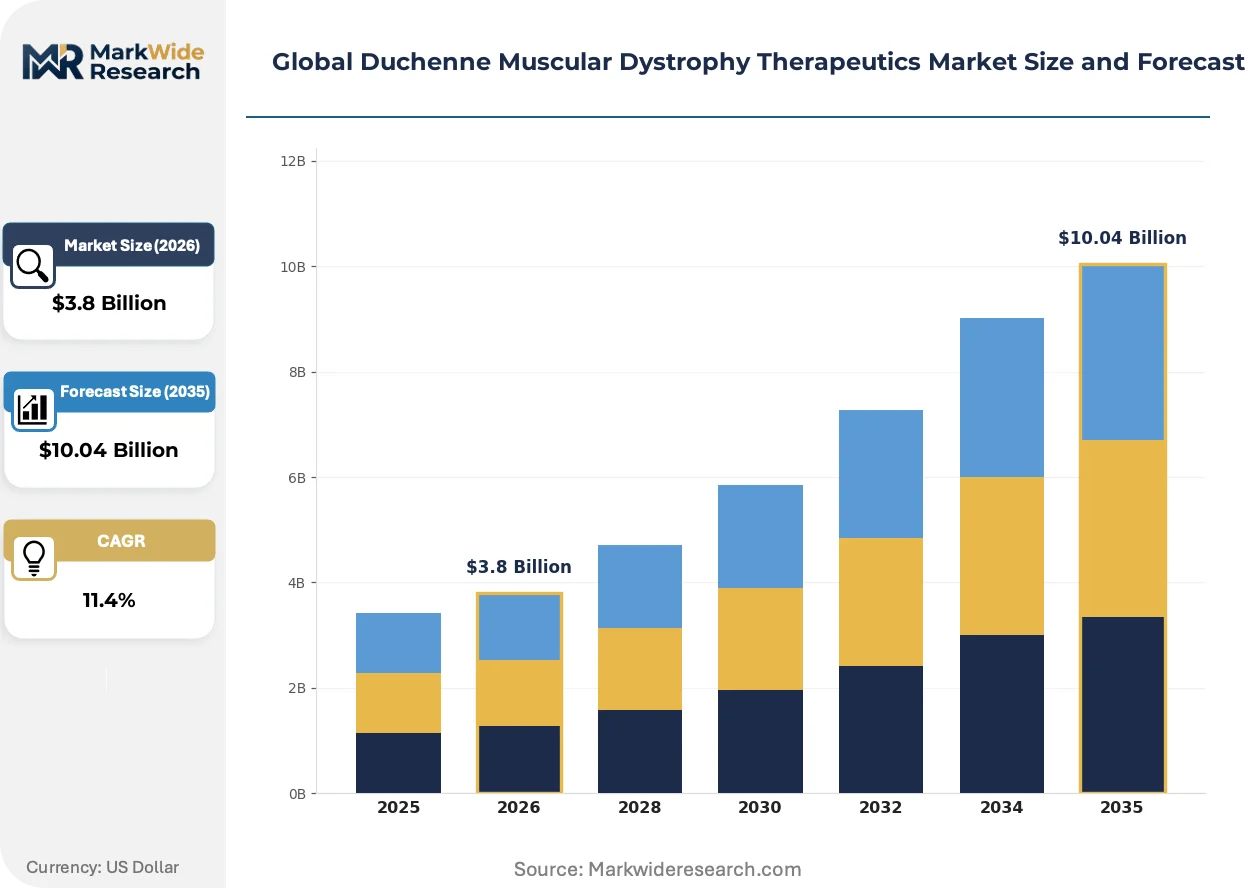
Market Dynamics
Synthetic oligonucleotide chemistry is hardening production economics for exon-skipping therapies, compressing manufacturing costs while FDA's accelerated approval pathway compresses commercialization timelines for mutation-specific modalities.
Growth Catalysts
- EMA's PRIME Designation:European regulators fast-track rare disease therapies, shortening assessment timelines for gene replacement candidates and expanding reimbursement access across Germany, France, and Italy.
- Specialty Clinic Networks:Pediatric neuromuscular centers in the United States are building intravenous delivery infrastructure for single-administration gene protocols, concentrating eligible patient identification.
- Synthetic Chemistry Advances:Next-generation phosphoramidite formulations are displacing phosphorothioate backbones, reducing synthesis cycle times and purification burdens for antisense oligonucleotide production.
Market Restraints
- Viral Vector Supply Concentration:Recombinant adeno-associated virus manufacturing capacity clusters at limited contract development sites, creating bottlenecks for gene therapy scale-up.
- Mutation-Specific Labeling:Narrow addressable populations per exon-skipping therapy fragment commercial viability and complicate payer negotiation leverage.
- Generic Corticosteroid Erosion:Prednisone commoditization is compressing margin pools for chronic standard-of-care maintenance, defunding R&D reinvestment from legacy platforms.
Strategic Opportunities
- Japan's Orphan Drug Framework:PMDA's Sakigake designation offers priority review and extended exclusivity for dystrophin-restoring modalities in an aging, affluent patient population.
- Utrophin Modulator Platforms:Oral small-molecule approaches targeting compensatory protein upregulation could address the 30% of patients with non-amenable mutations excluded from exon-skipping eligibility.
- Point-of-Care Genetic Testing:Rapid mutation sequencing in neuromuscular clinics is converging with therapy selection algorithms, enabling real-time protocol matching at treatment initiation.
Industry Challenges
- Confirmatory Trial Execution:FDA-mandated post-market studies for accelerated approvals require six-year dystrophin endpoint validation, stretching clinical infrastructure and patient retention.
- Cross-Border Reimbursement Fragmentation:European reference pricing systems generate divergent access thresholds between Germany's IQWiG assessments and Italy's AIFA negotiation frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Duchenne Muscular Dystrophy Therapeutics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Exon Skipping Therapies, Gene Therapies, Utrophin Modulators Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Stage of Disease: Early-Stage, Late-Stage, Advanced-Stage, Pre-Symptomatic |
| Companies Covered | Sarepta Therapeutics, PTC Therapeutics, Santhera Pharmaceuticals, Nippon Shinyaku, BioMarin Pharmaceutical, Italfarmaco, Capricor Therapeutics, FibroGen, Solid Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Duchenne Muscular Dystrophy Therapeutics Market Emerging Trajectories
Antisense chemistry, regulatory science, and patient identification infrastructure are converging to reshape how mutation-specific therapies reach addressable populations.
Next-generation tricyclo-DNA modifications are converging with peptide-conjugated delivery systems to improve muscle tissue penetration and reduce dosing frequency. Pediatric neuromuscular specialists in the United States are piloting these enhanced oligonucleotides in early-phase protocols. The structural consequence is a compression of the efficacy-toxicity tradeoff that has limited chronic exon-skipping adherence.
The FDA's confirmatory trial mandate for accelerated approvals is forcing sponsors to design six-year natural history comparisons with biomarker endpoints. This policy shift is extending development timelines and capital requirements for gene therapy candidates. Sponsors are responding by pre-positioning dystrophin quantification assays and patient registries prior to initial approval.
Integrated care networks are consolidating DMD patient management under single-center protocols that bundle genetic diagnosis, therapy selection, and long-term monitoring. This model displaces fragmented referral patterns between general pediatrics and subspecialty centers. The United Kingdom's NHS England has formalized this approach through designated highly specialized service contracts.
Global Duchenne Muscular Dystrophy Therapeutics Market Segmentation
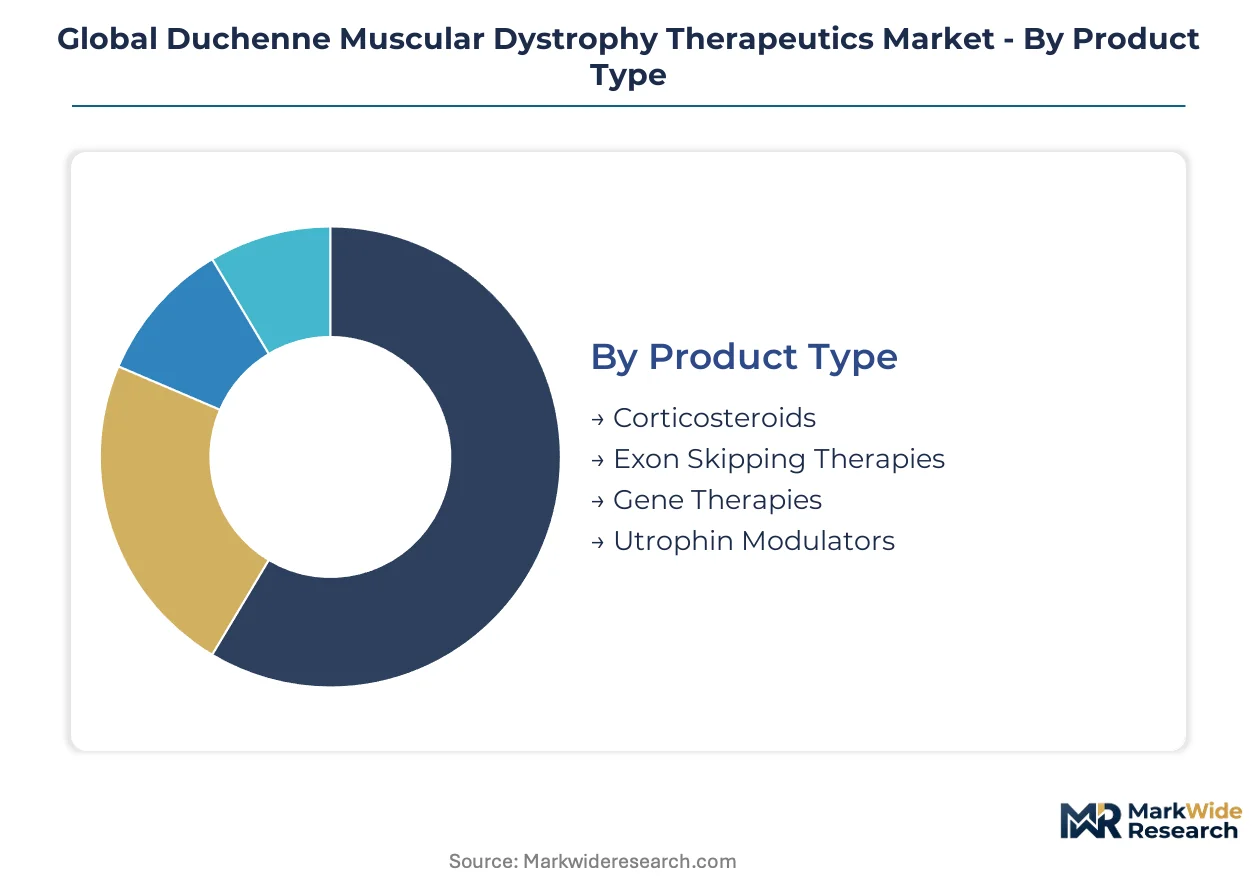
Duchenne muscular dystrophy therapeutics fragment across mutation-specific modalities, delivery infrastructure requirements, and disease progression windows. Each segmentation axis reveals distinct competitive dynamics and reimbursement pathways that shape portfolio allocation decisions.
Product Type:
Standalone pharmacological agents dominate chronic maintenance protocols, while biologic interventions require embedded delivery systems and specialized administration infrastructure.
- Corticosteroids:Chronic oral prednisone and deflazacort formulations constitute the foundational standard-of-care backbone. Demand concentrates in United States pediatric neurology practices where payer coverage for chronic maintenance has matured; generic prednisone commoditization is compressing margin pools and defunding R&D reinvestment.
- Gene Therapies:Recombinant adeno-associated viral vectors deliver micro-dystrophin constructs through single-administration protocols. United States specialty clinic networks are building intravenous delivery infrastructure for eligible advanced-stage patients; FDA's accelerated approval pathway compresses commercialization timelines while requiring six-year confirmatory trials.
- Exon Skipping Therapies:Antisense oligonucleotides restore reading frame through mutation-specific targeting.
- Utrophin Modulators:Oral small-molecule platforms upregulate compensatory protein expression for non-amenable mutations.
Volume placements concentrate in corticosteroids; the faster expansion belongs to gene therapies.
Delivery Mode:
Route of administration determines site-of-care requirements, patient adherence profiles, and manufacturing complexity tiers across the therapeutic portfolio.
- Intravenous:Infusion-dependent protocols for gene therapies and exon-skipping candidates require hospital-grade infrastructure. United States pediatric neuromuscular centers are consolidating eligible patient identification around intravenous-capable sites; viral vector supply concentration at limited contract manufacturing sites creates scale-up bottlenecks.
- Oral:Small-molecule corticosteroids and utrophin modulators enable chronic outpatient management. Dispensing concentrates in retail pharmacy networks across Germany and France where reference pricing systems govern reimbursement thresholds; generic competition erodes originator pricing power.
- Subcutaneous:Peptide-conjugated oligonucleotide formulations under early-phase investigation.
- Inhalation:Pulmonary-targeted delivery systems for respiratory muscle preservation in development.
Patient throughput concentrates in oral administration; capability investment is climbing fastest in intravenous infrastructure.
End User:
Care setting segmentation reflects the divergence between acute intervention protocols and chronic disease management models.
- Specialty Clinics:Dedicated pediatric neuromuscular centers bundle genetic diagnosis, therapy selection, and longitudinal monitoring. United States metropolitan clusters in Boston, Philadelphia, and Cincinnati anchor patient concentration; integrated care networks are displacing fragmented referral patterns between general pediatrics and subspecialty centers.
- Hospitals:Acute inpatient administration for gene therapy infusion and complication management. Tertiary centers in the United Kingdom's NHS England designated highly specialized service contracts capture complex case concentration; cross-border reimbursement fragmentation between Germany's IQWiG and Italy's AIFA generates divergent access thresholds.
- Homecare Settings:Chronic corticosteroid dispensing and patient monitoring protocols.
- Research Institutions:Early-phase clinical trial execution and natural history study enrollment.
Patient volume concentrates in specialty clinics; the steepest infrastructure expansion is occurring in hospital-based gene therapy suites.
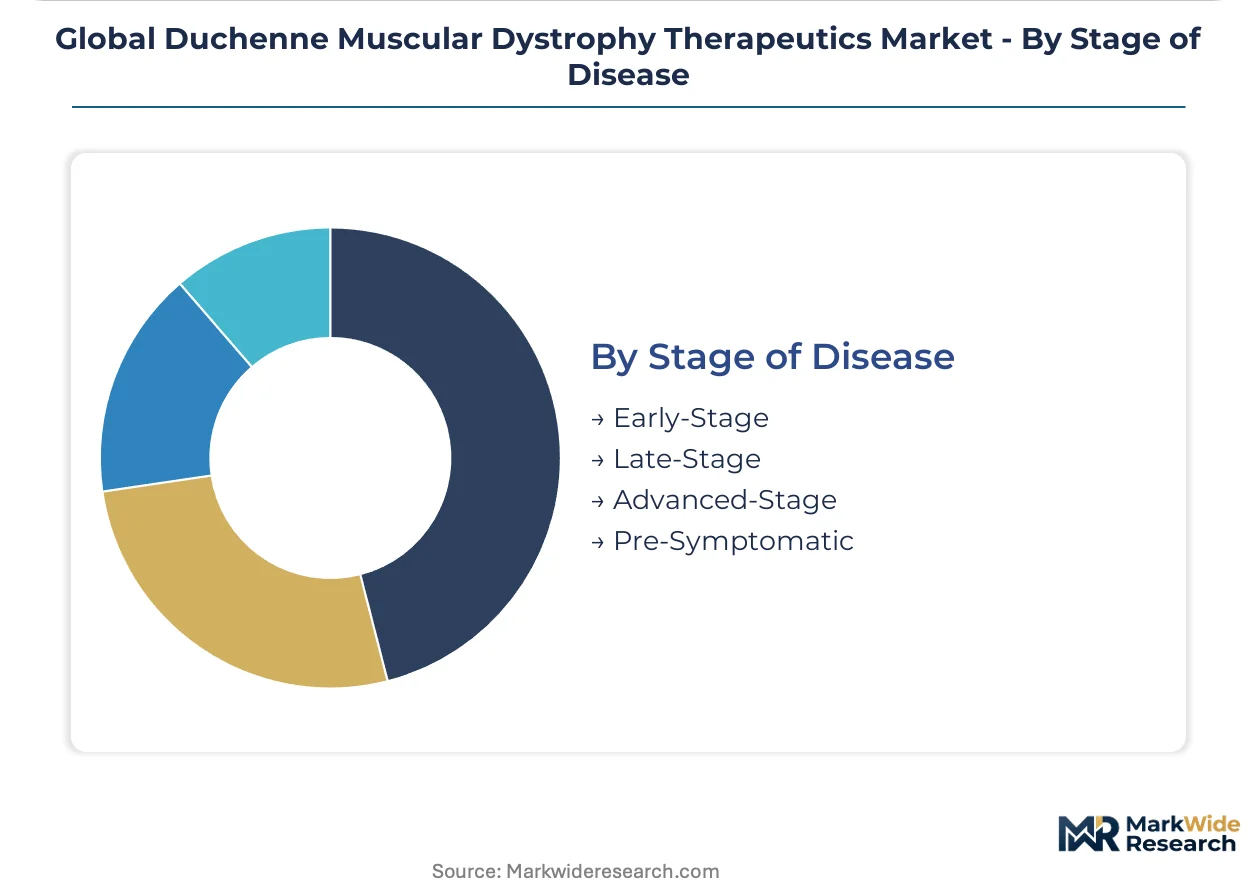
Stage of Disease:
Therapeutic eligibility windows align intervention timing with mechanism-of-action suitability and regulatory approval scope.
- Early-Stage:Ambulatory patients with preserved muscle function represent the target population for disease-modifying interventions. United States payer coverage for exon-skipping therapies has matured fastest in this segment; mutation-specific labeling fragments commercial viability per approved therapy.
- Late-Stage:Loss of ambulation triggers transition to respiratory and cardiac management protocols. EMA's PRIME designation fast-tracks gene replacement candidates for this population across Germany, France, and Italy; confirmatory trial execution stretches clinical infrastructure and patient retention.
- Advanced-Stage:Ventilator-dependent patients with limited therapeutic options.
- Pre-Symptomatic:Newborn screening expansion and familial cascade testing protocols.
Treatment initiations concentrate in early-stage; regulatory attention and pipeline investment are expanding most quickly in pre-symptomatic identification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and Kendall Square in Massachusetts concentrate gene therapy development through state-level tax incentives for rare disease R&D infrastructure.
United States
FDA's accelerated approval pathway compresses commercialization timelines for mutation-specific therapies. Payer coverage for exon-skipping and gene therapy protocols has matured fastest in Boston, Philadelphia, and Cincinnati pediatric neuromuscular centers. Specialty clinic networks in these metropolitan clusters are building intravenous delivery infrastructure for single-administration gene protocols.
Germany
EMA's PRIME designation fast-tracks gene replacement candidates through shortened assessment timelines. IQWiG health technology assessments govern reimbursement access thresholds for dystrophin-restoring modalities. Frankfurt and Munich anchor patient concentration within integrated care networks that bundle genetic diagnosis with longitudinal monitoring.
Japan
PMDA's Sakigake designation offers priority review and extended exclusivity for rare disease therapeutics. An aging, affluent patient population drives demand for advanced genetic interventions. Tokyo and Osaka metropolitan areas concentrate pediatric neuromuscular specialists piloting next-generation antisense chemistry protocols.
United Kingdom
NHS England designated highly specialized service contracts formalize single-center protocols for DMD patient management. These contracts displace fragmented referral patterns between general pediatrics and subspecialty centers. London and Greater Manchester capture complex case concentration through tertiary hospital-based gene therapy suites.
France
ANSM regulates accelerated access pathways for innovative rare disease treatments under early dialogue frameworks. Reference pricing systems generate specific access thresholds distinct from neighboring jurisdictions. Paris and Lyon metropolitan clusters concentrate clinical trial execution for natural history studies with six-year dystrophin endpoint validation.
Global Duchenne Muscular Dystrophy Therapeutics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with gene therapy developers controlling viral vector production while oligonucleotide chemistry houses supply antisense backbones. The market exhibits tiered concentration: mutation-specific exon-skipping therapies create narrow defensible niches, while corticosteroid platforms face generic commoditization. Three archetypes dominate: vertically integrated gene therapy sponsors, antisense chemistry specialists with European regulatory footprints, and oral small-molecule platforms targeting non-amenable mutations. Competitive moves center on manufacturing scale-up partnerships and confirmatory trial registry pre-positioning.
Within the gene therapy archetype, BioMarin Pharmaceutical anchors manufacturing scale in viral vector production. Sarepta Therapeutics and PTC Therapeutics occupy positions across the exon-skipping and gene replacement spectrum, representing the vertically integrated and European-regulatory-specialist archetypes respectively. These three companies exemplify how sponsors are responding to FDA's six-year confirmatory trial mandates through pre-positioned dystrophin quantification assays and patient registries prior to initial approval.
| Leading Market Players |
|---|
| Sarepta Therapeutics |
| PTC Therapeutics |
| Santhera Pharmaceuticals |
| Nippon Shinyaku |
| BioMarin Pharmaceutical |
| Italfarmaco |
| Capricor Therapeutics |
| FibroGen |
| Solid Biosciences |
| Others |
Supply Flow & Price Mechanics
Next-generation phosphoramidite chemistry is displacing phosphorothioate backbones across antisense oligonucleotide production, simultaneously compressing synthesis cycle times and concentrating manufacturing capability among specialized contract houses with captive purification infrastructure. This technological transition rewards sponsors with backward integration into oligonucleotide chemistry while fragmenting pricing power for legacy formulation suppliers.
Pricing Analysis
Volume placements concentrate in generic prednisone where margin pools have compressed to commodity levels; value capture belongs to mutation-specific exon-skipping therapies and single-administration gene protocols. Price differentiation rests on FDA's accelerated approval tier versus standard pathway timelines, with confirmatory trial requirements adding six-year cost burdens that sponsors pass through to United States payers. Pricing pressure stems from generic corticosteroid erosion defunding R&D reinvestment from chronic maintenance platforms. Hospital procurement committees exhibit highest price sensitivity for chronic oral therapies; gene therapy centers show lowest sensitivity given bundled reimbursement for single-administration protocols.
Supply Chain Analysis
Patient sample returns and biomaterial logistics for dystrophin quantification assays create reverse-flow complexity that few contract research organizations have optimized. Viral vector manufacturing concentrates in the United States, Germany, and Switzerland where GMP-grade facilities cluster around regulatory agency proximity. Recombinant adeno-associated virus production draws from plasmid DNA, HEK293 cell banks, and chromatography resin inputs. Single-source vulnerability at limited contract development sites creates scale-up bottlenecks for gene therapy candidates. Distribution runs through hospital-based specialty pharmacy networks rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's six-year confirmatory trial mandate for accelerated approvals erects a cost-of-compliance barrier that filters out undercapitalized developers while entrenching sponsors with pre-positioned patient registries and dystrophin quantification infrastructure.
For Market Incumbents: Lock in manufacturing scale partnerships with viral vector contract houses before capacity constraints harden. Secure exclusive access to pediatric neuromuscular center networks in Boston, Philadelphia, and Cincinnati where intravenous infrastructure investment is concentrating. Pre-position confirmatory trial registries to satisfy FDA's post-market study requirements without patient retention attrition.
For New Entrants and Emerging Players: Specialty clinic networks represent the most penetrable channel for utrophin modulator platforms targeting the 30% of patients excluded from exon-skipping eligibility. Japan's PMDA Sakigake designation offers faster regulatory timelines for dystrophin-restoring modalities in an aging, affluent population. Pursue point-of-care genetic testing partnerships to enable real-time mutation matching at treatment initiation.
For Investors and Strategic Acquirers: Exit pathways concentrate in gene therapy developers with validated viral vector manufacturing scale and confirmatory trial infrastructure already deployed. Long-term viability hinges on sponsors' ability to bridge six-year post-approval study execution without patient dropout. Monitor FDA confirmatory trial readouts as the critical inflection signal for portfolio revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Confirmatory Trial Registry Pre-Positioning | Sponsors deploying patient retention infrastructure before FDA approval compress post-market study risk. |
| Viral Vector Manufacturing Scale-Up | Backward integration into GMP-grade AAV production reduces dependence on limited contract sites. |
| Specialty Clinic Network Partnerships | Exclusive agreements with Boston and Cincinnati pediatric centers concentrate eligible patient identification. |
| Utrophin Modulator Pipeline Expansion | Oral small-molecule platforms address non-amenable mutations excluded from exon-skipping eligibility. |
| PMDA Sakigake Designation Pursuit | Japan's priority review pathway accelerates access in an aging, high-affinity patient population. |
Methodological Framework
FDA filings, ClinicalTrials.gov, and EMA submissions formed the secondary backbone for pipeline and regulatory tracking across mutation-specific therapies. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists validated commercial assumptions and reimbursement dynamics. Bottom-up patient population estimates by mutation amenable category were triangulated against top-down market value reconstructions from disclosed therapy pricing and treatment penetration rates.
Bottom-up modeling anchored patient-level assumptions across treatment line, administration route, and regional regulatory cluster dimensions before aggregation. Top-down cross-checks applied therapy-class growth patterns from historical analogs. CAGRs were derived from fitted adoption curves reflecting payer coverage maturation and confirmatory trial outcome probabilities. Forecast inputs incorporated viral vector manufacturing capacity expansion timelines and specialty clinic infrastructure buildout rates.
Several conditions sit outside the modeled scope, including pre-symptomatic newborn screening expansion timelines and cross-border reimbursement harmonization between Germany's IQWiG and Italy's AIFA. Forecasts reflect assumptions about confirmatory trial completion rates and patient retention through six-year study windows. Practitioners should monitor FDA advisory committee outcomes and EMA health technology assessment decisions for early signals of access threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market