
 Cell and Gene Therapy Manufacturing Market | 2026-2036
Cell and Gene Therapy Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Cell and Gene Therapy Manufacturing Market Intelligence
A scarcity of specialized talent in viral vector production and process development is redrawing the competitive landscape. Large contract manufacturers like Lonza leverage scale and established GMP expertise to attract partnerships. Catalent Inc. focuses on providing integrated development and manufacturing services. Meanwhile, biopharma giants such as Novartis AG sustain in-house capabilities to control their supply chains for flagship therapies.
Cell and gene therapy manufacturing encompasses the production of therapeutic agents through the genetic modification of cells. These processes require stringent aseptic controls and often utilize closed, automated systems to ensure product safety and efficacy. Viral vectors currently dominate the product type segment as the primary delivery mechanism. Within applications, oncology therapy holds the largest share, while contract manufacturing organizations represent a major end-user category due to high capital investment requirements.
Regulatory oversight from bodies like the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) is stringent. These agencies establish Good Manufacturing Practice (GMP) guidelines that dictate facility design, process validation, and quality control. Navigating the distinct requirements of different national regulators, including China's NMPA, remains a critical challenge for market access. Future success hinges on the ability to scale manufacturing processes while maintaining compliance with evolving standards.
Market Dynamics
The central structural force shaping the market is the drive for industrialization. This involves a fundamental shift from bespoke, manual laboratory processes to scalable, automated, and standardized manufacturing platforms capable of meeting commercial demand and stringent regulatory expectations for product consistency.
Growth Catalysts
- Advancing Gene-Editing Tools:Innovations in CRISPR-Cas9 and other gene-editing technologies are dramatically shortening the discovery and preclinical development timelines for new cell and gene therapies, expanding the pipeline of products requiring manufacturing services.
- Favorable Regulatory Pathways:The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation and the EMA's Priority Medicines (PRIME) scheme provide accelerated approval routes, incentivizing investment in manufacturing capacity to support rapid clinical progression.
- Expanding Therapeutic Pipeline:A growing number of therapies progressing through clinical trials for oncology, rare genetic disorders, and other indications creates a direct and sustained demand for specialized GMP manufacturing capabilities and viral vector supply.
Market Restraints
- High Production Costs:The cost of producing clinical-grade viral vectors, particularly lentivirus and adeno-associated virus (AAV), remains a significant financial barrier, limiting the commercial viability of some therapies and constraining development budgets.
- Scalability of Autologous Therapies:The patient-specific, "scale-out" nature of autologous cell therapy manufacturing presents immense logistical and cost challenges compared to the more conventional "scale-up" model for allogeneic or traditional biologic drugs.
- Regulatory Divergence:Navigating disparate GMP guidelines and data requirements from the FDA, EMA, and China's NMPA complicates global clinical trial supply and commercial launch strategies, adding time and cost to market access.
Strategic Opportunities
- Non-Viral Delivery Systems:Development of alternative delivery methods, such as lipid nanoparticles (LNPs) or electroporation, offers an opportunity to bypass the bottlenecks and high costs associated with viral vector manufacturing, potentially disrupting the current supply chain.
- Asia-Pacific Biotech Expansion:Governments in countries like South Korea and Singapore are making substantial investments in biotechnology infrastructure, creating underpenetrated markets for advanced CDMO services and technology licensing for cell and gene therapy production.
- Expansion into Chronic Diseases:Applying cell and gene therapy platforms beyond oncology and rare monogenic diseases to more prevalent chronic conditions, such as cardiovascular or autoimmune disorders, represents a vast, largely untapped commercial opportunity.
Industry Challenges
- Specialized Talent Shortage:A critical scarcity of scientists and technicians with hands-on experience in process development, analytics, and GMP-compliant manufacturing for cell therapies and viral vectors constrains operational capacity across the industry.
- High Capital Expenditure:The construction and validation of facilities compliant with GMP standards, including sophisticated cleanrooms and quality control labs, require substantial upfront capital investment, creating a high barrier to entry.
- Lack of Potency Assay Standardization:Developing reliable, standardized potency assays that are accepted by regulators globally remains a major technical hurdle, complicating comparability studies and the validation of manufacturing processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell and Gene Therapy Manufacturing Market |
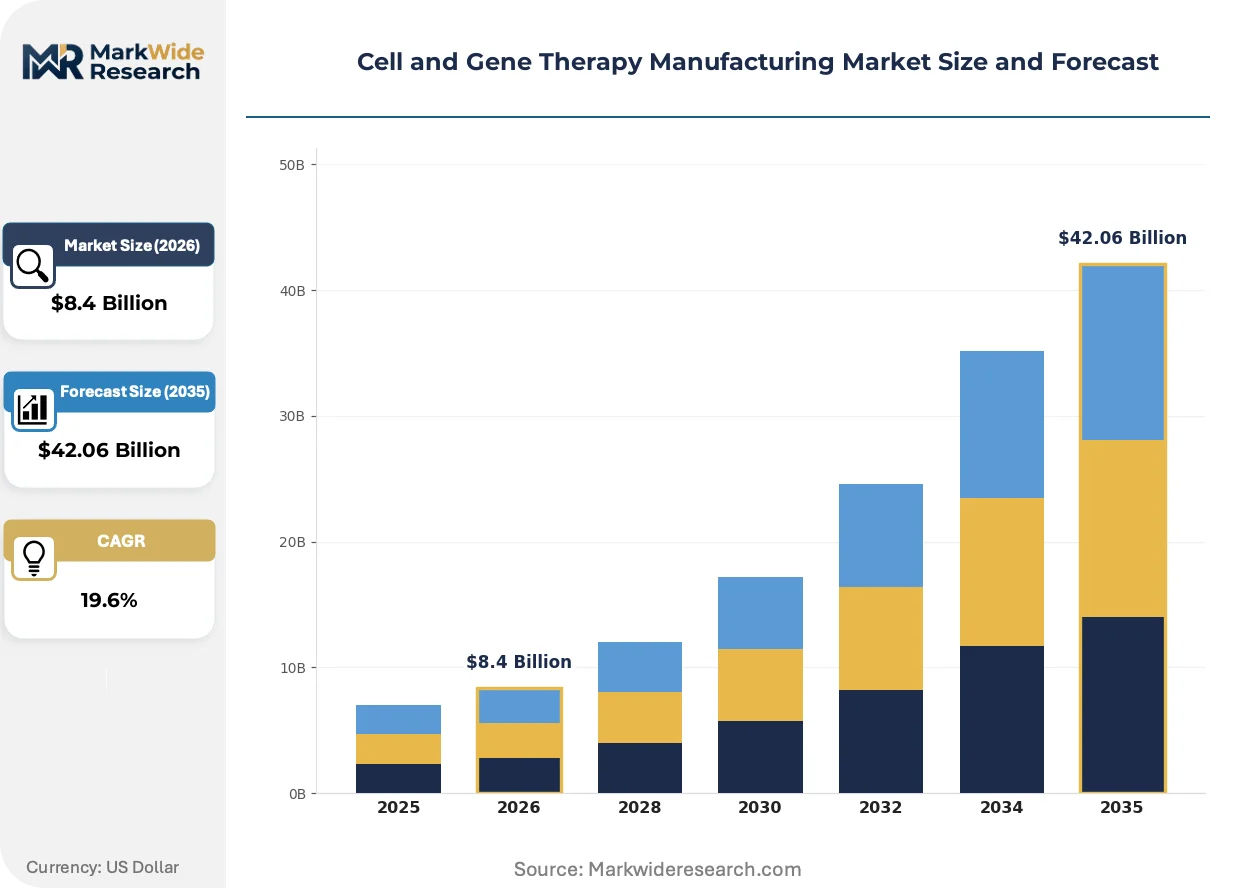
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $42.06 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viral Vectors, Plasmids, Cell Banks, Culture Media, Enzymes Technology: CRISPR, TALEN, ZFN, Lentiviral Transduction, mRNA Transfection Application: Oncology Therapy, Genetic Disorders, Immunodeficiency Treatment, Regenerative Medicine, Rare Diseases End User: Biotech Firms, Contract Manufacturing Organizations, Research Institutes, Clinical Laboratories |
| Companies Covered | Samsung Biologics, Novartis AG, Lonza, Miltenyi Biotec, Wuxi Advanced Therapies, Catalent Inc., Boehringer Ingelheim, Fujifilm Diosynth Biotechnologies, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell and Gene Therapy Manufacturing Market Strategic Shifts & Innovations
A transition toward industrial-scale production is defining the market's evolution. This movement prioritizes automation, closed-system processing, and data integration to improve consistency, reduce contamination risks, and manage the complex logistics inherent in these personalized treatments.
Closed, automated manufacturing platforms are gaining significant traction for their role in minimizing manual interventions. These integrated systems, combining bioreactors, cell-wash units, and fill-finish capabilities, ensure process sterility and reproducibility. Biopharma companies and their CDMO partners are rapidly implementing these technologies for both clinical-stage and commercial-scale production. This automation is bifurcating the manufacturing landscape between flexible, open systems for early research and standardized, closed platforms for late-stage development and commercial supply.
Regulatory frameworks are adapting specifically to these advanced products, exemplified by the EMA's updated Good Manufacturing Practice guidelines for Advanced Therapy Medicinal Products (ATMPs). This guidance imposes stricter requirements for process validation, raw material control, and demonstrating comparability after any manufacturing changes. Developers of allogeneic "off-the-shelf" therapies are most impacted, as they must prove robust batch-to-batch consistency to regulators across large-scale production campaigns.
Partnership models between therapy developers and manufacturers are evolving from transactional contracts to integrated, long-term collaborations. This trend is disrupting the conventional fee-for-service CDMO engagement, with dedicated production suites or reserved capacity agreements becoming more common. This strategic shift is most prominent in the United States and key European biotech hubs, where capital-constrained innovators seek to secure their supply chain and transfer manufacturing risk to specialized partners.
Cell and Gene Therapy Manufacturing Market Segmentation
The Cell and Gene Therapy Manufacturing Market requires precise segmentation to understand the diverse components, technologies, and end-user demands shaping its evolution. This granular analysis helps stakeholders identify areas of concentrated investment and emerging opportunities across the complex value chain.
Product Type:
The product type segmentation reveals a clear distinction between domestically produced components and those frequently sourced from specialized international suppliers.
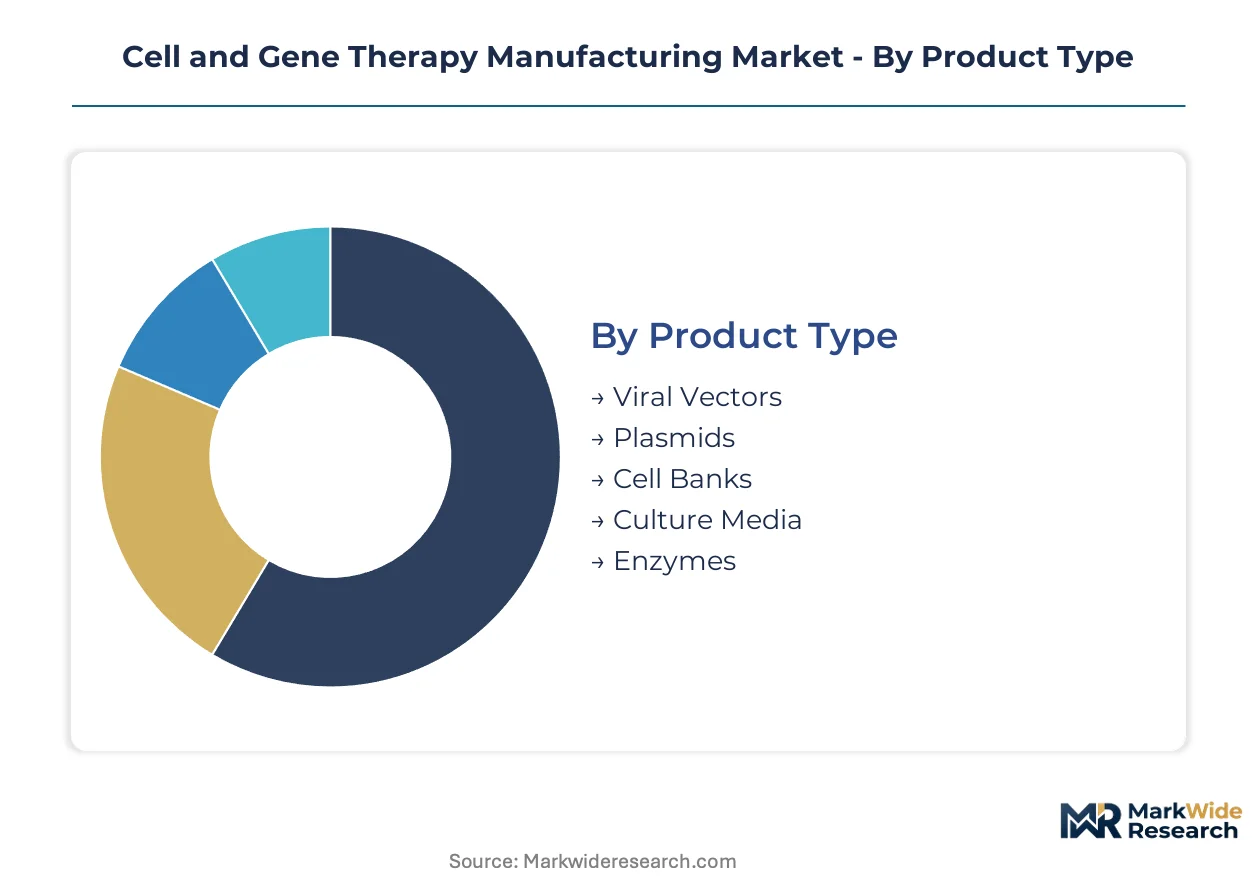
- Viral Vectors:These biological delivery vehicles, primarily AAV and lentivirus, introduce genetic material into target cells. Demand for clinical-grade viral vectors is concentrating in the United States and key European biotech hubs due to their critical role in gene therapy development.
- Plasmids:Circular DNA molecules serve as essential raw materials for viral vector production and mRNA vaccine manufacturing. Their production requires specialized fermentation and purification, with significant demand originating from biopharma companies in Germany and Switzerland.
- Cell Banks:These cryopreserved master and working cell lines ensure consistent starting material for cell therapy production. Maintaining robust cell banks is crucial for process validation and regulatory compliance across clinical trials.
- Culture Media:Specialized formulations provide the necessary nutrients and growth factors for cell expansion and viral vector production. These media are vital for optimizing yield and quality in manufacturing processes.
- Enzymes:Various enzymes are integral for genetic manipulation, DNA synthesis, and cell processing steps within the therapy manufacturing workflow. These reagents enable precise molecular interventions.
Viral Vectors commands the established base. The steepest expansion runs through Plasmids.
Technology:
Technology segments reflect varying levels of maturity and associated development costs, influencing their commercial adoption.
- CRISPR:This gene-editing tool offers precise genetic modification capabilities, accelerating research and therapeutic development timelines. Its innovation is driving new therapy development, particularly within academic institutions and early-stage biotech firms in the United States.
- TALEN:Transcription Activator-Like Effector Nucleases provide another platform for targeted gene editing, offering high specificity for certain applications. This technology finds application in ex vivo cell therapy manufacturing.
- ZFN:Zinc Finger Nucleases represent an earlier generation of gene-editing technology, still utilized for specific research and therapeutic indications. These tools offer established production routes for genetic modification.
- Lentiviral Transduction:This method uses lentiviruses to efficiently deliver genes into target cells, widely employed in CAR-T cell therapies. Its established use ensures broad application in commercial manufacturing.
- mRNA Transfection:Non-viral delivery of messenger RNA into cells facilitates transient protein expression, bypassing viral vector complexities. This approach is gaining traction for vaccine development and transient gene therapies.
Innovation in CRISPR drives new therapy development, while Lentiviral Transduction platforms offer established production routes.
Application:
Application segments highlight diverse patient populations and therapeutic areas, each requiring tailored manufacturing approaches.
- Oncology Therapy:This segment encompasses cell and gene therapies targeting various cancers, including CAR-T and oncolytic viruses. Demand for oncology therapies dominates current manufacturing capacity, particularly in the United States and European markets.
- Genetic Disorders:Therapies addressing inherited genetic conditions, such as cystic fibrosis or sickle cell disease, fall under this category. These therapies require highly specialized manufacturing processes due to their rare disease indications.
- Immunodeficiency Treatment:Gene therapies designed to correct primary immunodeficiencies represent a critical application area. Manufacturing for these treatments often involves ex vivo modification of patient cells.
- Regenerative Medicine:This broad application focuses on repairing or replacing damaged tissues and organs using cell-based products. This area represents a rapidly expanding area of clinical focus.
- Rare Diseases:Cell and gene therapies often provide the only treatment option for ultra-rare genetic conditions. Manufacturing for these indications benefits from accelerated regulatory pathways like RMAT.
Demand for Oncology Therapy dominates current manufacturing capacity, but Regenerative Medicine represents a rapidly expanding area of clinical focus.
End User:
End-user categories delineate the primary consumers of cell and gene therapy manufacturing services, with distinct operational models and strategic priorities.
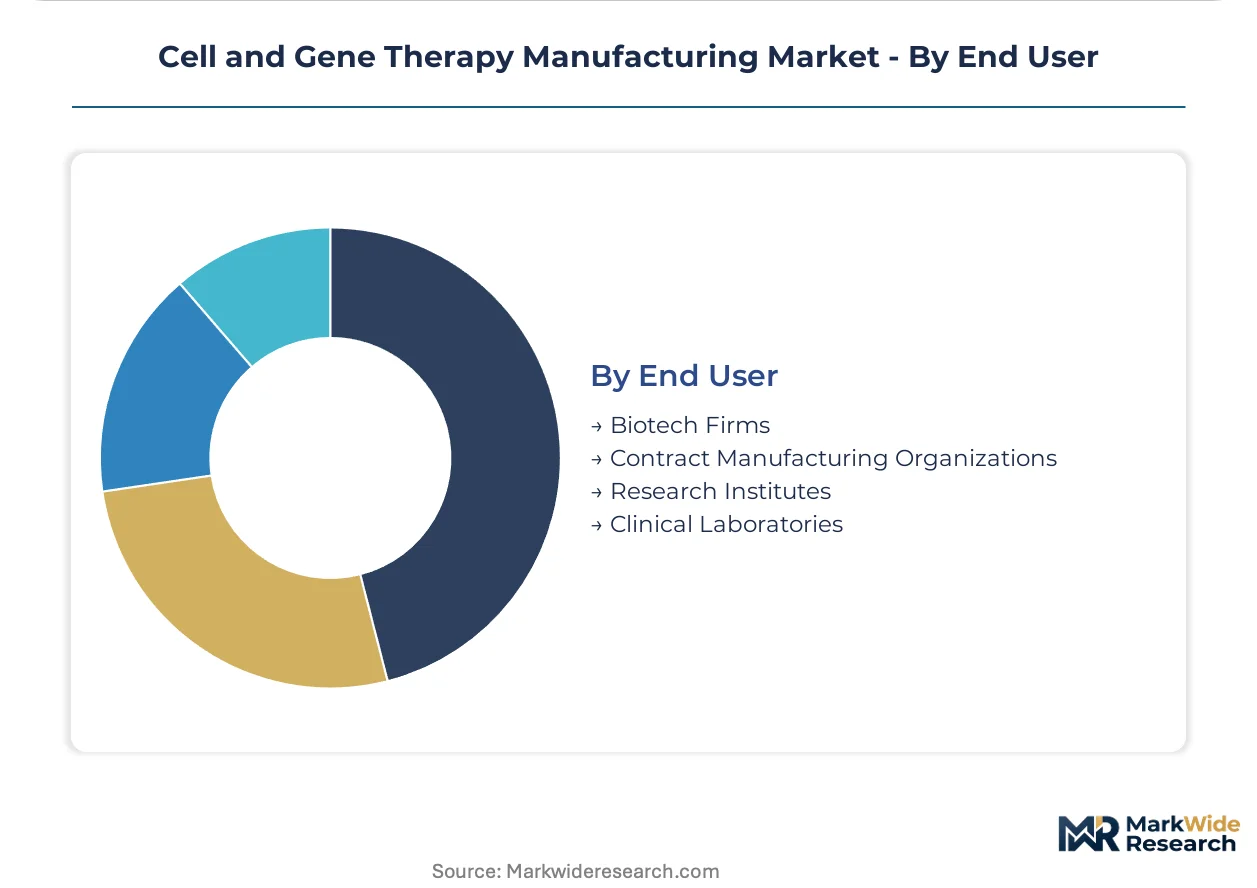
- Biotech Firms:These companies develop novel cell and gene therapies, often outsourcing manufacturing due to high capital expenditure. These firms focus on discovery and early-stage process development.
- Contract Manufacturing Organizations:CMOs provide specialized manufacturing services, leveraging scale and GMP expertise for therapy developers. Large-scale manufacturing capacity primarily resides with these organizations.
- Research Institutes:Academic and non-profit research centers conduct early-stage discovery and preclinical development of new therapies. These institutes often require flexible, small-batch manufacturing capabilities.
- Clinical Laboratories:These facilities perform diagnostic testing and often handle patient-specific cell processing for autologous therapies. They play a crucial role in the logistical chain for personalized treatments.
Contract Manufacturing Organizations handle the bulk of commercial production. Biotech Firms are driving the pipeline of new therapies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for advanced cell and gene therapy manufacturing concentrates in the United States, driven by high demand and specialized expertise. Regions like China are rapidly developing capacity, potentially altering future cost structures and offering alternative supply options.
United States
Demand for CAR-T therapies and viral vectors remains consistently high, reflecting a robust clinical pipeline. The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation accelerates clinical development and incentivizes investment. Biotech clusters in Boston, San Francisco, and Research Triangle Park drive innovation and manufacturing partnerships.
Germany
Strong demand for plasmid DNA and viral vector production fuels the market, especially for allogeneic therapies. EMA guidelines for Advanced Therapy Medicinal Products (ATMPs) ensure stringent quality control and process validation. Munich, Berlin, and the Rhine-Main region are significant hubs for biopharmaceutical research and contract manufacturing.
China
Expanding therapeutic pipelines create significant demand for localized manufacturing capacity and technology transfer. The NMPA is streamlining approval processes for advanced therapies, encouraging domestic production. Shanghai and Suzhou are emerging as major centers for cell and gene therapy production, attracting substantial investment.
Japan
Oncology therapy development and regenerative medicine applications drive manufacturing needs, particularly for ex vivo cell processing. The PMDA offers accelerated review pathways for innovative treatments, fostering a competitive environment. Tokyo and Osaka host specialized facilities for cell processing and viral vector supply, supporting clinical trials.
South Korea
Government investment in biotech infrastructure fuels demand for advanced CDMO services and technology licensing. MFDS regulations are adapting to support advanced biopharmaceutical manufacturing, aiming for global competitiveness. Seoul and Incheon are developing as key bio-manufacturing hubs, attracting foreign partnerships and expertise.
Cell and Gene Therapy Manufacturing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within cell and gene therapy manufacturing, creating a diverse competitive landscape. The market exhibits a tiered structure, with large contract manufacturers offering significant scale alongside specialized biopharma firms maintaining critical in-house capabilities. Strategic archetypes include integrated CDMOs providing end-to-end services, niche technology providers focusing on specific components like viral vectors, and therapy developers with captive production. Dominant competitive moves involve significant capacity expansion, strategic partnerships to secure supply chains, and continuous investment in process automation.
Large contract manufacturing organizations, such as Lonza and Catalent Inc., exemplify the integrated CDMO archetype, providing extensive development and manufacturing services across the value chain. These organizations leverage established GMP expertise and significant capital investment to attract partnerships and handle commercial-scale production for numerous clients. Conversely, biopharma giants like Novartis AG often sustain robust in-house capabilities, representing therapy developers focused on controlling their supply chains for flagship therapies and maintaining proprietary process knowledge. This dual approach highlights the industry's need for both outsourced scale and specialized internal control.
| Leading Market Players |
|---|
| Samsung Biologics |
| Novartis AG |
| Lonza |
| Miltenyi Biotec |
| Wuxi Advanced Therapies |
| Catalent Inc. |
| Boehringer Ingelheim |
| Fujifilm Diosynth Biotechnologies |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Good Manufacturing Practice (GMP) guidelines gate both supply qualification and price differentiation in cell and gene therapy manufacturing. These stringent standards necessitate significant investment, directly impacting service costs and market access.
Pricing Analysis
Pricing power for advanced cell and gene therapy manufacturing concentrates in the United States, reflecting high demand and specialized expertise. The dominant pricing model is project-based, often transitioning to long-term contract-based offtake agreements for commercial supply. Price differentiation stems from stringent GMP compliance and the high customization required for autologous therapies. Cost compression in viral vector production is intensifying due to the capital-intensive nature of these processes, making early-stage biotech firms particularly price-sensitive.
Supply Chain Analysis
The inbound logistics cost for critical raw materials, particularly specialized viral vector components, significantly impacts the supply chain for cell and gene therapies. Supply concentration for viral vectors centers in the United States and key European biotech hubs, while plasmid production relies on Germany and Switzerland. The supply chain relies heavily on clinical-grade viral vectors and plasmids. Single-source vulnerability for specialized reagents presents a structural risk, and distribution runs through direct-to-client models and complex cold chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell and gene therapy manufacturing market presents a significant service-attach opportunity. Specialized GMP manufacturing capacity and process development services are expanding faster than the underlying therapeutic pipeline, creating recurring revenue streams.
For Market Incumbents: Secure specialized talent and advanced manufacturing capacity to defend market share against emerging CDMOs. Incumbents like Lonza should prioritize capacity addition in key European biotech hubs and the United States. Investing in process automation can mitigate the critical specialized talent shortage. Strategic partnerships with therapy developers also transfer manufacturing risk and ensure long-term supply agreements.
For New Entrants and Emerging Players: Differentiate on novel technology platforms, such as non-viral delivery systems, to bypass existing bottlenecks. New entrants should target underpenetrated markets for advanced CDMO services, particularly within Asia-Pacific biotech expansion zones like South Korea. A key go-to-market angle involves technology licensing for localized production. Focusing on niche applications or specific process steps can carve out a defensible position.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across viral vector manufacturing and advanced automation platforms, signaling long-term market viability. Investors should target niche technology providers or specialized CDMOs with established GMP expertise and scalable closed systems. The market exhibits strong growth potential over the next decade. A critical signal to watch is the continued regulatory adaptation for allogeneic "off-the-shelf" therapies, which will unlock broader commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Significant capacity addition in the United States and European biotech hubs addresses demand for manufacturing services. |
| Process Automation Investment | Investment in automated, closed-system processing reduces contamination risks and improves product consistency for allogeneic therapies. |
| Strategic Partnerships | Long-term collaborations with therapy developers secure supply chains and transfer manufacturing risk to specialized partners. |
| Technology Licensing | Licensing non-viral delivery systems offers an opportunity to bypass viral vector bottlenecks and high production costs. |
| Talent Development Programs | Initiatives to address the specialized talent shortage in viral vector production enhance operational capacity across the industry. |
Research Approach
Initial hypotheses were tested against primary input from therapy development executives, CDMO operations leads, and regulatory affairs specialists, then refined. This involved combining insights from in-depth interviews with extensive secondary validation. Secondary data sources included FDA filings, EMA submissions, clinical trial databases, and company 10-K filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
Variance decomposition identified key drivers and restraints influencing market trajectory across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were calculated from historical trends and projected growth drivers. Industry-specific forecast inputs included clinical trial progression rates and viral vector supply capacity evolution.
Material uncertainties — unforeseen regulatory shifts, breakthrough technological disruptions, or significant changes in capital investment — sit outside the modeled envelope. Forecasts reflect assumptions regarding current market dynamics and known pipeline developments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market