
 Cellular Immunotherapy Market | 2026-2036
Cellular Immunotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Immunotherapy Market Intelligence
Lentiviral vectors are displacing gamma-retroviral systems in CAR-T manufacturing, a material-substitution event that is realigning cost structures across the industry. Novartis AG leverages its vertically integrated vector production platform to sustain supply security for Kymriah. Gilead Sciences Inc. anchors its position through dedicated cell therapy manufacturing campuses in California and the Netherlands. Bristol-Myers Squibb Company differentiates via dual-platform investments spanning both autologous and allogeneic modalities.
Cellular immunotherapy constitutes the therapeutic use of living immune cells—typically T lymphocytes, natural killer cells, or hematopoietic stem cells—that are ex vivo modified, expanded, and reinfused to target malignant or dysregulated tissue, with cryopreservation specifications requiring viable cell recovery rates above 80% post-thaw. CAR-T Therapy occupies the dominant revenue position due to established reimbursement codes for hematologic malignancies, while NK Cell Therapy represents the fastest-expanding segment as off-the-shelf manufacturing protocols reduce patient-matching constraints. Oncology commands the largest application share, though Autoimmune Disorders is emerging as a high-margin expansion vector for pipeline assets.
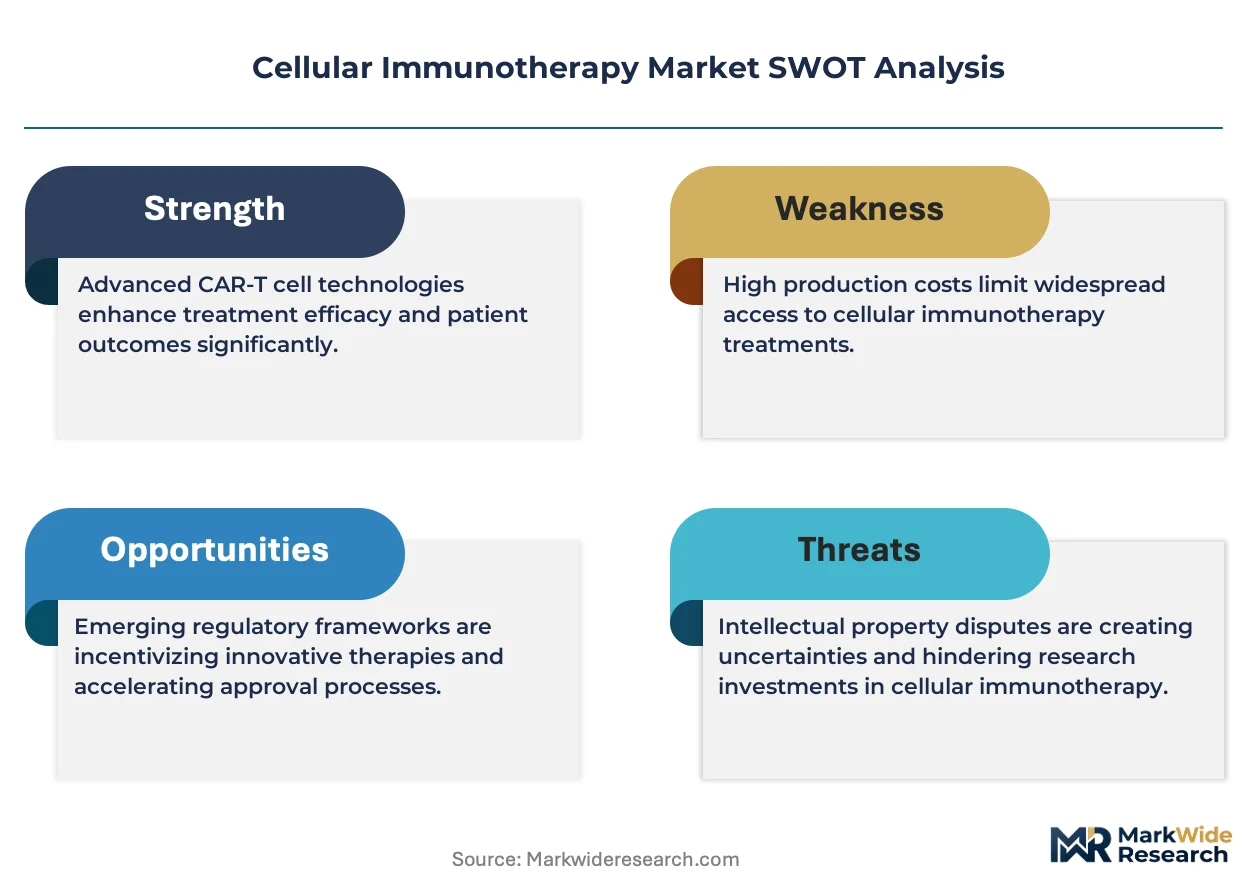
The FDA's regenerative medicine advanced therapy designation and the EMA's priority medicines scheme together compress clinical development timelines and shape competitive market access trajectories across North America and Europe. HIPAA compliance requirements and EU GDPR provisions on genetic data processing impose additional operational costs on multi-site clinical trial networks. Stakeholders must weigh manufacturing scale commitments against evolving payer evidence requirements for durable response endpoints.
Market Dynamics
The transition from gamma-retroviral to lentiviral vector systems is compressing manufacturing timelines and redistributing competitive advantage toward vertically integrated producers with captive plasmid supply chains.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy Designation:The accelerated approval pathway shortens clinical development cycles for qualifying cell therapies, reducing time-to-market for novel constructs.
- Autologous CAR-T reimbursement expansion:Medicare coverage for inpatient administration has normalized payment flows at academic medical centers across the United States, anchoring demand concentration.
- Allogeneic manufacturing scale-up:Off-the-shelf protocols using donor-derived cells are eliminating patient-matching bottlenecks and unlocking treatment access in community oncology settings.
Market Restraints
- Plasmid DNA supply concentration:Manufacturing-grade plasmid production clusters among a limited set of contract manufacturers, creating input vulnerability for vector producers.
- Cryopreservation technical ceiling:Current dimethyl sulfoxide-based protocols impose viable cell recovery thresholds that constrain logistics flexibility and cold-chain economics.
- EMA Advanced Therapy Medicinal Products complexity:The centralized marketing authorization procedure imposes extended regulatory timelines and higher compliance costs for European market entry compared to the FDA pathway.
Strategic Opportunities
- Autoimmune disorder pipeline expansion:Systemic lupus erythematosus and multiple sclerosis applications represent high-margin white space beyond oncology, with earlier-stage assets targeting B-cell depletion mechanisms.
- India CDSCO regulatory harmonization:The country's emerging cell therapy guidelines and PLI scheme incentives are attracting manufacturing investment for Asia-Pacific supply positioning.
- Natural killer cell allogeneic convergence:The combination of feeder-free expansion protocols and CRISPR-mediated knockout engineering is enabling durable off-the-shelf NK products.
Industry Challenges
- Vector bioprocess engineer scarcity:The specialized skill set spanning viral production, cell culture, and quality analytics commands premium compensation and constrains site expansion velocity.
- Multi-site HIPAA-GDPR compliance:International clinical trial networks face operational friction from divergent genetic data protection requirements across United States and European jurisdictions.
- Legacy electronic health record integration:Cell therapy orchestration platforms require real-time data exchange with hospital systems that lack standardized APIs for infusion scheduling and adverse event reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Immunotherapy Market |
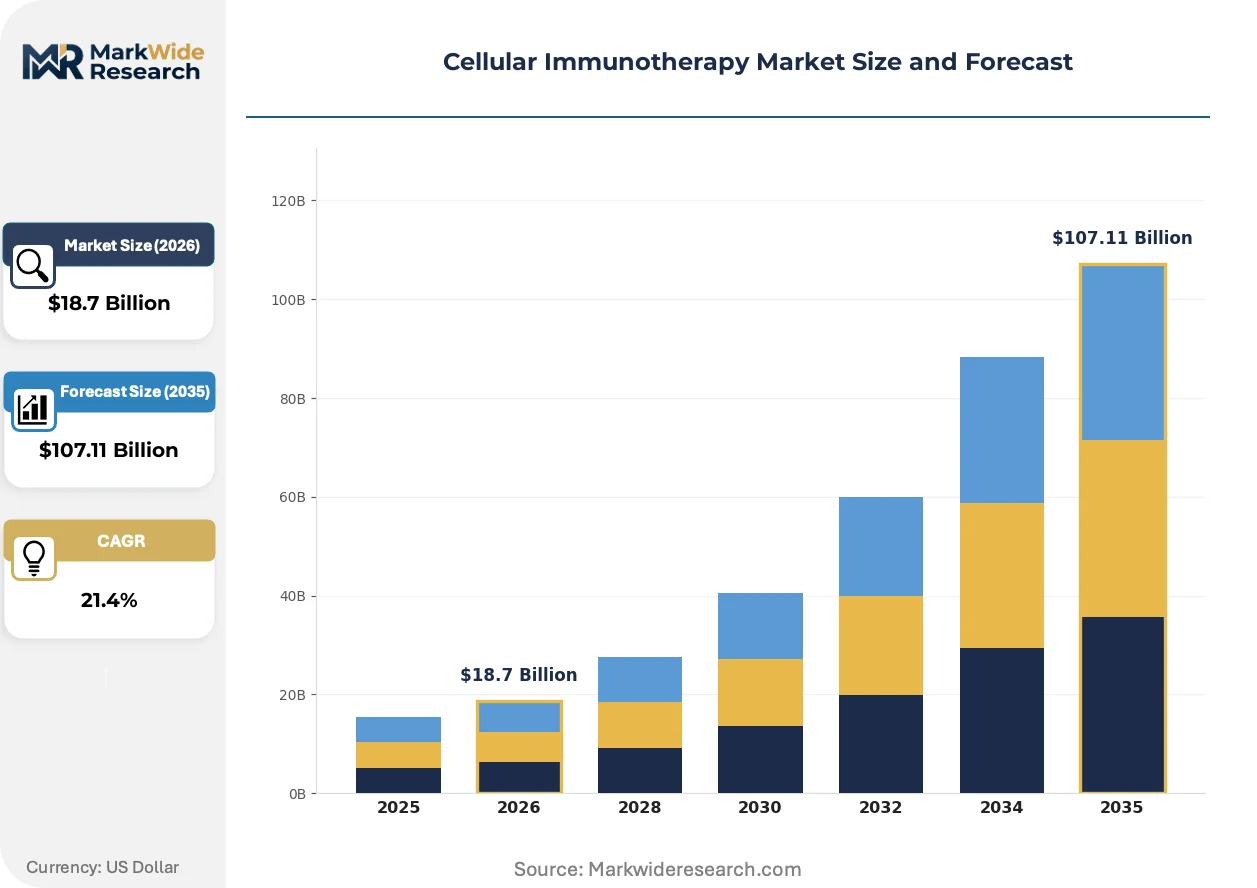
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $107.11 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAR-T Therapy, TCR Therapy, NK Cell Therapy, Stem Cell Therapy Application: Oncology, Autoimmune Disorders, Infectious Diseases, Regenerative Medicine End User: Hospitals, Research Institutions, Specialty Clinics, Biopharmaceutical Companies Technology: CRISPR, Gene Editing, Cell Separation, Cell Culture |
| Companies Covered | Novartis AG, Gilead Sciences Inc., Bristol-Myers Squibb Company, Johnson & Johnson, F. Hoffmann-La Roche Ltd, Merck KGaA, AstraZeneca, Pfizer Inc., Legend Biotech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Immunotherapy Market Strategic Shifts & Innovations
Vector engineering and manufacturing automation are converging to reshape cost structures, while regulatory frameworks adapt to accommodate accelerated development paradigms.
Sleeping Beauty transposon systems are electrifying non-viral gene delivery by eliminating reliance on GMP-grade viral particles. Contract development organizations serving mid-cap biotech sponsors are adopting these platforms to reduce cost-of-goods and simplify supply chains. The structural consequence is a compression of preclinical-to-IND timelines and a redistribution of manufacturing investment toward synthetic biology capabilities.
REACH registration requirements for novel chemical entities used in cell processing media are tightening substance documentation obligations for European manufacturers. The industrial consequence is a forced reformulation of cryopreservation and expansion media to exclude substances of very high concern. Cell therapy producers with EU commercialization plans are responding by qualifying alternative excipients and establishing dedicated European supply chains.
Hospital procurement committees are consolidating vendor relationships for CAR-T administration, favoring integrated service contracts that bundle leukapheresis, logistics, and inpatient care. Community oncology networks previously excluded from cellular therapy are gaining access through hub-and-spoke models with academic centers. The United States exhibits the most pronounced concentration, where Medicare reimbursement stability has enabled risk-sharing arrangements between manufacturers and hospital systems.
Cellular Immunotherapy Market Segmentation
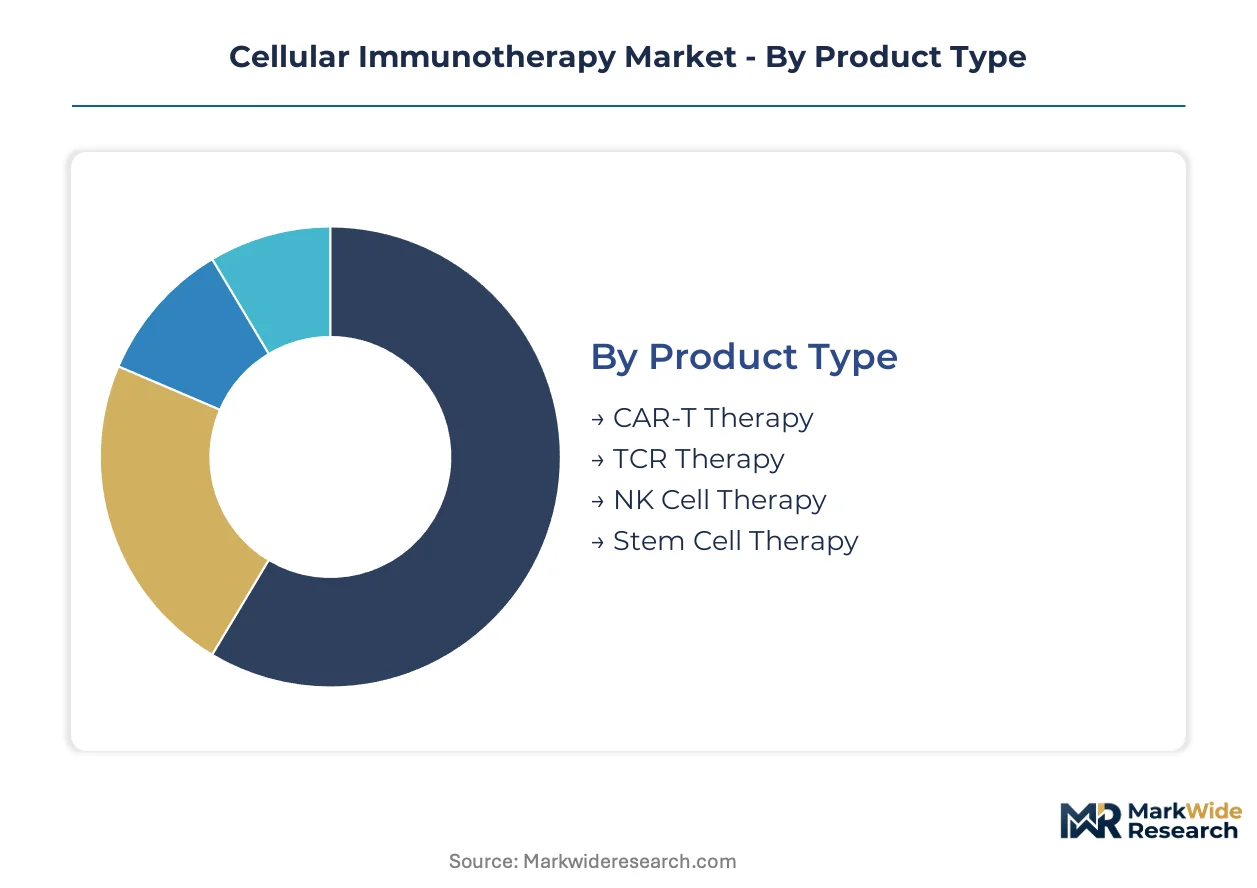
Cellular immunotherapy segmentation reveals how manufacturing complexity, reimbursement pathways, and clinical infrastructure shape commercial outcomes across distinct product architectures. Each dimension exposes different vectors of competitive advantage and investment risk.
Product Type:
Product architecture determines manufacturing scale, regulatory pathway, and reimbursement velocity.
- CAR-T Therapy:Autologous T-cell reprogramming using lentiviral or gamma-retroviral vectors dominates current revenue. Demand concentrates at academic medical centers in the United States where Medicare reimbursement codes for inpatient administration have normalized payment flows.
- NK Cell Therapy:Allogeneic natural killer cell products eliminate patient-matching constraints through feeder-free expansion protocols. Demand is climbing fastest in community oncology settings seeking off-the-shelf accessibility beyond specialized treatment centers.
- TCR Therapy:T-cell receptor engineering targets solid tumor antigens with MHC-restricted recognition mechanisms.
- Stem Cell Therapy:Hematopoietic and mesenchymal stem cell applications span oncology conditioning and regenerative indications.
Mature deployment sits with CAR-T Therapy. Newer deployment is concentrated in NK Cell Therapy.
Application:
Clinical indication selection dictates pricing power, trial design complexity, and competitive density.
- Oncology:Hematologic malignancies command established reimbursement with durable response endpoints driving payer acceptance. Demand concentrates in the United States and Germany where centralized CAR-T administration infrastructure has achieved operational scale.
- Autoimmune Disorders:Systemic lupus erythematosus and multiple sclerosis applications leverage B-cell depletion mechanisms validated in oncology. Pipeline assets are gaining share fastest as developers seek high-margin white space beyond saturated cancer indications.
- Infectious Diseases:Engineered T-cell therapies target persistent viral reservoirs including HIV and hepatitis.
- Regenerative Medicine:Stem cell-derived tissue repair applications span cardiac, neurological, and musculoskeletal conditions.
Commercial maturity clusters in Oncology. Pipeline momentum is accelerating in Autoimmune Disorders.
End User:
Site-of-care capabilities determine patient access, logistics complexity, and service contract structures.
- Hospitals:Academic medical centers with integrated leukapheresis, cryopreservation, and infusion units anchor current volume. Procurement committees in the United States are consolidating vendor relationships around bundled service contracts spanning logistics and inpatient care.
- Specialty Clinics:Community oncology networks are gaining access through hub-and-spoke models with academic centers, expanding treatment reach beyond traditional referral patterns.
- Research Institutions:Early-phase clinical trial execution and investigator-initiated studies drive protocol innovation.
- Biopharmaceutical Companies:In-house manufacturing campuses and contract manufacturing partnerships support pipeline progression.
Volume concentration remains with Hospitals. Access expansion is proceeding through Specialty Clinics.
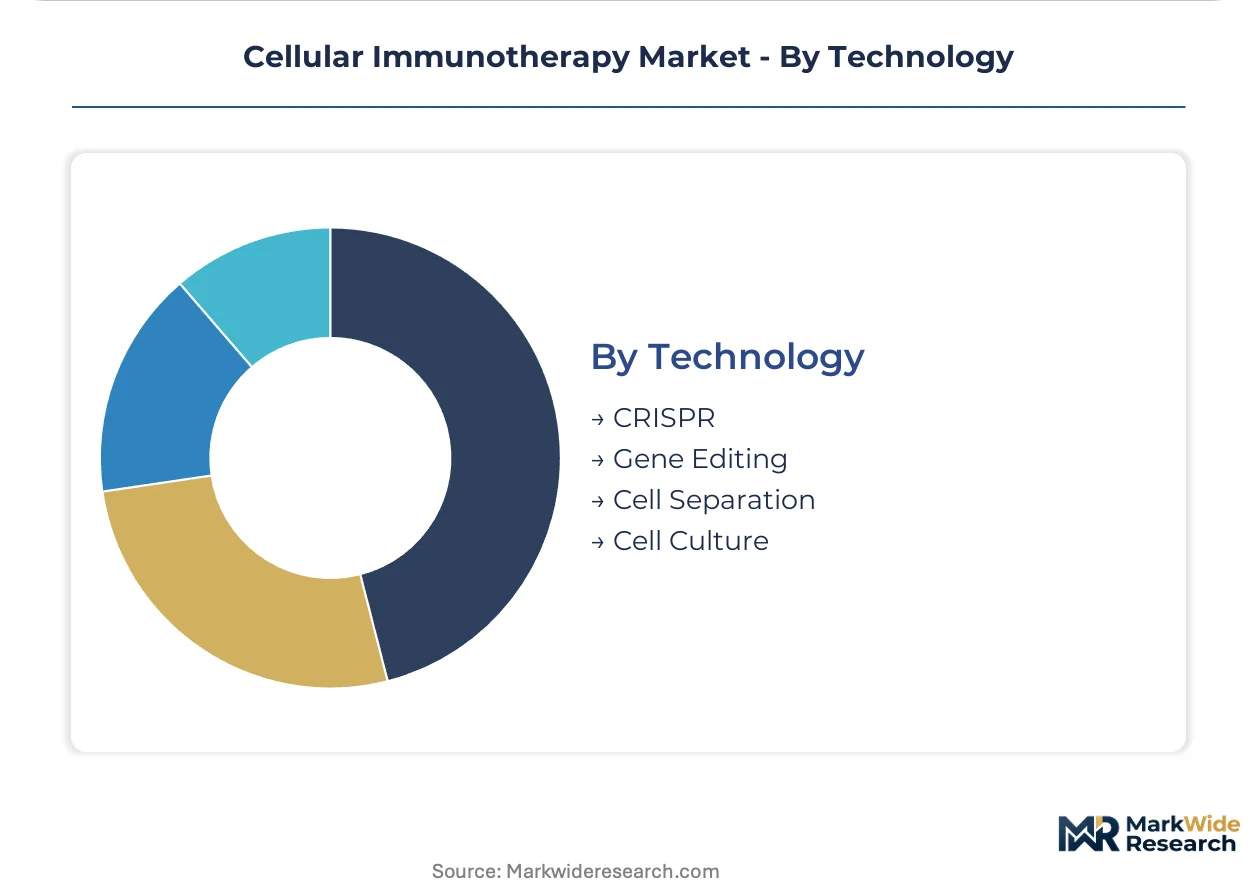
Technology:
Enabling technology selection shapes cost structures, intellectual property positions, and regulatory evidence requirements.
- Gene Editing:CRISPR-Cas9 and base editing platforms enable multiplexed genetic modifications for allogeneic cell products. Adoption is climbing fastest as developers engineer knockout phenotypes to reduce graft-versus-host risk and extend product persistence.
- Cell Culture:Serum-free and chemically defined media formulations support GMP-compliant expansion at clinical scale. Demand concentrates among contract manufacturers seeking to reduce lot-to-lot variability and simplify regulatory filings.
- CRISPR:Precise genomic targeting systems for therapeutic gene disruption and insertion.
- Cell Separation:Magnetic-activated and fluorescence-activated sorting technologies for population enrichment.
Established deployment centers on Cell Culture. Capability investment is intensifying in Gene Editing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentrates at academic medical centers where Medicare reimbursement for inpatient CAR-T administration has normalized payment flows and anchored treatment capacity expansion.
United States
FDA's Regenerative Medicine Advanced Therapy designation compresses clinical development timelines for qualifying cell therapies. The IRA's drug pricing provisions are reshaping reimbursement negotiations for durable response endpoints. Boston-Cambridge and San Francisco Bay Area clusters host the densest concentration of vector production facilities and cell therapy manufacturing campuses.
Germany
EMA's centralized marketing authorization procedure for Advanced Therapy Medicinal Products shapes European market access trajectories. REACH registration requirements for novel chemical entities in cell processing media are forcing reformulation of cryopreservation protocols. The Rhine-Main and Munich biotech corridors concentrate contract manufacturing capacity for lentiviral vector production.
Switzerland
Swissmedic's streamlined approval pathways for innovative therapies attract cell therapy developers seeking regulatory efficiency. Federal incentives for precision medicine infrastructure support manufacturing investment in the Lake Geneva region. Basel and Zurich anchor vector engineering and GMP-grade plasmid supply chain operations serving European markets.
China
NMPA's cell therapy guidelines and dual carbon goals are attracting manufacturing investment for Asia-Pacific supply positioning. National reimbursement negotiations for innovative therapies are expanding patient access beyond self-pay segments. Shanghai and Suzhou industrial parks concentrate CAR-T manufacturing capacity and CRISPR engineering platforms.
India
CDSCO's emerging cell therapy guidelines and PLI scheme incentives are positioning the country for Asia-Pacific supply chain integration. Cost advantages in bioprocess engineering talent are attracting contract development organization investment. Hyderabad and Bengaluru biotech clusters host expanding GMP manufacturing capacity for viral vector production.
Cellular Immunotherapy Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers commission dedicated cell therapy campuses to secure vector supply and reduce cost-of-goods. The vendor base clusters around three strategic archetypes: vertically integrated pharmaceutical conglomerates with captive plasmid supply chains, mid-cap biotech specialists pursuing platform diversification across autologous and allogeneic modalities, and contract development organizations adopting non-viral gene delivery systems to compress preclinical timelines. M&A activity and strategic technology licensing represent the dominant competitive moves as players secure manufacturing scale and intellectual property positions.
Among the integrated pharmaceutical tier, Novartis AG and Gilead Sciences Inc. exemplify scale-driven positioning through vertically structured vector production platforms. Bristol-Myers Squibb Company occupies a diversified position spanning dual-platform investments. These three entities represent contrasting strategic postures within a landscape where manufacturing sovereignty and regulatory pathway expertise determine competitive outcomes.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences Inc. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd |
| Merck KGaA |
| AstraZeneca |
| Pfizer Inc. |
| Legend Biotech Corporation |
| Others |
Cost & Logistics Intelligence
Autologous CAR-T and allogeneic NK cell tiers diverge sharply on manufacturing cost structure, with patient-specific processing commanding premium reimbursement while off-the-shelf protocols compress unit economics through donor-scale economies. This bifurcation manifests in supply chain geography: autologous production clusters at academic medical centers with captive leukapheresis units, whereas allogeneic manufacturing feeds from centralized GMP campuses with continental distribution reach.
Pricing Analysis
Volume concentration in autologous CAR-T sustains premium pricing anchored to Medicare inpatient reimbursement codes, while allogeneic NK products face margin compression from competitive manufacturing scale-up. Price differentiation hinges on durable response endpoints and vector engineering sophistication, with FDA regenerative medicine designation conferring access premiums. Cost compression in standard-grade allogeneic products is intensifying because contract manufacturers are qualifying feeder-free expansion protocols. Hospital procurement committees exhibit highest price sensitivity for logistics bundles, while biopharmaceutical sponsors remain least sensitive to vector production costs.
Supply Chain Analysis
GMP-grade plasmid qualification gates vector production, concentrating supply among United States, Switzerland, and Netherlands contract manufacturers with captive fermentation capacity. Manufacturing-grade plasmid DNA, lentiviral vector particles, and cryopreservation-grade dimethyl sulfoxide constitute critical input dependencies. Single-source vulnerability in plasmid supply creates structural exposure for mid-cap developers lacking backward integration. Distribution runs through integrated service contracts bundling leukapheresis, cold-chain logistics, and inpatient administration at academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing-grade plasmid scarcity props pricing for vector-integrated players, constraining expansion velocity for sponsors dependent on contract supply. Capacity bottlenecks at GMP fermentation facilities reward early manufacturing commitments.
For Market Incumbents: To counter allogeneic NK cell commoditization, Novartis and Gilead are deepening captive plasmid supply through dedicated fermentation campuses in Basel and California. Incumbents should secure leukapheresis capacity at academic medical centers through exclusive service contracts, while investing in feeder-free expansion protocols to reduce cost-of-goods in next-generation products. For New Entrants and Emerging Players: Community oncology networks underserved by current hub-and-spoke models represent the most penetrable access point, with specialty clinics seeking off-the-shelf NK products eliminating patient-matching delays. New entrants should target autoimmune disorder applications beyond saturated hematologic oncology, leveraging CDSCO regulatory harmonization in India for Asia-Pacific manufacturing positioning with lower bioprocess engineering costs. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated vector producers given FDA accelerated approval pathway compression and Medicare reimbursement stability. Acquisition targets with lentiviral platform scale and autoimmune pipeline assets offer long-term viability through indication expansion. The signal to watch is EMA advanced therapy medicinal products approval velocity as European market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive plasmid fermentation capacity secures vector supply against contract manufacturer bottlenecks. |
| Autoimmune Pipeline Diversification | Systemic lupus erythematosus applications unlock high-margin white space beyond oncology saturation. |
| Regulatory Approval Pathway | FDA regenerative medicine designation compresses clinical development timelines for qualifying constructs. |
| Geographic Expansion | India CDSCO harmonization and PLI incentives attract Asia-Pacific supply chain investment. |
| Technology Licensing | Sleeping Beauty transposon non-viral delivery reduces cost-of-goods and simplifies GMP compliance. |
Research Approach
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with CMS Medicare reimbursement data and hospital procurement databases. Primary interviews with cell therapy manufacturing executives, regulatory affairs leads at vector producers, academic medical center procurement directors, and payer access specialists validated demand assumptions and pricing dynamics. Bottom-up patient-flow modeling and top-down reimbursement value analysis were triangulated to anchor market sizing.
Bottom-up volume builds tracked treatment-eligible patient populations across hematologic malignancies and autoimmune indications, while top-down analysis calibrated against disclosed manufacturing capacity and vector production throughput. Segmentation dimensions spanned product architecture, clinical indication, site-of-care infrastructure, and enabling technology platform. CAGRs were derived from logistic diffusion curves fitted to reimbursement expansion timelines and manufacturing scale-up trajectories. Cryopreservation protocol evolution and allogeneic manufacturing yield improvements served as key forecast sensitivity inputs.
Revisions become necessary when plasmid supply disruptions, EMA regulatory timeline extensions, or autoimmune trial readouts materialize outside modeled scenarios. Forecasts reflect assumptions on Medicare reimbursement stability and vector manufacturing yield progression. A model refresh is warranted upon material change in FDA accelerated approval pathway utilization rates or CDSCO regulatory harmonization implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Inherited Orphan Blood Disorders Therapeutics Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Gene Electroporators Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market