
 Leukemia Therapeutics Treatment Market | 2026-2036
Leukemia Therapeutics Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Leukemia Therapeutics Treatment Market Foresight
EU MDR is expanding the cost-of-entry calculus for hematologic oncology device-drug combinations entering European markets. Novartis leverages its vertically integrated CAR-T manufacturing network to sustain supply security across multiple continents. Bristol-Myers Squibb anchors its position through deep R&D investment in bispecific antibody platforms for relapsed indications.
Leukemia therapeutics treatment encompasses pharmaceutical and cellular interventions designed to eliminate malignant hematopoietic cells, including alkylating agents, monoclonal antibodies, and autologous or allogeneic chimeric antigen receptor T-cell products manufactured under current Good Manufacturing Practice conditions with cryopreservation requirements and vector-based genetic modification. These interventions serve the primary purpose of inducing remission, preventing relapse, and extending survival in patients with hematologic malignancies. Targeted therapy occupies the margin-rich center of the market, driven by tyrosine kinase inhibitors and BCL-2 inhibitors that command premium positioning in chronic myeloid leukemia and acute myeloid leukemia respectively. Immunotherapy represents the fastest-expanding segment, with CAR-T and bispecific constructs displacing salvage chemotherapy in relapsed acute lymphoblastic leukemia. Stem cell transplantation remains mature and procedure-constrained, with growth limited by donor availability and transplant center capacity.
FDA breakthrough therapy designation, EMA PRIME eligibility, and WHO Essential Medicines List inclusion collectively shape development priorities, reimbursement negotiations, and market access timelines across jurisdictions. The FDA's accelerated approval framework permits earlier commercial entry contingent on confirmatory trials, while EMA's adaptive pathways parallel this flexibility for European launches. Stakeholders must monitor evolving regulatory demands for long-term follow-up data and real-world evidence mandates that will determine sustained market access for novel modalities.
Market Dynamics
Cell-based manufacturing scale-up is compressing commercialization timelines while straining cryopreservation logistics and vector production capacity across the leukemia therapeutics ecosystem.
Growth Catalysts
- FDA Accelerated Approval:The breakthrough therapy designation framework compresses Phase II-to-market intervals for hematologic oncology candidates, pulling forward revenue recognition timelines.
- Academic Medical Center Clustering:Hospital-based oncology departments in the United States concentrate CAR-T administration capacity, creating referral gravity that concentrates demand.
- Allogeneic Platform Maturation:Off-the-shelf cellular products promise manufacturing economies that autologous processes cannot match, electrifying investor allocation toward universal donor technologies.
Market Restraints
- Viral Vector Supply Concentration:Lentiviral and retroviral vector production concentrates among contract manufacturers in the United States and Europe, creating single-source vulnerability for CAR-T sponsors.
- EU MDR Compliance Burden:The Medical Device Regulation expands clinical evidence requirements for device-drug combinations, extending European market entry timelines by 18-24 months.
- Salvage Chemotherapy Substitution:Traditional cytotoxic regimens retain formulary position in resource-constrained settings, limiting premium therapy penetration in price-sensitive payer environments.
Strategic Opportunities
- India CDSCO Pathway:The country's national pharmaceutical regulator streamlines biosimilar and cellular therapy review, opening access to a treatment-naive patient pool exceeding 50,000 annual leukemia diagnoses.
- Real-World Evidence Mandates:FDA and EMA post-approval study requirements create competitive differentiation for sponsors with robust pharmacovigilance infrastructure.
- Point-of-Care Manufacturing:Decentralized cell processing at transplant centers promises logistics cost compression and vein-to-vein time reduction.
Industry Challenges
- Vector Bioprocess Engineering Talent:Scarcity of professionals combining viral production expertise with current Good Manufacturing Practice compliance limits manufacturing expansion velocity.
- Long-Term Follow-Up Infrastructure:Regulatory mandates for 15-year patient monitoring strain sponsor data collection capabilities and site retention economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leukemia Therapeutics Treatment Market |
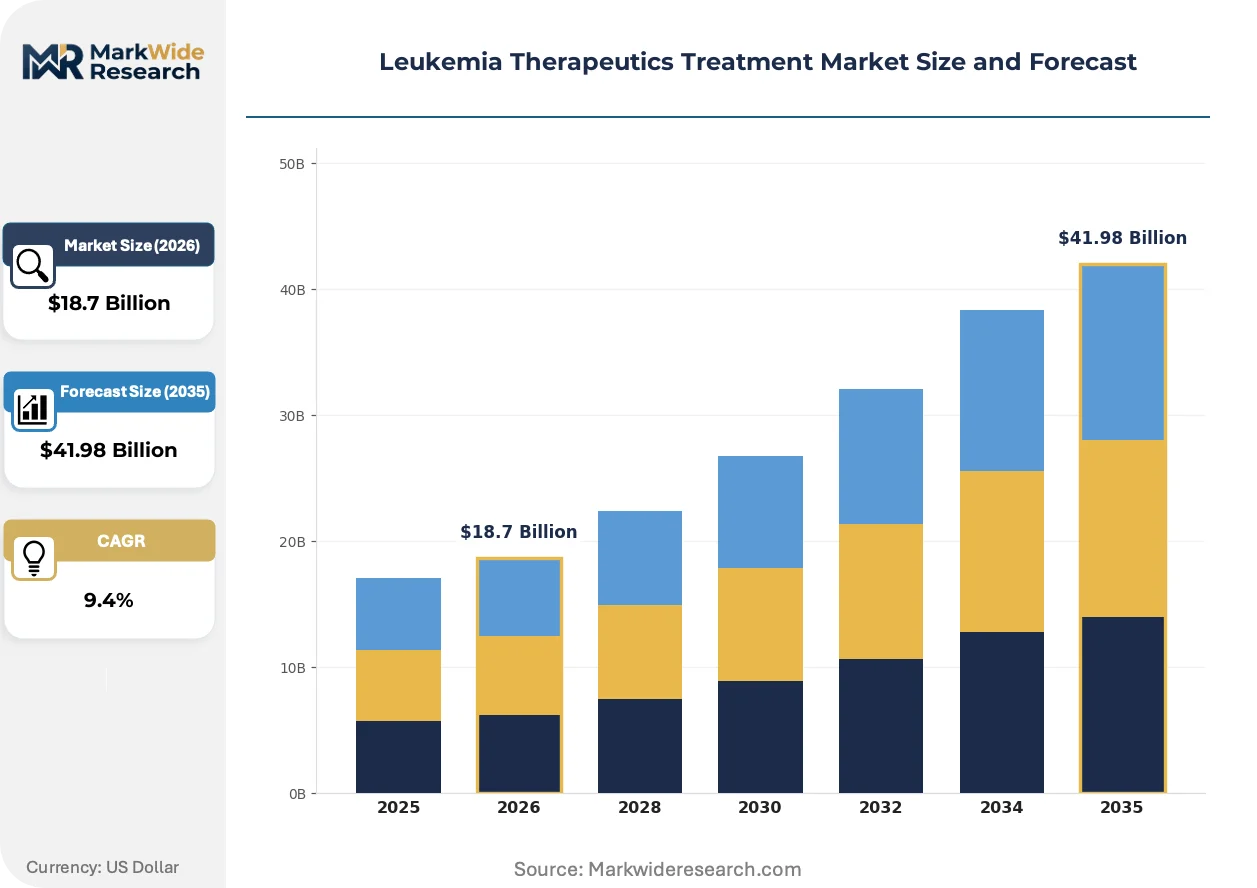
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Stem Cell Transplantation Delivery Mode: Intravenous, Oral, Subcutaneous, Intrapleural End User: Hospitals, Clinics, Research Institutes, Home Care Indication: Acute Myeloid Leukemia, Chronic Lymphocytic Leukemia, Chronic Myeloid Leukemia, Acute Lymphoblastic Leukemia |
| Companies Covered | Novartis, Bristol-Myers Squibb, Pfizer, F. Hoffmann-La Roche, AbbVie, Amgen, Johnson & Johnson, Sanofi, Takeda Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leukemia Therapeutics Treatment Market Shifts & Advancements
Next-generation modalities are compressing the therapeutic index between efficacy and toxicity while regulatory frameworks adapt to accelerated evidentiary standards.
Allogeneic CAR-T platforms are electrifying the manufacturing economics of cellular therapy. These off-the-shelf products eliminate patient-specific leukapheresis and reduce vein-to-vein intervals from weeks to days. Academic medical centers and community oncology networks are piloting allogeneic protocols ahead of full commercial approval.
EMA's adaptive pathways framework parallels FDA breakthrough designation, creating regulatory convergence that harmonizes European and American launch sequencing. The PRIME eligibility scheme prioritizes hematologic oncology assets for accelerated assessment, compressing scientific advice timelines. Sponsors are restructuring clinical development to generate confirmatory data simultaneously across both jurisdictions.
Hospital pharmacy committees are consolidating cellular therapy procurement under centralized value analysis frameworks. Traditional physician preference purchasing is yielding to outcomes-based contract structures that tie reimbursement to complete response rates at six months. This behavioral shift is most visible in United States academic medical centers, where CAR-T volume thresholds determine preferred vendor status.
Leukemia Therapeutics Treatment Market Segmentation
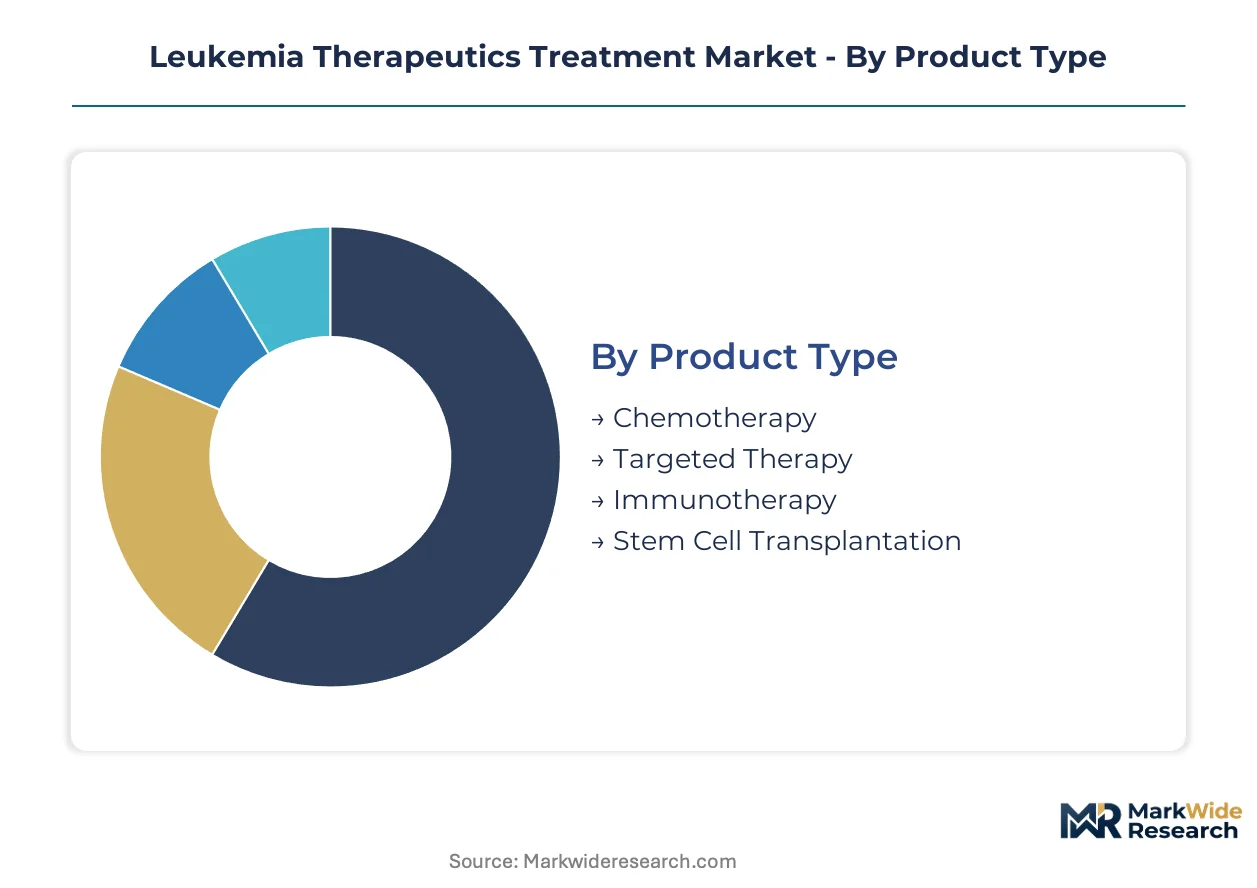
Leukemia therapeutics demand fragments across four distinct axes: molecular mechanism, administration route, care setting, and disease subtype. Each segmentation layer reveals divergent margin structures, regulatory pathways, and capacity constraints that reshape competitive positioning.
Product Type:
Customization intensity varies sharply across this category, from standardized cytotoxic protocols to patient-specific cellular manufacturing.
- Targeted Therapy:Tyrosine kinase inhibitors and BCL-2 antagonists deliver precision blockade of oncogenic signaling. Academic medical centers in the United States concentrate procurement of these oral agents, drawn by companion diagnostic requirements and premium reimbursement tiers.
- Immunotherapy:CAR-T constructs and bispecific antibodies redirect immune effector cells against malignant clones. Demand clusters at transplant-capable hospitals with apheresis infrastructure and FDA-registered cell processing facilities.
- Chemotherapy:Alkylating agents and antimetabolites retain formulary position in resource-constrained settings where salvage regimens dominate.
- Stem Cell Transplantation:Allogeneic and autologous graft procedures remain procedure-constrained by donor registries and transplant center accreditation.
Leading the category by volume: Chemotherapy. Expanding most quickly: Immunotherapy.
Delivery Mode:
Route selection tracks the cost tier of care setting, with institutional administration commanding higher reimbursement than ambulatory or home-based alternatives.
- Intravenous:Infusion-dependent biologics and cytotoxics require hospital pharmacy oversight for compounding and adverse event management. United States oncology clinics anchor volume for this mode.
- Oral:Small-molecule kinase inhibitors enable outpatient adherence monitoring with lower per-dose logistics burden. Patient assistance programs and specialty pharmacy networks concentrate distribution.
- Subcutaneous:Monoclonal antibody formulations reduce infusion chair time and shift administration toward community oncology practices.
- Intrapleural:Regional delivery for leukemic pleural involvement remains niche, confined to tertiary referral centers with interventional pulmonology capability.
Highest volume concentration: Intravenous. Steepest expansion trajectory: Oral.
End User:
Customer type determines procurement sophistication, with institutional buyers leveraging GPO contracts against fragmented home care reimbursement.
- Hospitals:Academic medical centers and community hospital systems consolidate CAR-T and transplant capacity under centralized value analysis frameworks. FDA REMS programs mandate these sites for cellular therapy.
- Clinics:Community oncology networks administer oral targeted agents and subcutaneous biologics, capturing patients outside transplant referral catchments.
- Research Institutes:Early-phase trial sites concentrate investigational agent exposure under NIH and pharmaceutical sponsor protocols.
- Home Care:Oral therapy administration shifts to this setting where nursing support and remote monitoring infrastructure exist.
Dominant by revenue: Hospitals. Gaining share fastest: Home Care.
Indication:
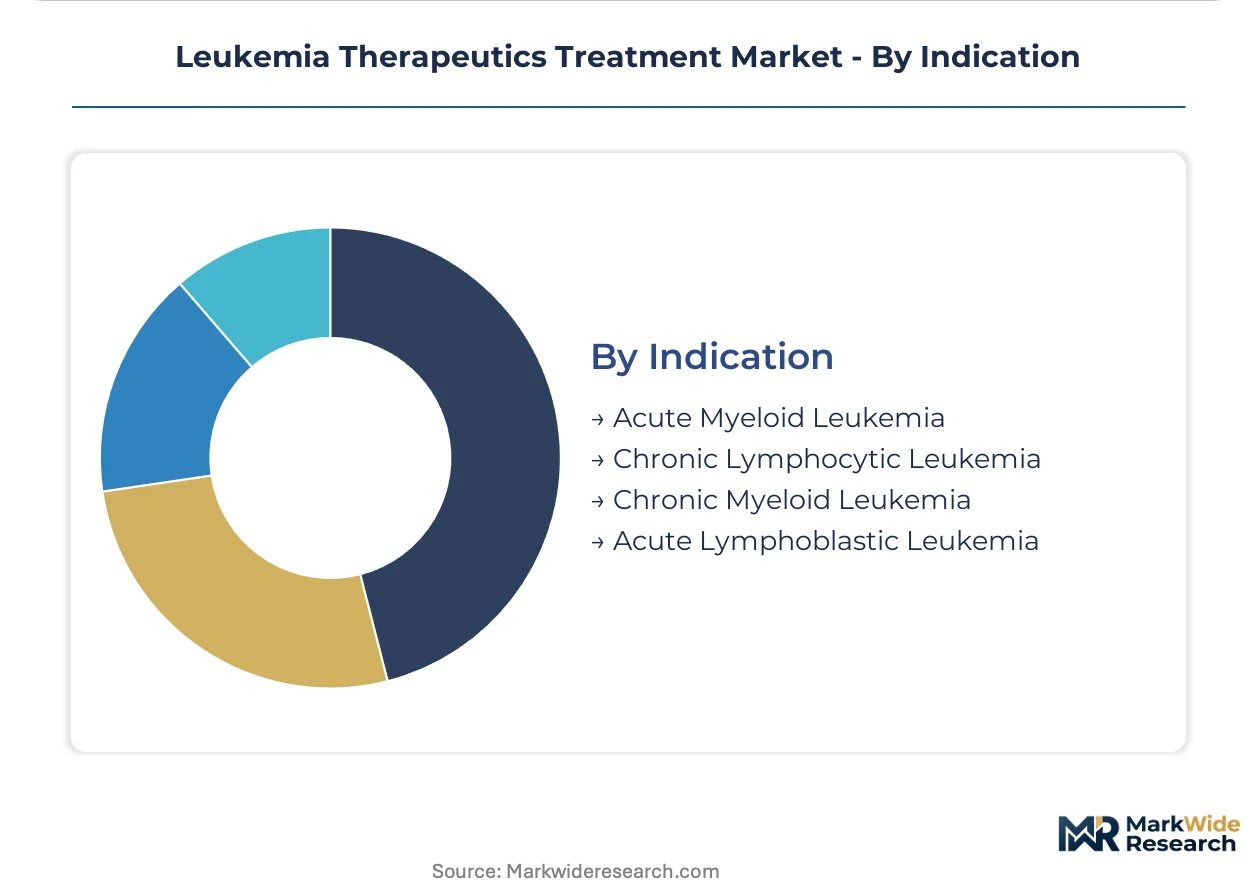
Disease subtype segmentation maps to distinct molecular drivers, with Philadelphia chromosome status and cytogenetic risk profiles determining therapeutic algorithm.
- Acute Myeloid Leukemia:FLT3 and IDH mutations stratify treatment selection toward approved targeted combinations. United States leukemia centers drive adoption of venetoclax-based regimens in unfit populations.
- Acute Lymphoblastic Leukemia:CD19-directed CAR-T and bispecific constructs displace salvage chemotherapy in relapsed pediatric and adult cohorts. Pediatric trial networks concentrate enrollment.
- Chronic Myeloid Leukemia:BCR-ABL tyrosine kinase inhibitors sustain deep molecular response as chronic oral therapy.
- Chronic Lymphocytic Leukemia:BTK inhibitors and BCL-2 antagonists have displaced chemoimmunotherapy in frontline and relapsed settings.
Largest patient population: Chronic Lymphocytic Leukemia. Climbing the fastest: Acute Lymphoblastic Leukemia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and the Greater Boston biotechnology corridor concentrate cell therapy manufacturing under state-level tax abatement schemes. These zones anchor domestic viral vector production and CAR-T processing capacity.
United States
Academic medical centers in Houston, Boston, and Seattle drive CAR-T administration volume through NIH-funded transplant networks. FDA breakthrough therapy designation compresses commercialization timelines for hematologic oncology candidates. The Research Triangle Park corridor anchors lentiviral vector manufacturing for multiple sponsors.
Germany
Heidelberg and Munich university hospitals concentrate European CAR-T enrollment under EMA PRIME eligibility pathways. The country's national pharmaceutical regulator enforces EU MDR compliance for device-drug combinations entering clinical use. Frankfurt and Mannheim host contract manufacturing organizations serving continental vector demand.
China
NMPA conditional approval pathways accelerate domestic CAR-T launches for relapsed acute lymphoblastic leukemia. The Yangtze River Delta biotechnology zone in Shanghai and Suzhou anchors cell therapy manufacturing infrastructure. Beijing's academic medical centers pilot allogeneic platforms ahead of full regulatory authorization.
India
CDSCO streamlined review pathways open access to a treatment-naive patient pool exceeding fifty thousand annual leukemia diagnoses. The country's national pharmaceutical regulator prioritizes biosimilar and cellular therapy applications. Mumbai and Hyderabad anchor contract research organization networks supporting multinational trial enrollment.
Japan
PMDA sakigake designation accelerates priority review for hematologic oncology innovations. The Kanto region surrounding Tokyo concentrates transplant-capable hospitals with apheresis infrastructure. Osaka and Nagoya academic centers participate in multinational CAR-T protocols under harmonized ICH guidelines.
Leukemia Therapeutics Treatment Market Competitive Landscape
Swiss and American producers anchor the premium-tier anchored by vertically integrated manufacturing networks; German and Japanese specialists hold positions in precision oncology platforms. The structure concentrates around three strategic archetypes: diversified pharmaceutical conglomerates with cell therapy manufacturing capabilities, biotechnology specialists focused on bispecific constructs, and emerging cellular therapy pure-plays advancing allogeneic platforms. Competitive moves center on manufacturing capacity expansion and strategic partnerships for vector supply security.
Within the diversified pharmaceutical tier, Novartis and Bristol-Myers Squibb exemplify integrated manufacturing strategies spanning multiple continents. Pfizer occupies a position emphasizing targeted small-molecule combinations. These three anchors represent distinct approaches to sustaining supply security amid viral vector production constraints.
| Leading Market Players |
|---|
| Novartis |
| Bristol-Myers Squibb |
| Pfizer |
| F. Hoffmann-La Roche |
| AbbVie |
| Amgen |
| Johnson & Johnson |
| Sanofi |
| Takeda Pharmaceutical |
| Others |
Supply & Pricing Matrix
Hospital pharmacy committee consolidation under centralized value analysis frameworks is compressing procurement timelines for cellular therapies, forcing manufacturers to absorb cryopreservation logistics costs or cede preferred vendor status at academic medical centers in the United States. This buyer-side restructuring elevates complete response rate guarantees as the dominant price differentiation mechanism, squeezing margin flexibility for sponsors lacking robust real-world evidence infrastructure.
Pricing Analysis
Short lead-time premiums dominate contract negotiations for autologous CAR-T products, with vein-to-vein intervals below twenty-one days commanding preferred formulary placement at transplant-capable hospitals. Three-tier pricing structure across premium, standard, and economy levels stratifies by manufacturing location and vector provenance, with FDA-registered facilities capturing sustained premiums. Cost compression in the chemotherapy substitution tier is intensifying because salvage regimen sponsors compete on per-cycle acquisition cost for resource-constrained payers. Community oncology networks exhibit highest price sensitivity due to reimbursement lag and infusion chair economics, while academic medical centers prioritize outcomes-based contracts over unit pricing.
Supply Chain Analysis
Single-source vulnerability sits with lentiviral vector production concentrated among contract manufacturers in the United States and Germany, creating chokepoint exposure for CAR-T sponsors dependent on third-party transfection capacity. Manufacturing feedstocks draw from plasma-derived media components, cryopreservation dimethyl sulfoxide, and GMP-grade plasmid DNA anchored in North American and European supply bases. Tariff exposure on Chinese-sourced ancillary reagents compounds logistics risk for sponsors without captive upstream control. Distribution runs through hospital-based specialty pharmacies with REMS-mandated cold chain custody, limiting direct-to-site alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vector manufacturing scarcity and fifteen-year follow-up mandates are accelerating consolidation, forcing cellular therapy pure-plays toward strategic acquisition by diversified pharmaceutical conglomerates with integrated pharmacovigilance infrastructure.
For Market Incumbents: Cement supply security through backward integration into viral vector bioprocessing or exclusive offtake agreements with GMP-certified contract manufacturers in the Research Triangle Park corridor. Lock in preferred vendor status at high-volume academic medical centers by embedding complete response rate guarantees into outcomes-based contracts, neutralizing bispecific antibody substitution threats from Bristol-Myers Squibb and Amgen. For New Entrants and Emerging Players: Begin with allogeneic platform development targeting the India CDSCO pathway, where streamlined biosimilar and cellular therapy review opens access to a treatment-naive patient pool exceeding fifty thousand annual leukemia diagnoses. Capture market entry through point-of-care manufacturing partnerships with Mumbai and Hyderabad transplant centers, bypassing centralized cryopreservation logistics that constrain established autologous players. For Investors and Strategic Acquirers: Re-rating potential sits with allogeneic platform specialists given FDA breakthrough therapy designation acceleration for off-the-shelf cellular products. Position for five-to-ten year horizon value capture by targeting acquisition candidates with validated universal donor cell lines and established CDMO relationships in the Yangtze River Delta or Greater Boston biotechnology corridor. Monitor NMPA conditional approval announcements for domestic Chinese CAR-T launches as the inflection signal for manufacturing capacity utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Vertically integrated CAR-T networks sustain supply security across multiple continents amid vector scarcity. |
| Regulatory Approval Pathway | EMA PRIME eligibility compresses scientific advice timelines for hematologic oncology assets entering European markets. |
| Clinical Trial Advancement | Academic medical center clustering in Houston and Boston concentrates CAR-T enrollment under NIH-funded transplant networks. |
| Pipeline Diversification | Bispecific antibody platforms for relapsed acute lymphoblastic leukemia displace salvage chemotherapy in pediatric cohorts. |
| Licensing Agreement | Vector supply partnerships with Frankfurt and Mannheim CMOs mitigate single-source vulnerability for continental European launches. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced against formulary database extracts and CMS Medicare reimbursement schedules. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated demand assumptions and pricing elasticity estimates. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level projections.
Bottom-up volume estimates tracked treatment line penetration, dosage form preference, administration route economics, and regional regulatory cluster adoption curves across the modeling period. Analysts derived CAGRs from log-linear trend fitting against historical approval velocity and analog therapy launch trajectories. Forecast inputs incorporated CAR-T manufacturing capacity expansion announcements, vector production lead times, and transplant center accreditation rates as industry-specific demand constraints.
Underlying measurement precision varies by segment; chronic myeloid leukemia tyrosine kinase inhibitor volume carries tighter precision than emerging allogeneic platform adoption. Forecasts reflect assumptions regarding FDA accelerated approval conversion rates, EMA adaptive pathway uptake, and real-world evidence mandate compliance timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market
Cell & Gene Therapy
Oncolytic Adenovirus Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market