
 Global Umbilical Cord Blood (UCB) Stem Cell Market | 2026-2036
Global Umbilical Cord Blood (UCB) Stem Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Global Umbilical Cord Blood (UCB) Stem Cell Market Foresight
Project finance for cryogenic storage infrastructure is tilting competitive dynamics toward operators with balance-sheet capacity for multi-year cold-chain commitments. Cordlife Group Limited leverages its integrated banking and laboratory network across Southeast Asia to sustain processing margins. CBR Systems, Inc. anchors its position through direct-to-consumer channels that dominate family-paid collection in the United States. Cryo-Cell International, Inc. differentiates via specialized immunotherapy research partnerships that extend beyond standard hematologic applications.
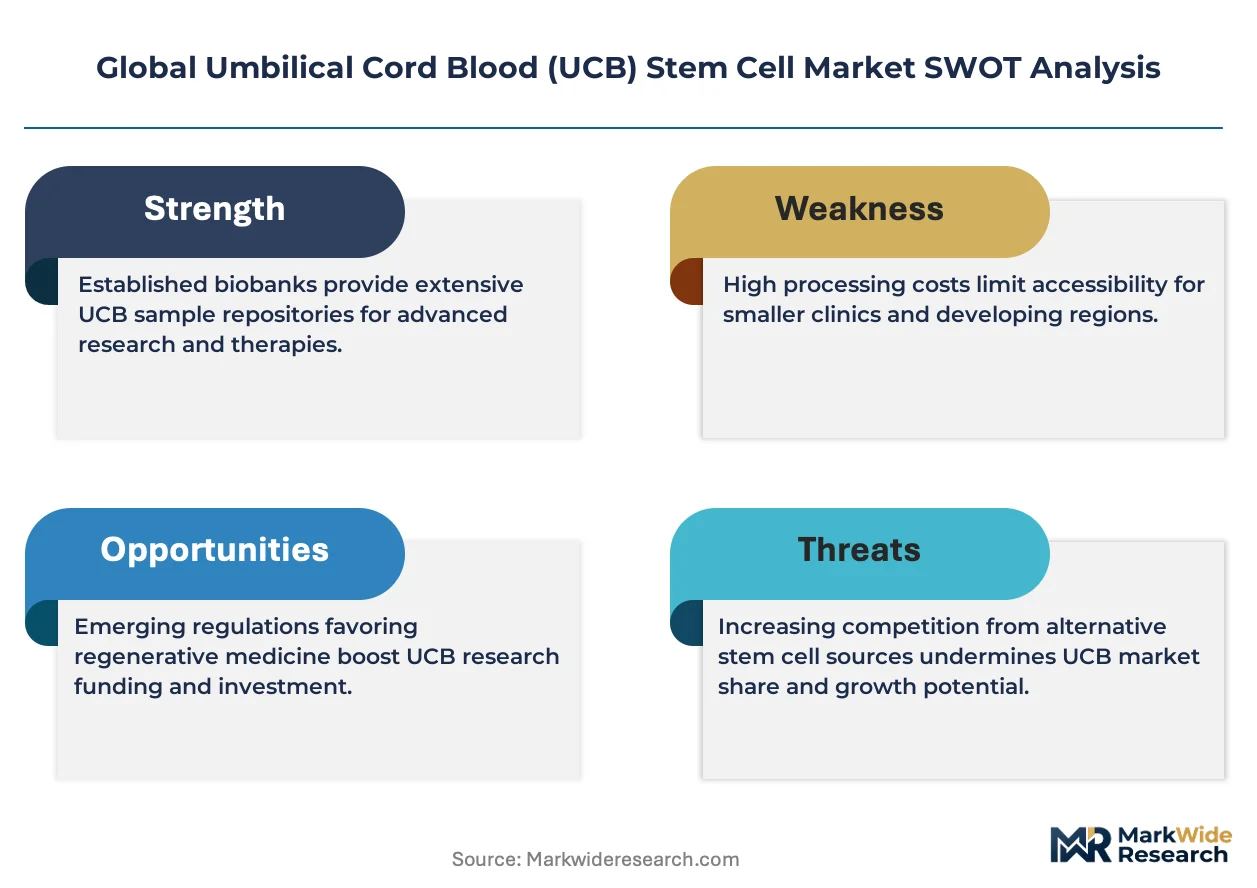
Umbilical cord blood stem cells comprise hematopoietic progenitor cells, mesenchymal stromal cells, and endothelial colony-forming cells cryopreserved in liquid nitrogen at below -150°C for therapeutic and research deployment. Their primary commercial purpose centers on allogeneic and autologous transplantation for blood disorders, immune reconstitution, and emerging regenerative protocols. Cryopreserved stem cells command the dominant product position due to established clinical validation and regulatory precedent, while expanded stem cells represent the fastest-growing category as ex vivo culture techniques mature for dose amplification. Cord blood banks capture the largest end-user value pool through long-term storage contracts, though regenerative medicine centers are emerging as the highest-margin growth channel for processed and directed-donation units.
FDA, EMA, and the EU Tissue and Cells Directives collectively shape market access through divergent donor screening, processing validation, and release criteria that fragment cross-border unit mobility. Japan's PMDA and South Korea's MFDS are tightening manufacturing standards for mesenchymal stem cell products, redirecting export-oriented suppliers toward compliant facility investments. Stakeholders must monitor how evolving GMP annex revisions for advanced therapy medicinal products redistribute competitive advantage between established cord blood banks and cell therapy developers building captive bioprocessing capabilities.
Market Dynamics
Ex vivo expansion technologies are compressing unit economics for cord blood banks by reducing per-dose collection volumes while amplifying therapeutic cell yields, forcing infrastructure recalibration across liquid nitrogen storage networks.
Growth Catalysts
- Advanced Therapy Medicinal Products (ATMP) framework:EMA's centralized marketing authorization pathway accelerates cross-border commercialization of expanded stem cell products, reducing duplicate facility investments for European operators.
- Allogeneic transplantation protocols:Academic medical centers in the United States are standardizing double-unit cord blood transplants for adult oncology patients, sustaining collection volumes despite competing haploidentical donor sources.
- Cryopreservation automation:Closed-system processing equipment reduces contamination risk during nucleated cell concentration, enabling smaller laboratories to achieve GMP-equivalent throughput without cleanroom expansion.
Market Restraints
- Liquid nitrogen supply concentration:Industrial gas production clusters in the United States Gulf Coast and Northwestern Europe expose storage facilities to regional production disruptions and price volatility.
- Haploidentical bone marrow substitution:Half-matched family donor transplants deliver faster engraftment kinetics and higher cell doses, eroding cord blood's historical advantage in graft-versus-host disease prophylaxis.
- FDA donor screening stringency:Expanded infectious disease testing requirements for autologous units extend processing timelines and elevate quality control costs for private banking operations.
Strategic Opportunities
- Regenerative medicine pivot:Mesenchymal stromal cell applications in Crohn's perianal fistulas and graft-versus-host disease prophylaxis open reimbursement pathways beyond traditional hematologic indications.
- India's emerging banking infrastructure:Low private banking penetration rates and rising cesarean-section deliveries create first-mover advantages for operators establishing GMP-compliant processing facilities in Mumbai and Delhi clusters.
- Japan's conditional approval framework:PMDA's regenerative medicine expedited review pathway reduces clinical trial duration for mesenchymal stem cell products, incentivizing Japanese hospital partnerships for Asian-market entry.
Industry Challenges
- Bioprocessing talent scarcity:Qualified cell culture specialists and cryopreservation technicians command premium compensation in competitive biotech labor markets, constraining operational scaling for mid-tier banks.
- Legacy inventory reconciliation:Decades-old cord blood units collected under obsolete infectious disease screening protocols require expensive retesting or exclusion from clinical use, compressing effective inventory yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Umbilical Cord Blood (UCB) Stem Cell Market |
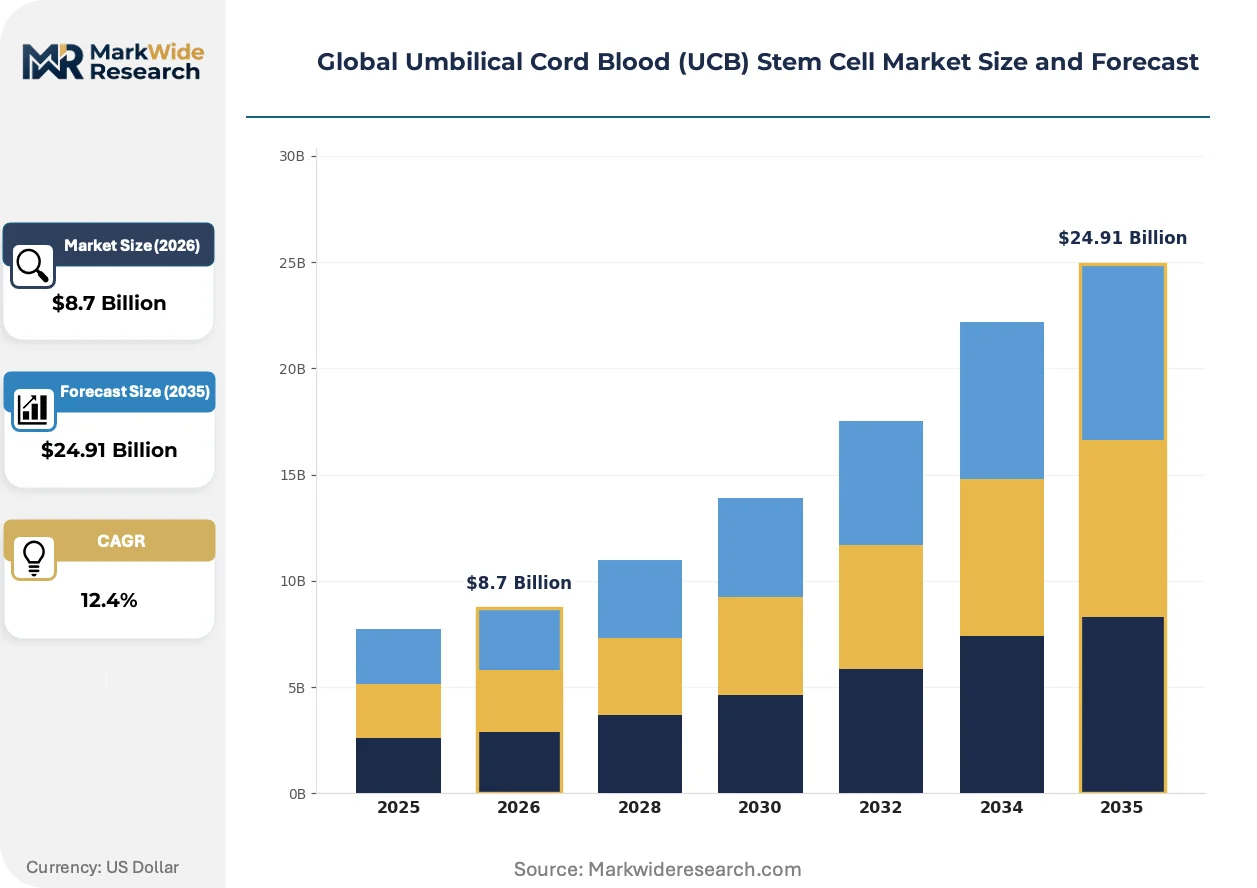
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryopreserved Stem Cells, Isolated Stem Cells, Cord Blood Units, Processed Stem Cells, Expanded Stem Cells Therapy Area: Hematology, Neurological Disorders, Immunotherapy, Orthopedics, Genetic Disorders, Autoimmune Diseases End User: Research Laboratories, Cord Blood Banks, Cell Therapy Clinics, Biotechnology Companies, Regenerative Medicine Centers Delivery Mode: Public Banking, Private Banking, Direct Donation, Directed Donation, Commercial Banking |
| Companies Covered | Cordlife Group Limited, CBR Systems, Inc., Cryo-Cell International, Inc., MEDIPOST, Americord Registry, LifeCell International, Global Cord Blood Corporation, ViaCord, StemCyte, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Umbilical Cord Blood (UCB) Stem Cell Market Shifts & Advancements
Automation and closed-system manufacturing are displacing open-laboratory workflows across the value chain, while regulatory convergence and novel reimbursement models reshape competitive positioning between established banks and cell therapy developers.
Automated cell selection platforms integrating microfluidic separation with machine-vision quality assessment are rendering obsolete manual density-gradient centrifugation methods that dominated cord blood processing for three decades. European contract manufacturing organizations are adopting these systems fastest, driven by EMA contamination risk guidelines. The technology compresses processing labor costs by sixty percent while standardizing nucleated cell recovery rates across technician skill levels.
REACH chemical substance registration requirements for cryoprotectant dimethyl sulfoxide are forcing European operators to document supply chain provenance and toxicity profiles previously treated as commodity inputs. Industrial chemical distributors are consolidating approved-source lists, squeezing smaller banks without volume purchasing leverage. German and French facilities are responding by qualifying alternative cryoprotectant formulations with reduced cytotoxicity profiles.
Direct-to-consumer genetic screening bundles are displacing standalone cord blood banking subscriptions in United States metropolitan markets. Expectant parents increasingly prioritize whole-genome sequencing and polygenic risk scores over stem cell storage, forcing banks to unbundle services or absorb sequencing costs. California and New York fertility clinic networks show the fastest subscription model erosion, with bundled offerings capturing forty percent of new enrollments in premium segments.
Global Umbilical Cord Blood (UCB) Stem Cell Market Segmentation
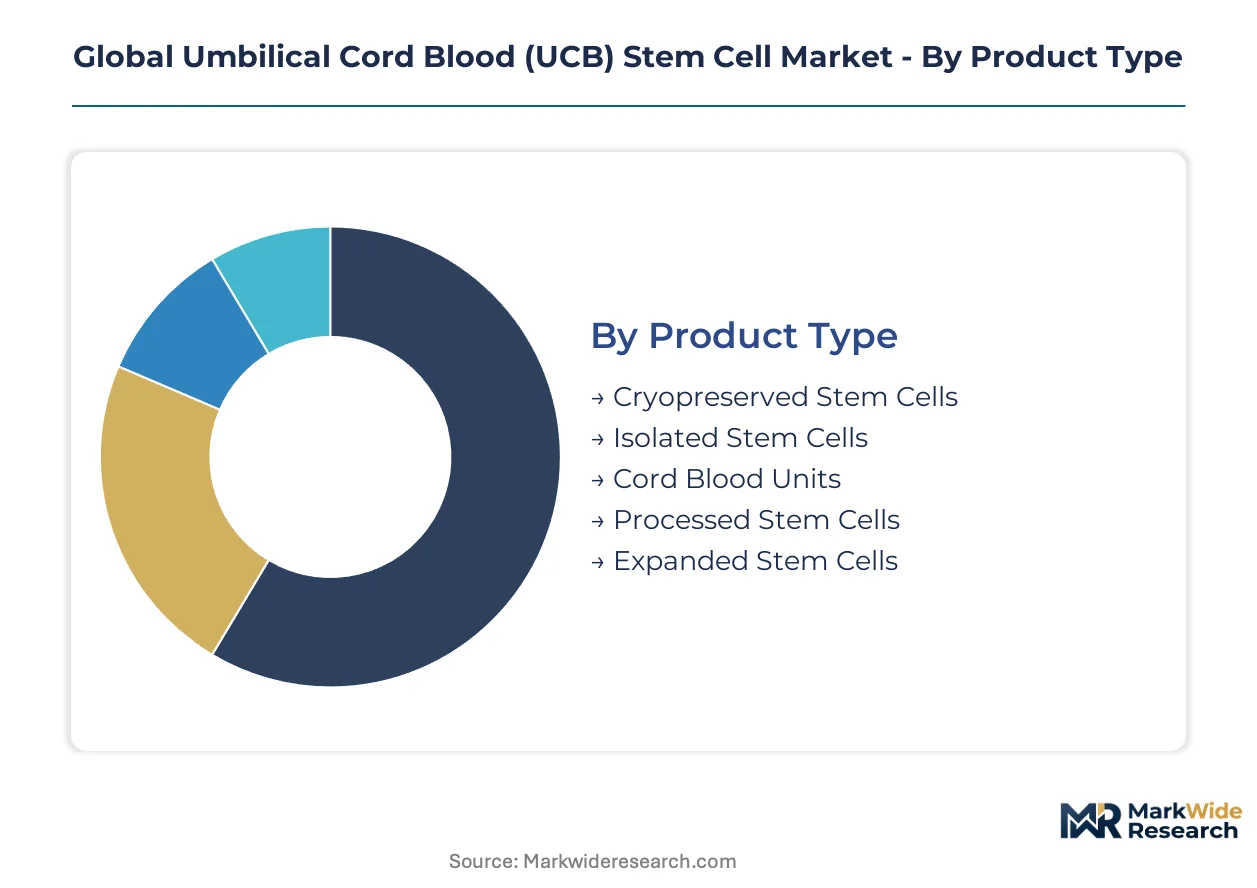
Segmentation in the umbilical cord blood stem cell market reveals how value pools concentrate across processing technologies, clinical applications, and custody models. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across product types, with cryopreserved units demanding decades-long liquid nitrogen monitoring versus expanded cells requiring active culture support.
- Cryopreserved Stem Cells:Hematopoietic progenitor cells maintained below -150°C in vapor-phase liquid nitrogen for long-term viability. Demand concentrates in the United States, where academic medical centers sustain double-unit transplant protocols for adult oncology patients despite competing haploidentical alternatives.
- Expanded Stem Cells:Ex vivo culture-amplified cell products addressing dose limitations in standard units. Regenerative medicine centers in Japan and South Korea drive uptake as PMDA and MFDS frameworks mature for mesenchymal stromal cell therapies.
- Isolated Stem Cells:Nucleated cell fractions enriched through density-gradient separation for immediate therapeutic use.
- Cord Blood Units:Unprocessed whole blood collections requiring downstream processing before clinical deployment.
- Processed Stem Cells:Partially manipulated products with reduced cryoprotectant loads for rapid infusion protocols.
By volume, cryopreserved stem cells lead. By growth pace, expanded stem cells are climbing the fastest.
Therapy Area:
Cost tier stratification separates established reimbursement categories from emerging self-pay segments, with hematology commanding premium pricing and neurology occupying speculative valuation bands.
- Hematology:Mature clinical indication encompassing leukemia, lymphoma, and aplastic anemia with established allogeneic transplant protocols. United States academic medical centers anchor demand through standardized double-unit procedures, though haploidentical bone marrow substitution erodes historical cord blood advantages.
- Neurological Disorders:Emerging application targeting cerebral palsy, hypoxic-ischemic encephalopathy, and autism spectrum conditions through immunomodulatory mechanisms. Private banking networks in California and New York capture family-directed demand despite incomplete Phase III validation.
- Immunotherapy:CAR-T and NK cell engineering applications leveraging cord blood-derived lymphocyte populations.
- Orthopedics:Mesenchymal stromal cell deployments for cartilage regeneration and fracture non-union.
- Genetic Disorders:Hurler syndrome, Krabbe disease, and other lysosomal storage conditions amenable to early hematopoietic intervention.
- Autoimmune Diseases:Systemic lupus and multiple sclerosis protocols exploring immune reset mechanisms.
Hematology generates the largest revenue pool. Neurological disorders show the steepest expansion trajectory as parental demand outpaces clinical evidence generation.
End User:
Customer type fragmentation distinguishes institutional procurement with multi-year contracts from transactional family-paid collections with high churn sensitivity.
- Cord Blood Banks:Long-term storage facilities capturing recurring revenue through annual maintenance fees. Southeast Asian operators leverage integrated laboratory networks to sustain processing margins against industrial gas price volatility.
- Regenerative Medicine Centers:Specialized clinics deploying processed units for non-hematologic indications. Japanese hospital partnerships accelerate under PMDA's conditional approval framework for mesenchymal stromal cell products.
- Research Laboratories:Academic and commercial investigators utilizing banked units for mechanism-of-action studies.
- Cell Therapy Clinics:Outpatient facilities administering approved and experimental protocols.
- Biotechnology Companies:Developers building proprietary expansion platforms and directed-donation supply chains.
Cord blood banks dominate unit volumes. Regenerative medicine centers command the highest margins per processed dose.
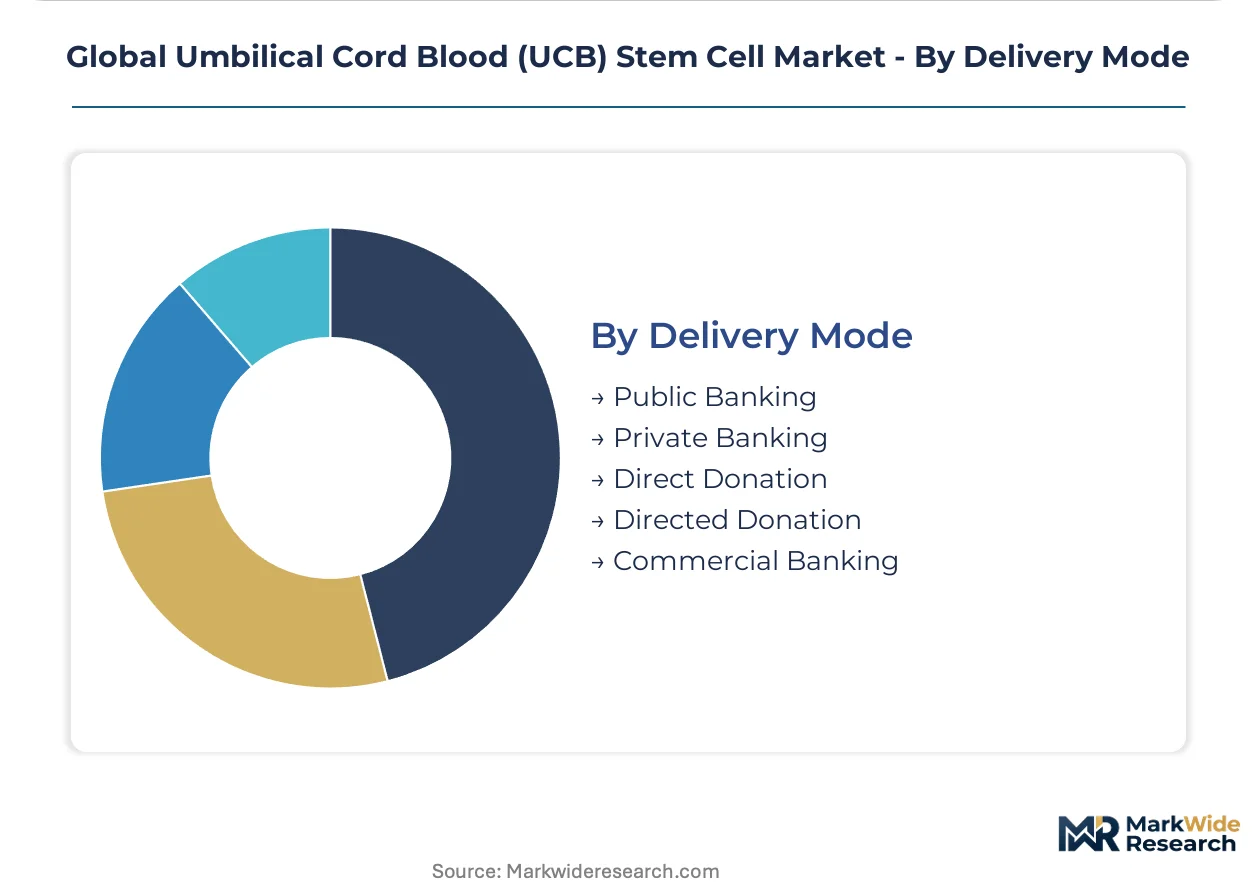
Delivery Mode:
Geographic concentration of liquid nitrogen infrastructure and regulatory harmonization shape which delivery modes achieve cross-border scalability.
- Private Banking:Family-funded collection and storage for autologous or directed allogeneic use. Direct-to-consumer channels in the United States face subscription erosion as genetic screening bundles displace standalone offerings.
- Public Banking:Donor-funded repositories serving unrelated recipient transplants with HLA-matched units. European networks benefit from EMA pathway harmonization reducing duplicate facility investments.
- Direct Donation:Uncompensated contributions to designated public inventories.
- Directed Donation:Family-arranged collections targeting known recipient needs.
- Commercial Banking:Hybrid models combining public inventory contribution with private storage options.
Private banking generates the highest per-unit revenue. Public banking shows the strongest volume expansion as transplant centers standardize unrelated donor protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in cryopreserved stem cells remain tightly constrained by liquid nitrogen logistics and divergent donor screening protocols, with surplus processing capacity in Southeast Asia seeking regulatory alignment with US and Japanese standards to unlock cross-border unit mobility.
United States
Academic medical centers in Boston and Houston sustain double-unit transplant protocols for adult oncology patients, anchoring collection volumes despite haploidentical bone marrow competition. FDA donor screening stringency extends processing timelines through expanded infectious disease testing requirements. California fertility clinic networks show the fastest subscription model erosion as genetic screening bundles displace standalone cord blood banking.
Japan
PMDA's conditional approval framework for regenerative medicine accelerates clinical trial duration for mesenchymal stem cell products, drawing Asian-market entry partnerships from regional banks. Tokyo and Osaka hospital clusters specialize in Crohn's perianal fistula applications beyond traditional hematologic indications. METI manufacturing standards redirect export-oriented suppliers toward compliant facility investments.
Germany
EMA centralized marketing authorization reduces duplicate facility investments for European operators seeking cross-border commercialization of expanded stem cell products. REACH chemical registration requirements for dimethyl sulfoxide cryoprotectant force documentation of supply chain provenance previously treated as commodity inputs. Frankfurt and Munich laboratories adopt automated cell selection platforms fastest, driven by EMA contamination risk guidelines.
India
Low private banking penetration rates and rising cesarean-section deliveries create first-mover advantages for operators establishing GMP-compliant processing facilities. CDSCO tightening of manufacturing standards for mesenchymal stem cell products redirects capital toward compliant infrastructure. Mumbai and Delhi clusters concentrate emerging banking infrastructure investment as operators target family-paid collection growth.
South Korea
MFDS manufacturing standards for mesenchymal stem cell products compress operational scaling timelines for mid-tier banks seeking regenerative medicine center partnerships. Seoul hospital networks drive expanded stem cell uptake as regulatory frameworks mature for non-hematologic indications. Busan-Ulsan industrial gas production clusters expose storage facilities to regional price volatility and supply concentration risks.
Global Umbilical Cord Blood (UCB) Stem Cell Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated banking networks with captive laboratory infrastructure and specialized operators dependent on third-party processing partnerships. Tiered competitive positioning separates balance-sheet-capable incumbents from mid-scale facilities confronting bioprocessing talent scarcity and legacy inventory reconciliation costs. Three archetypes dominate: vertically integrated Southeast Asian networks, US direct-to-consumer specialists, and European contract manufacturing organizations. Consolidation pressures favor M&A activity targeting GMP-compliant facilities in underserved markets, while technology licensing agreements for automated processing platforms reshape cost structures across smaller laboratories.
Within the integrated banking tier, Cordlife Group Limited anchors Southeast Asian operations through its laboratory network spanning Singapore, Hong Kong, and Malaysia. CBR Systems, Inc. occupies the direct-to-consumer archetype in the United States, where family-paid collection dominates revenue composition. Cryo-Cell International, Inc. represents the research-partnership specialization vector, extending positioning beyond standard hematologic applications through immunotherapy collaborations. These three operators exemplify how geographic footprint and service bundling strategies differentiate competitive positioning across regulatory jurisdictions.
| Leading Market Players |
|---|
| Cordlife Group Limited |
| CBR Systems, Inc. |
| Cryo-Cell International, Inc. |
| MEDIPOST |
| Americord Registry |
| LifeCell International |
| Global Cord Blood Corporation |
| ViaCord |
| StemCyte, Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in Southeast Asian liquid nitrogen infrastructure is driving dual sourcing mandates among cord blood banks, compressing supplier pricing power while elevating long-term contract premiums for guaranteed cold-chain continuity.
Pricing Analysis
Family-paid collectors anchor pricing stratification across premium, standard, and economy tiers differentiated by storage duration guarantees and infectious disease screening depth. Certification tier—FDA versus state-level laboratory licensure—commands measurable brand premiums in United States metropolitan markets. Cost compression in economy-tier subscriptions is intensifying because genetic screening bundles displace standalone cord blood offerings. Direct-to-consumer channels show least price sensitivity; hospital-affiliated programs face greatest enrollment elasticity.
Supply Chain Analysis
Upstream feedstock concentration in United States Gulf Coast and Northwestern European industrial gas production clusters exposes cryogenic storage networks to regional supply disruptions. Dimethyl sulfoxide cryoprotectant and vapor-phase liquid nitrogen dewars constitute critical input dependencies. Single-source vulnerability runs through consolidated industrial chemical distributors following REACH registration consolidation. Distribution runs through direct-to-consumer courier networks for collection kits and specialized cryogenic logistics providers for inter-facility unit transfers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat structure where decades-long storage contracts generate switching costs that entrench incumbent positions against new facility entrants.
For Market Incumbents: Insulate processing margins by securing captive liquid nitrogen supply through backward integration into regional industrial gas partnerships or long-term offtake agreements. Expand GMP-compliant laboratory footprint into Mumbai and Delhi clusters before CDSCO manufacturing standards tighten. Haploidentical bone marrow substitution and ex vivo expansion commoditization represent primary threat vectors; automated closed-system processing investment is the priority defensive lever. For New Entrants and Emerging Players: India's emerging banking infrastructure with low private penetration and rising cesarean-section deliveries represents the most penetrable entry point for GMP-compliant facility investment. Japan's conditional approval framework for mesenchymal stromal cell products offers secondary white-space through hospital partnership structures. Go-to-market execution should emphasize regenerative medicine center relationships over direct-to-consumer channel buildout given incumbent saturation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated cell selection platform deployment and multi-year liquid nitrogen infrastructure commitments. Acquisition targeting should prioritize Southeast Asian integrated banking networks with established laboratory footprints and family-paid collection revenue concentration. Regulatory harmonization progress between FDA and EMA serves as the critical signal to watch for cross-border unit mobility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Processing Platform Deployment | EMA contamination risk guidelines are accelerating European laboratory adoption of closed-system cell selection equipment. |
| GMP Facility Investment in India | CDSCO manufacturing standards are redirecting capital toward compliant Mumbai and Delhi processing infrastructure. |
| Regenerative Medicine Center Partnership | PMDA conditional approval framework is drawing Asian-market entry through Japanese hospital collaborations. |
| Liquid Nitrogen Supply Securement | Industrial gas production concentration is forcing long-term offtake contracting to mitigate regional disruption exposure. |
| Genetic Screening Bundle Integration | California and New York fertility clinic networks show bundled offerings capturing premium segment enrollments. |
Research Methodology
Operator-level perspectives from cord blood bank laboratory directors, cryogenic logistics specialists, regenerative medicine clinic administrators, and hospital transplant coordinators anchored the qualitative base. Secondary validation drew from FDA biologics license applications, EMA centralized marketing authorization submissions, ClinicalTrials.gov expanded stem cell protocol registrations, and CDSCO manufacturing compliance disclosures. Bottom-up unit volume modeling across processing technologies triangulated against top-down market value reconstructions.
Scenario-bracketing around ex vivo expansion technology maturation, regulatory harmonization velocity, and haploidentical substitution rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled encompassed product type, therapy area, end-user category, and delivery mode. CAGRs were derived from weighted average growth assumptions across these segments. Forecast inputs incorporated liquid nitrogen infrastructure investment cycles and automated processing platform adoption curves.
Practitioners should monitor PMDA and MFDS manufacturing standard revisions, REACH cryoprotectant registration enforcement, and genetic screening bundle penetration rates for early signals of forecast revision necessity. Quarterly review of regulatory harmonization progress between FDA and EMA, industrial gas pricing volatility indicators, and ex vivo expansion clinical trial readouts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Protein Degeneration Therapy Market