
 Hemophilia Therapeutics Market | 2026-2036
Hemophilia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Hemophilia Therapeutics Market Foresight
ISO 13485 certification for medical device-quality plasma fractionation is collapsing the supplier base for recombinant factor concentrates, forcing smaller plasma processors to exit or partner. CSL Behring leverages its vertically integrated plasma collection network across Australia and the United States to sustain bulk factor supply security. Novo Nordisk dominates the hemophilia A recombinant segment with extended half-life products that reduce infusion frequency. Takeda Pharmaceutical Company Limited anchors the Japanese market while competing aggressively in Europe and North America through its heritage Shire hemophilia portfolio.
Hemophilia therapeutics comprise clotting factor concentrates, antifibrinolytic agents, desmopressin, and gene therapy vectors designed to restore hemostatic function in patients with inherited coagulation deficiencies. Recombinant factor VIII and IX products are manufactured through mammalian cell culture in bioreactors exceeding 10,000-liter scale, followed by viral inactivation, chromatographic purification, and formulation into lyophilized powders for intravenous reconstitution. Factor Replacement Therapies occupy the dominant revenue position due to chronic lifetime administration, though Gene Therapy represents the fastest-expanding segment as one-time functional cures command premium pricing and reshape lifetime cost calculations. Intravenous delivery maintains structural dominance despite subcutaneous formulations gaining traction for prophylactic regimens in pediatric populations.
FDA's Breakthrough Therapy designation and EMA's PRIME scheme are accelerating market access for gene therapy candidates while tightening post-marketing safety surveillance requirements. The EU's MDR and FDA's BLA pathway impose stringent viral vector characterization standards that elevate manufacturing costs and extend validation timelines for new entrants. Stakeholders must monitor payer willingness to adopt outcomes-based reimbursement contracts for gene therapies, as these arrangements will determine whether curative modalities displace chronic factor replacement at scale.
Market Dynamics
Gene therapy adoption is compressing lifetime revenue models for chronic factor replacement, forcing manufacturers to restructure pricing around single-dose curative outcomes while hospital systems recalculate total cost of ownership across patient lifespans.
Growth Catalysts
- FDA Breakthrough Therapy designation:Accelerated approval pathways compress development timelines for novel gene therapy candidates. Hospital systems gain earlier access to functional cures.
- Extended half-life recombinant formulations:Bioconjugate technologies reduce prophylactic infusion frequency from thrice-weekly to biweekly or monthly regimens. Pediatric adherence rates improve measurably.
- Japan:Dedicated hemophilia treatment center expansion and national reimbursement reform for innovative therapies concentrate demand in Tokyo, Osaka, and Fukuoka medical corridors.
Market Restraints
- Plasma supply concentration:ISO 13485 certification requirements for medical device-quality fractionation collapse the viable supplier base. Australian and US plasma collection networks dominate bulk factor security.
- Viral vector manufacturing costs:EMA MDR and FDA BLA pathway standards for characterization and validation extend timelines for new gene therapy entrants. Manufacturing scale-up requires dedicated facilities.
- Gene therapy durability uncertainty:Long-term expression persistence remains unproven beyond five-year horizons. Payers hesitate to commit to premium single-dose reimbursement without outcome guarantees.
Strategic Opportunities
- Germany:Outpatient hemophilia care networks and statutory health insurance readiness for outcomes-based contracts create early-adopter positioning for curative modalities.
- Subcutaneous prophylactic delivery:Needle-free and patch-based administration technologies address pediatric venous access limitations. Home-based care models expand addressable patient populations.
- EU MDR orphan drug incentives:Reduced regulatory fees and protocol assistance for rare disease indications accelerate market entry timelines for novel factor concentrates.
Industry Challenges
- Gene therapy manufacturing workforce scarcity:Viral vector production, aseptic fill-finish operations, and quality control analytics require specialized training. Talent competition with oncology cell therapy intensifies.
- Legacy factor inventory obsolescence:Hospital formularies must manage transition from chronic replacement stocks to one-time gene therapy administration. Cold chain infrastructure faces stranded asset risk.
- Cross-border reimbursement harmonization:Divergent national health technology assessment methodologies for gene therapies fragment market access negotiations. Payer evidence requirements vary by jurisdiction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemophilia Therapeutics Market |
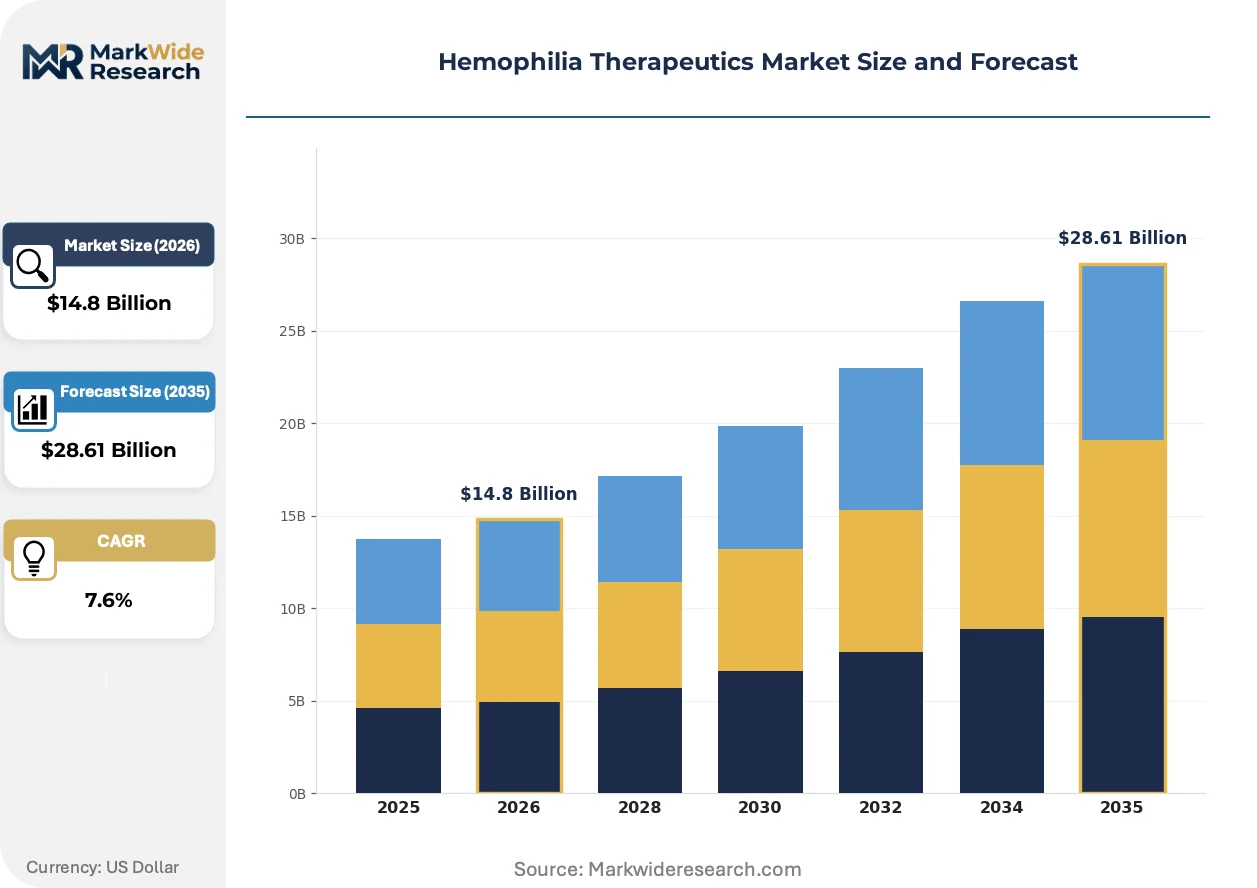
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Factor Replacement Therapies, Antifibrinolytics, Desmopressin, Gene Therapy Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation End User: Hospitals, Homecare, Outpatient Clinics, Specialty Pharmacies Indication: Hemophilia A, Hemophilia B, von Willebrand Disease, Other Coagulopathies |
| Companies Covered | Takeda Pharmaceutical Company Limited, CSL Behring, Pfizer, Novo Nordisk, Sanofi, Bayer AG, F. Hoffmann-La Roche Ltd, Octapharma AG, Spark Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemophilia Therapeutics Market Shifts & Advancements
Biomanufacturing scale and regulatory science are converging to enable commercial gene therapy at population scale, while delivery technologies and reimbursement models race to match clinical efficacy with economic sustainability.
Adeno-associated viral vector platforms are bifurcating the treatment landscape between liver-directed factor expression and emerging muscle-targeted delivery systems. Pediatric treatment centers in the United States and Germany are piloting both approaches for hemophilia A and B patients. The technology is bifurcating patient selection criteria by pre-existing neutralizing antibody status, creating parallel commercial pathways for seropositive and seronegative cohorts.
EMA's PRIME scheme and FDA's regenerative medicine advanced therapy designation are compressing pre-market development timelines while tightening post-authorization safety surveillance requirements. Manufacturers must build pharmacovigilance infrastructure capable of tracking patient outcomes across fifteen to twenty-year horizons. Gene therapy developers in Europe and North America are responding by embedding real-world evidence collection into treatment center protocols from first commercial doses.
Hospital procurement committees are consolidating factor concentrate purchasing through integrated delivery networks and specialty pharmacy carve-outs. Traditional wholesale distribution is losing share to direct manufacturer-to-treatment-center contracts with inventory management guarantees. This concentration is most visible in United States academic medical centers and German hemophilia comprehensive care centers, where annual contract values now exceed prior multi-year agreements.
Hemophilia Therapeutics Market Segmentation
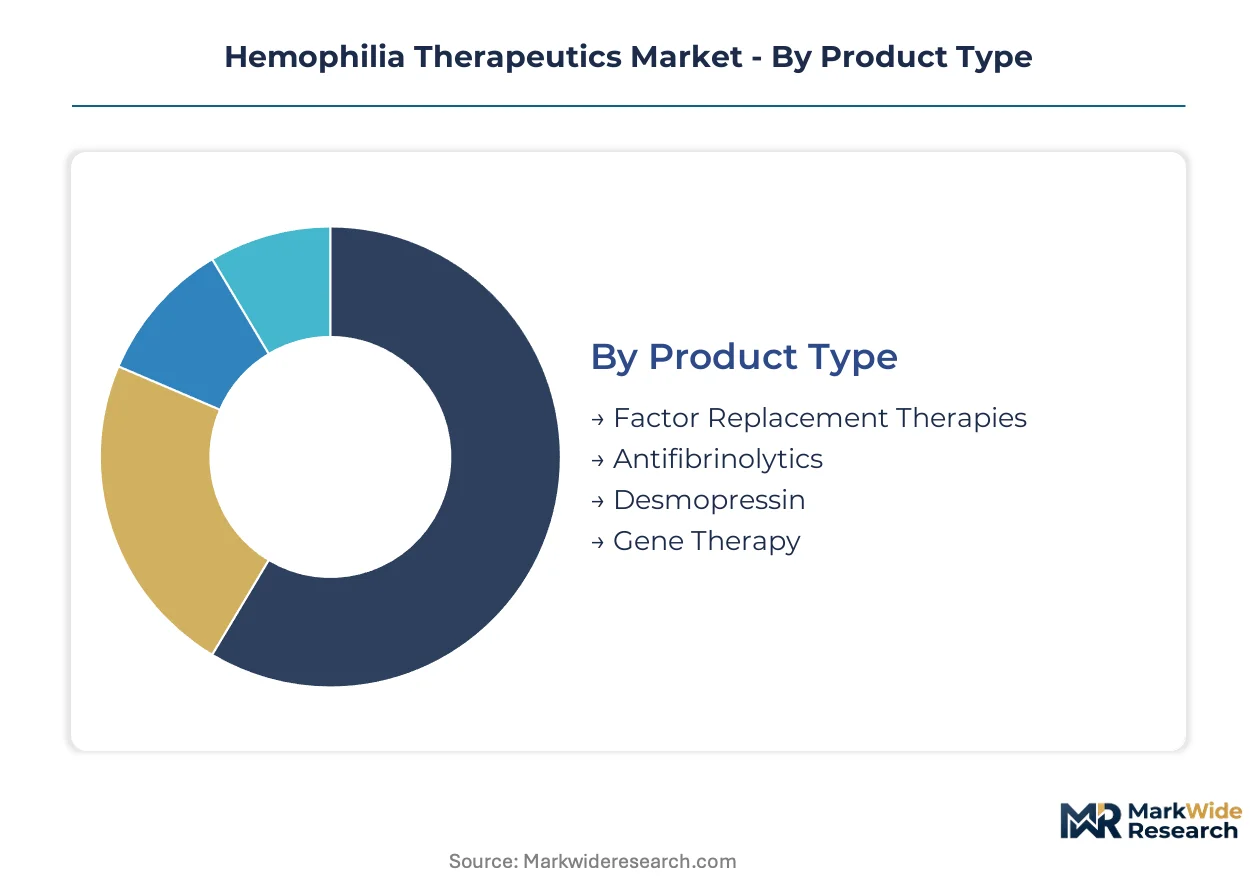
Segmentation in hemophilia therapeutics reveals distinct commercial pathways shaped by therapy modality, administration setting, and patient phenotype. Each dimension carries unique reimbursement dynamics and supply chain requirements that determine market access viability.
Product Type:
Factor Replacement Therapies dominate domestic consumption in the United States, Germany, and Japan, while Gene Therapy commands premium export pricing to concentrated treatment centers.
- Factor Replacement Therapies:Recombinant and plasma-derived factor VIII and IX concentrates manufactured through mammalian cell culture or plasma fractionation. Demand concentrates in United States academic medical centers and German comprehensive care networks driven by lifetime prophylactic administration requirements. Extended half-life formulations reduce infusion burden but maintain chronic revenue models.
- Gene Therapy:Adeno-associated viral vectors delivering functional factor VIII or IX genes for one-time functional cure. United States and German hospital systems lead adoption, though payer hesitation around durability guarantees constrains volume scaling.
- Antifibrinolytics:Tranexamic acid and aminocaproic acid adjuncts for mucosal bleeding control. Oral and intravenous formulations serve perioperative protocols across outpatient and surgical settings.
- Desmopressin:Synthetic vasopressin analog for mild hemophilia A and von Willebrand Disease. Intranasal and intravenous preparations address specific patient subpopulations with preserved endogenous factor stores.
Factor Replacement Therapies holds the largest share; momentum sits with Gene Therapy.
Delivery Mode:
Cost tier differentiation separates hospital-administered intravenous products from emerging home-based subcutaneous and oral alternatives targeting reduced healthcare utilization.
- Intravenous:Established route for factor concentrates requiring vascular access and infusion training. United States and Japanese treatment centers maintain infrastructure dominance, though pediatric venous access limitations drive interest in alternatives.
- Subcutaneous:Needle-free devices and patch technologies enable home-based prophylaxis without vascular access requirements. German and United States pediatric populations represent early adoption cohorts.
- Oral:Small molecule and peptide formulations in development for hemophilia A and B. Convenience positioning targets adolescent and adult patients with established venous access aversion.
- Inhalation:Investigational delivery for desmopressin and select hemostatic agents. Pulmonary absorption kinetics limit applicability to specific clinical scenarios.
Intravenous administration retains volume leadership; subcutaneous delivery is climbing the fastest among pediatric segments.
End User:
Customer type stratification separates institutional procurement through integrated delivery networks from direct-to-patient specialty pharmacy channels.
- Hospitals:Academic medical centers and hemophilia treatment centers in the United States, Germany, and Japan administer acute bleeding episodes and surgical prophylaxis. Gene therapy vector infusion requires specialized infrastructure.
- Homecare:Self-administered prophylaxis programs supported by nursing services and remote monitoring. United States and German reimbursement frameworks enable comprehensive home therapy coverage.
- Outpatient Clinics:Dedicated hemophilia centers in Tokyo, Osaka, and Fukuoka medical corridors concentrate Japanese demand. Periodic factor infusions and monitoring occur outside acute hospital settings.
- Specialty Pharmacies:Centralized distribution for factor concentrates with cold chain management and patient adherence programs. United States carved-out benefit design drives channel concentration.
Hospitals capture the greatest value per patient episode; homecare is expanding most quickly as prophylaxis protocols shift to self-administration.
Indication:
Maturity variation separates well-established hemophilia A and B therapeutic paradigms from emerging modalities for von Willebrand Disease and rare coagulopathies.
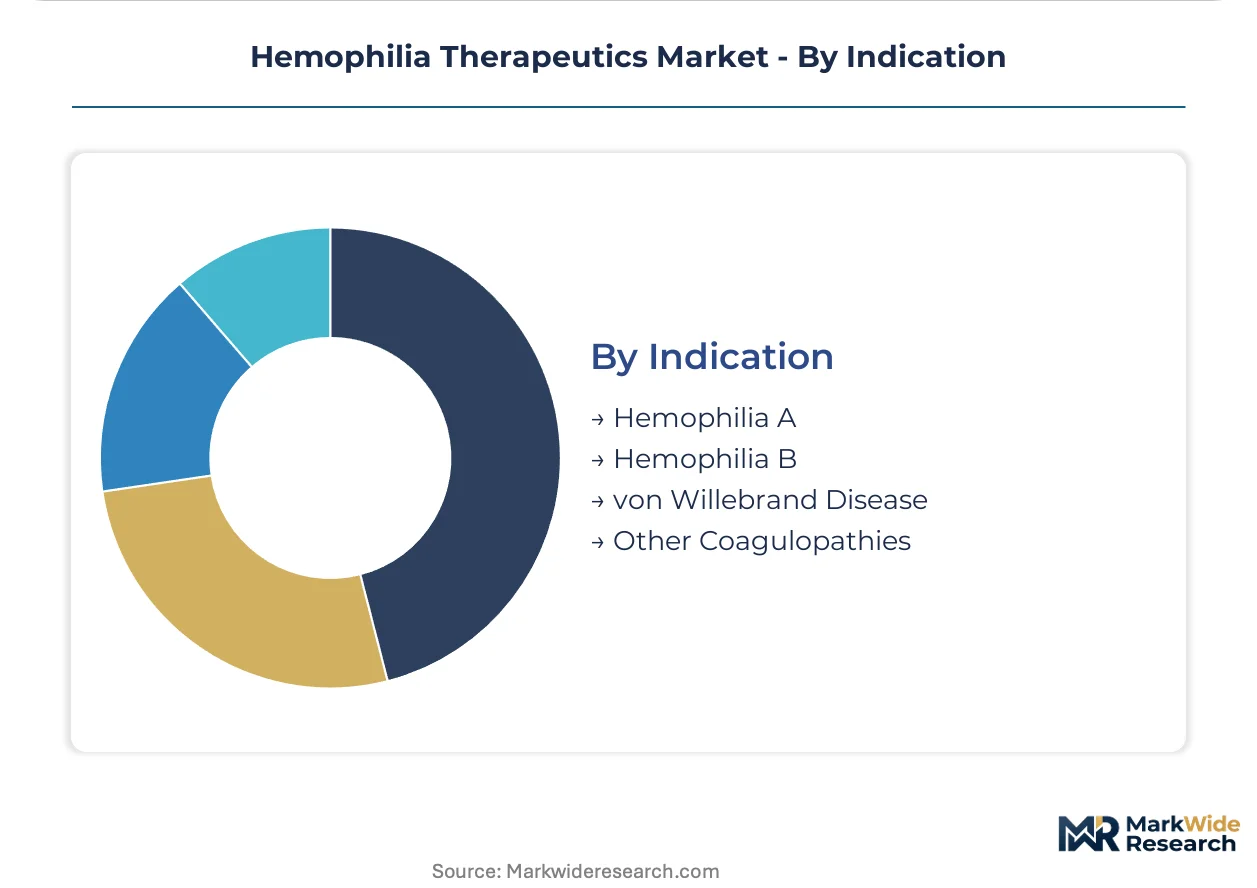
- Hemophilia A:Factor VIII deficiency representing the largest addressable population. Recombinant products, extended half-life formulations, and gene therapy candidates from multiple developers target this segment.
- Hemophilia B:Factor IX deficiency with smaller patient population but favorable gene therapy expression profiles. United States and European treatment centers prioritize curative approaches.
- von Willebrand Disease:Most common inherited bleeding disorder with heterogeneous severity. Plasma-derived concentrates and recombinant products address Type 3 and severe Type 2 variants.
- Other Coagulopathies:Factor VII, X, and XIII deficiencies with ultra-rare prevalence. Orphan drug incentives support development despite limited commercial scale.
Hemophilia A generates the highest absolute revenue; hemophilia B shows the steepest expansion trajectory for gene therapy uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Breakthrough Therapy designation and EMA PRIME scheme accelerate gene therapy access in concentrated treatment corridors. Hospital systems in the United States, Germany, and Japan recalculate total cost of ownership as curative modalities reshape chronic replacement economics. National reimbursement reforms in each market determine whether single-dose premiums displace lifetime factor administration.
United States
Academic medical centers in Boston, Philadelphia, and San Francisco anchor gene therapy adoption for hemophilia A and B. FDA BLA pathway requirements for viral vector characterization elevate manufacturing costs for new entrants. Integrated delivery networks in the Midwest and Southeast consolidate factor concentrate purchasing through direct manufacturer contracts with inventory guarantees.
Germany
Statutory health insurance readiness for outcomes-based reimbursement contracts positions Bavaria and North Rhine-Westphalia as early curative therapy adopters. EU MDR orphan drug incentives reduce regulatory fees for novel factor concentrates. Hemophilia comprehensive care centers in Munich, Cologne, and Hamburg concentrate outpatient demand through dedicated treatment networks.
Japan
METI and PMDA coordinate national reimbursement reform for innovative therapies across Tokyo, Osaka, and Fukuoka medical corridors. Dedicated hemophilia treatment center expansion concentrates demand in Kanto and Kansai regions. Extended half-life recombinant products gain priority formulary placement as infusion frequency reduction aligns with aging patient demographics.
United Kingdom
NICE technology appraisals determine gene therapy access through England's specialized commissioning framework. London and Manchester treatment centers pilot real-world evidence collection for fifteen-year outcome tracking. NHS England's budget impact thresholds create negotiation leverage against premium single-dose pricing.
Switzerland
Swissmedic accelerated assessment pathways compress timelines for gene therapy market authorization. Basel and Zurich hospital networks leverage proximity to European manufacturing sites for vector supply security. Outpatient hemophilia care models in German-speaking cantons emphasize home-based prophylaxis with remote monitoring infrastructure.
Hemophilia Therapeutics Market Competitive Landscape
Player mix skews toward vertically integrated plasma processors and recombinant specialists with mammalian cell culture scale. Market structure concentrates around three strategic archetypes: plasma fractionation networks with captive collection infrastructure, recombinant biologics manufacturers with extended half-life platforms, and gene therapy developers with AAV vector capabilities. Dominant competitive moves include backward integration into plasma collection networks and strategic partnerships for viral vector manufacturing capacity.
Within the plasma-derived tier, CSL Behring and Octapharma AG occupy positions anchored by Australian and European collection networks. Among recombinant specialists, Novo Nordisk and Sanofi exemplify the extended half-life formulation archetype. Takeda Pharmaceutical Company Limited sits within the heritage portfolio category following its Shire acquisition, competing across recombinant and plasma-derived segments. Pfizer and Bayer AG represent diversified pharmaceutical conglomerates with hemophilia assets embedded within broader rare disease franchises. Spark Therapeutics anchors the gene therapy developer category with liver-directed AAV platforms.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| CSL Behring |
| Pfizer |
| Novo Nordisk |
| Sanofi |
| Bayer AG |
| F. Hoffmann-La Roche Ltd |
| Octapharma AG |
| Spark Therapeutics |
| Others |
Supply & Pricing Matrix
Bioreactor scale economics exceeding 10,000-liter capacity tether pricing power to plasma collection network density and viral vector manufacturing yields, concentrating margin leverage among operators with captive fractionation infrastructure.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-compliant medical device-grade concentrates and standard pharmaceutical-tier products. Gene therapy commands single-dose premiums against chronic replacement models, though payer hesitation around durability guarantees compresses realized pricing. Cost compression in plasma-derived segments intensifies as Australian and US collection networks consolidate. Pediatric homecare providers exhibit highest price sensitivity; academic medical centers with dedicated hemophilia treatment centers demonstrate lowest.
Supply Chain Analysis
Viral vector manufacturing capacity in the United States and Germany constrains gene therapy commercialization timelines, while plasma fractionation in Australia and Austria secures bulk factor VIII and IX supply. Mammalian cell culture media, chromatography resins, and aseptic fill-finish capacity constitute critical input dependencies. Single-source vulnerability in AAV vector production elevates stranded inventory risk for treatment centers. Distribution runs through direct manufacturer-to-hospital contracts with cold chain guarantees, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from patient adherence programs, remote monitoring infrastructure, and outcomes-based contracting layers expands faster than factor concentrate hardware sales, creating recurring revenue pools for platform operators.
For Market Incumbents: Shield factor replacement franchises by embedding real-world evidence collection into treatment protocols before gene therapy durability data matures. Secure backward integration into plasma collection networks to maintain bulk supply security against ISO 13485 certification barriers. Prioritize certification investment in EU MDR orphan drug pathways to accelerate novel concentrate timelines. For New Entrants and Emerging Players: Anchor in subcutaneous delivery device development for pediatric populations with venous access limitations, where reimbursement frameworks in Germany and the United States enable premium positioning. Target white-space in muscle-directed AAV platforms for seropositive patients excluded from liver-directed gene therapy. Pursue hospital system partnership go-to-market models with inventory management guarantees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors viral vector manufacturing specialists with demonstrated GMP scale-up capabilities over early-stage discovery platforms. Long-term viability hinges on fifteen-year pharmacovigilance infrastructure and payer contracting relationships. Monitor gene therapy durability readouts beyond five-year horizons as the critical inflection signal for chronic replacement displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Outcomes-Based Reimbursement Contracting | Germany's statutory health insurance frameworks pioneer curative therapy payment models. |
| Viral Vector Manufacturing Scale-Up | EMA MDR and FDA BLA standards elevate barriers for new gene therapy entrants. |
| Extended Half-Life Formulation Development | Bioconjugate technologies reduce infusion burden and improve pediatric adherence. |
| Plasma Collection Network Expansion | Australian and US sourcing dominance secures bulk factor concentrate supply security. |
| Subcutaneous Delivery Device Launch | Needle-free and patch technologies address home-based prophylaxis demand. |
Research Methodology
Initial hypotheses were tested against primary input from hemophilia treatment center directors, hospital procurement managers, regulatory affairs leads at plasma processors, payer access specialists, and gene therapy development executives and refined through secondary validation against FDA BLA filings, EMA PRIME scheme documentation, ClinicalTrials.gov records, and national reimbursement databases. Bottom-up patient population sizing triangulated with top-down revenue aggregation across the analysis window.
Variance decomposition separated volume drivers from price-mix effects across therapy modality, patient phenotype, administration setting, and regional regulatory cluster dimensions. CAGRs derived from logistic diffusion modeling of gene therapy adoption curves against chronic replacement persistence rates, incorporating viral vector manufacturing capacity constraints and payer contracting velocity assumptions.
Material uncertainties — gene therapy durability beyond five-year horizons, cross-border reimbursement harmonization failures, and plasma supply concentration disruptions — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as real-world evidence accumulation and regulatory science evolution reshape curative modality access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market