
 India Insulin Drug and Delivery Device Market | 2026-2036
India Insulin Drug and Delivery Device Market Size, Share, and Industry Trends Forecast 2026-2036
India Insulin Drug and Delivery Device Market Insights
Subscription-based insulin pump maintenance and cloud-connected dose monitoring is hardening into a core revenue layer beyond device sales. Novo Nordisk leverages its endocrinology-focused distribution network to sustain premium positioning in pen-based delivery systems across metro hospitals. Biocon anchors its competitive stance through in-house biosimilar insulin production, while Sanofi competes via established brand strength in the retail pharmacy channel.
India Insulin Drug and Delivery Device comprises recombinant human insulin, insulin analogs, and associated delivery mechanisms engineered for precise glycemic control through parenteral or inhalation routes, with formulations requiring cold-chain stability between 2°C and 8°C. Insulin pens dominate volume due to patient convenience and reduced dosing errors, while insulin pumps capture premium margin pools among Type 1 diabetes patients in urban centers. The home care end-user segment is expanding fastest as self-monitoring blood glucose devices integrate with smartphone-enabled dose tracking, though hospitals retain the largest absolute prescription throughput for initiating intensive insulin therapy.
CDSCO regulates insulin as a biological drug and medical device under separate approval tracks, while the PLI scheme incentivizes domestic manufacturing of active pharmaceutical ingredients and finished formulations. BIS standards for syringe and needle specifications shape product entry requirements, and FSSAI oversight of glucose monitoring strips creates additional compliance layers for bundled offerings. Stakeholders must monitor how state-level tendering for public hospital procurement and evolving reimbursement under Ayushman Bharat reshape channel economics and pricing power across delivery modes.
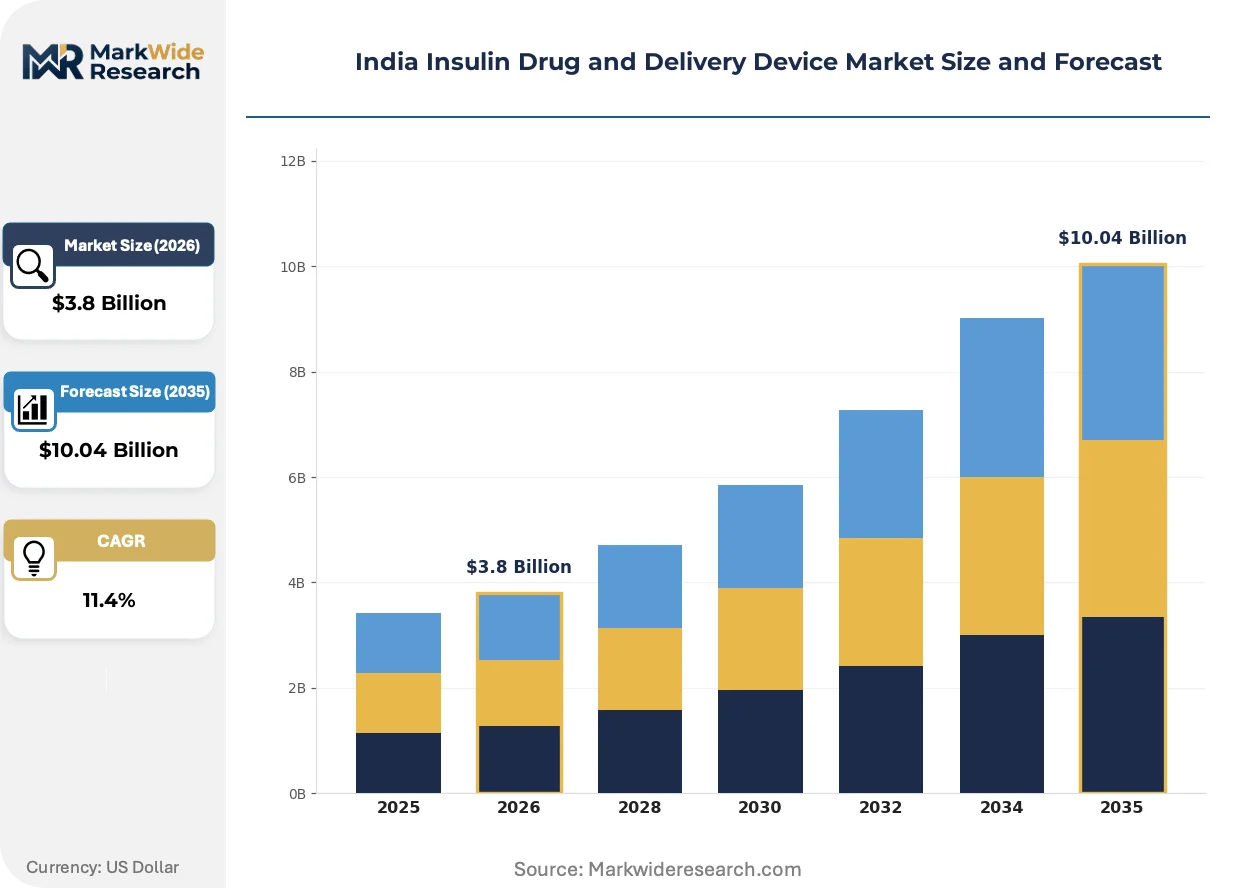
Market Dynamics
CDSCO's parallel track approvals for insulin drugs and delivery devices are compressing commercialization timelines, while Maharashtra's hospital procurement clusters concentrate demand leverage among institutional buyers.
Growth Catalysts
- Ayushman Bharat expansion:The national health insurance scheme extends reimbursement coverage for insulin therapy to tier-2 and tier-3 cities, expanding addressable patient pools beyond metro centers.
- PLI scheme for domestic API manufacturing:Production-linked incentives for recombinant human insulin active pharmaceutical ingredients reduce import dependency and strengthen cold-chain security.
- Smartphone-enabled dose tracking:Bluetooth-integrated glucose monitors pair with pen devices, creating adherence data streams that physicians leverage for therapy optimization.
Market Restraints
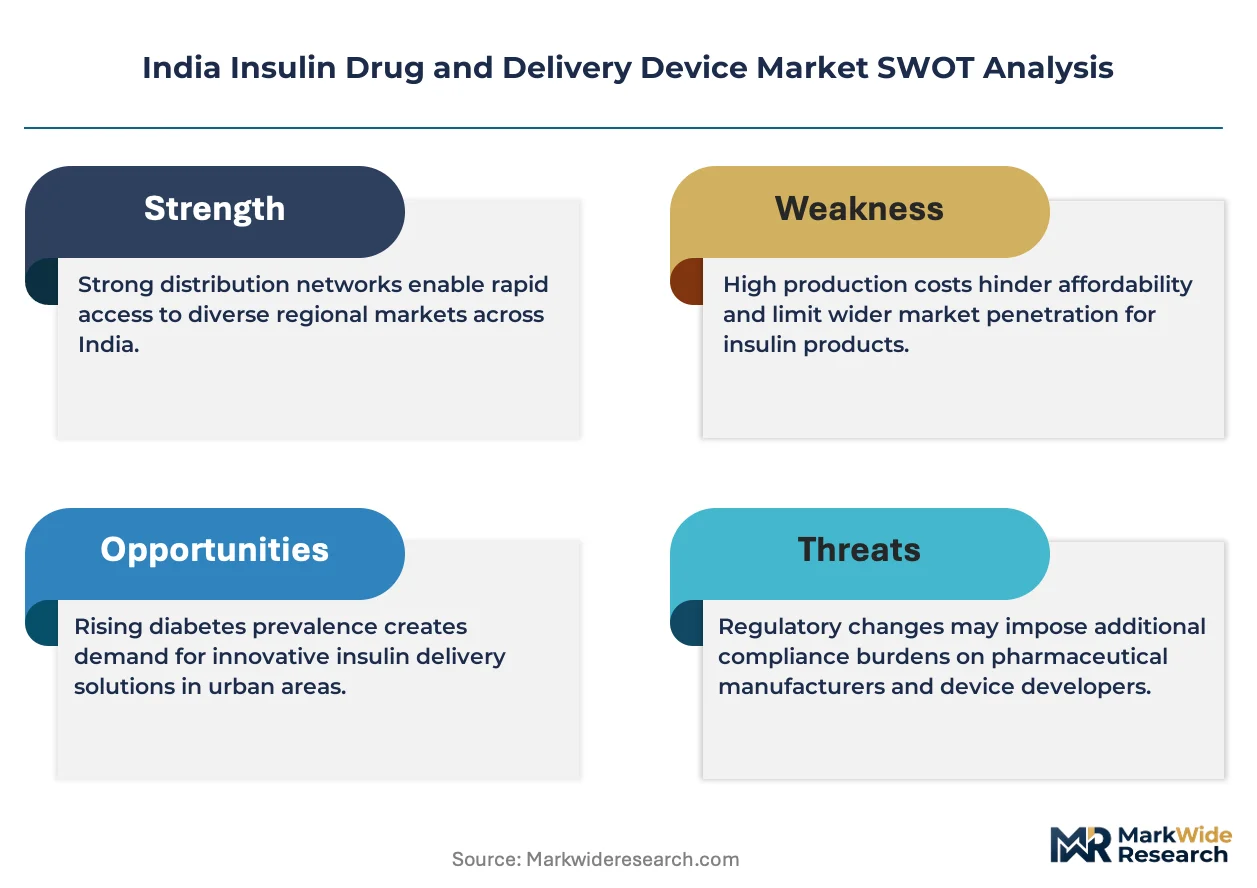
- Cold-chain infrastructure gaps:Temperature excursions during last-mile distribution in rural Karnataka and Tamil Nadu degrade insulin potency, forcing write-offs and supply uncertainty.
- Import concentration for analog formulations:Overseas sourcing of rapid-acting and long-acting insulin analogs exposes margins to currency volatility and shipping disruptions.
- BIS needle specification compliance:Domestic manufacturers face retooling costs to meet Bureau of Indian Standards dimensional tolerances for pen needle compatibility.
Strategic Opportunities
- Tier-3 city home care penetration:Underdeveloped districts in Madhya Pradesh and Uttar Pradesh present whitespace for self-administration device adoption as diagnostic reach expands.
- Subscription-based pump maintenance:Recurring revenue models for cloud-connected insulin pump calibration and consumable replenishment decouple service income from device sales cycles.
- FSSAI glucose strip bundling:Regulatory clarity on combined device-strip offerings enables integrated product portfolios that capture recurring test-strip demand.
Industry Challenges
- Endocrinologist workforce scarcity:Limited specialist availability in tier-2 cities delays intensive insulin therapy initiation and complicates patient education for pump adoption.
- CDSCO device-drug dual classification:Separate approval tracks for insulin pens as biological products versus mechanical devices create documentation redundancy and timeline misalignment.
- Legacy syringe user transition friction:Long-tenured vial-and-syringe patients in public hospital settings resist pen device conversion despite dosing accuracy benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Insulin Drug and Delivery Device Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Syringes, Insulin Pumps, Insulin Inhalers Delivery Mode: Subcutaneous, Intravenous, Inhalation, Oral End User: Hospitals, Clinics, Home Care, Retail Pharmacies Therapy Area: Diabetes Type 1, Diabetes Type 2, Gestational Diabetes, Pre-diabetes |
| Companies Covered | Medtronic, Biocon, Novo Nordisk, Boehringer Ingelheim, BD (Becton Dickinson), Sanofi, Roche, Wockhardt, Eli Lilly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Insulin Drug and Delivery Device Market Trends and Innovations
Device connectivity and domestic manufacturing incentives are restructuring how insulin reaches patients, with implications for pricing power and channel control across the value chain.
Continuous glucose monitoring systems paired with algorithm-driven insulin dosing are unifying glycemic data streams with automated delivery adjustments. Type 1 diabetes patients in Bengaluru and Chennai metro hospitals adopt these closed-loop configurations fastest. The technology is unifying previously separate device categories—pumps, sensors, and pens—into integrated ecosystems that lock patients into single-vendor platforms.
CDSCO's 2023 guidance on software-as-a-medical-device classification for dose-tracking applications imposes pre-market validation requirements on smartphone-connected pen systems. Domestic manufacturers must demonstrate cybersecurity resilience and clinical equivalence to predicate devices. Pen device vendors with cloud platforms face the steepest compliance burden, while standalone mechanical pen suppliers gain temporary competitive relief.
Hospital procurement committees in Maharashtra are consolidating insulin purchasing through centralized tendering, displacing fragmented pharmacy-level ordering. This concentrates volume leverage among three to four institutional buyers in Mumbai and Pune corridors. The shift is most visible in public sector hospitals, where annual framework agreements now specify device compatibility requirements that exclude non-conforming pen formats.
India Insulin Drug and Delivery Device Market Segmentation
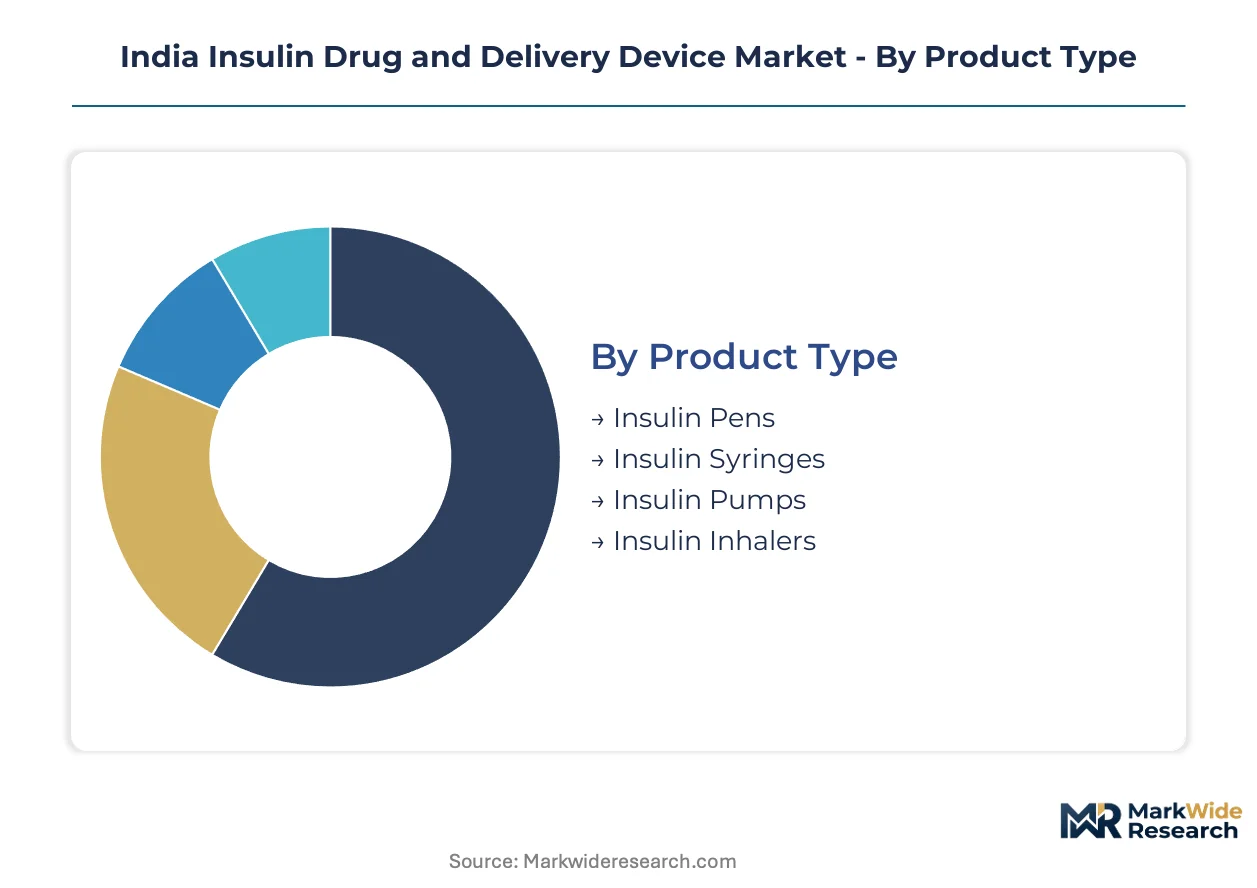
Segmentation in the India Insulin Drug and Delivery Device Market reveals how regulatory pathways, patient acuity, and care settings fragment commercial opportunities. Each dimension carries distinct approval burdens, pricing power, and channel access requirements that shape go-to-market strategy.
Product Type:
CDSCO classifies insulin pens and pumps as combination products requiring dual drug-device approvals, while syringes fall under simpler mechanical device tracks. BIS needle specifications apply differentially across these categories.
- Insulin Pens:Reusable and disposable pen systems dominate prescription volumes in Maharashtra and Karnataka metro hospitals. CDSCO's biological product classification for the insulin cartridge adds 12-18 months to approval timelines versus mechanical pen bodies alone.
- Insulin Pumps:Continuous subcutaneous infusion devices capture premium margins among Type 1 diabetes patients in Bengaluru and Chennai. CDSCO's 2023 software-as-a-medical-device guidance imposes cybersecurity validation on cloud-connected pump platforms, steepening compliance costs for vendors with dose-tracking applications.
- Insulin Syringes:Vial-and-syringe formats retain volume in public hospital procurement tenders across Tamil Nadu.
- Insulin Inhalers:Pulmonary delivery devices face FSSAI overlap for excipient safety in inhaled formulations.
Insulin pens sit at the top of the volume ranking, with insulin pumps climbing the fastest.
Delivery Mode:
Route selection determines cold-chain intensity, patient training requirements, and reimbursement eligibility under Ayushman Bharat.
- Subcutaneous:Abdominal, thigh, and arm injection sites support self-administration across home care settings in tier-2 cities. Pen devices and pumps both leverage this route, with patient education programs concentrated in Kerala and Gujarat where diagnostic penetration exceeds national averages.
- Intravenous:Hospital-controlled infusion for diabetic ketoacidosis and perioperative glycemic management concentrates in tertiary care centers across Delhi NCR and Mumbai. This route requires trained nursing staff and continuous monitoring infrastructure absent in retail pharmacy channels.
- Inhalation:Pulmonary insulin delivery remains niche due to FSSAI respiratory excipient scrutiny and limited pulmonologist availability for patient selection.
- Oral:Gastrointestinal enzyme degradation has blocked commercial viability, with no approved products in the India market despite ongoing trials.
Subcutaneous delivery commands absolute volume leadership, while pump-augmented subcutaneous infusion gains share fastest among Type 1 cohorts.
End User:
Channel economics diverge sharply between institutional procurement and retail pharmacy flows, with home care emerging as the margin-expansion frontier.
- Hospitals:Tertiary care centers in Maharashtra, Karnataka, and Tamil Nadu generate the largest absolute prescription throughput for intensive insulin initiation. Centralized tendering in Mumbai and Pune corridors now specifies device compatibility requirements that exclude non-conforming pen formats.
- Home Care:Self-administration device adoption accelerates fastest in tier-2 and tier-3 cities as smartphone-enabled glucose monitors pair with pen systems. Madhya Pradesh and Uttar Pradesh districts present whitespace where diagnostic reach is expanding ahead of specialist availability.
- Clinics:Endocrinology-focused outpatient facilities in Bengaluru and Chennai mediate pump adoption for affluent Type 1 patients.
- Retail Pharmacies:Community pharmacy channels dominate refill prescriptions for stable Type 2 patients on basal insulin analogs.
Hospitals retain the volume crown, though home care demonstrates the steepest expansion trajectory as self-monitoring technology diffuses.
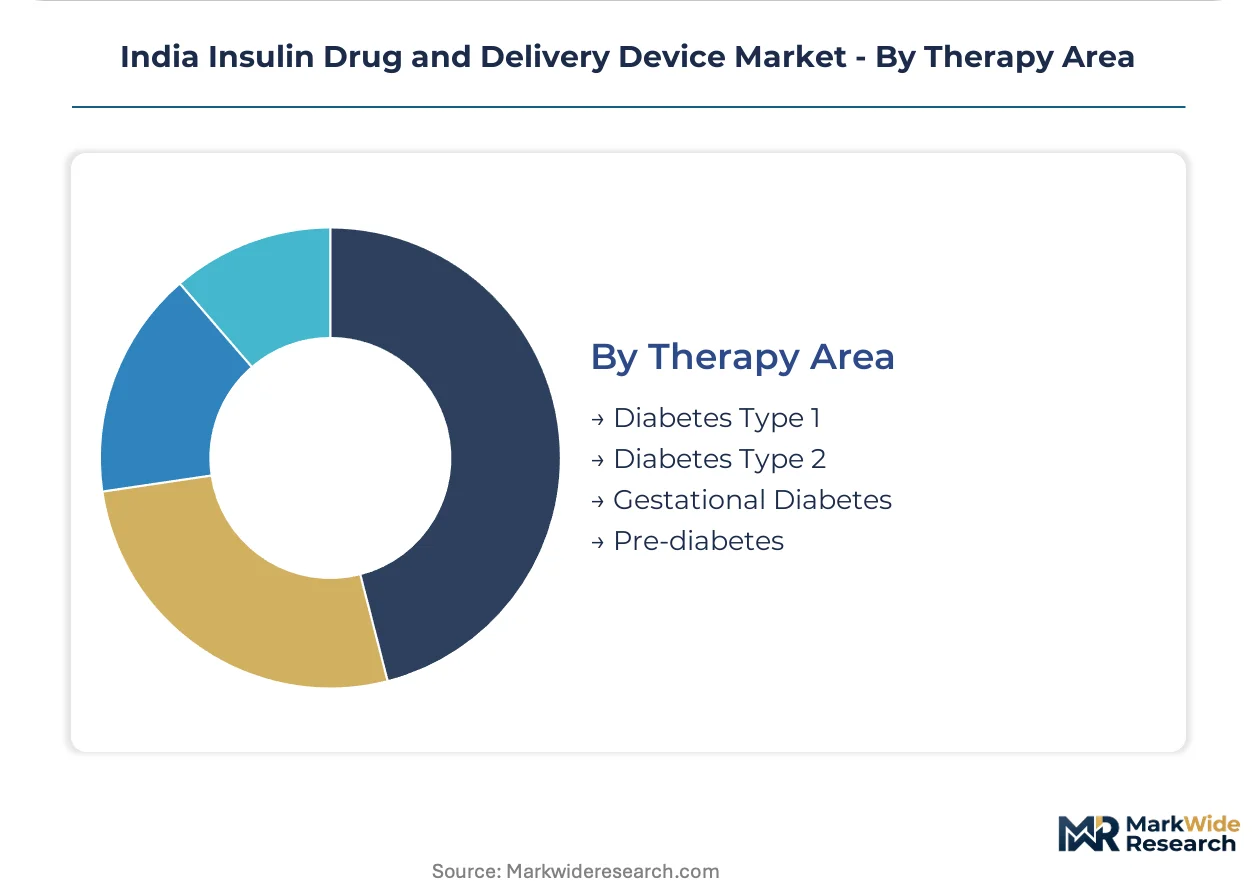
Therapy Area:
Disease severity and progression stage determine device complexity, with Type 1 patients requiring pump-eligible intensive regimens.
- Diabetes Type 1:Absolute insulin deficiency mandates intensive basal-bolus therapy or pump-based automated delivery. Pediatric and young adult patients in urban Chennai and Bengaluru metro hospitals adopt closed-loop pump-sensor configurations fastest, locking into single-vendor ecosystems.
- Diabetes Type 2:Progressive beta-cell failure creates expanding insulin demand among India's 77 million diagnosed patients. Pen-based basal insulin dominates initial intensification, with analog uptake concentrated in private hospital channels where reimbursement coverage is strongest.
- Gestational Diabetes:Pregnancy-specific glycemic targets require rapid-acting insulin with meal-time flexibility, favoring pen devices over pumps due to cost sensitivity and limited treatment duration.
- Pre-diabetes:Lifestyle intervention focus keeps pharmacotherapy penetration minimal, with insulin initiation rare outside progression to overt diabetes.
Type 2 diabetes anchors volume rankings given population scale, while Type 1 shows the fastest device premiumization as closed-loop technology penetrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing incentives under India's PLI scheme are compressing cost-of-compliance gaps between imported and locally produced insulin APIs, redirecting capital toward Gujarat and Maharashtra production clusters while cold-chain infrastructure investments lag in interior states.
Maharashtra
Mumbai and Pune hospital procurement corridors generate the highest insulin prescription volumes nationally, with centralized tendering frameworks now mandating device compatibility specifications. CDSCO's parallel drug-device approval tracks accelerate commercialization for manufacturers with established Maharashtra distribution networks. The Mumbai metropolitan cluster concentrates tertiary care capacity and specialist endocrinologist availability.
Karnataka
Bengaluru's medical device innovation ecosystem anchors adoption of closed-loop pump-sensor configurations among Type 1 diabetes patients. The state's diagnostic penetration exceeds national averages, creating concentrated demand for smartphone-integrated glucose monitoring systems. CDSCO software-as-a-medical-device compliance requirements impose cybersecurity validation burdens on cloud-connected platform vendors headquartered in the city.
Tamil Nadu
Chennai's hospital density supports intensive insulin therapy initiation, though cold-chain gaps in rural districts degrade last-mile distribution quality. The state's public sector procurement committees specify BIS-compliant needle specifications in annual framework agreements. Madurai and Coimbatore secondary cities present expanding home care device adoption as diagnostic reach extends beyond metro centers.
Gujarat
Ahmedabad and Vadodara pharmaceutical manufacturing clusters leverage PLI scheme incentives for recombinant human insulin API production. The state's established chemical synthesis infrastructure supports backward integration into fermentation-based biological manufacturing. Domestic cold-chain logistics providers are consolidating warehouse capacity around these production hubs to reduce temperature excursion risks.
Delhi-NCR
The national capital region concentrates regulatory expertise and CDSCO headquarters proximity, accelerating approval navigation for device-drug combination products. Gurugram and Noida hospital chains serve as early adoption centers for subscription-based pump maintenance models. Ayushman Bharat reimbursement administration centers in Delhi process claims for tier-2 and tier-3 city patient pools across northern states.
India Insulin Drug and Delivery Device Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational pharmaceutical incumbents dominating analog formulations while domestic API producers capture recombinant human insulin volume. The market structure concentrates around three to four institutional procurement decision-makers in Maharashtra and Karnataka corridors. Two strategic archetypes predominate: integrated biopharmaceutical manufacturers with captive insulin production and medical device specialists with distribution-led pen system penetration. Competitive moves center on PLI-linked capacity expansion in Gujarat and subscription-based service model development for cloud-connected delivery platforms.
Among integrated biopharmaceutical manufacturers, Biocon exemplifies domestic API production capability anchored in Bangalore, while Novo Nordisk occupies a position representing endocrinology-focused distribution depth. Sanofi sits within the tier of established brand strength in retail pharmacy channels. These three entities represent divergent strategic postures: captive manufacturing, specialist therapeutic focus, and mass-market brand equity respectively.
| Leading Market Players |
|---|
| Medtronic |
| Biocon |
| Novo Nordisk |
| Boehringer Ingelheim |
| BD (Becton Dickinson) |
| Sanofi |
| Roche |
| Wockhardt |
| Eli Lilly |
| Others |
Pricing and Supply Chain Analysis
Backward integration into recombinant human insulin API production under India's PLI scheme anchors both supply security and pricing power for domestic manufacturers, compressing cost gaps against imported analog formulations while cold-chain infrastructure investments lag in interior states.
Pricing Analysis
Distributor margin layers in Maharashtra and Karnataka hospital procurement corridors concentrate pricing power among three to four institutional buyers, with centralized tendering frameworks mandating device compatibility specifications that exclude non-conforming pen formats. Three-tier pricing structure across premium insulin pumps, standard pen devices, and economy vial-syringe formats separates Type 1 diabetes patients in Bengaluru metro hospitals from stable Type 2 patients in retail pharmacy channels. Cost compression in the analog insulin tier is intensifying because currency volatility on overseas sourcing exposes margins to shipping disruptions and import duty fluctuations. Public sector procurement committees exhibit highest price sensitivity, while affluent Type 1 cohorts in private hospital settings demonstrate lowest elasticity for closed-loop pump-sensor configurations.
Supply Chain Analysis
CDSCO's dual drug-device classification for insulin pens and BIS needle specification compliance create certification gating that domestic manufacturers must clear before Maharashtra hospital procurement committees. API production concentrates in Gujarat and Karnataka fermentation clusters, while finished formulation fill-finish operations distribute across Maharashtra and Tamil Nadu pharmaceutical hubs. Cold-chain logistics draw from specialized 2-8°C warehouse networks anchored around Ahmedabad and Mumbai, with last-mile distribution resting on fragmented ambient-temperature transport in rural Madhya Pradesh and Uttar Pradesh. Single-source vulnerability in rapid-acting insulin analog imports from European manufacturing sites exposes supply continuity to geopolitical disruption. Distribution runs through three-channel architecture: direct hospital tender fulfillment, retail pharmacy wholesale networks, and emerging direct-to-patient subscription models for pump maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on PLI-linked API cost-down capture and the shift toward recurring-revenue pump maintenance subscriptions that decouple service income from device sales cycles.
For Market Incumbents: Extend endocrinology-focused distribution networks into tier-2 cities ahead of diagnostic penetration expansion, while deepening backward integration into pen needle manufacturing to deflect BIS compliance cost pressure from third-party suppliers. Biocon and Novo Nordisk should consolidate hospital procurement committee relationships through framework agreement renewals that embed device compatibility specifications, locking out non-conforming pen formats from Maharashtra and Karnataka tenders.
For New Entrants and Emerging Players: Diagnostic equipment distributors in Madhya Pradesh and Uttar Pradesh districts present the most penetrable channel for home care device adoption, where specialist availability lags behind glucose monitoring penetration. Tier-3 city pharmacy chains offer whitespace for smartphone-integrated pen systems that pair with cloud-connected dose tracking, bypassing hospital procurement concentration. A subscription-based pump maintenance go-to-market model captures recurring revenue without requiring upfront device margin competition against established pump vendors.
For Investors and Strategic Acquirers: Roll-up economics work for regional cold-chain logistics providers because PLI scheme API production growth in Gujarat and Maharashtra demands specialized 2-8°C warehouse consolidation that fragmented ambient-temperature players cannot replicate. Target acquisition archetypes include domestic pen needle manufacturers facing BIS retooling costs and diagnostic equipment distributors with established tier-2 city relationships. The signal to watch is CDSCO guidance expansion on software-as-a-medical-device classification, which would steepen compliance burdens on cloud-connected platform vendors and create distressed acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| PLI-Linked API Manufacturing Scale-Up | Domestic recombinant human insulin production in Gujarat fermentation clusters reduces import dependency and currency exposure. |
| CDSCO Dual Classification Compliance Investment | Parallel drug-device approval track navigation accelerates commercialization timelines for pen system vendors with regulatory expertise. |
| Hospital System Partnership Framework | Maharashtra centralized tendering relationships concentrate volume leverage among institutional buyers specifying device compatibility. |
| Software Companion Development | Bluetooth-integrated glucose monitors paired with pen devices create adherence data streams physicians leverage for therapy optimization. |
| Reimbursement Strategy Under Ayushman Bharat | Tier-2 and tier-3 city coverage expansion extends addressable patient pools beyond metro center concentration. |
Research Methodology
Multiple input streams — primary interviews with CDSCO regulatory affairs leads, hospital procurement managers, and endocrinology-focused distribution executives, alongside secondary validation through CDSCO approval databases, Ayushman Bharat reimbursement filings, and PLI scheme beneficiary disclosures — were reconciled through bottom-up prescription volume modeling and top-down market sizing triangulation.
Historical insulin prescription growth patterns across Maharashtra, Karnataka, and Tamil Nadu were cross-referenced against panel input from formulary directors and GPO contracts managers to anchor trajectory assumptions across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end user channel, and therapy area severity, with CAGRs derived from fitted growth curves calibrated to diagnostic penetration expansion and smartphone-enabled glucose monitoring adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CDSCO software-as-a-medical-device guidance evolution and PLI scheme extension decisions. A model refresh is warranted upon material change in Ayushman Bharat reimbursement tier definitions or cold-chain infrastructure investment acceleration in rural Karnataka and Tamil Nadu districts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Prokaryotic Recombinant Protein Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market