
 Gene Delivery Technologies Market | 2026-2036
Gene Delivery Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Delivery Technologies Market Intelligence
The distinction between research-grade and clinical-grade viral vectors is collapsing as manufacturing standards tighten for therapeutic applications. Thermo Fisher Scientific Inc. leverages its extensive portfolio of reagents and services to support this transition across the development pipeline. Bio-Rad Laboratories, Inc. specializes in electroporation and transfection instrumentation for both research and clinical settings. QIAGEN provides a range of sample and assay technologies critical for the pre-clinical validation of gene delivery constructs.
Gene delivery technologies are methods designed to introduce foreign genetic material into host cells, a process called transfection. These systems utilize vehicles like viral vectors, such as lentivirus, or non-viral carriers like lipid nanoparticles to ensure high efficiency and targeted delivery. Their primary commercial purpose is enabling gene therapy and cell engineering. While viral vectors currently lead in application-specific use, non-viral vectors like nanoparticles are gaining significant traction among biotechnology firms due to improved safety profiles and manufacturing scalability.
Regulatory frameworks from the U.S. FDA and the European Medicines Agency (EMA) impose stringent requirements for Chemistry, Manufacturing, and Controls (CMC) data. These guidelines, alongside evolving standards from bodies like China's NMPA, directly influence vector characterization, safety testing, and ultimate market approval. The critical strategic choice for developers involves balancing the established efficacy of viral vectors against the manufacturing scalability and safety profile of non-viral alternatives.
Market Dynamics
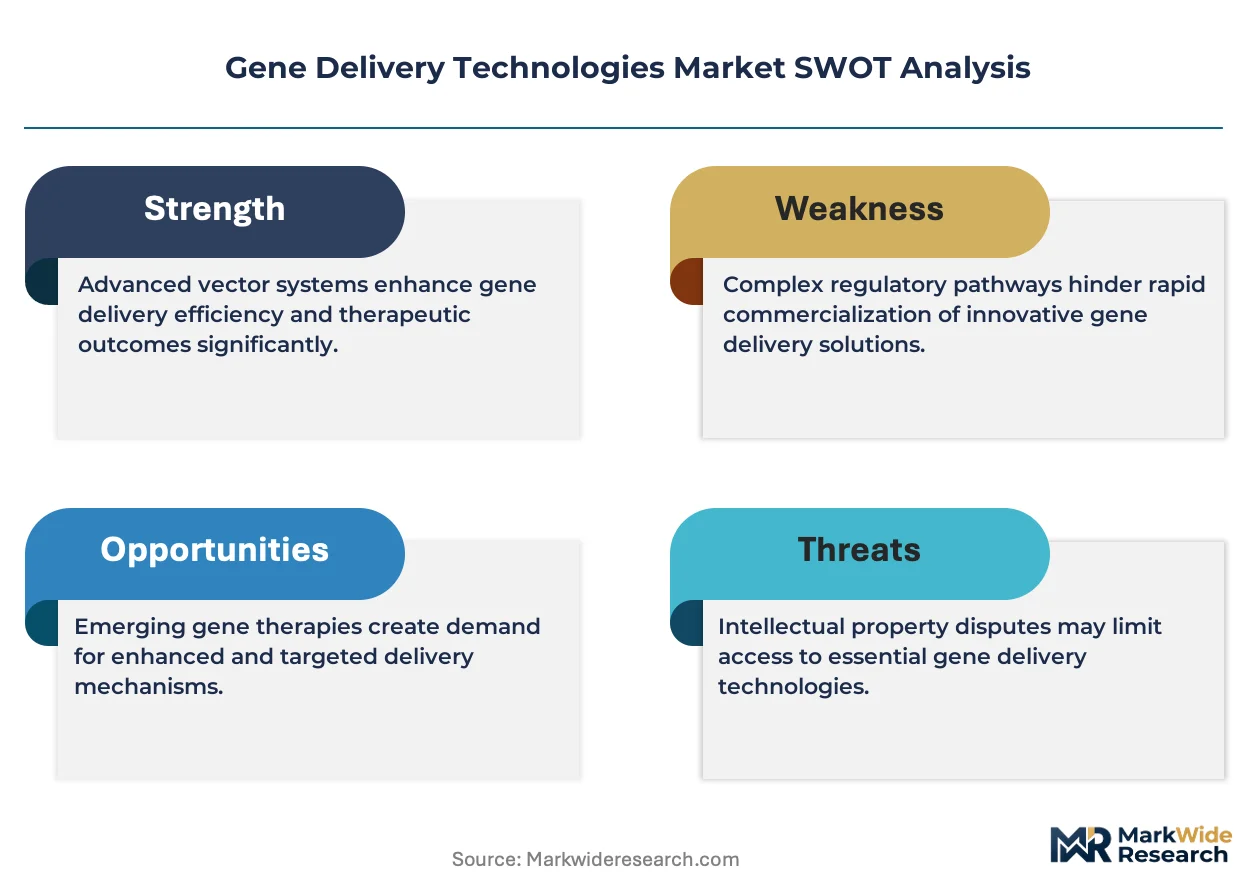
The market's central dynamic is the strategic trade-off between the established efficacy of viral vectors and the manufacturing scalability of non-viral systems. This tension dictates platform selection, investment priorities, and the entire approach to Chemistry, Manufacturing, and Controls.
Growth Catalysts
- CRISPR-Cas9 Refinements:Advances in CRISPR systems enhance gene editing precision, expanding the scope of treatable disorders and accelerating research.
- Monogenic Disease Pipeline:A robust clinical pipeline targeting monogenic diseases creates sustained demand for effective and safe delivery vectors.
- Regulatory Incentives:Accelerated approval pathways, like the FDA's RMAT designation, shorten timelines to market for qualifying gene therapies.
Market Restraints
- Vector Manufacturing Costs:The high cost of GMP-compliant viral vector production creates significant financial barriers, particularly for smaller biotechnology firms.
- Immunogenicity Concerns:Host immune responses to viral vectors can neutralize therapeutic effect and pose safety risks, limiting redosing options.
- CMC Regulatory Burden:Stringent Chemistry, Manufacturing, and Controls documentation required by the FDA and EMA presents a bottleneck, delaying clinical trials.
Strategic Opportunities
- AI-Powered Vector Design:Applying machine learning to design novel vectors offers a path to optimize tissue targeting and evade immune detection.
- In Vivo Delivery Systems:Developing vectors for safe direct in vivo administration represents a major growth area beyond current ex vivo therapies.
- Asia-Pacific Clinical Trials:Regulatory streamlining in China and South Korea creates opportunities for conducting multinational clinical trials.
Industry Challenges
- Specialized Talent Shortage:A scarcity of technicians with expertise in large-scale GMP vector manufacturing and complex analytics constrains industry growth.
- Assay Standardization Deficit:The lack of standardized analytical methods for quantifying vector potency and purity complicates regulatory comparisons and process scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Delivery Technologies Market |
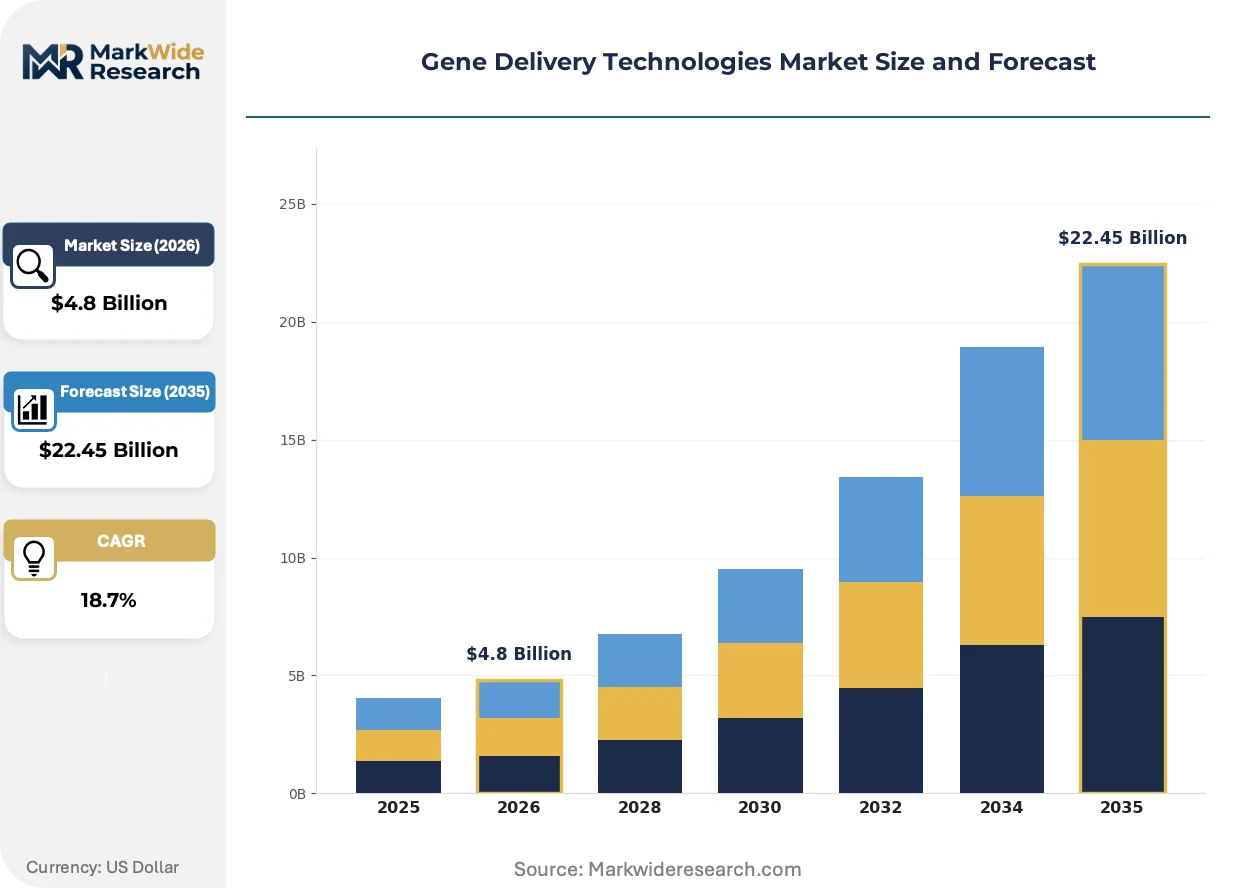
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viral Vectors, Non-viral Vectors, Liposomes, Nanoparticles, Electroporation Devices Technology: Viral, Physical, Chemical, Biological, Nanotechnology Application: Gene Therapy, Genetic Vaccines, Cell Engineering, Diagnostic Tools, Regenerative Medicine End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations, Academic Labs |
| Companies Covered | Thermo Fisher Scientific Inc., QIAGEN, Horizon Discovery Ltd., OriGene Technologies, Inc., Oxford Biomedica PLC, Takara Bio Inc., Bio-Rad Laboratories, Inc., F. Hoffmann-La Roche Ltd, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Delivery Technologies Market Strategic Shifts & Innovations
The field is transitioning from a research-centric phase to an industrialized one, where manufacturing scalability and regulatory compliance are paramount. This shift prioritizes technologies that offer predictable performance, cost-efficiency, and a clear path to commercial production.
Lipid nanoparticles (LNPs) serve as non-viral carriers for nucleic acids like mRNA. Biotechnology firms are rapidly adopting LNPs for vaccines and certain therapeutic applications due to their safety profile and manufacturing speed. This adoption is decomposing the monolithic reliance on viral vectors, creating a bifurcated market where vector choice is application-specific.
Global regulatory convergence is accelerating through the adoption of International Council for Harmonisation (ICH) guidelines like Q5A(R2). This alignment simplifies the requirements for Chemistry, Manufacturing, and Controls (CMC) data submissions across major markets. Multinational pharmaceutical companies benefit most, as they can use a more unified development and documentation strategy for FDA, EMA, and PMDA submissions.
A shift towards outsourcing vector development to specialized Contract Development and Manufacturing Organizations (CDMOs) is underway. This model allows emerging biotechs to access advanced manufacturing and regulatory expertise without massive capital outlays. The trend is most visible in biopharmaceutical clusters across the United States and Europe, where speed to clinic is critical.
Gene Delivery Technologies Market Segmentation
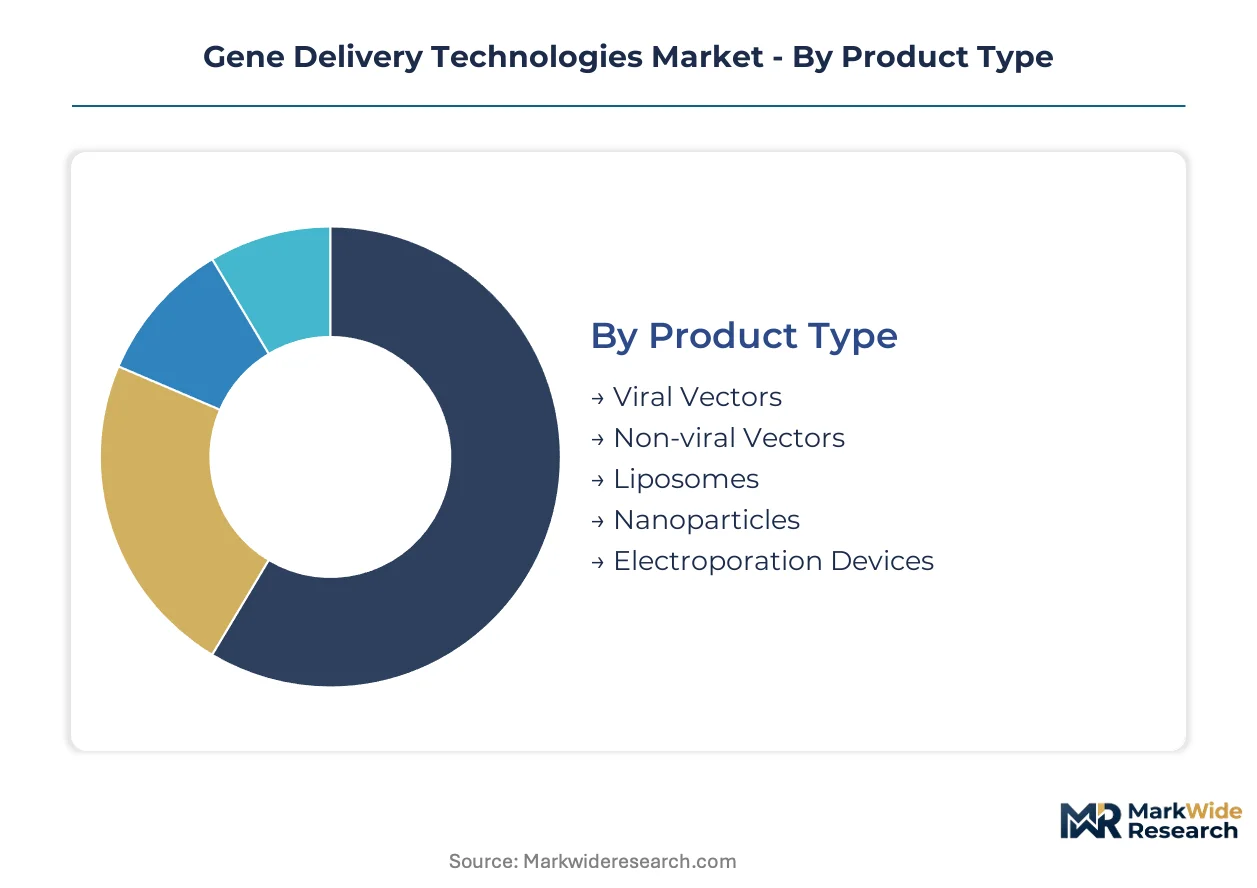
Understanding the intricate segmentation of the gene delivery technologies market is crucial for developers and investors. Each category highlights distinct functional roles and commercial implications across the therapeutic development pipeline. This granular view clarifies where innovation is most impactful and where market demand is concentrating.
Product Type:
Geographic demand for gene delivery products shows a clear bifurcation, with established viral vectors dominating domestic markets in the United States and Europe, while non-viral alternatives gain traction for export-led vaccine production in Asia-Pacific.
- Viral Vectors:These biological delivery systems, including lentivirus and adenovirus, excel at high-efficiency gene transfer into target cells. Demand concentrates in advanced gene therapy clinical trials across the United States, driven by their proven efficacy in treating complex monogenic disorders.
- Non-viral Vectors:Comprising synthetic carriers like lipid nanoparticles and polymers, these systems offer improved safety profiles and manufacturing scalability. Biotechnology firms in China and South Korea are increasingly adopting non-viral vectors for vaccine development and ex vivo cell engineering applications.
- Liposomes:These spherical lipid vesicles encapsulate nucleic acids for cellular delivery, offering a biocompatible option.
- Nanoparticles:Engineered at the nanoscale, these carriers provide targeted delivery and enhanced cellular uptake for various genetic materials.
- Electroporation Devices:These instruments use electrical pulses to transiently permeabilize cell membranes, facilitating non-viral gene entry.
Viral Vectors holds the largest share; momentum sits with Non-viral Vectors.
Technology:
The choice of gene delivery technology is fundamentally driven by its intended application, with viral methods preferred for precision gene editing and nanotechnology advancing rapidly for broader therapeutic use.
- Viral:Leveraging modified viruses, this technology offers highly efficient gene transfer for both in vivo and ex vivo applications. Pharmaceutical companies in Germany and the UK prioritize viral technology for advanced gene therapy development.
- Nanotechnology:Utilizing engineered nanoparticles, this approach enables targeted delivery and controlled release of genetic material. Research institutions in Japan and Canada are exploring nanotechnology for next-generation drug delivery systems.
- Physical:Methods like electroporation and gene gun delivery use mechanical or electrical forces to introduce genetic material into cells.
- Chemical:Cationic lipids and polymers form complexes with nucleic acids, facilitating their cellular uptake through endocytosis.
- Biological:This category encompasses methods like bacterial and eukaryotic cell-mediated gene transfer, offering niche delivery solutions.
Viral technology retains significant market share, yet nanotechnology-based approaches are expanding most quickly.
Application:
Different application areas cater to distinct customer profiles, ranging from specialized pharmaceutical companies developing gene therapies to research institutions utilizing diagnostic tools.
- Gene Therapy:This application focuses on correcting genetic defects by introducing functional genes into patient cells for therapeutic effect. Pharmaceutical companies in the United States are heavily invested in gene therapy clinical pipelines.
- Regenerative Medicine:Gene delivery supports tissue repair and regeneration by introducing genetic material to stimulate cell growth or differentiation. Academic labs and biotechnology firms in Europe are exploring this area for chronic disease treatment.
- Genetic Vaccines:These vaccines use genetic material to elicit an immune response against pathogens, offering rapid development and manufacturing.
- Cell Engineering:Modifying cellular functions through gene introduction is critical for research, bioproduction, and advanced cell-based therapies.
- Diagnostic Tools:Gene delivery systems aid in developing molecular diagnostics and biosensors for disease detection and monitoring.
Gene Therapy applications command the largest revenue, but Regenerative Medicine is gaining share fastest.
End User:
The supply of gene delivery solutions is heavily concentrated among specialized providers, influencing procurement patterns across the end-user landscape.
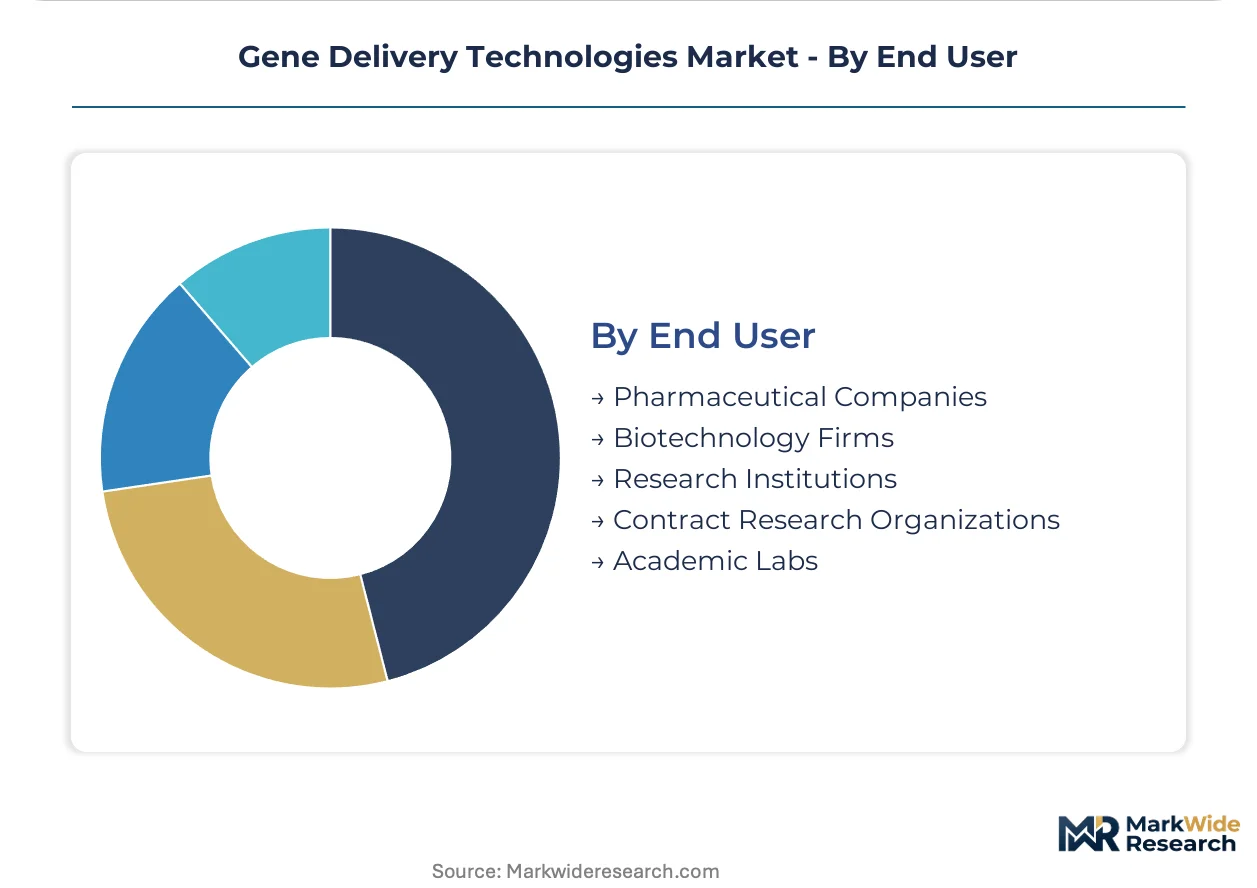
- Pharmaceutical Companies:These large entities engage in extensive R&D and commercialization of gene-based therapies and vaccines. They often seek long-term partnerships with CDMOs for GMP-compliant vector manufacturing.
- Biotechnology Firms:Focused on innovative therapeutic development, these companies leverage gene delivery for novel drug candidates and cell engineering. Many smaller biotechs rely on external expertise from Contract Research Organizations.
- Research Institutions:Universities and government-funded labs conduct fundamental research into gene function and therapeutic applications. Their procurement prioritizes research-grade reagents and cost-effective solutions.
- Contract Research Organizations:CROs provide specialized services for preclinical and clinical development, including vector characterization and safety testing. They bridge the gap between research and commercialization.
- Academic Labs:These labs focus on early-stage discovery and proof-of-concept studies, requiring flexible and accessible gene delivery tools.
Pharmaceutical Companies represent the largest end-user group, while Biotechnology Firms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global gene delivery technologies market sees a nuanced export-import balance, with established viral vector production often concentrated in developed nations for domestic use. Non-viral alternatives, however, drive export-led vaccine manufacturing in Asia-Pacific economies. This dynamic shapes investment in manufacturing infrastructure and regulatory alignment across different regions.
United States
Demand for gene therapy clinical trials consistently drives the market for high-efficiency viral vectors. The FDA's accelerated approval pathways, like the RMAT designation, shorten timelines for qualifying therapies. Extensive biopharmaceutical investment in the Boston-Cambridge biotech cluster fuels advanced research and development activities.
Germany
Pharmaceutical companies in Germany prioritize viral technology for advanced gene therapy development, leveraging strong academic research. European Medicines Agency (EMA) guidelines heavily influence Chemistry, Manufacturing, and Controls standards. Munich and Berlin serve as key R&D hubs, attracting significant investment in novel delivery systems.
China
Non-viral vectors, particularly lipid nanoparticles, are gaining significant traction for vaccine development and ex vivo cell engineering applications. China's NMPA regulations are increasingly influencing vector characterization and safety testing for domestic market approval. Biopharmaceutical parks in Shanghai and Suzhou lead in manufacturing scalability for these emerging technologies.
South Korea
Biotechnology firms in South Korea are rapidly adopting non-viral vectors for cell engineering and various therapeutic applications. The Ministry of Food and Drug Safety (MFDS) sets stringent standards for product quality and safety. Research institutions in Seoul and Daejeon are active in developing next-generation delivery systems.
Japan
Research institutions in Japan are exploring nanotechnology for next-generation drug delivery systems, focusing on targeted and controlled release. The Pharmaceuticals and Medical Devices Agency (PMDA) provides regulatory oversight for gene therapy products. Tokyo and Osaka remain critical centers for advanced biomedical research and development.
Gene Delivery Technologies Market Key Industry Players
Concentration sits with large, diversified life science conglomerates that offer a broad spectrum of gene delivery solutions. The market exhibits a tiered structure, ranging from specialized vector manufacturers to broader instrumentation providers. Portfolio diversification and strategic partnerships represent dominant competitive moves among these entities.
Within the broad life sciences sector, Thermo Fisher Scientific Inc. and QIAGEN exemplify companies offering extensive portfolios of reagents, instruments, and services supporting both research and clinical applications. Bio-Rad Laboratories, Inc., a US-based firm, represents a specialist in instrumentation for electroporation and transfection. These companies anchor different segments of the market from comprehensive solutions to targeted technology.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Horizon Discovery Ltd. |
| OriGene Technologies, Inc. |
| Oxford Biomedica PLC |
| Takara Bio Inc. |
| Bio-Rad Laboratories, Inc. |
| F. Hoffmann-La Roche Ltd |
| Promega Corporation |
| Others |
Cost & Logistics Intelligence
Non-viral alternatives, particularly lipid nanoparticles, are displacing traditional viral vectors, reshaping manufacturing geographies and introducing new cost structures that influence overall pricing dynamics.
Pricing Analysis
Pharmaceutical companies anchor a value-based pricing structure for gene delivery technologies, prioritizing efficacy and regulatory compliance. Pricing differentiation stems from the level of GMP compliance, the proven efficacy and purity of the vector, and the degree of customization required for specific gene therapy applications. Pricing pressure stems from the high cost of GMP-compliant viral vector production, particularly for smaller biotechnology firms. Research institutions exhibit the highest price sensitivity, while large pharmaceutical companies prioritize validated performance.
Supply Chain Analysis
The United States and Germany anchor advanced viral vector production for gene therapy clinical trials. China and South Korea concentrate on manufacturing non-viral vectors, especially lipid nanoparticles, for vaccine and ex vivo applications. The supply chain draws from critical raw materials such as specialized cell culture media, high-grade plasmids, and purification resins. Single-source vulnerability for high-purity reagents and specialized analytical equipment represents a structural risk. Distribution runs directly from CDMOs and specialized manufacturers to end-user pharmaceutical companies and research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gene delivery market requires a robust substitution defense as non-viral lipid nanoparticles threaten to displace traditional viral vectors. Incumbents must navigate this shift by diversifying their technology portfolios.
For Market Incumbents:Compound investments in both viral and non-viral vector platforms to mitigate the risk of technological obsolescence. Diversify manufacturing capabilities to support both established viral vector production and scalable lipid nanoparticle synthesis. Strategic partnerships with specialized Contract Development and Manufacturing Organizations can expand capacity and reduce the capital outlay required for GMP-compliant facilities, addressing the high manufacturing cost threat.
For New Entrants and Emerging Players:Lead with innovative non-viral delivery systems, such as advanced lipid nanoparticles, targeting applications where safety and manufacturing scalability are paramount. Focus on ex vivo cell engineering and vaccine development in Asia-Pacific markets, which show strong demand for these alternatives. A strong go-to-market angle involves offering cost-effective and rapidly scalable solutions that meet evolving regulatory standards.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized biotechnology firms demonstrating proficiency in both cutting-edge vector design and scalable GMP manufacturing processes. These firms, particularly those with strong intellectual property in AI-powered vector optimization, offer long-term viability. The signal to watch is the successful clinical translation of novel in vivo delivery systems with reduced immunogenicity.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Enhances production capacity for non-viral vectors, meeting growing demand from biotechnology firms. |
| Regulatory Approval Pathway | Accelerates market access for novel gene therapies, leveraging FDA and EMA expedited designations. |
| Strategic Partnership | Expands R&D capabilities and market reach through collaborations with academic labs and CDMOs. |
| Pipeline Diversification | Reduces reliance on single vector types by investing in both viral and non-viral delivery platforms. |
| AI-Powered Vector Design | Optimizes targeting and reduces immunogenicity, advancing next-generation gene delivery systems. |
Research Approach
Initial hypotheses were tested against primary input from gene therapy developers, regulatory affairs specialists, CDMO executives, and research scientists, and refined through iterative analysis. This involved in-depth interviews combined with validation against secondary sources like FDA filings, EMA submissions, and biopharmaceutical industry reports. Bottom-up data points were triangulated with top-down market sizing.
Variance decomposition isolated the impact of technology adoption, application-specific demand, and regional regulatory frameworks on market growth. Segmentation dimensions modeled included product type, technology, application, end-user, and geographic demand patterns across the analysis window. CAGRs were derived from historical trends and projected future adoption rates, incorporating clinical trial pipeline advancements and manufacturing capacity expansion.
The analysis sits within stated boundaries; outcomes outside major regulatory shifts or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions regarding clinical trial success rates and manufacturing cost efficiencies. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Cell and Gene Therapy Manufacturing Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global Therapeutic Vaccines Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market