
 Stem Cell Manufacturing Market | 2026-2036
Stem Cell Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Stem Cell Manufacturing Market Intelligence
The divergence in capital investment for automated, large-scale bioreactors versus manual, small-batch culture systems is bifurcating the market. Lonza Group leverages its extensive contract manufacturing infrastructure to serve biopharmaceutical clients requiring scalable production. Sartorius AG specializes in providing integrated bioprocessing solutions, including single-use technologies that cater to both research and commercial scales. Thermo Fisher Scientific competes by offering a broad portfolio encompassing cell culture media, reagents, and analytical instruments essential for the entire workflow.
Stem cell manufacturing involves the systematic isolation, expansion, and differentiation of cells under controlled conditions to ensure viability, purity, and potency. The primary purpose is to produce consistent, clinical-grade cell populations for therapeutic and research applications. Mesenchymal stem cells lead current clinical use, particularly for tissue regeneration. However, induced pluripotent stem cells represent the fastest-growing product category, driven by their utility in complex drug discovery models and future regenerative therapies. Biopharmaceutical firms constitute the largest end-user segment.
Regulatory frameworks from the US FDA, Europe's EMA, and Japan's PMDA impose rigorous Good Manufacturing Practice (GMP) standards on cell-based products. These regulations directly influence process validation, quality control requirements, and documentation for gaining market access. Consequently, manufacturers must continually balance investment in automation and process analytics against the evolving demands for scalability and stringent compliance. This decision is central to achieving commercial viability in the regenerative medicine field.
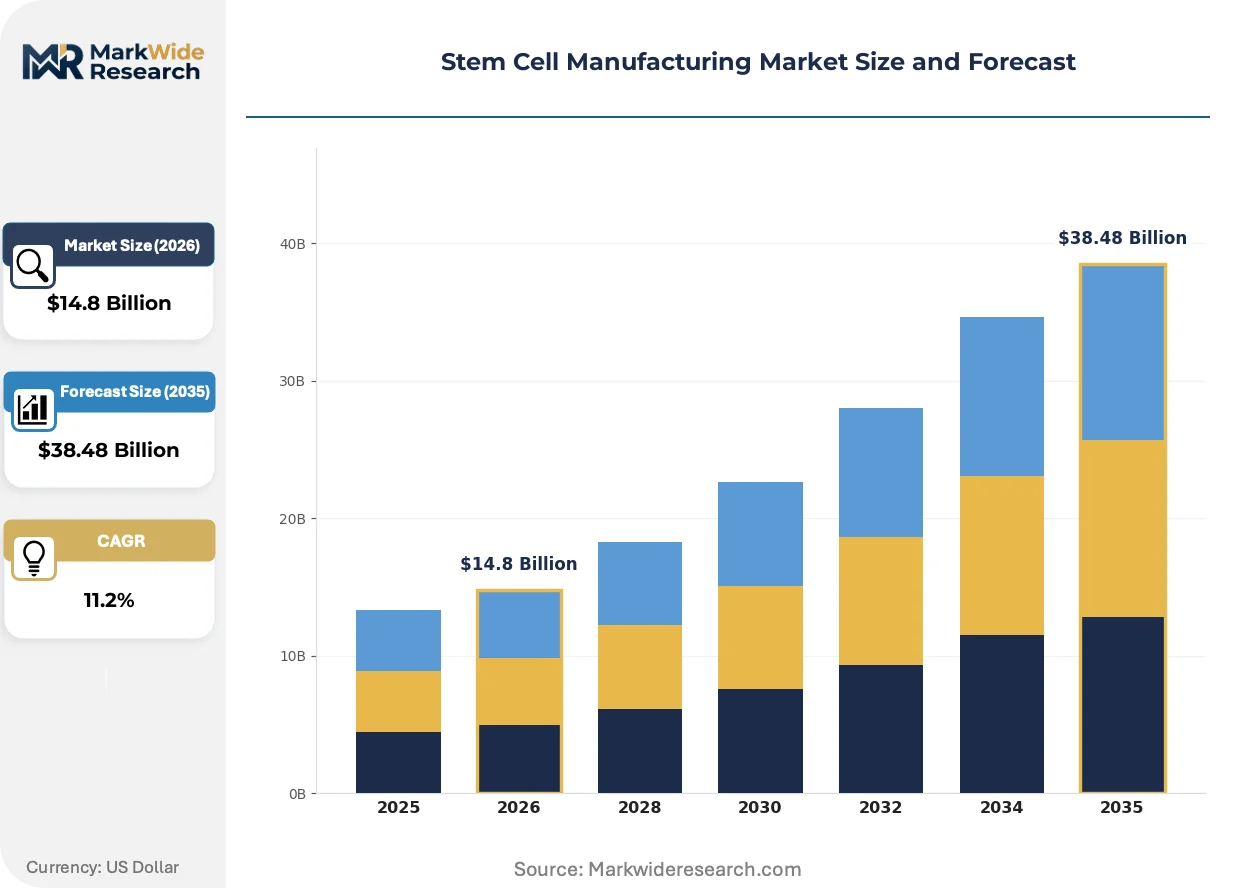
Market Dynamics
The central dynamic shaping the stem cell manufacturing market is the bifurcation between scalable, automated production and manual, small-batch systems. This split is driven by the dual needs of serving large biopharmaceutical clients and supporting early-stage research with flexible, lower-cost solutions.
Growth Catalysts
- Bioreactor Technology:Advancements in single-use bioreactors and perfusion systems are enabling more efficient and scalable expansion of cell populations, particularly mesenchymal stem cells, which directly supports tissue regeneration applications.
- Clinical Pipeline Expansion:A growing pipeline of cell-based therapies progressing through clinical trials, especially in oncology and regenerative medicine, creates sustained demand for GMP-grade manufacturing capacity.
- Regulatory Support:Expedited approval pathways offered by regulators like the US FDA and Europe's EMA for regenerative medicines are encouraging investment in clinical-stage manufacturing infrastructure.
Market Restraints
- High Capital Costs:The substantial upfront investment required to build and validate GMP-compliant manufacturing facilities, complete with automated bioreactors and cleanroom environments, presents a significant barrier to entry.
- Biological Complexity:Maintaining cell viability, potency, and genetic stability during large-scale culture remains a fundamental technical hurdle, leading to batch-to-batch variability and potential product failure.
- Input Material Scarcity:The supply of critical raw materials, such as clinical-grade growth factors and specialized culture media, is concentrated among a few suppliers, creating risks of price volatility and supply chain disruptions.
Strategic Opportunities
- iPSC Manufacturing Platforms:Developing dedicated, automated manufacturing workflows for induced pluripotent stem cells (iPSCs) addresses a major bottleneck for their use in creating complex disease models and future allogeneic therapies.
- Process Analytical Technology (PAT):Integrating real-time sensors and data analytics into the manufacturing process offers a path to predictive quality control, reducing batch failures and ensuring compliance with regulatory standards.
- Cryopreservation Logistics:Building out specialized cold-chain logistics and cryopreservation services for both starting materials and final cell therapy products represents an underserved segment of the value chain.
Industry Challenges
- Specialized Talent Deficit:A persistent shortage of scientists and technicians with combined expertise in cell biology, bioprocess engineering, and GMP regulations constrains operational capacity and quality assurance.
- Lack of Standardization:The absence of universally accepted reference materials and potency assays complicates process validation and makes it difficult to compare product efficacy across different manufacturers and clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stem Cell Manufacturing Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $38.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesenchymal, Hematopoietic, Induced Pluripotent, Embryonic, Neural Manufacturing Stage: Cell Isolation, Expansion, Differentiation, Cryopreservation, Quality Control Application: Tissue Regeneration, Drug Discovery, Gene Therapy, Immunotherapy, Toxicology Testing End User: Biopharmaceutical Firms, Contract Manufacturing Organizations, Research Institutes, Regenerative Medicine Centers |
| Companies Covered | Thermo Fisher Scientific, Lonza Group, Merck KGaA, Danaher Corporation, Sartorius AG, Miltenyi Biotec, Eppendorf AG, STEMCELL Technologies, Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stem Cell Manufacturing Market Strategic Shifts & Innovations
Process automation and the integration of digital technologies are transforming stem cell manufacturing from a lab-scale art into an industrial science. This shift is essential for meeting the quality, scalability, and cost-efficiency demands of commercial-stage cell therapies.
Microfluidic bioreactor systems provide a controlled microenvironment for cell culture. These systems are being adopted by academic research centers and early-stage biotechnology firms for process development and optimization. The technology is miniaturizing the physical footprint and material volume required for high-throughput screening and small-batch production, accelerating preclinical research timelines.
Regulatory agencies, including the US FDA and Japan's PMDA, are increasingly emphasizing the need for robust process controls and characterization data in regulatory submissions. This is forcing manufacturers to implement advanced process analytical technology (PAT) and quality-by-design (QbD) principles earlier in the development cycle. Biopharmaceutical firms are most affected, as they must now generate more comprehensive data to support their clinical trial applications.
Demand for manufacturing services is evolving from simple fee-for-service arrangements toward integrated, long-term partnerships with contract development and manufacturing organizations (CDMOs). This trend disrupts the traditional model where biopharmaceutical firms build their own captive capacity. The shift is most visible in the key life science clusters of the United States and Germany, where emerging companies seek to mitigate financial risk.
Stem Cell Manufacturing Market Segmentation
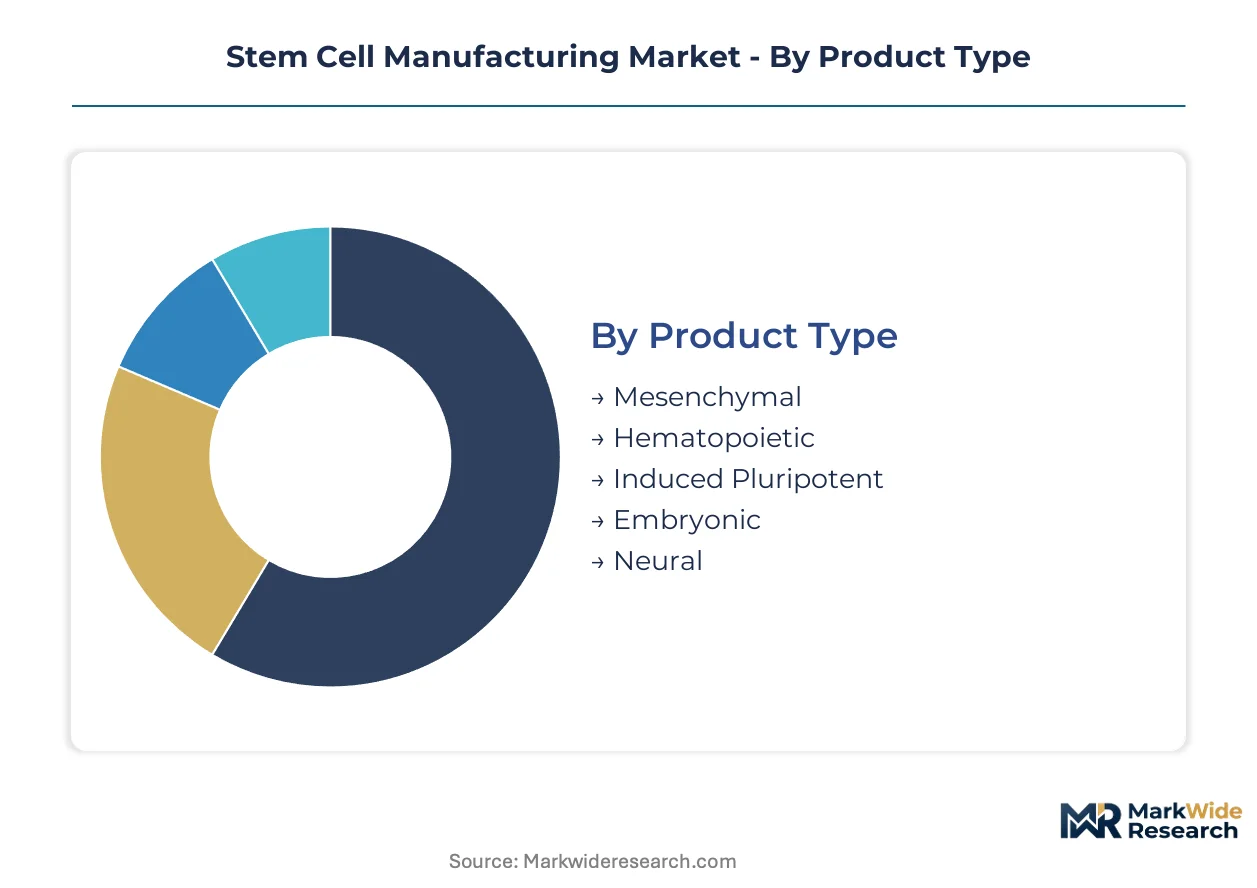
Understanding the segmentation of the stem cell manufacturing market is crucial for identifying distinct operational requirements, regulatory pathways, and investment priorities. This granular view enables stakeholders to tailor strategies for product development, market entry, and supply chain optimization across diverse applications and end-user demands.
Product Type:
Regulatory frameworks influence product categorization, with distinctions often made based on cell origin and differentiation potential.
- Mesenchymal:These multipotent stromal cells are widely researched for their immunomodulatory and regenerative properties, often derived from bone marrow, adipose tissue, or umbilical cord. Demand concentrates in tissue regeneration applications, driven by their established safety profiles in clinical trials.
- Induced Pluripotent:Reprogrammed adult somatic cells that exhibit pluripotency, offering an ethical and patient-specific source for various cell types without immune rejection concerns. Their utility in complex drug discovery models and future allogeneic therapies makes this the fastest-growing product category.
- Hematopoietic:These stem cells are primarily found in bone marrow and peripheral blood, crucial for blood cell formation and widely used in oncology for transplantation.
- Embryonic:Derived from human embryos, these pluripotent cells can differentiate into any cell type, but their use faces ethical and regulatory challenges in many regions.
- Neural:Specialized stem cells capable of differentiating into neurons, astrocytes, and oligodendrocytes, primarily explored for neurological disorder research.
Mesenchymal stem cells handle the majority of therapeutic throughput; induced pluripotent stem cells are the fastest mover on share.
Manufacturing Stage:
The volume and complexity of cell processing vary significantly across different stages of stem cell manufacturing.
- Expansion:This stage involves culturing isolated stem cells to achieve the high cell numbers required for clinical applications or research, often leveraging advanced bioreactor technologies. Demand is concentrating in scalable, automated systems within biopharmaceutical firms, driven by the need for consistent, large-batch production.
- Quality Control:Critical for ensuring cell viability, purity, potency, and sterility, this stage involves extensive testing and analytics to meet stringent regulatory standards. Regulatory bodies like the US FDA and Europe's EMA impose rigorous GMP standards, necessitating robust process analytical technology.
- Cell Isolation:This initial step involves separating stem cells from their source tissue, often requiring specialized techniques to maintain cell integrity and purity.
- Diferentiation:Guiding stem cells to develop into specific cell types for therapeutic use or disease modeling, a complex process requiring precise control over environmental cues.
- Cryopreservation:The process of preserving cells at ultra-low temperatures for long-term storage, essential for maintaining cell banks and facilitating global distribution of cell therapies.
Each manufacturing stage carries distinct cost implications, with expansion and quality control demanding substantial capital investment.
Application:
Different end-user requirements drive specific manufacturing adaptations for diverse stem cell applications.
- Tissue Regeneration:This application focuses on repairing or replacing damaged tissues and organs using stem cells, including treatments for orthopedic injuries, cardiovascular diseases, and skin grafts. Demand is concentrated in regenerative medicine centers across the United States and Germany, supported by advancements in bioreactor technology.
- Drug Discovery:Stem cells, particularly iPSCs, are used to create disease models in vitro for screening new drug candidates and understanding disease mechanisms, offering a more physiologically relevant testing platform. This application is expanding most quickly within biopharmaceutical research and development, driven by the need for more predictive preclinical models.
- Gene Therapy:Stem cells can serve as vehicles for delivering therapeutic genes to patients, addressing genetic disorders or enhancing immune responses in cancer treatment.
- Immunotherapy:Utilizing stem cell-derived immune cells to modulate the body's immune response, particularly in cancer treatment and autoimmune diseases.
- Toxicology Testing:Employing stem cell-derived cells to assess the toxicity of new compounds, offering an alternative to traditional animal testing methods.
Tissue regeneration applications currently dominate market demand, while drug discovery models demonstrate significant future potential.
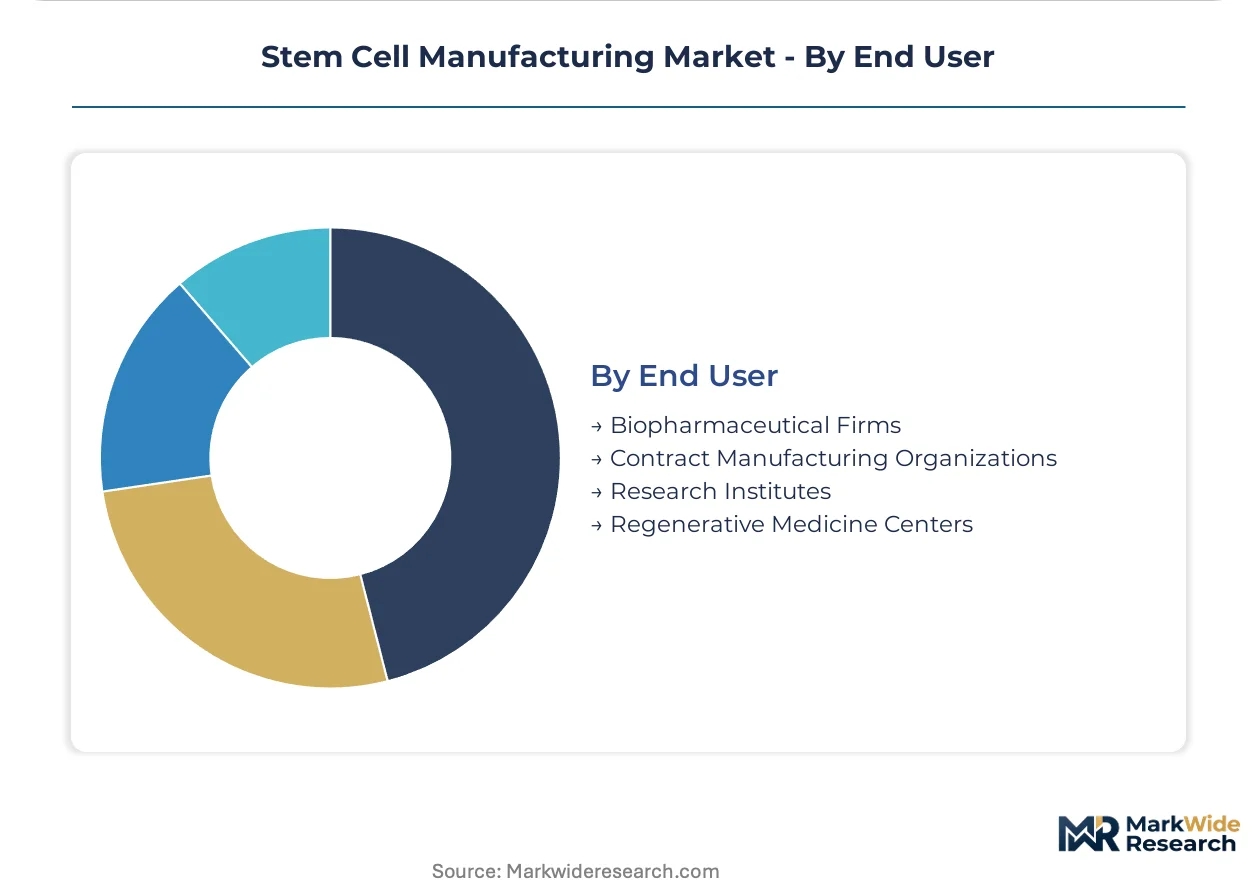
End User:
The concentration of specialized expertise and infrastructure defines the operational models of various end-user segments.
- Biopharmaceutical Firms:These companies develop and commercialize cell-based therapies, requiring large-scale, GMP-compliant manufacturing capabilities for clinical trials and market supply. This segment represents the largest end-user, driving demand for automated production platforms and robust quality systems.
- Contract Manufacturing Organizations:CDMOs provide specialized manufacturing services to biopharmaceutical and biotechnology clients, offering scalable production and regulatory expertise without requiring clients to build their own facilities. The shift towards integrated, long-term partnerships with CDMOs is accelerating in key life science clusters.
- Research Institutes:Academic and non-profit organizations conducting fundamental and translational research on stem cells, often requiring small-batch, flexible manufacturing solutions.
- Regenerative Medicine Centers:Clinical facilities that administer stem cell therapies directly to patients, requiring access to clinical-grade cells and specialized handling protocols.
Biopharmaceutical firms prioritize commercial-scale production, whereas contract manufacturing organizations offer flexible solutions for diverse clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity in stem cell manufacturing varies significantly, with academic research requiring more cost-sensitive, flexible solutions, while biopharmaceutical firms prioritize consistent, clinical-grade output regardless of higher investment. This bifurcation shapes regional investment patterns and regulatory focus across key life science hubs. Capital flows towards established clusters capable of supporting both ends of this spectrum.
United States
Biopharmaceutical firms in the United States drive substantial demand for large-scale, GMP-compliant manufacturing capacity, particularly for therapies progressing through clinical trials. The US FDA's expedited approval pathways for regenerative medicines encourage significant investment in advanced manufacturing infrastructure. Life science clusters in Boston and the San Francisco Bay Area are concentrating research and development, fostering innovation in cell expansion technologies.
Germany
Germany's robust biotechnology sector fuels demand for stem cell manufacturing, especially in tissue regeneration applications. The Europe's EMA imposes stringent GMP standards for cell-based products, influencing process validation and quality control requirements. Munich and Berlin serve as central hubs for both academic research and commercial development, attracting specialized talent and capital.
Japan
Japan demonstrates strong demand for induced pluripotent stem cell (iPSC) manufacturing platforms, driven by their utility in complex disease models and future regenerative therapies. The PMDA emphasizes robust process controls and characterization data in regulatory submissions, pushing manufacturers towards advanced analytical technologies. Kyoto and Tokyo are critical centers for iPSC research and commercialization efforts.
China
China's rapidly expanding biopharmaceutical industry generates increasing demand for stem cell manufacturing capabilities, particularly for oncology and regenerative medicine applications. The NMPA is developing and enforcing stricter GMP standards for advanced cell therapies, necessitating higher quality control investments. Shanghai and Beijing are emerging as key centers for cell therapy development and manufacturing capacity expansion.
Stem Cell Manufacturing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the stem cell manufacturing market, reflecting the bifurcated demand for both advanced solutions and economical options. The market structure exhibits a mix of specialized technology providers, integrated solution vendors, and contract manufacturing organizations. Companies are actively engaging in capacity expansion and strategic partnerships to address evolving client needs.
Specialists providing integrated bioprocessing solutions, such as Sartorius AG, cater to both research and commercial scales with single-use technologies. Lonza Group leverages its extensive contract manufacturing infrastructure to serve biopharmaceutical clients requiring scalable production. Thermo Fisher Scientific occupies a position as a broad portfolio supplier, offering cell culture media, reagents, and analytical instruments essential for the entire workflow.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Lonza Group |
| Merck KGaA |
| Danaher Corporation |
| Sartorius AG |
| Miltenyi Biotec |
| Eppendorf AG |
| STEMCELL Technologies |
| Corning |
| Others |
Cost & Logistics Intelligence
The US FDA's stringent Good Manufacturing Practice (GMP) standards gate both the qualification of manufacturing supply and the price differentiation of clinical-grade cell therapy products. This regulatory oversight ensures product quality while driving up production costs for compliant facilities.
Pricing Analysis
Service and maintenance contracts for bioreactor systems and analytical instruments drive significant lifetime value for equipment providers. The dominant pricing model for manufacturing services is project-based, often transitioning to long-term contract-based offtake agreements for commercial-scale production. Price differentiation stems from the certification level of manufacturing facilities and the volume scale of cell batches. Pricing pressure arises from the high capital expenditures required for GMP-compliant facilities. Biopharmaceutical firms, needing consistent clinical-grade output, are less price-sensitive than academic research institutes seeking flexible, lower-cost solutions.
Supply Chain Analysis
Port congestion and container availability impact the timely delivery of specialized equipment and raw materials for stem cell manufacturing. Geographic supply concentration for critical raw materials, such as clinical-grade growth factors and specialized culture media, centers on a few key suppliers in the United States and Europe. Single-source vulnerability for these specialized inputs presents a significant supply chain risk. Distribution runs through a hybrid model, combining direct sales from manufacturers to biopharmaceutical firms with specialized cold-chain logistics for cell therapy products reaching regenerative medicine centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stem cell manufacturing market faces a capability scarcity, particularly in bioprocess engineering expertise combined with GMP regulatory knowledge. Addressing this talent gap is critical for scaling operations.
For Market Incumbents: Consolidate fragmented manufacturing capacity through strategic acquisitions of smaller, specialized CDMOs focusing on iPSC or gene therapy platforms. This move mitigates the threat of emerging biotechnology firms with novel process technologies. Invest in advanced process analytical technology (PAT) to enhance real-time quality control, reducing batch failures and ensuring consistent product quality in a highly regulated environment.
For New Entrants and Emerging Players: Differentiate on specialized manufacturing services for induced pluripotent stem cells (iPSCs), which represent a rapidly growing product category with significant future potential. The drug discovery application segment, currently expanding within biopharmaceutical research, offers a penetrable entry point. A key go-to-market angle involves offering flexible, small-batch manufacturing solutions coupled with robust process development support for early-stage clinical trials.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the commercial-scale manufacturing segment, driven by the need for automated bioreactors and GMP-compliant facilities. Acquisition targets should include specialized contract development and manufacturing organizations (CDMOs) with proven expertise in cell therapy production and strong regulatory track records. A signal to watch is the increasing number of cell-based therapies progressing to Phase 3 clinical trials, indicating future demand for large-scale production capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Increases capacity for clinical trials and commercial supply of cell therapies. |
| Process Analytical Technology Integration | Enhances real-time quality control and ensures compliance with regulatory standards. |
| Cold-Chain Logistics Expansion | Facilitates global distribution and long-term storage of sensitive cell products. |
| iPSC Platform Development | Addresses a critical bottleneck for future allogeneic therapies and drug discovery models. |
| Talent Development Programs | Mitigates the persistent shortage of specialized bioprocess and regulatory expertise. |
Research Approach
Initial hypotheses were tested against primary input from bioprocess engineers, regulatory affairs specialists, and CDMO executives, then refined through iterative analysis. This involved combining insights from in-depth interviews with industry stakeholders and validating findings against secondary research. Secondary data sources included US FDA and Europe's EMA regulatory filings, scientific publications from PubMed, and corporate annual reports, triangulating quantitative and qualitative evidence.
The analytical framework decomposed market variance across the analysis window by segmenting based on product type, manufacturing stage, application, end-user, and regional regulatory environment. Compound annual growth rates were derived from historical data trends and projected future demand, considering factors like clinical trial success rates and bioreactor adoption curves. This approach ensures a robust, data-driven forecast.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory shifts or major clinical trial failures would require recalibration. Forecasts reflect assumptions documented regarding technological advancements and market dynamics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Gene Vector Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Global Gene Therapy Market