
 Gene Therapy Products Market | 2026-2036
Gene Therapy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Therapy Products Market Insights
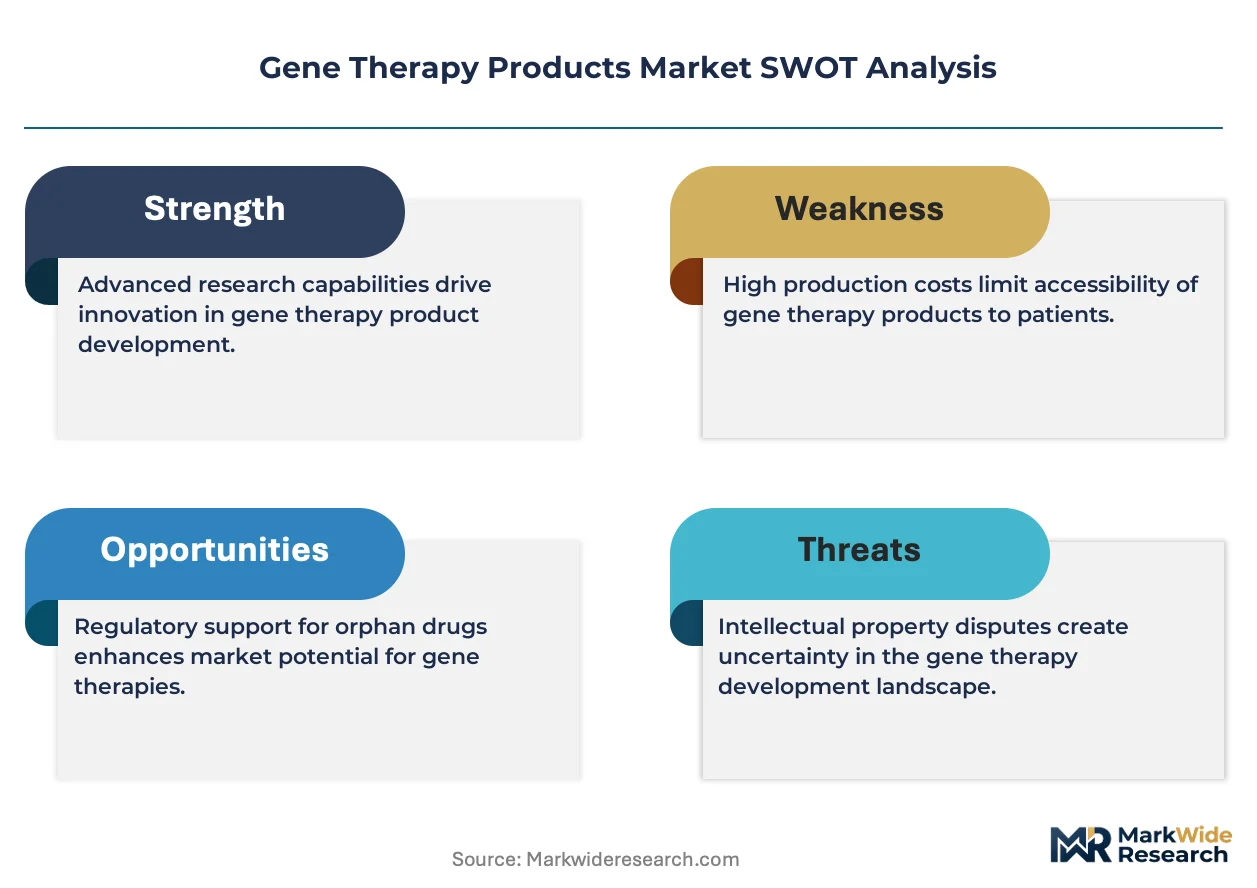
Buyer concentration among hospital networks and specialty treatment centers is restructuring procurement dynamics for gene therapy products. Novartis AG leverages its established oncology infrastructure to secure preferred provider agreements with major academic medical centers. bluebird bio sustains manufacturing partnerships that anchor its distribution to certified treatment sites. Biogen Inc. competes through specialized neurology-focused delivery networks that control patient access pathways.
Gene therapy products are biopharmaceutical agents that introduce, remove, or modify genetic material within a patient's cells to treat or prevent disease, typically utilizing viral vectors such as adeno-associated virus (AAV) or lentivirus with payload capacities ranging from 4.7 to 10 kilobases. These products serve the primary commercial purpose of correcting monogenic disorders and engineering cellular responses against malignancies where conventional small-molecule interventions fail. AAV vector systems occupy the dominant manufacturing volume position due to established safety profiles in ocular and hematologic applications, while mRNA platforms represent the fastest-expanding modality as lipid nanoparticle formulation expertise diffuses beyond vaccine applications. Oncology commands the largest current revenue pool among therapeutic applications, though rare genetic disorders sustain premium pricing structures that attract specialized development investment.
The FDA's regenerative medicine advanced therapy (RMAT) designation and the EMA's priority medicines (PRIME) scheme create divergent market access timelines that shape corporate clinical trial location decisions. ISO 21973 standards for analytical methods in gene therapy vector characterization establish minimum quality benchmarks that differentiate contract manufacturers capable of supporting commercial supply. Stakeholders must monitor how CMS reimbursement frameworks for inpatient gene therapy administration evolve relative to site-of-care economics.
Market Dynamics
Academic medical centers are consolidating in-house viral vector manufacturing capabilities, compressing procurement cycles and reshaping supplier relationships across the gene therapy value chain. This vertical integration push is redrawing competitive boundaries between contract manufacturers and treatment site networks.
Growth Catalysts
- RMAT designation:The FDA's regenerative medicine advanced therapy pathway compresses clinical trial timelines and accelerates commercialization for qualifying candidates. Developers prioritize US trial sites to capture this regulatory advantage.
- Lentivirus manufacturing scale-up:Suspension bioreactor platforms are displacing adherent cell culture for lentiviral vector production, expanding payload capacity for hematologic applications.
- Boston-San Francisco corridor concentration:Venture deployment and NIH funding gravity centers on these biotech clusters, concentrating talent pools and specialized GMP infrastructure.
Market Restraints
- Plasmid DNA supply concentration:A limited base of qualified GMP plasmid suppliers creates single-source vulnerability for AAV and lentivirus producers.
- ISO 21973 compliance costs:Vector characterization method validation imposes capital-intensive analytical infrastructure requirements on contract manufacturers.
- Allogeneic cell therapy substitution:Off-the-shelf CAR-T platforms threaten autologous gene therapy economics in oncology indications.
Strategic Opportunities
- India CDMO expansion:The country's PLI scheme for biopharmaceuticals creates manufacturing cost arbitrage for vector production destined for emerging markets.
- In vivo gene editing convergence:CRISPR-Cas9 integration with lipid nanoparticle delivery opens hereditary disease applications beyond viral vector constraints.
- Japan PMDA Sakigake pathway:Priority review designation for regenerative medicines accelerates Japan market entry timelines for Western developers.
Industry Challenges
- Vector analytical scientist scarcity:Specialized expertise in potency assay development and empty capsid quantification outpaces training pipeline output.
- Site certification timeline compression:Treatment center qualification for commercial gene therapy administration requires 18-24 month infrastructure buildouts that lag approval schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Therapy Products Market |
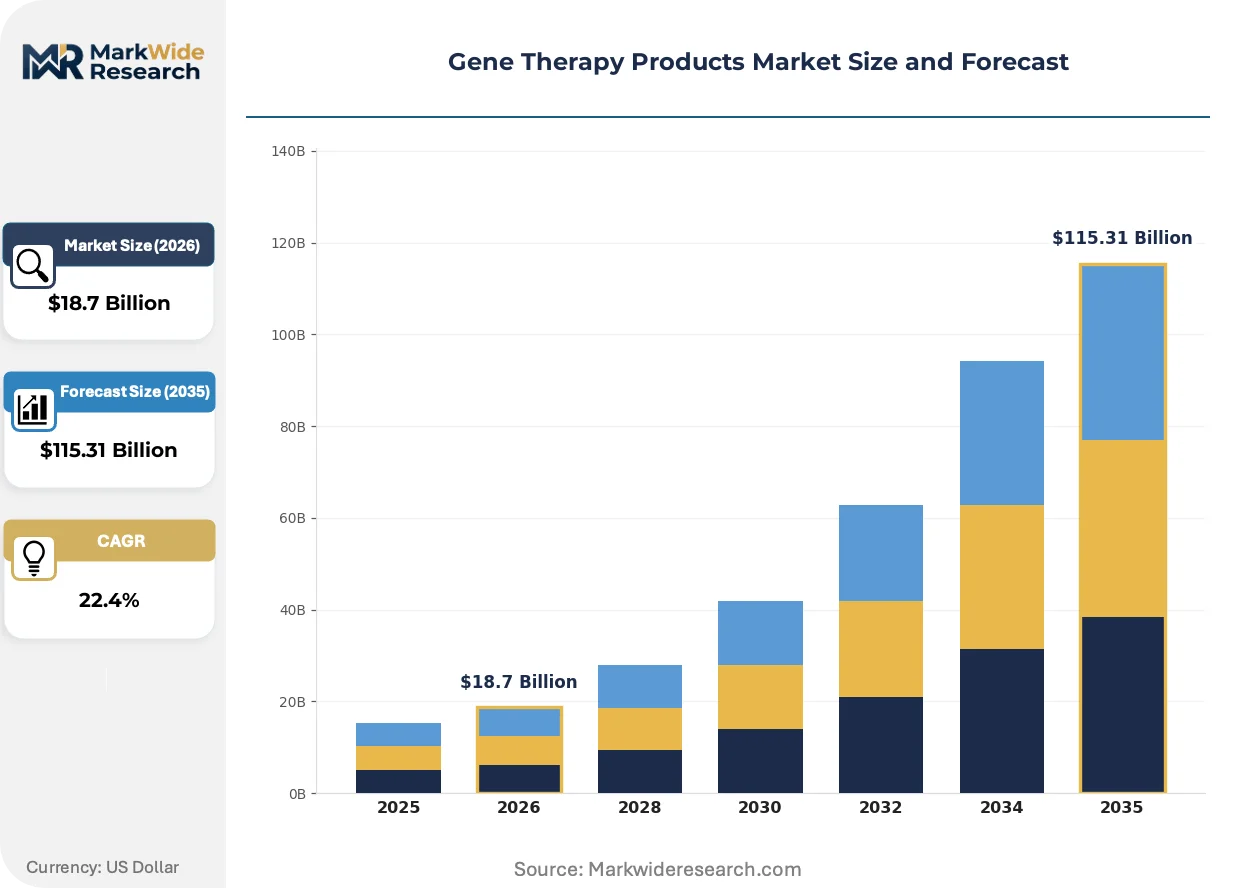
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AAV, Lentivirus, Plasmid DNA, mRNA Application: Oncology, Rare Genetic Disorders, Infectious Diseases, Cardiovascular Delivery Method: In Vivo, Ex Vivo, Direct Injection, Liposomal End User: Research Institutions, Hospitals, Biopharmaceutical Companies, Contract Research Organizations |
| Companies Covered | Novartis AG, bluebird bio, Biogen Inc., Amgen Inc., Spark Therapeutics, Gilead Sciences Inc., BioMarin Pharmaceutical, CRISPR Therapeutics, UniQure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Therapy Products Market Trends and Innovations
Continuous manufacturing platforms are displacing batch-process dominance in viral vector production, compressing cycle times and enabling real-time release testing. This operational shift is automating quality control integration and redefining competitive moats around process analytical technology capabilities.
Closed-system bioreactor technology is automating contamination risk reduction in GMP suites. CDMOs deploying these platforms report 40% footprint compression versus traditional cleanroom configurations. The technology is enabling distributed manufacturing networks closer to treatment sites, reducing cold-chain logistics burden for time-sensitive cellular products.
The EU's Advanced Therapy Medicinal Products Regulation revision is harmonizing manufacturing inspection standards across member states. This regulatory convergence is reducing duplicate facility audits for multi-national sponsors. Germany and France are consolidating national competent authority review functions, compressing centralized procedure timelines for vector-based therapies.
Hospital network procurement consolidation is compressing supplier negotiation cycles and unbundling vector supply from administration service contracts. Major academic medical center alliances in the United States are establishing preferred manufacturer pools with volume-commitment structures. This purchasing evolution is most visible in hematologic gene therapy categories where treatment site density concentrates negotiating leverage.
Gene Therapy Products Market Segmentation
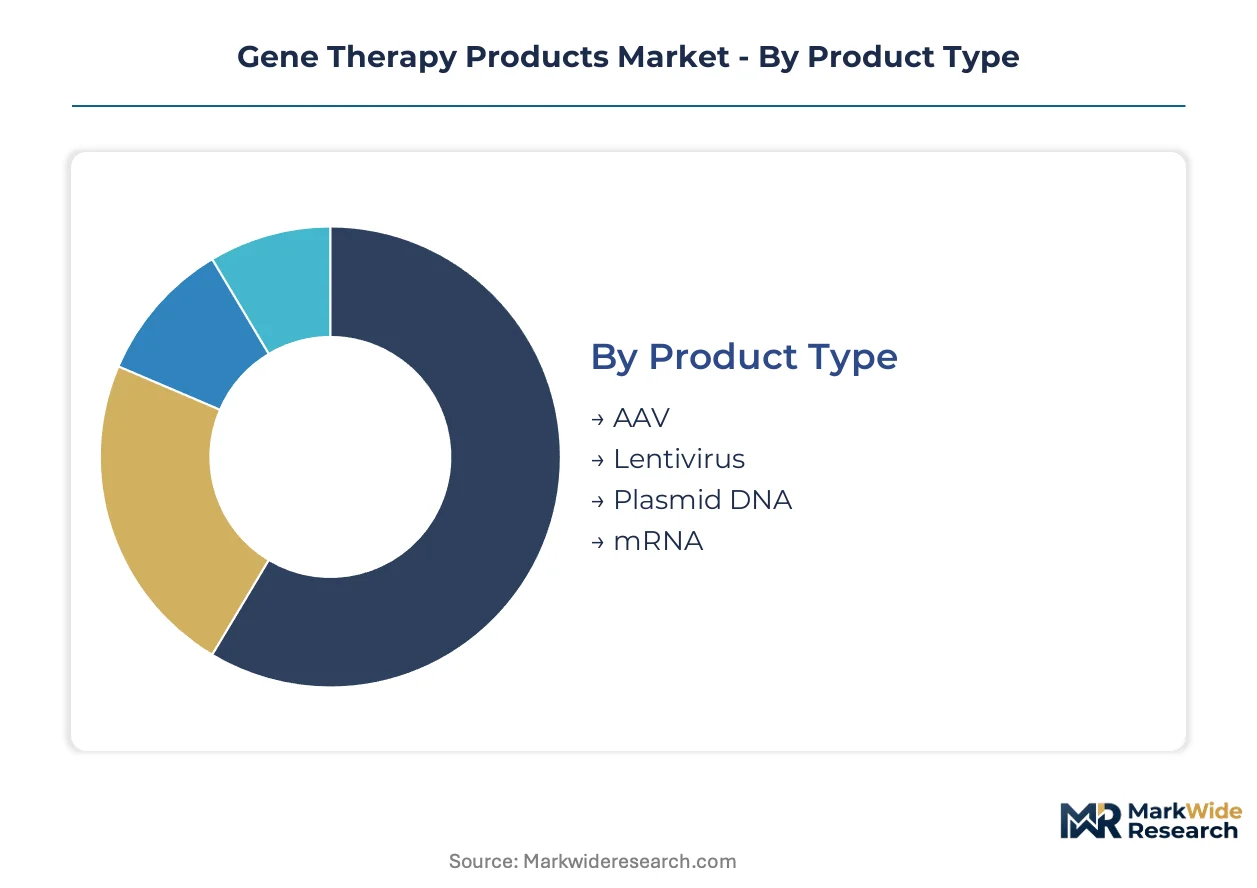
Gene therapy product segmentation reveals how manufacturing capabilities and clinical trial concentration align with vector biology constraints. Supply-side specialization in viral vector production creates natural boundaries between product categories that shape procurement patterns across therapeutic areas.
Product Type:
Vector manufacturing infrastructure concentrates around platform-specific bioreactor configurations and analytical method suites that lock in supplier relationships.
- AAV:Adeno-associated virus vectors dominate commercial manufacturing volumes with established safety profiles in ocular and hematologic applications. Demand concentrates at academic medical centers in Boston and San Francisco where in-house GMP suites process patient-specific batches. FDA regenerative medicine advanced therapy designations for AAV-based candidates accelerate site qualification timelines.
- Lentivirus:Suspension bioreactor platforms are displacing adherent cell culture systems, expanding payload capacity for CAR-T and hematopoietic stem cell applications. Supply concentrates among contract manufacturers with validated lentiviral master cell banks and ISO 21973-compliant potency assays.
- Plasmid DNA:Limited qualified GMP suppliers create single-source vulnerability for AAV and lentivirus producers dependent on transfection-grade material.
- mRNA:Lipid nanoparticle formulation expertise diffusing beyond vaccine applications drives the steepest capacity expansion trajectory among nucleic acid platforms.
AAV absorbs the bulk of installed capacity; mRNA is expanding most quickly.
Application:
Reimbursement frameworks and treatment site density determine which therapeutic areas sustain premium pricing and specialized manufacturing investment.
- Oncology:CAR-T and tumor-infiltrating lymphocyte therapies command the largest current revenue pool, with Novartis AG and Gilead Sciences anchoring manufacturing networks to certified treatment centers. CMS inpatient reimbursement policies shape site-of-care economics for cellular products.
- Rare Genetic Disorders:Monogenic disease applications sustain premium pricing structures that attract specialized development investment despite limited patient populations. Bluebird bio's betibeglogene autotemcel and elivaldogene tivaparvovec anchor distribution to qualified treatment sites with 18-24 month certification timelines.
- Infectious Diseases:mRNA platform adaptability positions this segment for rapid response manufacturing, though commercial sustainability lags oncology and rare disease categories.
- Cardiovascular:AAV-mediated gene transfer for heart failure indications represents emerging demand concentrated among heart transplant centers with established interventional cardiology infrastructure.
Oncology captures the majority of manufacturing capacity allocation; rare genetic disorders maintain the highest margin profile.
Delivery Method:
Route of administration dictates cold-chain logistics complexity and treatment site infrastructure requirements that segment procurement relationships.
- In Vivo:Direct vector administration to patients eliminates ex vivo cell handling, compressing treatment site infrastructure requirements to infusion-capable suites. AAV and lipid nanoparticle platforms dominate this category with established intravenous and intravitreal delivery protocols.
- Ex Vivo:Patient cell harvest, genetic modification, and reinfusion require proximity manufacturing or sophisticated logistics networks that concentrate procurement among integrated health systems. Autologous CAR-T therapies anchor this segment with patient-specific batch economics.
- Direct Injection:Intramuscular, intratumoral, and intrathecal routes limit addressable patient populations to specialized intervention centers with advanced imaging guidance.
- Liposomal:Non-viral delivery systems reduce immunogenicity concerns and enable repeat dosing, though transfection efficiency constraints limit current therapeutic applications.
Ex vivo absorbs the bulk of manufacturing complexity premium; in vivo is climbing the fastest as lipid nanoparticle platforms mature.
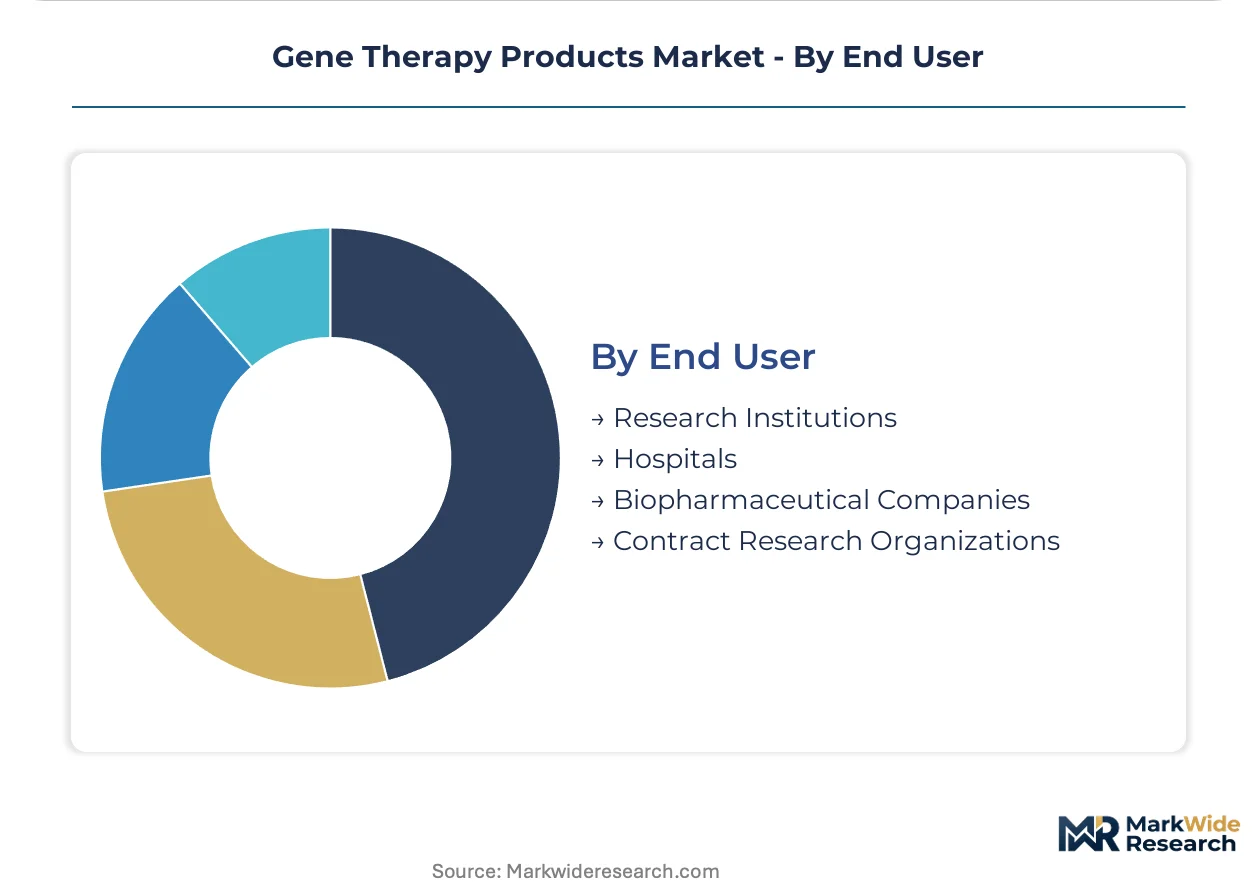
End User:
Procurement authority and technical specification control vary sharply across customer types, fragmenting supplier engagement models.
- Research Institutions:NIH-funded academic centers in Boston and San Francisco drive early-stage vector innovation with non-GMP manufacturing capabilities that transition to commercial partnerships.
- Hospitals:Consolidating hospital networks establish preferred manufacturer pools with volume-commitment structures, unbundling vector supply from administration service contracts.
- Biopharmaceutical Companies:Sponsors with internal GMP capabilities compete with CDMO partnerships based on pipeline concentration and platform standardization strategies.
- Contract Research Organizations:Vector analytical services and potency assay development represent specialized procurement relationships distinct from manufacturing supply.
Hospitals command the largest procurement volume; biopharmaceutical companies are gaining share fastest through vertical integration into manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for gene therapy products concentrates heavily in the United States, where academic medical centers and biotech clusters drive procurement volume. Venture deployment and NIH funding gravity pull manufacturing investment toward specific metropolitan corridors.
United States
Boston and San Francisco anchor domestic demand, with academic medical centers expanding in-house GMP manufacturing suites. The FDA's regenerative medicine advanced therapy designation accelerates clinical trial timelines and commercialization pathways. Novartis AG and bluebird bio maintain preferred provider agreements with major treatment networks in these corridors.
Germany
The national competent authority consolidates review functions under the EU's Advanced Therapy Medicinal Products Regulation revision. EMA manufacturing inspection harmonization reduces duplicate facility audits for vector-based therapies. Heidelberg and Munich host specialized CDMO infrastructure serving Western European sponsors.
Switzerland
Swissmedic maintains streamlined pathways for advanced therapy medicinal products that attract Western developers seeking parallel EU market entry. Basel anchors pharmaceutical innovation clusters with established viral vector manufacturing expertise. Roche and Novartis heritage creates specialized talent pools in gene therapy process development.
Japan
The PMDA's Sakigake priority review designation accelerates market entry timelines for regenerative medicines from Western sponsors. METI funding supports domestic cell and gene therapy manufacturing infrastructure expansion. The Kanto region around Tokyo concentrates clinical trial site networks and specialized GMP facilities.
India
The PLI scheme for biopharmaceuticals creates manufacturing cost arbitrage for vector production destined for emerging markets. CDSCO regulatory frameworks evolve to accommodate advanced therapy imports while domestic capabilities mature. Hyderabad and Bangalore host expanding contract development and manufacturing infrastructure.
Gene Therapy Products Market Competitive Landscape
United States producers anchor the premium-tier vector supply; European specialists hold regulatory compliance advantages. The market structure concentrates around platform-specific manufacturing capabilities that lock in supplier relationships. Three archetypes dominate: integrated pharmaceutical conglomerates with oncology infrastructure, pure-play gene therapy developers with certified treatment site networks, and contract manufacturers with ISO 21973-compliant analytical suites. Capacity expansion and strategic partnerships represent the dominant competitive moves as sponsors secure supply for commercial launches.
Within the integrated pharmaceutical tier, Novartis AG and Gilead Sciences exemplify archetypes leveraging established infrastructure to anchor manufacturing networks. Bluebird bio occupies a position representing pure-play developers dependent on certified treatment site partnerships. These three entities collectively illustrate how geographic concentration in Boston and San Francisco corridors shapes competitive positioning through proximity to academic medical center demand.
| Leading Market Players |
|---|
| Novartis AG |
| bluebird bio |
| Biogen Inc. |
| Amgen Inc. |
| Spark Therapeutics |
| Gilead Sciences Inc. |
| BioMarin Pharmaceutical |
| CRISPR Therapeutics |
| UniQure |
| Others |
Pricing and Supply Chain Analysis
Plasmid DNA costs cascade through viral vector manufacturing tiers, with transfection-grade material commanding premium pricing at GMP-compliant suppliers before flowing into AAV and lentivirus production contracts. ISO 21973 analytical validation requirements stratify contract manufacturers across premium-certified, standard-compliant, and economy-tier service levels that academic medical centers and biopharmaceutical sponsors navigate during procurement cycles.
Pricing Analysis
High-volume oncology applications absorb manufacturing capacity at compressed margins while rare genetic disorder therapies sustain premium pricing structures. Three-tier pricing structure across premium-certified, standard-validated, and economy-tier contract manufacturers reflects ISO 21973 compliance depth and potency assay sophistication. Cost compression in standard-tier lentivirus production is intensifying as suspension bioreactor platforms displace legacy adherent systems. Hospital networks exhibit acute price sensitivity in CAR-T procurement, whereas rare disease sponsors demonstrate lower elasticity due to limited qualified supplier pools.
Supply Chain Analysis
Single-source vulnerability sits with qualified GMP plasmid suppliers concentrated in the United States, Germany, and Switzerland. Vector production draws from transfection-grade plasmids, specialized cell culture media, and lipid nanoparticle formulation chemistries. Tariff exposure on European-sourced analytical instrumentation threatens contract manufacturer cost structures. Distribution runs through certified treatment site networks requiring 18-24 month qualification timelines that synchronize with commercial launch schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy manufacturing capacity constraints are forcing consolidation among subscale contract developers unable to secure preferred provider status with hospital networks. FDA regenerative medicine advanced therapy designation timelines compress competitive windows for capital-constrained players.
For Market Incumbents: Deepen ISO 21973-compliant analytical capabilities to defend against emerging CDMOs in India and Southeast Asia. Anchor manufacturing partnerships with Boston and San Francisco academic medical centers before site certification queues lengthen. Prioritize lentivirus suspension platform capacity additions to capture CAR-T manufacturing share from adherent-system competitors. For New Entrants and Emerging Players: Begin with cardiovascular AAV applications where heart transplant center density remains underpenetrated relative to oncology saturation. Target Japan's PMDA Sakigake pathway for accelerated regulatory validation that Western sponsors underutilize. Position around in vivo gene editing convergence with lipid nanoparticle delivery to bypass established viral vector supply bottlenecks. For Investors and Strategic Acquirers: PMDA Sakigake designation acceleration is the leading indicator that Japan market entry timelines are compressing for Western developers, signaling acquisition premium expansion for Japan-registered assets. Mid-tier CDMOs with validated master cell banks and regional GMP infrastructure represent the optimal acquisition archetype over the coming decade. Monitor CMS reimbursement framework finalization for inpatient gene therapy administration as the signal to watch for site-of-care economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Suspension bioreactor deployment expands lentivirus payload capacity for hematologic applications. |
| Regulatory Approval Pathway | RMAT designation accelerates FDA timelines and anchors US trial site concentration. |
| Clinical Trial Advancement | Heidelberg and Munich CDMO infrastructure serves Western European sponsor demand. |
| Long-term Supply Agreement | Preferred provider contracts with hospital networks lock in vector procurement volumes. |
| Joint Venture | India PLI scheme partnerships enable cost arbitrage for emerging market vector supply. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews across vector manufacturing executives, regulatory affairs leads at sponsors, hospital procurement managers, and CDMO business development directors. FDA 483 observations, EMA manufacturing inspection reports, ClinicalTrials.gov protocol registries, and ISO certification databases provided validation layers. Bottom-up vector production capacity tallies triangulated against top-down therapeutic area demand projections.
Data-stream reconciliation across supply-side capacity surveys and demand-side treatment site expansion plans shaped the analytical framework across the analysis window. Segmentation dimensions included vector platform biology, therapeutic application area, delivery method complexity, and end-user procurement authority. CAGRs derived from patient population epidemiology, approved therapy pricing trajectories, and manufacturing cost curve assumptions for suspension versus adherent production platforms.
Underlying measurement precision varies by segment; oncology CAR-T applications carry tighter precision than emerging cardiovascular indications due to established treatment site density and reimbursement pathways. Forecasts reflect assumptions regarding RMAT designation velocity, CMS reimbursement finalization, and allogeneic cell therapy substitution rates that could materially revise projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Canine Stem Cell Therapy Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
Stem Cell Reconstructive Market