
 NTRK Fusion Gene Positive Advanced Solid Tumor Market | 2026-2036
NTRK Fusion Gene Positive Advanced Solid Tumor Market Size, Share, and Industry Trends Forecast 2026-2036
NTRK Fusion Gene Positive Advanced Solid Tumor Market Analytics
The capability gap between large pharmaceutical developers and precision oncology specialists is collapsing as platform technologies commoditize kinase inhibitor discovery. Bayer AG leverages its radiopharmaceutical infrastructure to extend into targeted alpha-therapy combinations for NTRK-positive tumors. F. Hoffmann-La Roche Ltd anchors its position through integrated diagnostic-therapeutic workflows spanning tissue-based and liquid biopsy detection. Blueprint Medicines competes with differentiated resistance-profile coverage against secondary NTRK mutations.
NTRK fusion gene positive advanced solid tumors arise from chromosomal rearrangements involving neurotrophic tyrosine receptor kinase genes, producing constitutively active chimeric proteins that drive oncogenic signaling across histologically diverse malignancies including sarcoma, thyroid, lung, and colorectal cancers. Detection requires next-generation sequencing or fluorescence in situ hybridization platforms capable of identifying fusion partners across NTRK1, NTRK2, and NTRK3 loci. Targeted therapy dominates clinical value generation, with larotrectinib and entrectinib establishing efficacy benchmarks that reshape treatment sequencing across oncology practices. Specialty clinics represent the fastest-growing end-user channel, concentrating high-complexity molecular case review and clinical trial access for rare biomarker subsets.
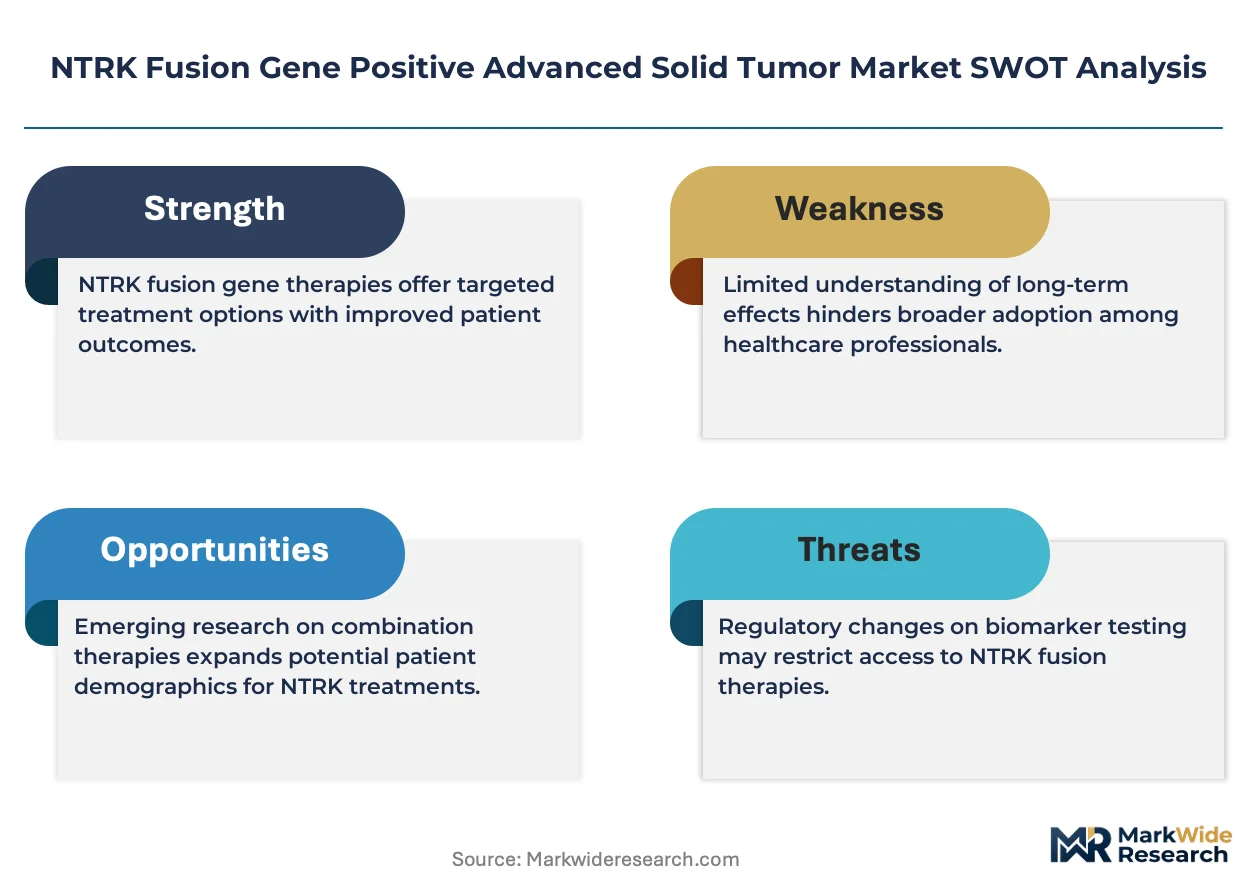
FDA tumor-agnostic approval frameworks and EMA's parallel scientific advice pathways shape development strategies for NTRK-directed agents, while companion diagnostic mandates from both regulators determine market access timelines. Payer evidence requirements for biomarker-driven therapies increasingly demand real-world outcome data linking genomic testing to treatment response and total cost of care. Stakeholders must monitor emerging resistance mechanisms and next-generation inhibitor development programs to anticipate shifts in treatment algorithms and competitive positioning.
Market Dynamics
FDA tumor-agnostic approval pathways and companion diagnostic mandates are compressing development timelines while fragmenting competitive positioning across kinase inhibitor developers.
Growth Catalysts
- Comprehensive Genomic Profiling Expansion:Academic medical centers in the United States are scaling next-generation sequencing infrastructure to identify rare fusion-positive subsets across histologically diverse malignancies.
- EMA Parallel Scientific Advice Pathways:European developers leverage coordinated regulatory feedback to align clinical trial designs with payer evidence requirements for biomarker-driven therapies.
- Liquid Biopsy Validation:Circulating tumor DNA platforms are achieving analytical validation thresholds that enable non-invasive NTRK fusion detection in patients with insufficient tissue.
Market Restraints
- Reference Laboratory Concentration:Molecular testing capacity concentrates among three national laboratory networks, creating single-point-of-failure risk for diagnostic access.
- Companion Diagnostic Synchronization:FDA-mandated co-development timelines extend market entry by 18-24 months for novel NTRK-directed agents.
- Resistance Mechanism Heterogeneity:Solvent-front and gatekeeper mutations require iterative inhibitor redesign, fragmenting addressable patient pools across resistance subtypes.
Strategic Opportunities
- Pediatric Oncology Integration:Infants and children with congenital NTRK fusion-driven tumors represent an underserved population with distinct regulatory and clinical trial pathways.
- Central Nervous System Penetration:Blood-brain barrier-permeable next-generation inhibitors address unmet need in leptomeningeal disease and primary brain metastases.
- Real-World Evidence Infrastructure:Flatiron Health and similar oncology data platforms enable post-market outcome tracking that satisfies payer requirements for continued coverage.
Industry Challenges
- Molecular Pathologist Workforce Constraints:Fusion interpretation requires specialized expertise that outstrips training program output across community hospital settings.
- Cross-Contamination in Tissue Processing:Low-prevalence biomarker testing demands stringent laboratory protocols to prevent false-positive calls from specimen mix-up.
- Prior Authorization Friction:Payer molecular testing policies create administrative burden that delays treatment initiation for symptomatic patients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NTRK Fusion Gene Positive Advanced Solid Tumor Market |
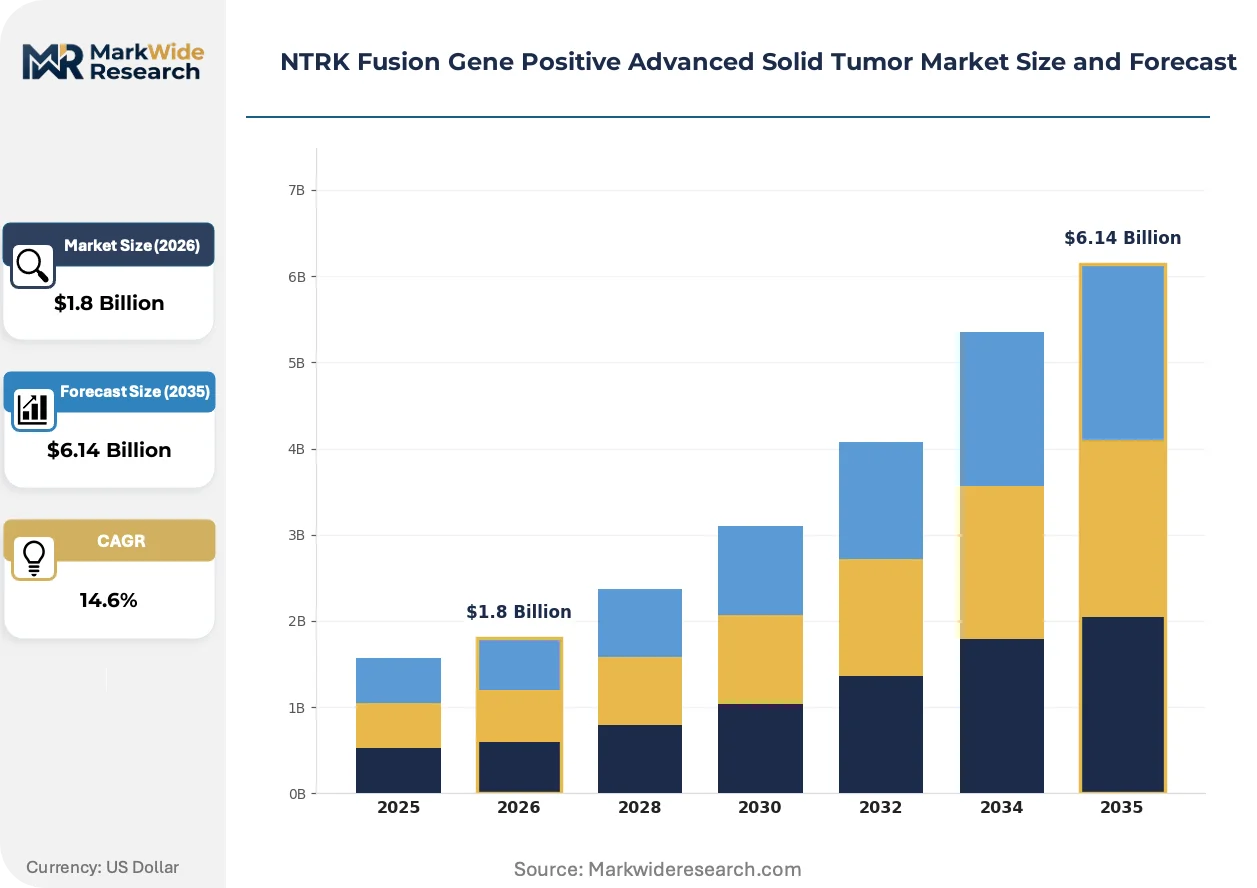
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Chemotherapy, Immunotherapy, Radiation Therapy End User: Oncologists, Hospitals, Research Institutions, Specialty Clinics Treatment Approach: Combination Therapy, Monotherapy, Neoadjuvant Treatment, Adjuvant Treatment Delivery Mode: Intravenous, Oral, Subcutaneous, Topical |
| Companies Covered | Bayer AG, F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Pfizer Inc., Bristol-Myers Squibb Company, Blueprint Medicines, NeoGenomics Laboratories, Inc., Empire Genomics, LLC, Plexxikon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NTRK Fusion Gene Positive Advanced Solid Tumor Market Evolving Landscape
Platform commodification in kinase inhibitor discovery is eroding traditional R&D moats while elevating diagnostic-therapeutic integration as the primary value capture mechanism.
Next-generation TRK inhibitors with differentiated resistance profiles are supplanting first-generation agents in clinical trial enrollment. Oncology investigators at major academic centers are prioritizing patients with acquired resistance mutations for protocol access. This substitution pattern is compressing the commercial runway of established therapies and accelerating portfolio renewal cycles across precision oncology developers.
EMA's expanded access frameworks and FDA's Project Orphan are converging to create accelerated assessment pathways for ultra-rare biomarker subsets. Developers now structure pivotal trials around histology-agnostic endpoints rather than organ-specific response criteria. Pediatric and young adult populations are capturing disproportionate regulatory attention given the congenital prevalence of NTRK fusions in infantile fibrosarcoma.
Specialty pharmacy distribution is consolidating patient access for oral targeted therapies under vertically integrated oncology networks. Community practices are ceding molecular case review and clinical trial referral to academic hub-and-spoke models. This channel restructuring concentrates treatment volume in United States metropolitan corridors with NCI-designated comprehensive cancer center density.
NTRK Fusion Gene Positive Advanced Solid Tumor Market Segmentation
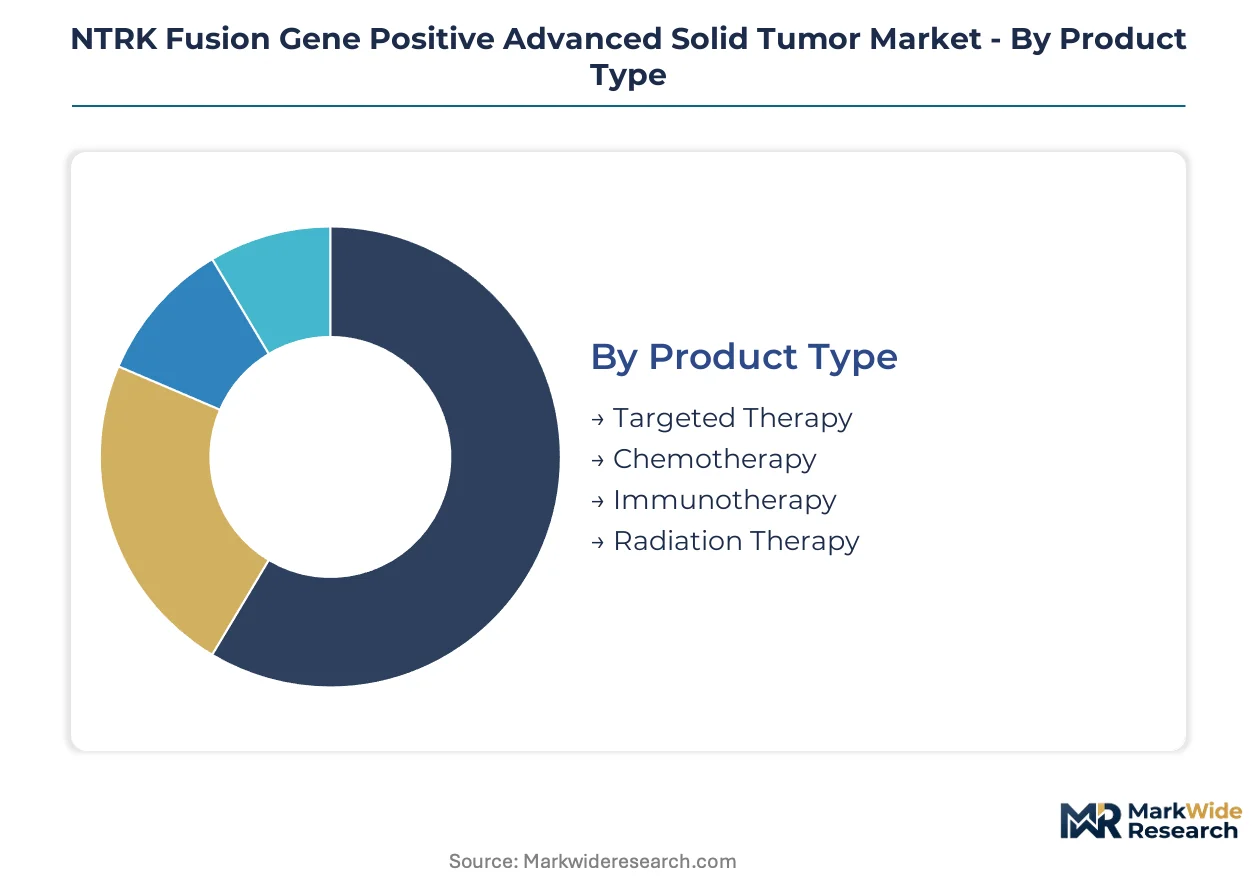
NTRK fusion-positive tumors span diverse histologies with heterogeneous treatment needs, requiring granular segmentation to match therapeutic modality with patient profile and care setting. Molecular complexity drives preference for targeted agents in first-line settings while resistance patterns shape sequencing decisions across subsequent lines of therapy.
Product Type:
Domestic consumption concentrates in oral targeted therapies within the United States, while intravenous formulations see stronger export-led demand into European and Asia-Pacific markets where infusion infrastructure dominates academic center workflows.
- Targeted Therapy:Small-molecule TRK inhibitors deliver tumor-agnostic efficacy across histologically diverse malignancies. United States academic medical centers drive demand through integrated diagnostic-therapeutic pathways that match fusion-positive patients to protocol enrollment.
- Chemotherapy:Cytotoxic regimens retain utility in NTRK fusion-positive subsets where targeted agent access is delayed or resistance has emerged. Community oncology practices in Germany and France maintain higher chemotherapy sequencing rates due to prior authorization friction for biomarker-directed therapies.
- Immunotherapy:Checkpoint inhibitors show limited single-agent activity in fusion-driven tumors but see combination exploration in academic trials.
- Radiation Therapy:External beam and stereotactic approaches address oligometastatic disease and palliative indications across care settings.
Targeted Therapy commands the established base. The steepest expansion runs through Immunotherapy combinations.
End User:
Cost tier stratification separates high-complexity molecular case review at academic hubs from community practice stabilization care, with reimbursement premiums concentrating in NCI-designated centers.
- Oncologists:Medical oncologists at academic centers coordinate multidisciplinary molecular tumor boards that determine treatment sequencing for fusion-positive patients. United States metropolitan corridors with comprehensive cancer center density capture disproportionate patient volume.
- Specialty Clinics:Precision oncology clinics concentrate next-generation sequencing infrastructure and clinical trial access for rare biomarker subsets. Pediatric specialty networks in Boston and Houston lead congenital NTRK fusion case volume.
- Hospitals:General hospital oncology departments handle stabilization and supportive care for advanced disease.
- Research Institutions:Academic medical centers conduct histology-agnostic pivotal trials under FDA tumor-agnostic frameworks.
Oncologists anchor the established base. Specialty clinics are gaining share fastest through hub-and-spoke referral consolidation.
Treatment Approach:
Application logic differentiates curative-intent neoadjuvant protocols from palliative monotherapy, with volume concentration in metastatic settings where fusion detection triggers targeted therapy prioritization.
- Monotherapy:Single-agent TRK inhibitors establish first-line standards across sarcoma, thyroid, and lung histologies. FDA tumor-agnostic approvals enable immediate targeted therapy initiation upon fusion confirmation without organ-specific protocol requirements.
- Combination Therapy:Rational combinations pair TRK inhibitors with chemotherapy or immunotherapy to address heterogeneous resistance mechanisms. Academic centers in the United Kingdom and Netherlands lead trial enrollment for acquired solvent-front mutation subsets.
- Neoadjuvant Treatment:Pre-surgical targeted therapy sees exploration in locally advanced sarcoma and colorectal primaries.
- Adjuvant Treatment:Post-surgical targeted consolidation remains investigational with limited regulatory precedent.
Monotherapy commands the established base. Combination Therapy is climbing the fastest through resistance-driven protocol expansion.
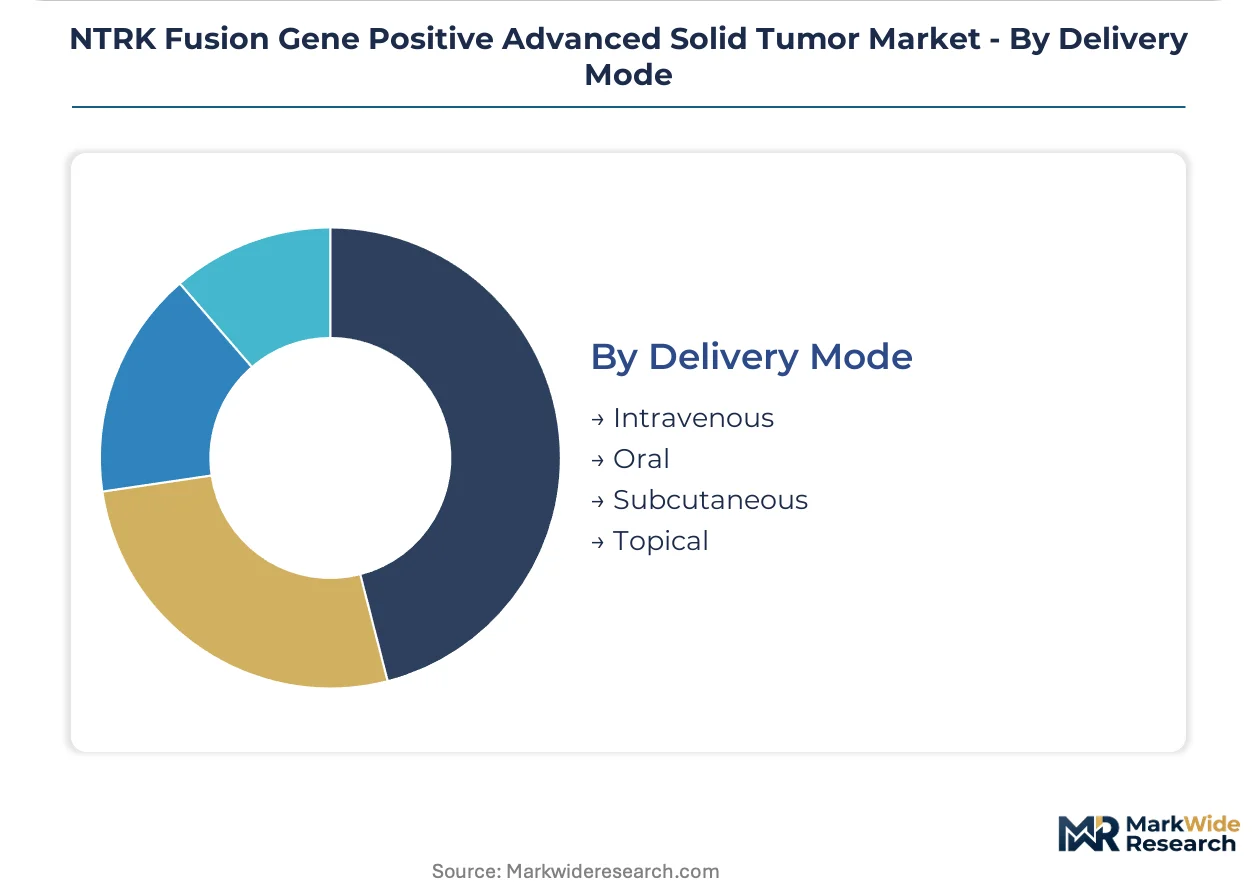
Delivery Mode:
Patient type stratification separates ambulatory oral administration from infusion-dependent hospitalized care, with convenience premiums driving preference shift toward self-administered regimens.
- Oral:Capsule formulations of TRK inhibitors enable outpatient management with reduced infusion center burden. United States specialty pharmacy networks consolidate distribution under vertically integrated oncology platforms that capture adherence data for payer reporting.
- Intravenous:Infusion delivery persists for combination regimens and patients with gastrointestinal intolerance of oral agents. German and French hospital outpatient departments maintain higher intravenous share due to centralized pharmacy compounding economics.
- Subcutaneous:Depot formulations see limited development for maintenance therapy indications.
- Topical:Localized delivery remains experimental for cutaneous metastatic deposits.
Oral formulations command the established base. Intravenous delivery retains stable share through combination therapy requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States payers accept premium pricing for comprehensive genomic testing and targeted therapies, while European health technology assessment bodies impose stricter cost-effectiveness thresholds that compress reimbursement rates for biomarker-directed treatments.
United States
FDA tumor-agnostic approval pathways and Medicare coverage for next-generation sequencing drive diagnostic-therapeutic integration at academic medical centers. The Centers for Medicare & Medicaid Services maintains favorable reimbursement for companion diagnostic testing. Boston, Houston, and New York metropolitan corridors concentrate NCI-designated comprehensive cancer centers that handle complex molecular case review and clinical trial enrollment.
Germany
Hospital outpatient departments maintain higher intravenous therapy share due to centralized pharmacy compounding economics and statutory health insurance fee schedules. The Federal Joint Committee (G-BA) applies early benefit assessment requirements that delay market access for novel targeted agents. Heidelberg and Munich academic hospital networks lead molecular tumor board infrastructure for rare fusion detection.
Japan
PMDA sakigake designation system accelerates review timelines for innovative oncology therapies addressing unmet medical need. The Ministry of Health, Labour and Welfare maintains national health insurance price listing processes that cap premium pricing duration. Tokyo and Osaka metropolitan medical centers concentrate liquid biopsy validation studies for circulating tumor DNA-based NTRK fusion detection.
United Kingdom
NICE technology appraisals impose cost-per-quality-adjusted-life-year thresholds that restrict access to high-price targeted therapies without substantial overall survival benefits. The NHS Genomic Medicine Service coordinates national testing infrastructure for rare biomarker identification. London and Manchester genomic laboratory hubs process tissue samples from regional cancer networks across England.
France
ANSM early access programs (ATU) enable pre-approval utilization for patients with life-threatening conditions and no therapeutic alternatives. HAS transparency committee assessments determine reimbursement levels based on clinical added value ratings. Paris and Lyon academic hospital clusters specialize in pediatric oncology protocols for congenital NTRK fusion-driven tumors.
NTRK Fusion Gene Positive Advanced Solid Tumor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in this precision oncology segment. Large pharmaceutical developers with integrated diagnostic-therapeutic platforms compete against specialized biotechnology firms with focused kinase inhibitor portfolios. Three archetypes dominate: diversified pharma conglomerates with radiopharmaceutical or diagnostic infrastructure, precision oncology specialists with resistance-profile differentiation, and reference laboratory networks with molecular testing scale. M&A activity concentrates on acquiring next-generation inhibitor programs, while strategic partnerships between drug developers and diagnostic firms accelerate companion diagnostic co-development timelines.
Within the diversified pharmaceutical tier, Bayer AG and F. Hoffmann-La Roche Ltd occupy positions defined by therapeutic modality breadth and diagnostic integration depth. Bayer leverages radiopharmaceutical infrastructure for targeted alpha-therapy combination approaches, while Roche anchors integrated tissue-based and liquid biopsy detection workflows. Among precision oncology specialists, Blueprint Medicines exemplifies the resistance-profile differentiation archetype with next-generation inhibitor development against solvent-front and gatekeeper mutations. These three companies represent distinct competitive vectors—therapeutic modality integration, diagnostic-therapeutic workflow control, and resistance mechanism coverage—that define strategic positioning in tumor-agnostic biomarker markets.
| Leading Market Players |
|---|
| Bayer AG |
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Blueprint Medicines |
| NeoGenomics Laboratories, Inc. |
| Empire Genomics, LLC |
| Plexxikon |
| Others |
Value Network & Pricing Analysis
FDA companion diagnostic mandates and EMA parallel scientific advice pathways gate both supply qualification timelines and price differentiation for NTRK-directed therapies, compressing development economics while stratifying reimbursement access across regulatory jurisdictions. Payer evidence requirements for biomarker-driven treatments simultaneously enforce cost-effectiveness thresholds and reward integrated diagnostic-therapeutic workflows, concentrating pricing power in vertically integrated platform developers.
Pricing Analysis
After-sales revenue from resistance monitoring services and longitudinal outcome tracking drives lifetime value capture for precision oncology developers. Value-based pricing models tether reimbursement to confirmed fusion detection and demonstrated response, with United States payers accepting premium positioning for tumor-agnostic approvals while European health technology assessment bodies enforce stricter cost-per-quality-adjusted-life-year thresholds. Price differentiation rests on companion diagnostic co-development status and real-world evidence infrastructure depth, with academic medical center networks showing lowest price sensitivity due to protocol-driven patient access imperatives and community oncology practices facing highest cost compression from prior authorization friction.
Supply Chain Analysis
Inbound logistics costs for temperature-sensitive biologics and radioactive isotopes concentrate supply chain risk on cold-chain integrity across trans-Pacific and trans-Atlantic trade lanes. Active pharmaceutical ingredient synthesis for kinase inhibitors centers on contract manufacturing organizations in Switzerland and Singapore, with diagnostic reagent production anchored in Massachusetts and California. Supply chain vulnerability stems from single-source dependency for rare isotope generation in nuclear reactors. Distribution runs through specialty pharmacy networks under vertically integrated oncology platforms that consolidate patient access and adherence monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market enters a cyclical recovery phase as next-generation inhibitor pipelines mature and resistance-driven substitution patterns renew therapeutic value capture. Patent cliff dynamics for first-generation TRK inhibitors compress incumbent revenue windows while creating acquisition opportunities for pipeline replenishment.
For Market Incumbents: Shield market position through backward integration into liquid biopsy platforms and captive companion diagnostic development, countering emerging entrant pressure from resistance-profile specialists. Prioritize CNS-penetrant formulation investment to differentiate against solvent-front mutation coverage gaps. Vertical control over circulating tumor DNA detection infrastructure secures patient identification upstream of treatment decisions. For New Entrants and Emerging Players: Lead with pediatric oncology indication strategies that exploit distinct regulatory pathways and congenital fusion prevalence in infantile fibrosarcoma. Target academic medical center hub-and-spoke networks in United States metropolitan corridors with highest NCI-designated comprehensive cancer center density. Go-to-market positioning should emphasize molecular pathologist education and interpretation support services to overcome workforce constraint barriers in community settings. For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical conglomerates divesting non-core oncology assets amid portfolio prioritization shifts toward immuno-oncology platforms. Long-term viability hinges on sustained biomarker testing expansion and iterative inhibitor development against heterogeneous resistance mechanisms. Watch for FDA breakthrough therapy designation signals in solvent-front mutation coverage as inflection indicators for next-generation asset valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA-mandated synchronization timelines compress market entry windows for novel TRK inhibitors. |
| Resistance-Profile Pipeline Expansion | Next-generation inhibitor programs against gatekeeper mutations displace first-generation commercial runways. |
| Liquid Biopsy Platform Integration | Circulating tumor DNA validation enables non-invasive fusion detection in tissue-insufficient patients. |
| Pediatric Oncology Protocol Development | Congenital NTRK fusion prevalence in infantile fibrosarcoma opens distinct regulatory and clinical trial pathways. |
| Real-World Evidence Infrastructure Buildout | Flatiron Health and similar platforms satisfy payer requirements for continued biomarker-driven therapy coverage. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient flow modeling and top-down revenue triangulation converged on segment-level estimates across the analysis window.
Variance decomposition across treatment line, dosage form, administration route, and regional regulatory cluster shaped the analytical framework. CAGRs derived from patient incidence projections, testing penetration curves, and therapy sequencing patterns. Forecast inputs incorporated companion diagnostic adoption rates and resistance mechanism emergence timelines.
The analysis sits within stated boundaries; outcomes outside sustained biomarker testing reimbursement, companion diagnostic regulatory harmonization, or next-generation inhibitor clinical success would require recalibration. Forecasts reflect documented assumptions regarding payer evidence requirements and molecular pathologist workforce expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Global Cell and Gene Therapy Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Drug Delivery in Cancer Market