
 Europe Gene Therapy Market | 2026-2036
Europe Gene Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gene Therapy Market Insights
Outcome-based reimbursement for single-administration gene therapies is consolidating how European payers contract for curative treatments. Novartis leverages its Zolgensma access framework to sustain long-term value demonstration across multiple European markets. Gilead Sciences anchors its position through specialized logistics networks for autologous CAR-T delivery. Orchard Therapeutics differentiates via deep expertise in lentiviral-based ex vivo therapies for rare metabolic conditions.
Gene therapy encompasses the introduction, removal, or modification of genetic material within a patient's cells to treat or prevent disease, typically employing viral vectors such as adenoviruses, lentiviruses, or retroviruses engineered to deliver therapeutic transgenes. These treatments target monogenic disorders, certain cancers, and degenerative conditions by correcting underlying disease mechanisms rather than managing symptoms. Adenoviruses and lentiviruses represent the dominant vector platforms, with lentiviral systems capturing significant development investment due to their stable genomic integration and efficacy in hematopoietic stem cell applications. Oncology commands the largest therapy area allocation, though neurological disorders represent the fastest-expanding segment as blood-brain barrier delivery technologies mature.
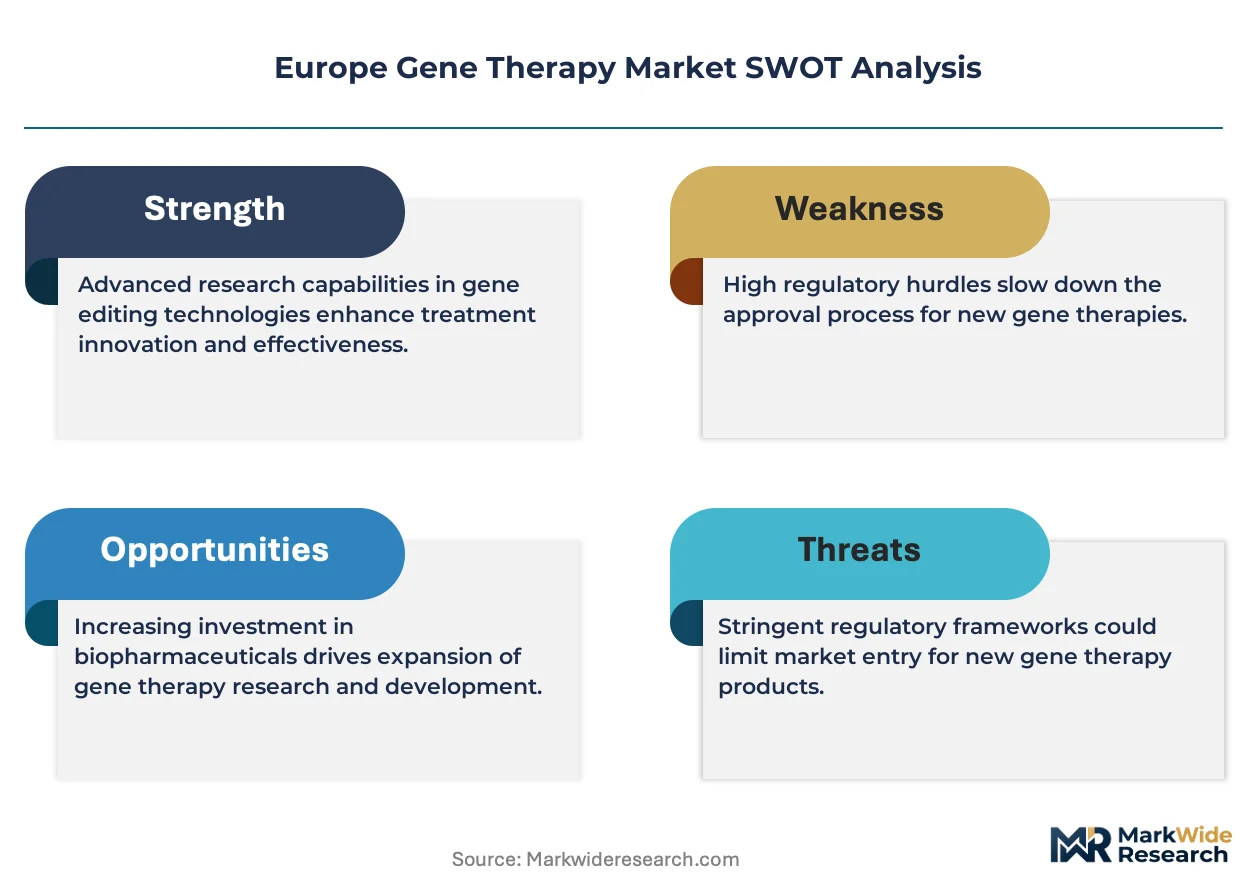
EMA's Committee for Advanced Therapies (CAT) and the EU's ATMP Regulation establish the centralized approval pathway for gene therapies across all member states, while national health technology assessment bodies like NICE in the United Kingdom and IQWiG in Germany determine reimbursement eligibility. The EU Clinical Trials Regulation harmonizes investigator-initiated and commercial study requirements, reducing regulatory fragmentation for multi-country protocols. Stakeholders must monitor evolving payer evidence requirements for long-term durability data and conditional reimbursement schemes tied to real-world performance tracking.
Market Dynamics
Outcome-based reimbursement contracts are compressing traditional pharmaceutical pricing models across European gene therapy markets, forcing manufacturers to demonstrate multi-year clinical durability before securing full payment.
Growth Catalysts
- ATMP Regulation:The EU's centralized approval pathway accelerates cross-border market access for advanced therapy medicinal products, eliminating redundant national reviews.
- Hematopoietic stem cell applications:Lentiviral vector platforms are capturing development investment due to stable genomic integration capabilities in ex vivo gene therapies.
- Germany:IQWiG's early benefit assessment framework creates predictable reimbursement timelines for innovative gene therapies entering the statutory health insurance system.
Market Restraints
- Plasmid DNA supply:Contract manufacturing concentration in select European biotech hubs creates single-source vulnerability for viral vector production inputs.
- Cold chain infrastructure:Autologous CAR-T therapies require liquid nitrogen storage at -150°C throughout logistics networks, limiting treatment center expansion.
- EMA conditional marketing authorization:Post-authorization evidence requirements extend commercial risk periods before full reimbursement commitment.
Strategic Opportunities
- Neurological disorders:Blood-brain barrier delivery technologies are opening addressable patient populations for previously untreatable CNS conditions.
- Adaptive pathways:EMA's rolling review mechanism compresses development timelines for therapies targeting unmet medical needs in rare diseases.
- United Kingdom:NICE's highly specialized technologies program offers premium pricing corridors for ultra-rare gene therapies meeting specific clinical criteria.
Industry Challenges
- Vector manufacturing scale-up:GMP-compliant suspension bioreactor operations require capital-intensive facility retrofits that strain mid-cap developer balance sheets.
- Real-world evidence systems:National registries lack harmonized data standards for tracking long-term patient outcomes across heterogeneous healthcare systems.
- Cross-border patient mobility:Referral center concentration in metropolitan clusters creates geographic access inequities for rural and eastern European populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gene Therapy Market |
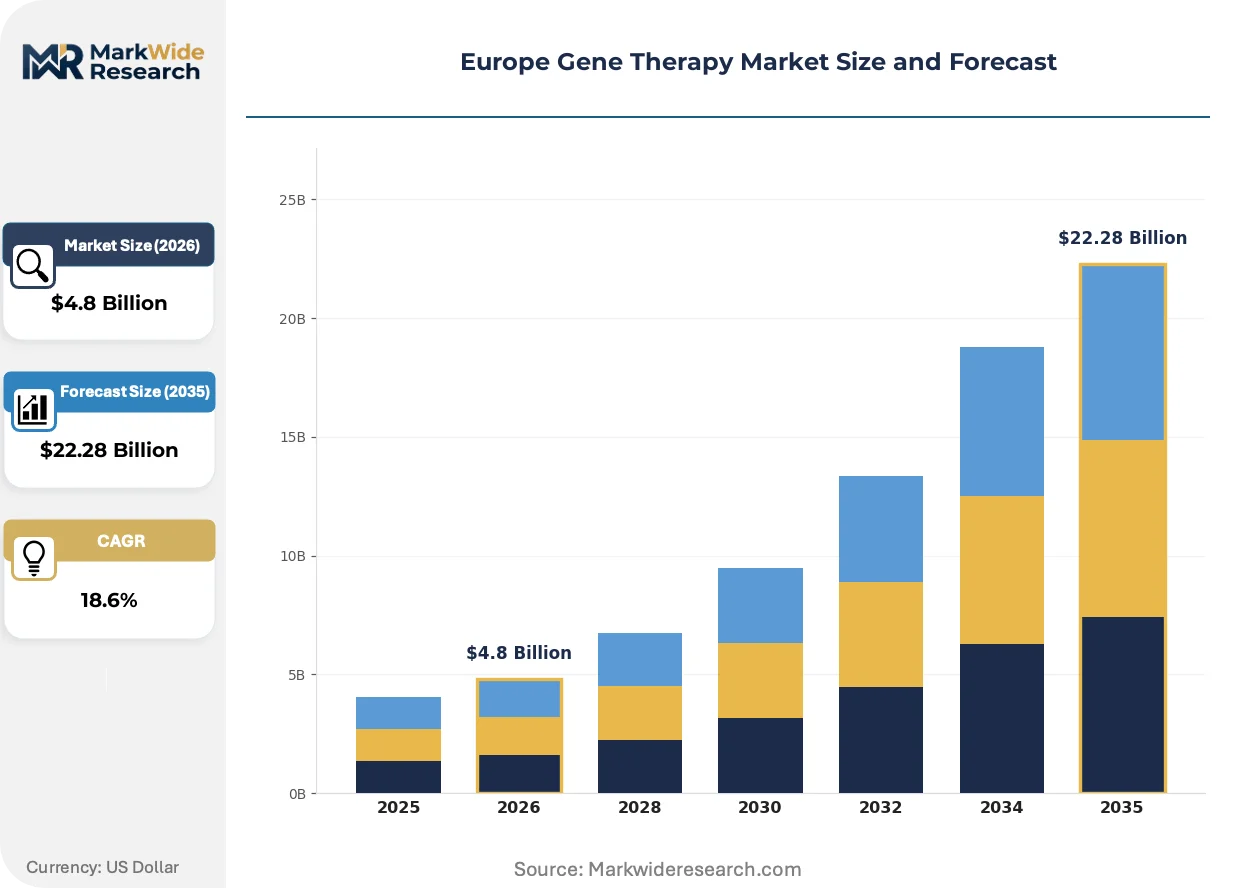
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adenoviruses, Retroviruses, Lentiviruses, Others Therapy Area: Oncology, Cardiovascular Diseases, Neurological Disorders, Genetic Disorders End User: Hospitals, Research Institutes, Clinics, Pharmaceutical Companies Delivery Method: In Vivo, Ex Vivo, Intravenous, Direct Injection |
| Companies Covered | Novartis, Gilead Sciences, Amgen, F. Hoffmann-La Roche, Orchard Therapeutics, BioMarin Pharmaceutical, PTC Therapeutics, Bristol-Myers Squibb, uniQure NV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gene Therapy Market Trends and Innovations
Vector engineering and manufacturing automation are compressing production costs while expanding treatable disease categories beyond hematologic conditions into solid tumors and neurodegenerative disorders.
Non-viral delivery systems incorporating lipid nanoparticles are overtaking traditional adenoviral platforms for in vivo gene editing applications. Academic medical centers in France and the Netherlands are adopting these systems for liver-directed therapies. The shift is enabling repeat dosing protocols previously impossible with immunogenic viral vectors.
EMA's Committee for Advanced Therapies has streamlined scientific advice procedures for gene therapy developers, reducing pre-submission consultation timelines. Manufacturers are leveraging this regulatory clarity to align pivotal trial designs with HTA evidence requirements. Germany and France have seen accelerated protocol approvals under the harmonized EU Clinical Trials Regulation.
Hospital pharmacy departments are consolidating gene therapy procurement through centralized tendering alliances rather than individual institutional contracts. University medical centers in Belgium and Sweden are pooling volume commitments to secure supply guarantees. This concentration is most visible in CAR-T therapies, where treatment center networks negotiate directly with manufacturers for multi-year delivery schedules.
Europe Gene Therapy Market Segmentation
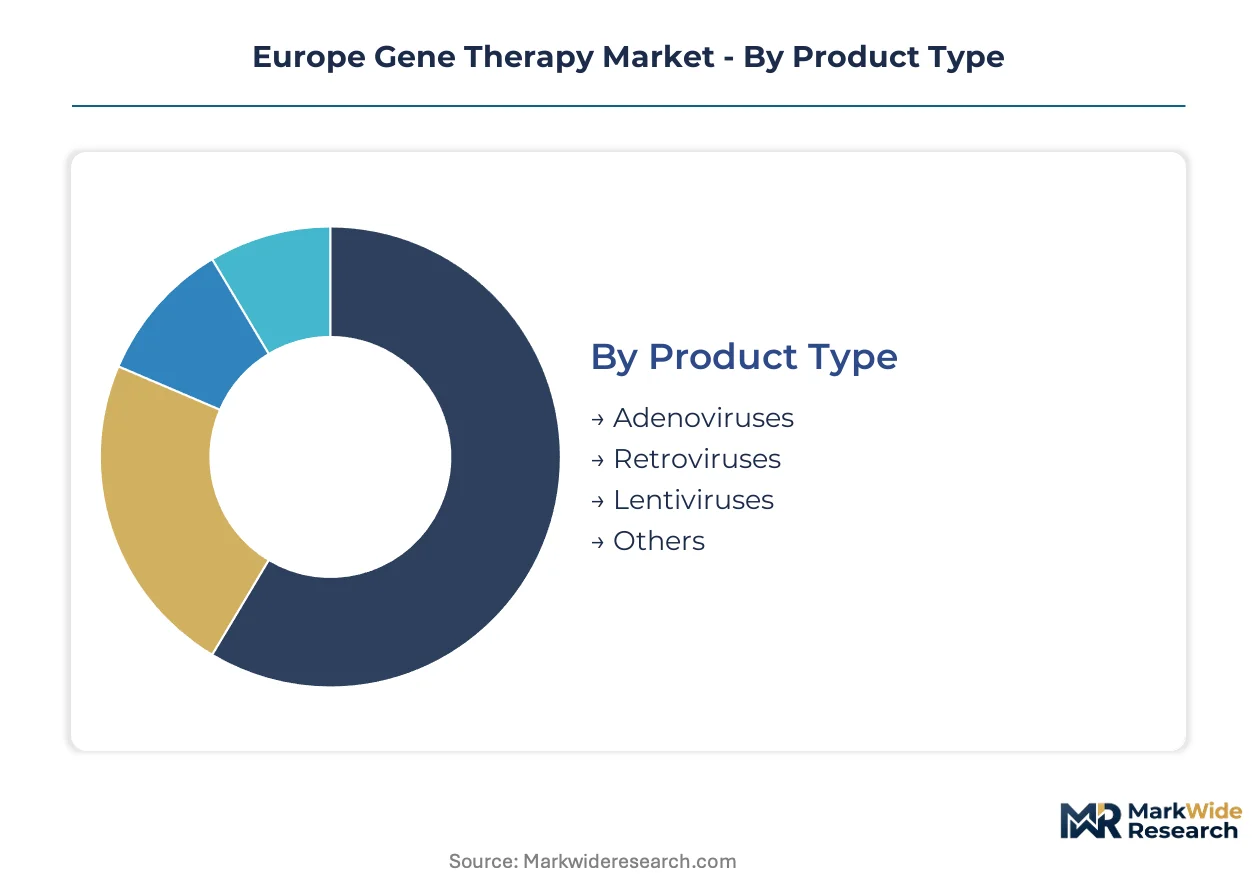
Gene therapy segmentation in Europe reflects the interplay between vector engineering capabilities, clinical delivery infrastructure, and regulatory approval pathways. Distinct technology platforms command different manufacturing investments and reimbursement negotiations across EMA member states.
Product Type:
Vector selection determines genomic integration stability, immunogenicity profile, and manufacturing scalability for commercial supply.
- Adenoviruses:These non-integrating vectors deliver transient transgene expression ideal for vaccine applications and certain cancer immunotherapies. German and French academic centers deploy adenoviral platforms for localized solid tumor treatments where durable expression is unnecessary.
- Lentiviruses:Stable genomic integration enables permanent correction in dividing and non-dividing cells alike. Ex vivo hematopoietic stem cell applications in the United Kingdom and Italy concentrate development investment here due to proven clinical durability in metabolic disorders.
- Retroviruses:Gamma-retroviral systems remain relevant for specific T-cell engineering protocols where insertional mutagenesis risks are managed through vector design.
- Others:AAV variants and engineered hybrid vectors address tissue-specific delivery challenges in ophthalmology and neurology programs.
Lentiviruses lead on scale; adenoviruses lead on momentum in oncology applications.
Therapy Area:
Clinical indication shapes trial design complexity, patient recruitment pools, and HTA evidence requirements for market access.
- Oncology:CAR-T and TCR-T cell therapies dominate hospital-based adoption, with specialized treatment centers in Germany and France managing complex logistics for autologous manufacturing.
- Neurological Disorders:Blood-brain barrier delivery advances are opening previously inaccessible patient populations for lysosomal storage diseases and neurodegenerative conditions.
- Genetic Disorders:Monogenic diseases with well-understood pathophysiology offer clearest regulatory pathways under EMA's adaptive frameworks.
- Cardiovascular Diseases:Angiogenic gene therapies and regenerative approaches target ischemic tissue repair through localized vector delivery.
Oncology leads on scale; neurological disorders are climbing the fastest as delivery technologies mature.
End User:
Institutional capabilities determine which settings can manage cold chain, cell processing, and patient monitoring requirements.
- Hospitals:University medical centers in Belgium, Sweden, and the Netherlands consolidate procurement through centralized tendering alliances for multi-year supply guarantees.
- Research Institutes:Academic medical centers in France and the Netherlands pioneer non-viral lipid nanoparticle systems for liver-directed in vivo editing protocols.
- Clinics:Specialized treatment networks in metropolitan clusters handle referral patients from rural and eastern European regions.
- Pharmaceutical Companies:Sponsors leverage EMA's Committee for Advanced Therapies scientific advice to align trial designs with HTA evidence requirements.
Hospitals lead on scale; research institutes lead on momentum in platform innovation.
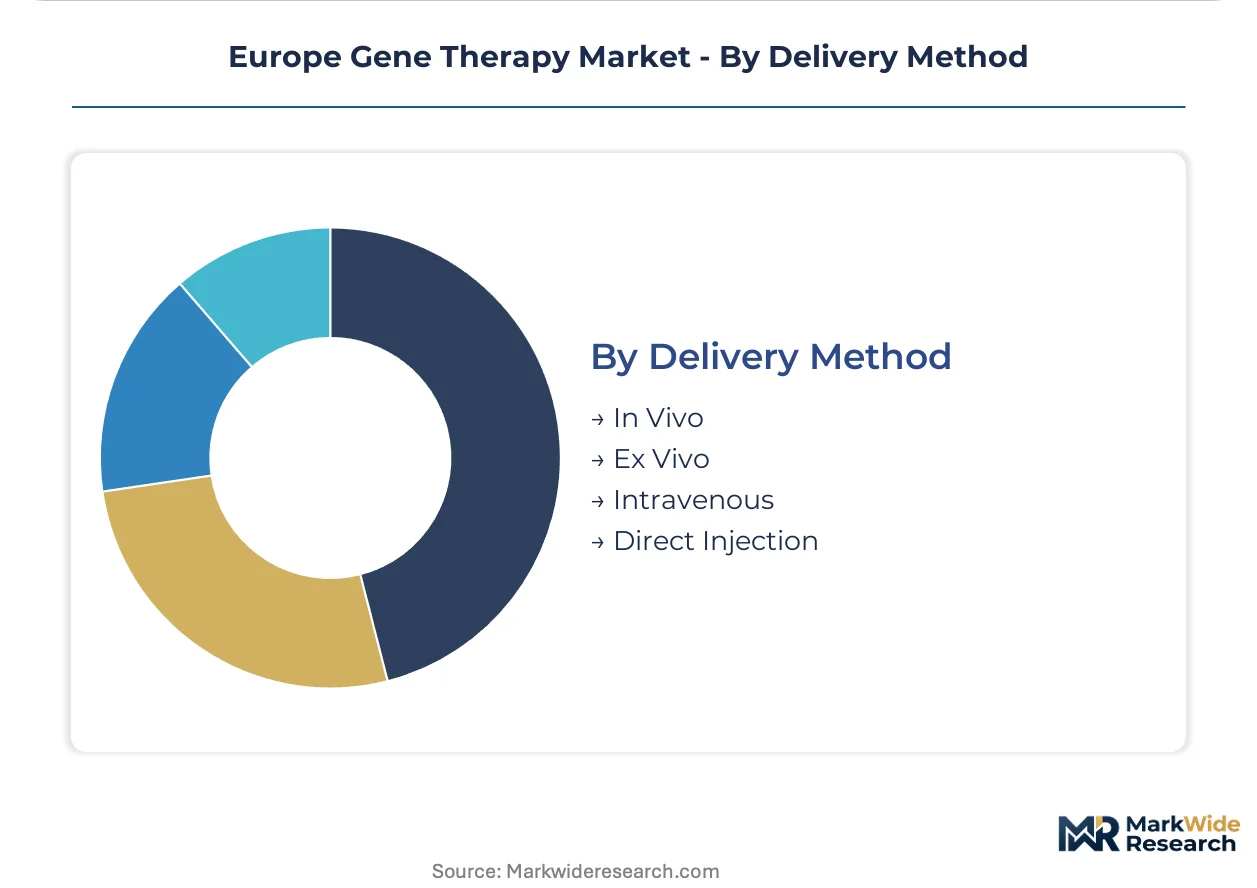
Delivery Method:
Administration route constrains treatable tissue types, dosing feasibility, and manufacturing format.
- Ex Vivo:Cell modification outside the patient enables precise quality control and expansion before reinfusion. Lentiviral transduction of hematopoietic stem cells commands significant European manufacturing investment.
- In Vivo:Direct vector administration to patients eliminates cell handling logistics but requires sophisticated targeting to avoid off-tissue expression.
- Intravenous:Systemic delivery suits liver-directed metabolic corrections and hematologic malignancies where circulating cells are the therapeutic target.
- Direct Injection:Localized administration into solid tumors, myocardium, or CNS structures demands specialized interventional capabilities available at concentrated referral centers.
Ex vivo leads on scale; in vivo is gaining share fastest as non-viral platforms enable repeat dosing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA's centralized approval pathway creates compliance-cost uniformity that prevents regulatory arbitrage, yet national reimbursement negotiations diverge sharply across member states. Production capacity concentrates where HTA frameworks offer predictable pricing corridors and specialized treatment infrastructure exists.
Germany
IQWiG's early benefit assessment framework anchors predictable reimbursement timelines for gene therapies entering statutory health insurance. The country's national pharmaceutical regulator mandates real-world evidence collection through disease registries that track long-term patient outcomes. Manufacturing clusters in Munich and Heidelberg host GMP-compliant suspension bioreactor facilities serving lentiviral vector production for ex vivo applications.
United Kingdom
NICE's highly specialized technologies program creates premium pricing corridors for ultra-rare gene therapies meeting specific clinical criteria. The national health technology assessment body requires multi-year durability data before full reimbursement commitment. London and Oxford academic medical centers pioneer non-viral lipid nanoparticle systems for liver-directed in vivo editing protocols.
France
ANSM's accelerated assessment procedures compress market access timelines for therapies targeting unmet medical needs in rare diseases. The national pharmaceutical regulator coordinates with HAS on conditional reimbursement schemes tied to real-world performance tracking. Paris and Lyon university hospitals consolidate CAR-T procurement through centralized tendering alliances for multi-year supply guarantees.
Italy
AIFA's managed entry agreements structure outcome-based contracts that link payment to demonstrated clinical durability over extended follow-up periods. The national pharmaceutical regulator permits regional variance in treatment center designation, creating access inequities between northern and southern regions. Milan and Rome specialized centers manage complex logistics for autologous cell processing and liquid nitrogen storage at -150°C.
Netherlands
Zorginstituut Nederland's budget impact thresholds force manufacturers to demonstrate cost-effectiveness within constrained healthcare spending envelopes. The national health technology assessment body emphasizes cross-border patient mobility solutions for ultra-rare conditions requiring concentrated expertise. Leiden and Utrecht research institutes advance blood-brain barrier delivery technologies for neurological gene therapy applications.
Europe Gene Therapy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates dominating commercialized therapies while CDMOs capture vector production scale. The market structure consolidates around therapy area expertise rather than geographic footprint, creating tiered competition between hematologic-oncology anchors and emerging neurology-focused entrants. Two strategic archetypes predominate: vector-integrated developers controlling manufacturing through captive supply, and platform-agnostic licensors accessing external production networks. Capacity expansion and outcome-based pricing partnerships constitute the dominant competitive moves as manufacturers secure long-term hospital contracts.
Within the integrated developer tier, Novartis and Gilead Sciences exemplify divergent approaches to European market access. Novartis leverages its Zolgensma access framework to sustain long-term value demonstration across multiple European markets. Gilead Sciences anchors its position through specialized logistics networks for autologous CAR-T delivery. Orchard Therapeutics occupies a distinct position among mid-cap specialists, representing deep expertise in lentiviral-based ex vivo therapies for rare metabolic conditions.
| Leading Market Players |
|---|
| Novartis |
| Gilead Sciences |
| Amgen |
| F. Hoffmann-La Roche |
| Orchard Therapeutics |
| BioMarin Pharmaceutical |
| PTC Therapeutics |
| Bristol-Myers Squibb |
| uniQure NV |
| Others |
Pricing and Supply Chain Analysis
Hospital pharmacy consortiums in Belgium, Sweden, and the Netherlands anchor outcome-based contracting for gene therapies, compressing manufacturer pricing power through multi-year durability commitments tied to real-world performance tracking.
Pricing Analysis
Capacity additions in Germany and the United Kingdom are reshaping price floors for lentiviral vector manufacturing as GMP-compliant suspension bioreactor facilities expand. Three-tier pricing structure across premium, standard, and economy levels separates novel ATMPs from follow-on indications and biosimilar-class therapies. Cost compression in autologous CAR-T is intensifying because centralized tendering alliances pool volume commitments across university medical centers. National health technology assessment bodies exhibit divergent price sensitivity, with NICE in the United Kingdom demanding deeper discounts than IQWiG in Germany for comparable clinical profiles.
Supply Chain Analysis
Dual-sourcing requirements mandated by EMA's ATMP framework compel manufacturers to qualify multiple plasmid DNA suppliers and viral vector production sites across European biotech hubs. Supply concentration in Belgium, the Netherlands, and Germany feeds from specialized CDMO networks for ex vivo cell processing and cryogenic logistics. Raw material dependencies on plasmid DNA, cell culture media, and liquid nitrogen storage systems create single-source vulnerability for autologous therapies. Tariff exposure on imported bioreactor equipment strains mid-cap developer balance sheets. Distribution runs through hospital-based treatment centers with -150°C cold chain infrastructure rather than traditional pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe gene therapy market functions as a regulatory compounder where EMA's adaptive pathways and centralized ATMP approval create predictable demand expansion for innovative treatments targeting rare diseases.
For Market Incumbents: Lock in long-term vector manufacturing capacity through captive supply agreements or strategic CDMO partnerships before competitor facility expansions in Germany and the United Kingdom saturate available GMP-compliant suspension bioreactor slots. Secure preferred provider status with hospital pharmacy consortiums in Belgium and Sweden through outcome-based contracts that demonstrate multi-year clinical durability. Vertical integration into plasmid DNA production mitigates single-source vulnerability as contract manufacturing concentration intensifies. For New Entrants and Emerging Players: Digital health platform partnerships offer the lowest-friction route to embed patient monitoring and real-world evidence collection capabilities required by conditional reimbursement schemes in France and Italy. Neurological disorders represent the most penetrable therapy area as blood-brain barrier delivery technologies mature and established players concentrate in hematologic oncology. Target academic medical centers in the Netherlands pioneering non-viral lipid nanoparticle systems for liver-directed in vivo editing protocols. For Investors and Strategic Acquirers: Large-cap pharmaceutical conglomerates with existing ATMP portfolios are the most active acquirers in this space, seeking vector-integrated developers with proven EMA regulatory pathways. Mid-cap specialists with deep expertise in lentiviral-based ex vivo therapies and established hospital contracts offer the strongest acquisition target profile across a five-to-ten year window. Watch for inflection in national registry harmonization efforts, as standardized long-term outcome tracking would unlock broader payer acceptance and compress commercial risk periods.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP-compliant suspension bioreactor expansion in Munich and Heidelberg secures lentiviral vector supply for ex vivo metabolic therapies. |
| Regulatory Approval Pathway | EMA's Committee for Advanced Therapies scientific advice alignment compresses pre-submission consultation timelines for pivotal trial designs. |
| Hospital System Partnership | Centralized tendering alliances in Paris and Lyon consolidate CAR-T procurement through multi-year volume commitments. |
| Pipeline Diversification | Blood-brain barrier delivery technology investment opens addressable patient populations for previously untreatable CNS conditions. |
| Reimbursement Strategy | Outcome-based contracts with IQWiG and NICE link payment to demonstrated clinical durability over extended follow-up periods. |
Research Methodology
Multiple input streams — regulatory submission databases, hospital procurement records, and CDMO capacity disclosures — were reconciled to construct market estimates for the Europe gene therapy market. Primary interviews with gene therapy development executives, regulatory affairs leads at EMA, hospital pharmacy procurement managers, and payer access specialists were cross-validated against secondary sources including EMA CAT opinions, ClinicalTrials.gov entries, and national HTA assessment reports. Bottom-up vector production capacity modeling and top-down therapy area demand aggregation were triangulated to ensure consistency.
Data-stream reconciliation across patient population epidemiology, treatment center capacity constraints, and reimbursement timeline assumptions informed the analytical framework across the projection horizon. Segmentation dimensions modeled include vector platform type, therapy area indication, delivery method, and national regulatory cluster. CAGRs were derived from fitted growth curves anchored to documented patient access volumes and announced manufacturing expansions. Forecast inputs incorporated EMA approval probability weightings and conditional marketing authorization conversion rates.
Regulatory pathway delays, manufacturing scale-up failures, and payer evidence requirement escalations are the dominant revision risks to the outlook. Deviation in EMA's willingness to grant full marketing authorization versus conditional pathways would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Oncolytic Virus Cancer Therapy Market