
 Cell Surface Markers Market | 2026-2036
Cell Surface Markers Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Surface Markers Market Intelligence
Software-as-a-service (SaaS) platforms for data analysis is repositioning the value proposition from simple reagent sales to integrated workflow solutions. Thermo Fisher Scientific Inc. leverages its extensive portfolio to offer comprehensive instrument-to-reagent-to-software packages. Becton, Dickinson and Company sustains its market leadership through deep expertise in flow cytometry instrumentation and associated antibody panels. Meanwhile, Bio-Rad Laboratories, Inc. competes on the strength of its specialized antibody and protein quantification tools.
Cell surface markers are proteins or glycoproteins, such as CD (Cluster of Differentiation) antigens, expressed on the outer membrane of cells. These markers function in cell signaling, adhesion, and interaction, serving as unique identifiers for specific cell types and states. Monoclonal antibodies represent the dominant product type due to their high specificity and reproducibility. Within applications, immunophenotyping for research and cancer diagnostics accounts for the largest share, while drug discovery applications show significant growth potential.
The development and clinical use of diagnostic assays are governed by bodies such as the US FDA and Europe's EMA. Compliance with Good Manufacturing Practice (GMP) and ISO 13485 standards is mandatory for reagents intended for clinical applications, influencing manufacturing costs. Navigating the transition from research-use-only (RUO) to in-vitro diagnostic (IVD) regulatory pathways remains a critical strategic decision for manufacturers.
Market Dynamics
The convergence of high-throughput analysis instrumentation with advanced data analytics software is the central force shaping the cell surface markers market. This shift moves the competitive basis from individual reagent performance to the value of integrated, data-centric workflow solutions.
Growth Catalysts
- Advancements in Cytometry:Mass cytometry and spectral flow cytometry technologies enable the simultaneous analysis of dozens of markers on a single cell, driving demand for larger, more complex antibody panels in immunology and oncology research.
- Expanding Diagnostic Applications:The use of immunophenotyping for diagnosing and monitoring hematological malignancies and immune disorders is becoming standard clinical practice, creating consistent demand from hospitals and diagnostic laboratories. -
- Government Research Funding:Sustained public investment in life sciences and cancer research, particularly through initiatives in the United States, Germany, and China, provides a stable funding source for academic labs that are primary consumers of cell surface markers.
Market Restraints
- High Cost of Clinical-Grade Reagents:The stringent requirements of Good Manufacturing Practice (GMP) significantly increase the production cost of monoclonal antibodies intended for IVD use, limiting adoption in cost-sensitive settings.
- Regulatory Pathway Complexity:Navigating the distinct regulatory requirements of the FDA and EMA for transitioning a marker from Research-Use-Only (RUO) to a clinically validated In-Vitro Diagnostic (IVD) product is a costly and time-intensive barrier for manufacturers.
- Data Interpretation Challenges:The massive, high-dimensional datasets generated by modern flow cytometry require specialized bioinformatics expertise to analyze and interpret, creating a bottleneck for research groups lacking computational resources or skilled personnel.
Strategic Opportunities
- Drug Discovery and Development:Using cell surface markers to identify target engagement, measure pharmacodynamic effects, and stratify patient populations in clinical trials presents a significant opportunity in the biopharmaceutical sector.
- Integrated Workflow Solutions:Developing and marketing complete systems that bundle instruments, validated antibody panels, and dedicated SaaS data analysis platforms offers a path to capture greater customer value and create sticky ecosystems.
- Companion Diagnostics Co-Development:Partnering with pharmaceutical companies to develop companion diagnostic assays based on specific cell surface markers can create a dedicated, high-value market for a reagent tied to a successful therapeutic.
Industry Challenges
- Reproducibility and Standardization:A lack of universally accepted standards for antibody validation and instrument setup leads to variability in results between laboratories, hindering the comparison of data and the clinical translation of research findings.
- Bioinformatics Talent Gap:A shortage of scientists with dual expertise in immunology and computational biology challenges organizations in fully leveraging the complex data generated from high-parameter cytometry experiments.
- Compliance and Certification Timelines:Achieving and maintaining ISO 13485 certification for manufacturing facilities is a resource-intensive process that can delay the entry of new diagnostic products into the market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Surface Markers Market |
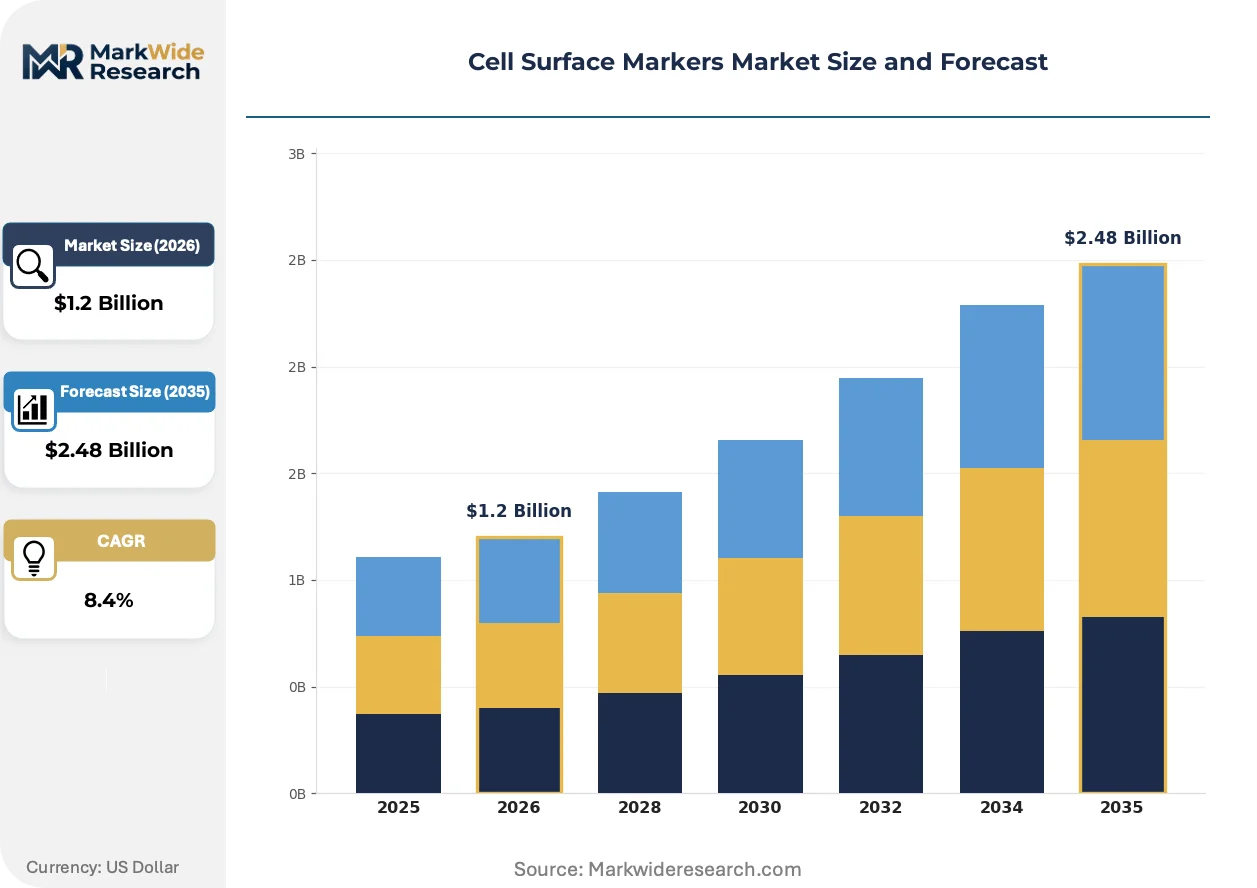
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Fluorochrome-Conjugated Antibodies, Recombinant Proteins Technology: Flow Cytometry, Immunohistochemistry, Western Blotting, ELISA, Mass Cytometry Application: Immunophenotyping, Cancer Diagnostics, Stem Cell Research, Infectious Disease Detection, Drug Discovery End User: Research Laboratories, Diagnostic Centers, Pharmaceutical Companies, Academic Institutions |
| Companies Covered | Thermo Fisher Scientific Inc., Becton, Dickinson and Company, Merck KGaA, Danaher Corporation, Bio-Rad Laboratories, Inc., Bio-Techne, Abcam plc, BioLegend, Miltenyi Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Surface Markers Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of hardware, software, and biological reagents into cohesive systems. This transition prioritizes data quality, reproducibility, and analytical efficiency over the performance of standalone components, fundamentally altering supplier-customer relationships.
Mass cytometry is a powerful technology that uses antibodies tagged with heavy metal isotopes for high-dimensional single-cell analysis. Major academic research centers and pharmaceutical R&D laboratories are the primary adopters for deep immune profiling. This technology is expanding into new applications such as monitoring patient responses in clinical trials and discovering novel biomarkers for complex diseases.
The European Union's In Vitro Diagnostic Regulation (IVDR) imposes significantly more stringent rules than its predecessor. This regulation demands more extensive clinical evidence and robust post-market surveillance for all diagnostic tests sold in the EU. Manufacturers of IVD-grade antibody panels are most affected, facing the need to re-validate products and update quality management systems to maintain their CE marking.
A clear behavioral shift from purchasing individual reagents to procuring complete workflow packages is evident. This model disrupts the traditional, fragmented sales approach by bundling instruments, validated consumables, and analytical software into a single offering. This trend is most prominent in large-scale biotechnology and pharmaceutical settings in North America and Europe, where operational efficiency and data integrity are paramount.
Cell Surface Markers Market Segmentation
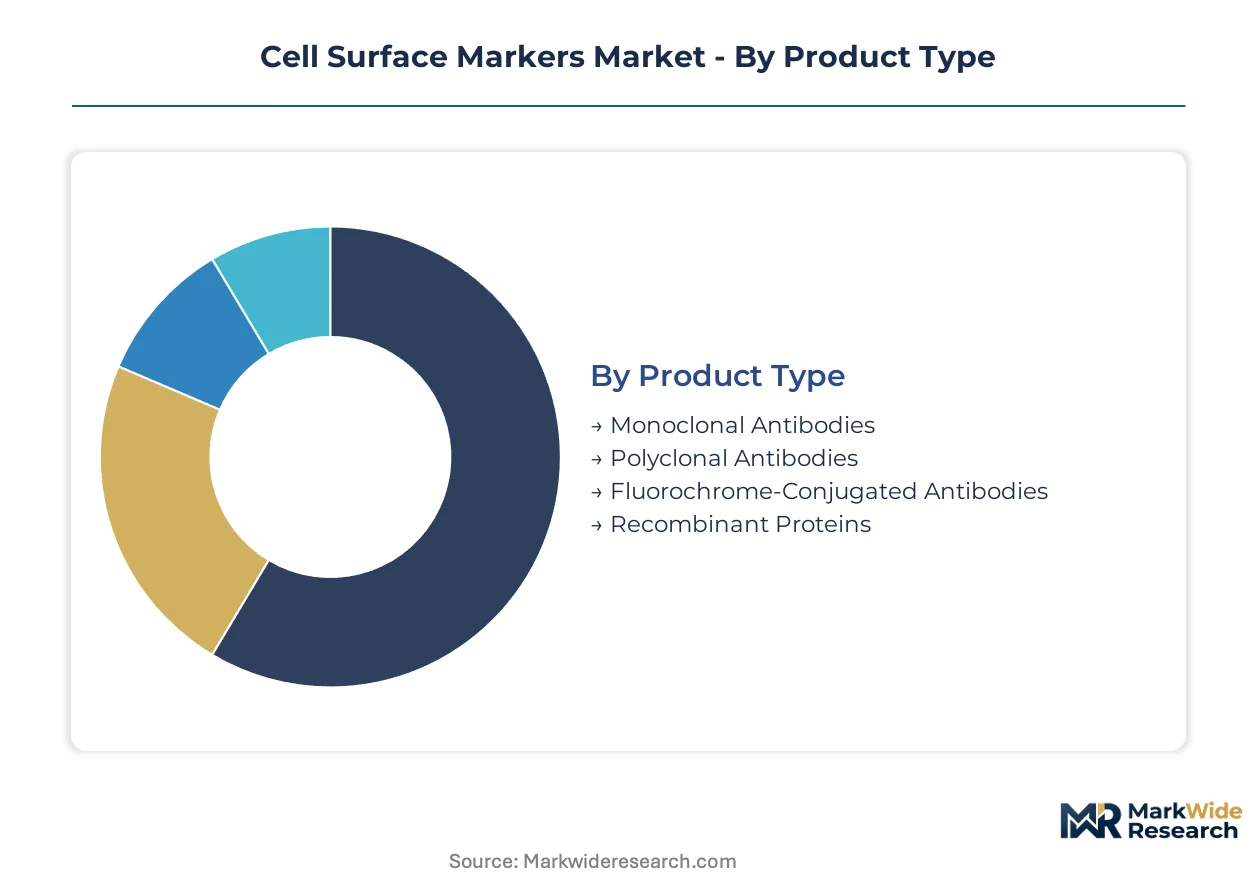
The cell surface markers market segments across product types, technologies, applications, and end-users, reflecting diverse research and clinical needs. Understanding these distinctions is critical for manufacturers to tailor offerings and navigate specific regulatory pathways. Each segment presents unique technical requirements and market dynamics.
Product Type:
Manufacturers of cell surface markers face varying regulatory burdens, with certain product types requiring stringent approvals from bodies like the US FDA and Europe's EMA for clinical use.
- Monoclonal Antibodies:These highly specific antibodies target single epitopes on cell surface markers, offering high reproducibility for both research-use-only (RUO) and in-vitro diagnostic (IVD) applications. Demand is concentrated in cancer diagnostics and immunophenotyping, where precise cell identification is paramount.
- Polyclonal Antibodies:Derived from multiple B cell clones, these antibodies recognize various epitopes on an antigen, providing broader target recognition for initial screening and research applications. Academic institutions frequently utilize polyclonal antibodies for exploratory studies.
- Fluorochrome-Conjugated Antibodies:These antibodies are chemically linked to fluorescent dyes, enabling detection and quantification of cell surface markers using flow cytometry and microscopy. Their demand is expanding within high-throughput analysis in pharmaceutical R&D and clinical research laboratories.
- Recombinant Proteins:Engineered proteins or protein fragments serve as highly specific antigens or detection reagents, offering batch-to-batch consistency and reduced animal-derived components. Biotechnology firms leverage recombinant proteins for novel assay development.
Monoclonal Antibodies sit at the top of the volume ranking, with Fluorochrome-Conjugated Antibodies climbing the fastest.
Technology:
The choice of technology directly correlates with the required analytical depth and throughput for cell population analysis in both research and diagnostic settings.
- Flow Cytometry:This established technology rapidly analyzes physical and chemical characteristics of cells as they pass through a laser beam, enabling multi-parameter analysis of cell populations. Diagnostic centers and research laboratories widely adopt flow cytometry for immunophenotyping and disease monitoring.
- Immunohistochemistry:A microscopy-based technique that uses antibodies to detect specific antigens in tissue sections, providing spatial information on marker expression within cellular contexts. Pathology laboratories utilize immunohistochemistry for cancer diagnosis and prognosis.
- Western Blotting:This laboratory technique separates proteins by size and detects specific proteins using antibodies, primarily used for protein identification and quantification in research. Academic research groups employ Western Blotting for protein expression studies.
- ELISA:Enzyme-linked immunosorbent assay is a plate-based assay technique designed for detecting and quantifying soluble substances such as peptides, proteins, antibodies, and hormones. Pharmaceutical companies use ELISA for drug screening and biomarker validation.
- Mass Cytometry:A cutting-edge technology that uses antibodies tagged with heavy metal isotopes for high-dimensional single-cell analysis, overcoming limitations of spectral overlap in fluorescence-based methods. Pharmaceutical R&D laboratories and major academic research centers in the United States are primary adopters for deep immune profiling.
Flow Cytometry maintains broad market penetration, while Mass Cytometry shows rapid adoption in specialized research.
Application:
The diverse applications of cell surface markers span from fundamental biological understanding to critical clinical decision-making, influencing demand patterns across different user segments.
- Immunophenotyping:This application involves identifying and quantifying different cell populations based on their cell surface marker expression, crucial for diagnosing hematological malignancies and immune disorders. Hospitals and diagnostic laboratories routinely perform immunophenotyping.
- Cancer Diagnostics:Cell surface markers serve as biomarkers for cancer detection, classification, and monitoring treatment response, enabling personalized oncology approaches. Diagnostic centers and oncology clinics rely on these markers for precise tumor characterization.
- Stem Cell Research:Specific cell surface markers identify and isolate various stem cell populations, facilitating studies on regenerative medicine and developmental biology. Research laboratories actively use markers for stem cell differentiation tracking.
- Infectious Disease Detection:Markers on immune cells or pathogens aid in diagnosing infectious diseases and monitoring immune responses, contributing to public health surveillance. Clinical microbiology laboratories utilize these markers for pathogen identification.
- Drug Discovery:Cell surface markers are employed to identify novel drug targets, screen therapeutic compounds, and assess drug efficacy and toxicity in preclinical and clinical development. Biopharmaceutical companies integrate markers into their drug development pipelines.
Immunophenotyping represents the largest application segment, with Drug Discovery applications exhibiting substantial growth potential.
End User:
End-user segments are differentiated by their operational scale, research focus, and primary funding sources, influencing their procurement strategies and demand for integrated solutions.
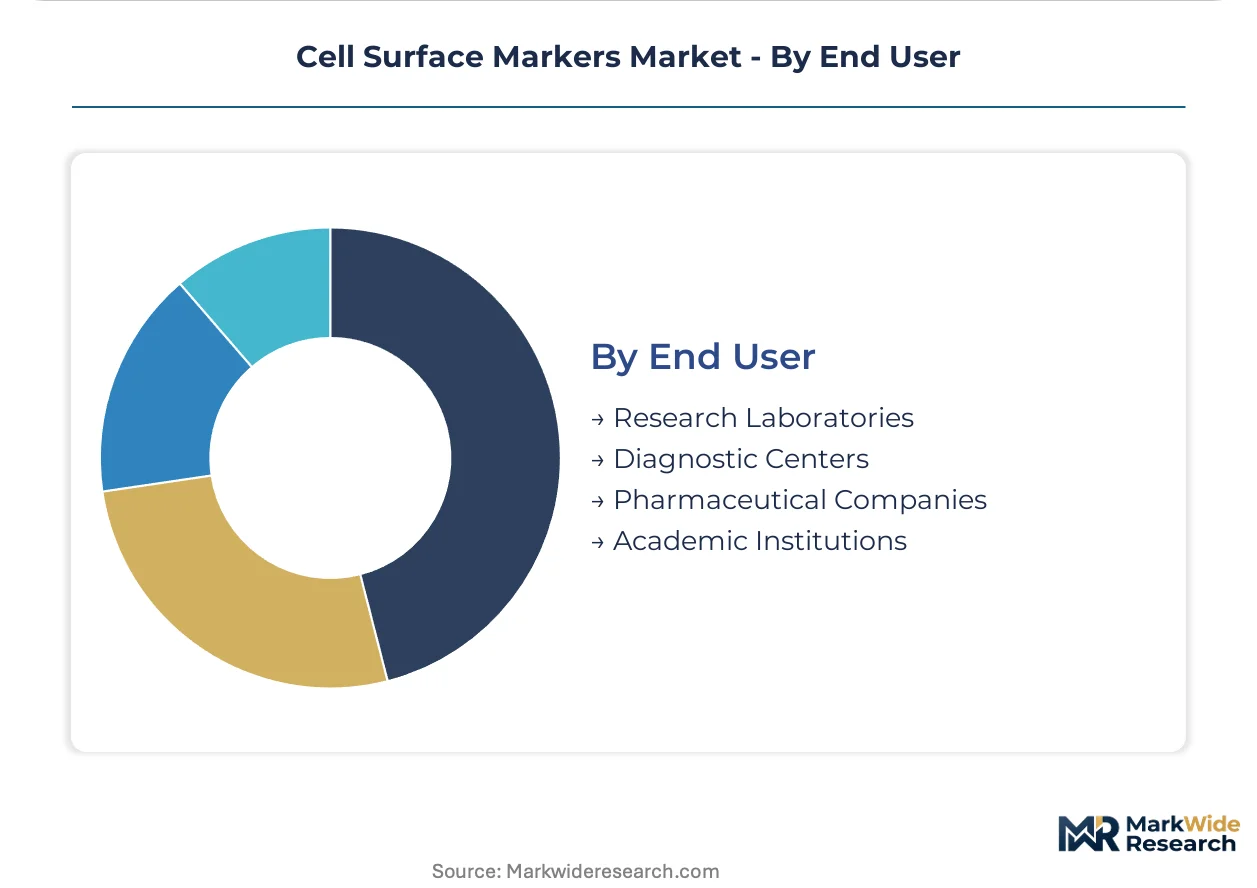
- Research Laboratories:These include academic labs, government research institutions, and contract research organizations focused on basic and translational science. They are primary consumers of research-use-only reagents and advanced analytical platforms.
- Diagnostic Centers:Clinical laboratories and reference labs perform routine and specialized diagnostic tests for patient care, requiring IVD-grade reagents and validated assays. These centers prioritize regulatory compliance and assay standardization.
- Pharmaceutical Companies:Biopharmaceutical firms leverage cell surface markers for drug discovery, target validation, preclinical testing, and clinical trial monitoring. Their demand often involves high-throughput screening and companion diagnostic co-development.
- Academic Institutions:Universities and colleges conduct fundamental research in immunology, cell biology, and oncology, often funded by government grants. They drive demand for innovative technologies and specialized antibody panels.
Research Laboratories constitute a foundational demand base, while Pharmaceutical Companies are increasingly driving advanced marker development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The stringent regulatory pathways for in-vitro diagnostic (IVD) products in some regions are causing manufacturers to strategically evaluate their production and market entry points. This regulatory arbitrage influences where clinical-grade reagents are developed and manufactured. Compliance with diverse national and supranational standards drives regional investment in specialized production facilities.
United States
Demand for advanced cell surface markers is high due to extensive pharmaceutical R&D and a robust academic research ecosystem. The US FDA's rigorous approval process for IVD products drives significant investment in clinical trial infrastructure. Biotech clusters in Boston and San Francisco lead innovation in high-parameter cytometry and biomarker discovery.
Germany
German research institutions and diagnostic laboratories are major consumers of cell surface markers, particularly for cancer diagnostics and immunology studies. The European Medicines Agency (EMA) and the In Vitro Diagnostic Regulation (IVDR) significantly impact product development and market access. Munich and Berlin host prominent biotechnology hubs, fostering collaborations between industry and academia.
China
Rapid expansion in cancer diagnostic applications and government-backed life science initiatives are fueling demand for cell surface markers. China's NMPA oversees the approval of medical devices and diagnostics, influencing local manufacturing standards. Major research parks in Shanghai and Beijing are attracting significant investment in advanced biological research.
Japan
Japanese biopharmaceutical companies and academic centers prioritize precision medicine and advanced cellular therapies, driving demand for highly specific cell surface markers. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates medical devices and IVDs, ensuring product quality and safety. Tokyo and Osaka are key centers for biomedical research and development activities.
United Kingdom
The UK's strong academic base in immunology and oncology research creates consistent demand for cell surface markers for exploratory studies. The Medicines and Healthcare products Regulatory Agency (MHRA) sets standards for medical devices and diagnostics within the UK market. The Cambridge biomedical campus and London's biotech sector are central to research innovation.
Cell Surface Markers Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a dynamic market structure. The cell surface markers market exhibits a tiered competitive landscape, with established players alongside specialized innovators. Strategic partnerships and portfolio diversification are dominant competitive moves in this sector.
Within the integrated workflow solutions tier, Thermo Fisher Scientific Inc. and Becton, Dickinson and Company represent market leaders leveraging extensive instrument and reagent portfolios. Bio-Rad Laboratories, Inc. occupies a strong position through its specialized antibody and protein quantification tools. These companies anchor the market through comprehensive offerings that span research to clinical applications, prioritizing data quality and analytical efficiency for end-users.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Becton, Dickinson and Company |
| Merck KGaA |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Bio-Techne |
| Abcam plc |
| BioLegend |
| Miltenyi Biotec |
| Others |
Cost & Logistics Intelligence
Vertical integration into comprehensive workflow solutions anchors supplier market positions, enabling pricing power through bundled offerings and data analysis platforms. This strategy captures greater customer value.
Pricing Analysis
Distributor margins often influence the final cost of cell surface markers to end-users. Value-based pricing dominates integrated workflow solutions, while transactional pricing applies to individual reagents. Price differentiation stems from certification level, such as US FDA or Europe's EMA compliance for IVD products, and comprehensive after-sales software support. Pricing pressure stems from the high cost of clinical-grade reagents due to stringent Good Manufacturing Practice requirements, making academic institutions more price-sensitive than pharmaceutical companies, which prioritize validated performance.
Supply Chain Analysis
Specialized scientific workforce availability in the United States, Germany, and China underpins cell surface marker manufacturing. Supply concentration for advanced antibody production and fluorochrome conjugation centers in these regions, which also source highly purified antibodies and fluorescent dyes as key inputs. Regulatory restriction for in-vitro diagnostic-grade product approval presents a structural risk. Distribution primarily occurs through a combination of direct sales from major manufacturers and specialized laboratory distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell surface markers market presents a late-cycle quality story, driven by a demand shift towards premium, integrated workflow solutions. End-users now prioritize data quality and reproducibility over standalone component performance.
For Market Incumbents: Deploy vertical integration to deepen control over instrument-to-reagent-to-software packages. Acquire specialized bioinformatics firms to address the data interpretation bottleneck and enhance integrated workflow solutions. Expand IVD-grade manufacturing capacity and invest in ISO 13485 certification to navigate regulatory pathway complexity. This secures market share against emerging niche players.
For New Entrants and Emerging Players: Online marketplaces offer a direct route to academic institutions, a penetrable segment for research-use-only reagents. Target white-space opportunities in niche antibody panels for emerging biomarkers or specialized software for high-parameter cytometry data analysis. A go-to-market angle focused on open-source data analysis tool integration can attract computationally savvy researchers.
For Investors and Strategic Acquirers: Roll-up economics work for specialized reagent manufacturers because of market fragmentation in niche antibody panels. The market demonstrates long-term viability, driven by sustained demand from cancer diagnostics and drug discovery applications. Target acquisition archetypes include bioinformatics startups and developers of novel, high-specificity antibody panels. Increased pharmaceutical-academic collaborations for biomarker discovery is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand IVD Product Portfolio | Meets clinical demand for validated diagnostic assays, strengthening market position. |
| Develop Integrated Workflow Platforms | Bundles instruments, reagents, and software, creating sticky ecosystems for end-users. |
| Partner for Companion Diagnostics | Secures high-value, dedicated markets tied to successful therapeutic drugs. |
| Invest in Mass Cytometry R&D | Leverages advanced technology for high-dimensional single-cell analysis in oncology. |
| Acquire Bioinformatics Expertise | Addresses data interpretation challenges, enhancing value proposition for complex datasets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to inform this analysis. Primary interviews with R&D directors, diagnostic lab managers, academic researchers, and regulatory affairs specialists provided granular insights. Secondary validation drew from US FDA filings, Europe's EMA submissions, scientific publications, and company annual reports. Bottom-up and top-down triangulation ensured robust data consistency.
Historical market performance data anchored the forecast window, providing a robust baseline for future projections. The analytical framework modeled segmentation across product type, technology, application, end-user, and regulatory compliance level. Compound annual growth rates were derived using regression analysis across the analysis window. New diagnostic assay approvals and pharmaceutical R&D spending served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for mass cytometry would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and R&D investment. Unforeseen regulatory changes or major breakthroughs in alternative diagnostic methods represent risk factors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Vanishing Bone Disease Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Global Hormone Refractory Breast Cancer Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Global Mrna Vaccine Market