
 RNA Interference (Rnai) Drug Delivery Market | 2026-2036
RNA Interference (Rnai) Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
RNA Interference (Rnai) Drug Delivery Market Intelligence
The gap between validated liposomal platforms and experimental viral vector systems is realigning procurement decisions across the RNAi drug delivery landscape. Alnylam Pharmaceuticals anchors its position through proprietary N-acetylgalactosamine conjugate chemistry that enables liver-targeted siRNA delivery. Arrowhead Pharmaceuticals leverages a modular TRiM platform to sustain pipeline breadth across multiple therapeutic areas.
RNA interference drug delivery encompasses the engineered transport of small interfering RNA, microRNA, or antisense oligonucleotides into target cells using lipid nanoparticles, polymer complexes, or conjugated carriers, typically requiring particle sizes below 100 nanometers for optimal cellular uptake and endosomal escape. Its primary purpose is to achieve sequence-specific gene silencing for therapeutic intervention in previously undruggable disease pathways. Liposomal formulations dominate current revenue streams due to their established manufacturing scalability and regulatory familiarity. Nanoparticle platforms represent the fastest-expanding segment as next-generation ionizable lipids improve tissue specificity beyond hepatocyte targets. Chemical modifications retain critical importance for metabolic stability, though margin pools increasingly shift toward formulation innovation rather than backbone chemistry alone.
The FDA maintains stringent chemistry, manufacturing, and controls requirements for RNAi therapeutics through its Office of Therapeutic Biologics and Advanced Therapies, while the EMA adapts its ATMP framework to address exon-skipping and gene-silencing modalities entering European markets. REACH compliance for novel lipid excipients adds complexity to supply qualification for companies seeking dual-market access. Stakeholders must track how evolving FDA guidance on immunogenicity assessment and emerging EMA real-world evidence expectations will reshape clinical development timelines and post-market surveillance obligations.
Market Dynamics
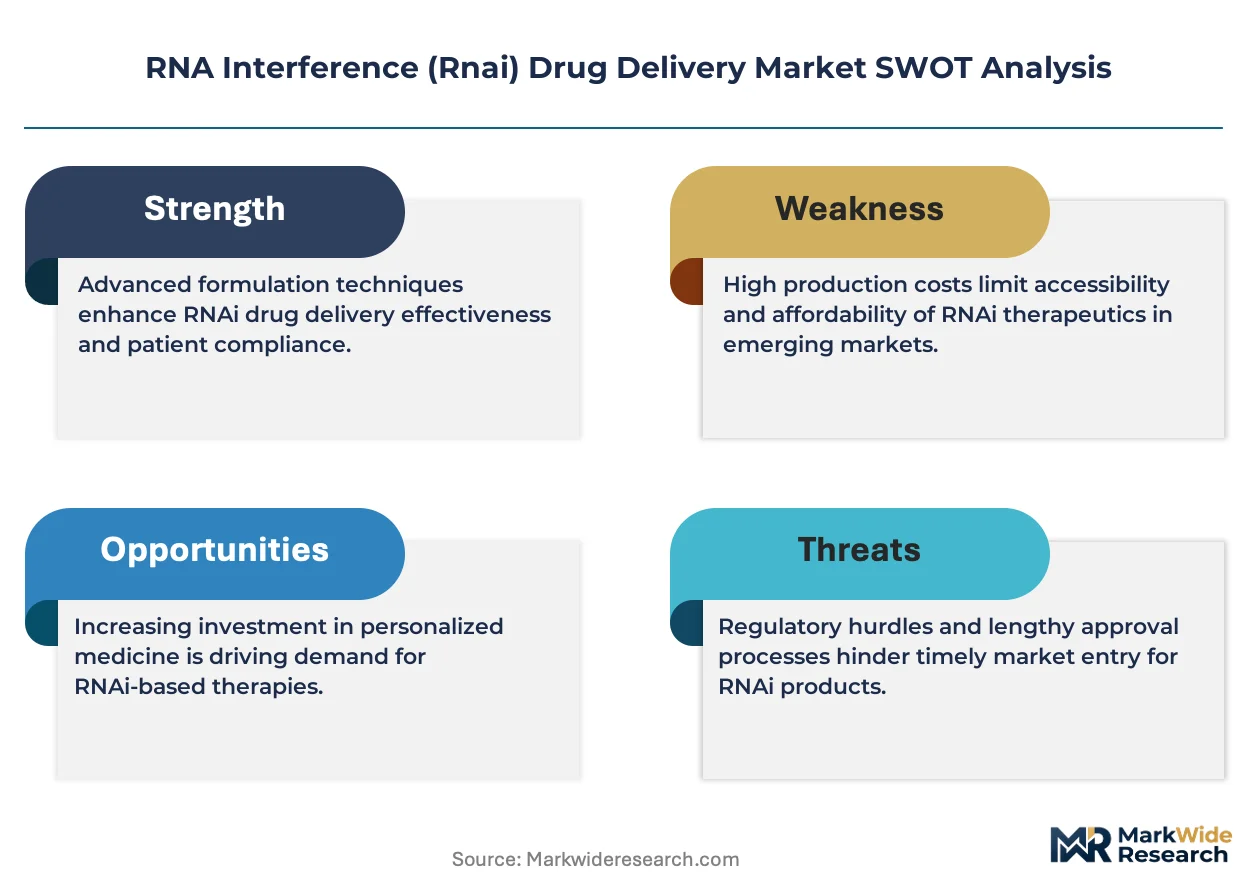
Ionizable lipid chemistry is redefining tissue specificity boundaries, pulling investment away from legacy hepatocyte-constrained platforms toward extrahepatic targets. This molecular engineering pivot is compressing development timelines for neurology and oncology applications while fragmenting incumbent supplier relationships.
Growth Catalysts
- EMA Adaptive Pathways:The European Medicines Agency's accelerated assessment framework for advanced therapy medicinal products is shortening regulatory timelines for RNAi candidates addressing rare genetic disorders.
- Oncology End-Use Expansion:Solid tumor penetration is driving demand for tumor-penetrating peptide conjugates that enable siRNA accumulation in hypoxic microenvironments beyond vascularized tissues.
- Polymeric Excipient Innovation:Biodegradable poly(beta-amino ester) formulations are expanding stability windows for temperature-sensitive RNA payloads in tropical distribution corridors.
Market Restraints
- Specialized Lipid Input Concentration:Ionizable lipid production concentrates among contract manufacturers in Switzerland and Massachusetts, creating single-source vulnerability for dual-market filings.
- Endosomal Escape Limitation:Current lipid nanoparticle architectures achieve sub-5% cytosolic release efficiency, forcing dose escalation that inflames manufacturing scale-up costs.
- REACH Compliance Friction:European Chemicals Agency registration requirements for novel lipid excipients add 18-24 months to supply qualification timelines for EU market entry.
Strategic Opportunities
- Central Nervous System Delivery:Blood-brain barrier-penetrating exosome formulations open addressable space for Huntington's and Alzheimer's applications previously excluded from RNAi intervention.
- India Manufacturing Localization:The country's production-linked incentive scheme for pharmaceuticals is attracting lipid nanoparticle contract development and manufacturing organizations to serve Asian markets.
- Antibody-siRNA Conjugate Convergence:Bifunctional biologics combining monoclonal antibody targeting with RNAi payloads are creating new modality categories in immuno-oncology.
Industry Challenges
- Formulation Science Talent Scarcity:Lipid nanoparticle optimization requires rare cross-training in colloid chemistry and nucleic acid biochemistry, constraining pipeline expansion at mid-cap developers.
- GMP Facility Retrofit Intensity:Existing biologics manufacturing suites require containment upgrades for potent siRNA handling, demanding capital deployment that strains development-stage balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RNA Interference (Rnai) Drug Delivery Market |
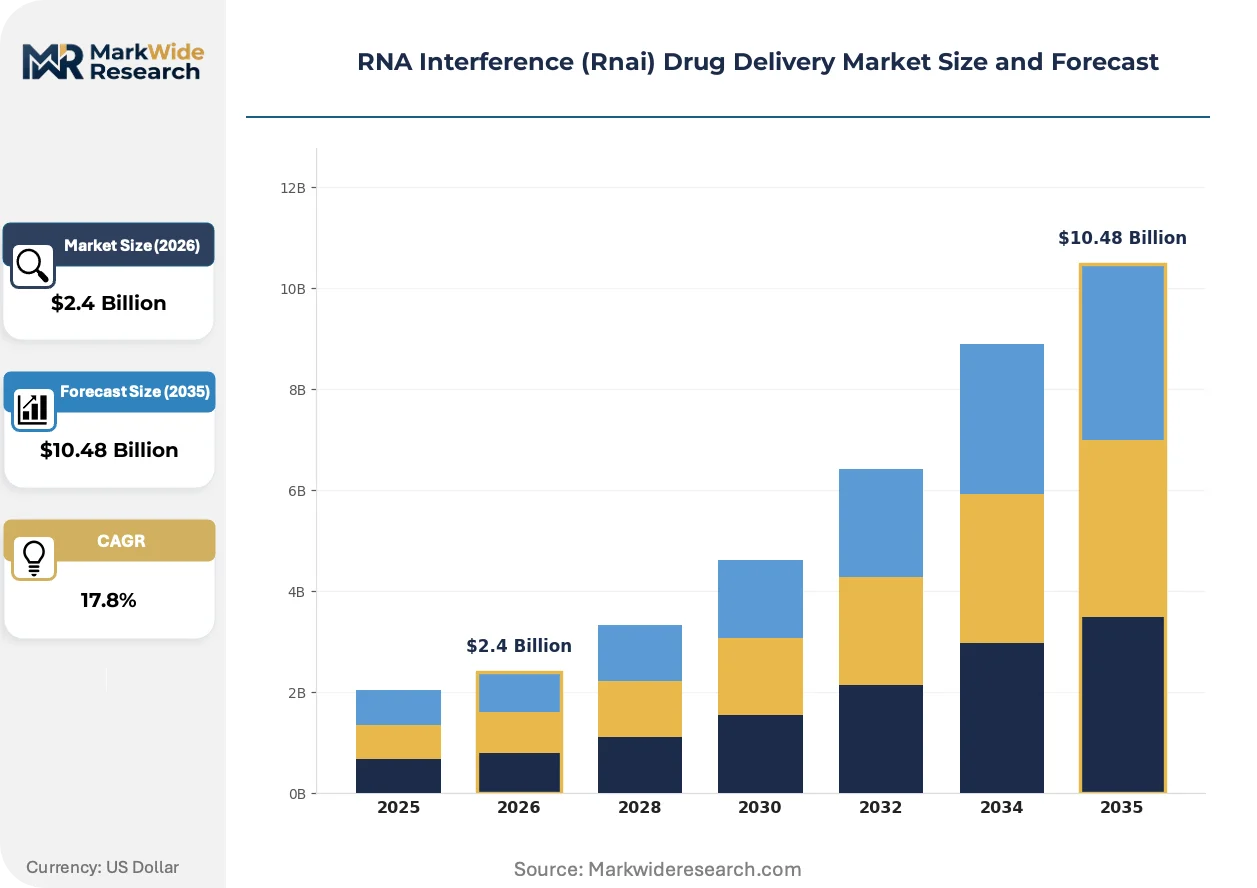
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $10.48 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposomal Formulations, Nanoparticles, Viral Vectors, Chemical Modifications Technology: MicroRNA, Short Interfering RNA, Antisense Oligonucleotides, RNAi-based Vaccines End User: Pharmaceutical Companies, Research Institutions, Contract Research Organizations, Biotech Firms Application: Cancer Therapy, Genetic Disorders, Infectious Diseases, Cardiovascular Disorders |
| Companies Covered | Alnylam Pharmaceuticals, Arrowhead Pharmaceuticals, Dicerna Pharmaceuticals, Silence Therapeutics, Ionis Pharmaceuticals, Arbutus Biopharma, Sirnaomics, Arcturus Therapeutics, OliX Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RNA Interference (Rnai) Drug Delivery Market Strategic Shifts & Innovations
Next-generation delivery architectures are dissolving the historical trade-off between tissue specificity and manufacturing scalability. Three parallel developments are compressing the gap between discovery-stage constructs and commercially viable formulations.
Lipid nanoparticle engineering is converging with organ-selective targeting ligands. Alnylam's N-acetylgalactosamine conjugate chemistry established liver tropism; newer platforms incorporate retinal pigment epithelium-targeting peptides and muscle-homing aptamers. Biotech developers are adopting these hybrid systems at preclinical stages, collapsing the timeline from target validation to tissue-specific proof-of-concept.
REACH authorization timelines for novel excipients are compressing competitive entry windows. The European Chemicals Agency's 2023 guidance update on polymer registration for pharmaceutical use is forcing developers to front-load toxicology packages. Early-stage companies with existing lipid master files are securing preferred supplier status with multinational pharmaceutical partners.
CDMO selection criteria are pivoting toward integrated analytical capabilities. Sponsors now require contract partners to deliver in-house bioanalytical method development, real-time stability monitoring, and regulatory submission support as bundled offerings. This bundling is visible most acutely in the United States, where FDA chemistry-manufacturing-controls expectations have tightened for complex generic RNAi filings.
RNA Interference (Rnai) Drug Delivery Market Segmentation
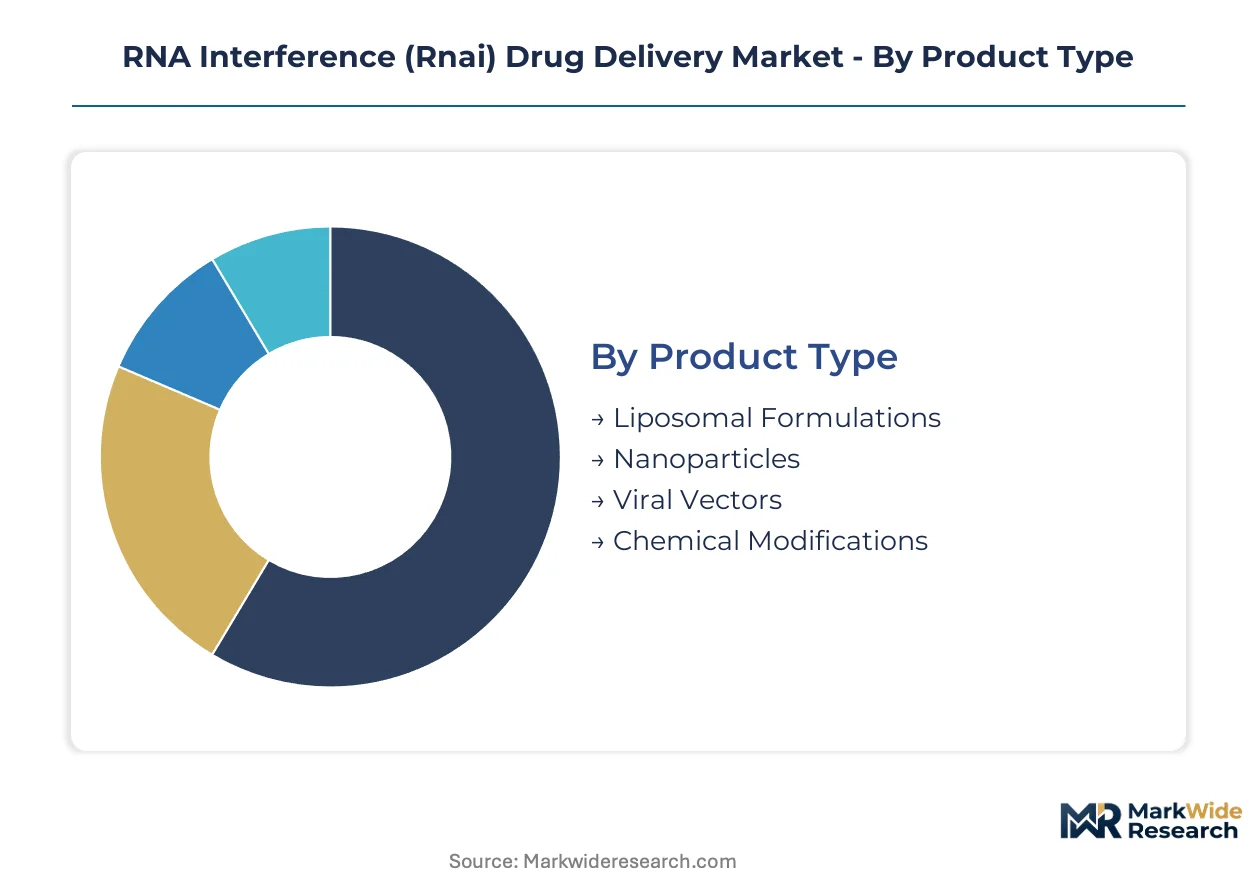
RNAi drug delivery platforms fragment across molecular payload types, carrier architectures, and therapeutic applications. Each segmentation axis reveals distinct procurement patterns, regulatory pathways, and manufacturing scale requirements that reshape competitive positioning.
Product Type:
Lipid nanoparticle engineering and viral vector manufacturing represent the core technical divergence in delivery platform selection.
- Liposomal Formulations:Phospholipid bilayer encapsulation systems with established GMP manufacturing infrastructure dominate current commercial supply. Demand concentrates in the United States where FDA chemistry-manufacturing-controls precedents accelerate approval timelines for liver-targeted siRNA therapies.
- Nanoparticles:Ionizable lipid-based architectures enable endosomal escape through pH-responsive membrane fusion, expanding tissue specificity beyond hepatocyte constraints. Polymeric formulations from Massachusetts and Switzerland-based contract manufacturers are displacing legacy liposomal platforms in oncology applications.
- Viral Vectors:Adeno-associated virus and lentiviral delivery systems provide nuclear entry for sustained gene silencing in dividing cell populations.
- Chemical Modifications:Phosphorothioate backbone substitutions and 2'-O-methyl ribose modifications enhance serum stability without carrier encapsulation.
Liposomal formulations lead on scale; nanoparticles lead on momentum.
Technology:
Payload chemistry determines target engagement mechanisms, dosing frequency, and intellectual property positioning across therapeutic programs.
- Short Interfering RNA:Synthetic double-stranded constructs 21-23 nucleotides in length trigger RISC-mediated mRNA cleavage with catalytic turnover. Alnylam Pharmaceuticals and Arrowhead Pharmaceuticals anchor demand concentration through proprietary conjugate chemistries and TRiM platform licensing.
- Antisense Oligonucleotides:Single-stranded DNA analogs bind complementary mRNA to block translation or induce RNase H degradation. Ionis Pharmaceuticals drives adoption in spinal muscular atrophy and familial chylomicronemia syndrome through FDA-approved intrathecal and subcutaneous formulations.
- MicroRNA:Endogenous regulatory RNA mimics or inhibitors modulate multiple gene networks simultaneously for complex disease phenotypes.
- RNAi-based Vaccines:Self-amplifying mRNA constructs encoding replicase machinery enable low-dose immunogen expression for prophylactic applications.
Antisense oligonucleotides lead on scale; short interfering RNA leads on momentum.
End User:
Customer type dictates contract structure, technical service requirements, and regulatory submission responsibility allocation.
- Pharmaceutical Companies:Large-cap developers with internal formulation science capabilities pursue platform acquisitions and exclusive licensing arrangements. Demand concentrates in the United States and Switzerland where EMA and FDA parallel submission strategies require integrated regulatory affairs support.
- Biotech Firms:Venture-backed developers with single-asset pipelines outsource manufacturing entirely to contract development and manufacturing organizations. Arrowhead Pharmaceuticals and Alnylam anchor procurement volumes through platform technology partnerships.
- Research Institutions:Academic laboratories require small-batch, high-complexity synthesis for target validation studies.
- Contract Research Organizations:Service providers aggregate demand from multiple sponsors for toxicology and pharmacokinetic assessment.
Pharmaceutical companies lead on scale; biotech firms lead on momentum.
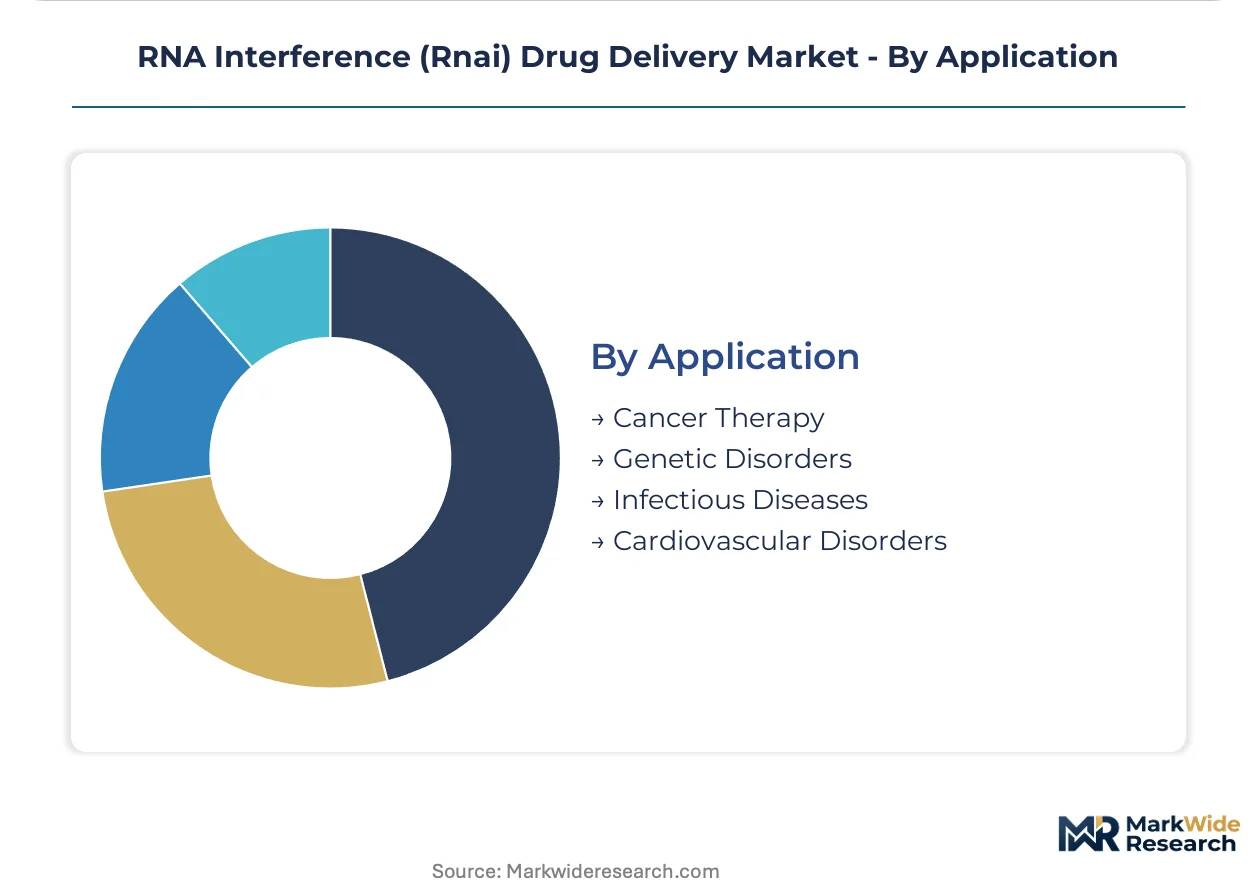
Application:
Therapeutic area selection determines target tissue accessibility, dosing route feasibility, and competitive landscape density.
- Cancer Therapy:Solid tumor penetration requires tumor-penetrating peptide conjugates and hypoxia-responsive delivery systems. Demand concentrates in the United States where FDA breakthrough therapy designation accelerates development timelines for oncologic RNAi candidates.
- Genetic Disorders:Liver-expressed gene silencing for transthyretin amyloidosis and acute hepatic porphyria established the first approved RNAi therapeutic category. Alnylam's Onpattro and Givlaari anchor revenue concentration through orphan drug exclusivity.
- Infectious Diseases:Host factor targeting and viral genome degradation enable broad-spectrum antiviral applications.
- Cardiovascular Disorders:Lipoprotein metabolism modulation addresses polygenic risk factors through PCSK9 and apolipoprotein C-III silencing.
Genetic disorders lead on scale; cancer therapy leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation scientists cluster in Massachusetts and Switzerland, anchoring lipid nanoparticle innovation for RNAi delivery platforms. This talent concentration shapes regulatory filing patterns and contract manufacturing site selection across major markets.
United States
FDA breakthrough therapy designations accelerate oncology RNAi timelines, pulling development-stage companies toward Boston and San Francisco clusters. The agency's Office of Therapeutic Biologics maintains stringent chemistry-manufacturing-controls expectations for lipid excipient qualification. Cambridge, Massachusetts hosts the densest concentration of ionizable lipid contract manufacturers serving dual US-EU filing strategies.
Switzerland
Swissmedic's alignment with EMA accelerated assessment pathways attracts platform technology licensors seeking European orphan drug access. Basel and Zurich anchor specialized lipid production for hepatocyte-targeted siRNA formulations. Local contract manufacturers supply Alnylam Pharmaceuticals and emerging competitors with GMP-grade ionizable lipids.
Germany
REACH compliance expertise concentrates in Frankfurt and Ludwigshafen, enabling faster novel excipient registration for EU market entry. The country's chemical industry infrastructure supports polymeric formulation scale-up for temperature-stable RNA payloads. Heidelberg and Munich biotech clusters drive preclinical demand for blood-brain barrier-penetrating delivery systems.
China
NMPA's 2023 technical guidance on nucleic acid therapeutics is harmonizing with ICH standards, shortening review timelines for imported RNAi assets. Shanghai and Suzhou industrial parks attract CDMO investments serving Asian-Pacific distribution. Domestic developers leverage local siRNA synthesis capacity to undercut Western manufacturing costs for infectious disease applications.
India
CDSCO's streamlined approval for repurposed lipid excipients is accelerating generic RNAi filing timelines. The production-linked incentive scheme for pharmaceuticals is drawing lipid nanoparticle contract manufacturers to Hyderabad and Ahmedabad. Local formulation scientists supply research institutions with small-batch liposomal encapsulation for target validation studies.
RNA Interference (Rnai) Drug Delivery Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the RNAi delivery landscape. Integrated pharmaceutical developers with captive manufacturing capabilities face pressure from platform-licensing biotechs that outsource entirely to contract partners. Three archetypes dominate: liver-targeting specialists with established GalNAc conjugate chemistry, modular platform licensors spanning multiple therapeutic areas, and CDMOs capturing margin from manufacturing scarcity. Competitive intensity centers on exclusive lipid supply agreements and integrated analytical service bundling.
Among platform-technology developers, Alnylam Pharmaceuticals exemplifies the integrated archetype through proprietary N-acetylgalactosamine chemistry, while Arrowhead Pharmaceuticals represents the modular licensing model with its TRiM platform. Arcturus Therapeutics occupies a position at the delivery-technology intersection, anchoring ionizable lipid innovation for extrahepatic targets. These three entities illustrate how intellectual property positioning around tissue specificity and manufacturing scalability determines partnership leverage.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals |
| Arrowhead Pharmaceuticals |
| Dicerna Pharmaceuticals |
| Silence Therapeutics |
| Ionis Pharmaceuticals |
| Arbutus Biopharma |
| Sirnaomics |
| Arcturus Therapeutics |
| OliX Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up contract manufacturers in Massachusetts and Switzerland impose pricing discipline through exclusive lipid supply agreements, while sovereign-backed Indian producers undercut Western cost structures via production-linked incentive schemes. This ownership bifurcation splits procurement strategies between premium bundled analytical services and transactional excipient sourcing.
Pricing Analysis
Bundled regulatory submission support commands 40-60% premiums over unbundled ionizable lipid supply, with CDMOs in Cambridge and Basel integrating real-time stability monitoring and bioanalytical method development as standard offerings. Price differentiation hinges on GMP certification tier and volume scale, with orphan drug manufacturers absorbing premium pricing for dedicated manufacturing slots. Cost compression in standard-grade liposomal formulations is intensifying because Indian and Chinese suppliers are expanding capacity for tropical-stable polymeric excipients. Biotech firms with single-asset pipelines exhibit highest price sensitivity, while large-cap pharmaceutical developers prioritize supply security over unit economics.
Supply Chain Analysis
India's domestic-content mandates under the PLI scheme are reshaping sourcing patterns, drawing lipid nanoparticle contract manufacturers to Hyderabad and Ahmedabad for Asian market access. Geographic supply concentration centers on Switzerland, Massachusetts, and coastal China for GMP-grade ionizable lipids, with raw material dependencies on phospholipid feedstocks, synthetic cholesterol analogs, and polyethylene glycol derivatives. Single-source vulnerability persists for novel cationic lipid architectures patented by Swiss and Massachusetts-based specialists. Distribution runs through integrated CDMO partnerships that bundle manufacturing with regulatory affairs support for dual US-EU filings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA breakthrough therapy designations for oncology RNAi assets accelerating procurement timelines and compressing vendor selection windows. EMA adaptive pathways for rare genetic disorders amplify this dynamic, creating procurement urgency that favors established platform licensors.
For Market Incumbents: Anchor market position through exclusive supply agreements for next-generation ionizable lipids targeting extrahepatic tissues, while retrofitting existing GMP suites for potent siRNA containment to defend against emerging CDMO competitors in India and China. Patent cliff exposure for first-generation GalNAc conjugates threatens revenue concentration; vertical integration into proprietary analytical method development preserves margin pools as manufacturing commoditizes.
For New Entrants and Emerging Players: Digital-channel partnerships with research institutions offer low-friction entry points, enabling platform validation through small-batch liposomal synthesis contracts before scaling to pharmaceutical partnerships. Blood-brain barrier-penetrating exosome formulations for Huntington's and Alzheimer's applications represent the most penetrable white space, with preclinical demand concentrated in Heidelberg and Munich clusters. A go-to-market angle emphasizing REACH-compliant lipid master files accelerates European partnership discussions.
For Investors and Strategic Acquirers: Valuations sit cheapest among modular platform licensors with tissue-agnostic delivery chemistry spanning multiple therapeutic areas, rather than single-target asset developers. Long-term viability hinges on regulatory exclusivity duration and manufacturing scalability across ionizable lipid generations. The signal to watch is NMPA harmonization progress with ICH standards, which would unlock Asian market expansion for Western platform technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for oncology RNAi candidates. |
| Manufacturing Scale-Up | GMP facility retrofits for potent siRNA handling strain development-stage balance sheets. |
| Platform Licensing Agreement | Arrowhead's TRiM platform sustains pipeline breadth across multiple therapeutic areas. |
| Clinical Trial Advancement | EMA adaptive pathways shorten timelines for rare genetic disorder candidates. |
| Pipeline Diversification | Antibody-siRNA conjugates create new modality categories in immuno-oncology. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, CDMO procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and REACH registration databases. Bottom-up patient-population modeling and top-down pharmaceutical R&D expenditure analysis provided cross-verification for market sizing.
Comparable-period anchoring established baseline reference points from historical RNAi therapeutic approvals and lipid nanoparticle manufacturing capacity expansion, with projections extending across the analysis window. Segmentation dimensions included carrier architecture, payload chemistry, therapeutic application, and regional regulatory cluster. CAGRs derived from patent expiration timelines, pipeline progression rates, and CDMO capacity buildout announcements. Forecast inputs incorporated ionizable lipid innovation cycles and EMA real-world evidence expectations.
The model assumes a particular technology adoption path; alternative pathways for viral vector delivery or fully synthetic non-lipid carriers would alter the outlook. Forecasts reflect assumptions around regulatory harmonization progress, excipient qualification timelines, and manufacturing talent availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
AI in Pharma and Biotech Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Isogenic Cell Lines Market