
 Global Cell Signaling Market | 2026-2036
Global Cell Signaling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Signaling Market Foresight
Asset-light leasing models for high-end fluorescence imaging and mass spectrometry instruments is reconfiguring competitive access for mid-tier biotechnology firms and academic institutes. Thermo Fisher Scientific dominates instrument placements through embedded service contracts that lock in reagent pull-through. Bio-Rad Laboratories leverages its vertical integration into assay development to sustain margin capture across both hardware and consumable layers. Cell Signaling Technology specializes in antibody validation rigor, anchoring premium positioning in phosphorylation-specific research workflows.
Cell signaling encompasses the molecular mechanisms by which cells communicate through ligand-receptor binding, second messenger cascades, and kinase-driven phosphorylation events, typically studied via fluorescence imaging, flow cytometry, or ELISA-based detection systems with sensitivity thresholds reaching picomolar concentrations. The primary commercial purpose is enabling drug discovery and oncology research by mapping disease-relevant pathways such as MAPK/ERK or PI3K/Akt/mTOR. Reagents and assay kits constitute the recurring revenue backbone of the market, while instruments represent the capital-intensive entry barrier that shapes vendor-customer switching costs. Software platforms for multi-omics data integration represent the fastest-expanding margin pool as pharmaceutical companies demand AI-compatible analytics for high-content screening datasets.
The FDA's Good Laboratory Practice standards and the EMA's clinical trial assay validation guidelines jointly determine market access for cell signaling products used in regulated drug development environments, while ISO 13485 certification serves as the baseline quality management filter for suppliers serving in vitro diagnostic applications. China's NMPA has tightened import registration requirements for research-use-only reagents, redirecting some procurement toward SAMR-registered domestic alternatives. Stakeholders must monitor how the EU AI Act's risk classification framework will treat algorithm-driven image analysis platforms that increasingly automate cell signaling quantification.
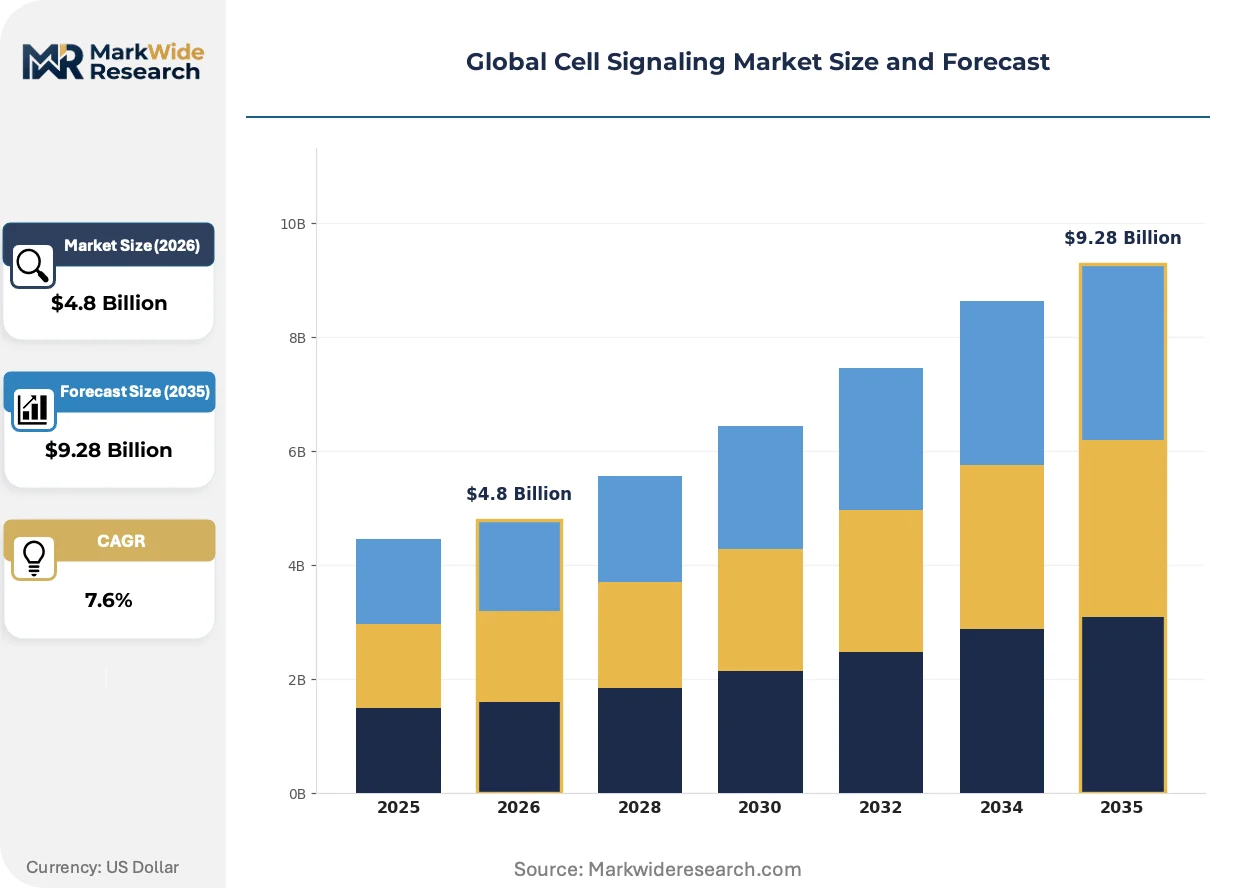
Market Dynamics
Pharmaceutical pipelines are pivoting toward kinase inhibitor programs, compressing validation timelines for phosphorylation-specific assay kits and forcing reagent suppliers to synchronize product development cycles with FDA accelerated approval schedules.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed clinical timelines for targeted oncology therapies are pulling forward demand for validated cell signaling assays in early-phase trials.
- AI-Compatible Analytics:Pharmaceutical sponsors now mandate software platforms that integrate multi-omics datasets, expanding the addressable base for high-content screening providers.
- Precision Medicine Clusters:Research infrastructure concentration in the United States, Germany, and Japan is anchoring regional procurement gravity for advanced imaging systems.
Market Restraints
- Capital Equipment Intensity:Mass spectrometry and fluorescence imaging platforms require substantial upfront investment, freezing out mid-tier biotechnology firms without leasing access.
- Antibody Validation Bottlenecks:Batch-to-batch variability in phosphorylation-specific reagents creates reproducibility failures that delay regulatory submissions.
- Import Registration Friction:China's NMPA has tightened SAMR registration requirements for research-use-only reagents, redirecting procurement toward domestic alternatives.
Strategic Opportunities
- Asset-Light Instrument Access:Leasing models for high-end mass spectrometry systems are unlocking mid-tier biotechnology firms previously excluded from ownership economics.
- EU AI Act Compliance Services:Algorithm-driven image analysis platforms face emerging risk classification requirements, creating advisory and validation service revenue pools.
- Embedded Service Contracts:Instrument vendors can lock in multi-year reagent pull-through by bundling maintenance with consumable supply agreements.
Industry Challenges
- Multi-Omics Integration Talent:Shortage of computational biologists capable of bridging high-content screening data with pathway modeling is throttling pharma adoption timelines.
- ISO 13485 Certification Delays:In vitro diagnostic applications require quality management audits that extend product launch cycles by 12-18 months for assay kit manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Signaling Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assay Kits, Instruments, Software Platforms, Services Technology: Fluorescence Imaging, Mass Spectrometry, Microarray Analysis, Flow Cytometry, ELISA Application: Drug Discovery, Oncology Research, Neurobiology, Immunology, Stem Cell Research End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutes, Contract Research Organizations |
| Companies Covered | Bio-Rad Laboratories Inc., Cell Signaling Technology Inc., Thermo Fisher Scientific Inc., Merck KGaA, Danaher Corporation, QIAGEN, Bio-Techne Corporation, PerkinElmer Inc., Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Signaling Market Shifts & Advancements
Workflow automation and regulatory digitization are compressing the gap between discovery-stage assay development and clinical validation, reshaping how reagent suppliers architect product roadmaps.
Single-cell phosphoproteomics is hybridizing mass spectrometry sensitivity with flow cytometry throughput. Contract research organizations serving pharmaceutical sponsors are adopting these platforms at accelerating cadence. The technology is hybridizing previously separate detection modalities into unified workflows that collapse sample preparation timelines from days to hours.
The EU AI Act's risk classification framework is recategorizing algorithm-driven image analysis platforms used for automated cell signaling quantification. Vendors must now document training data provenance and model interpretability for high-risk designations. European pharmaceutical sponsors are prioritizing suppliers with pre-validated compliance documentation, shifting procurement evaluation criteria.
Biotechnology firms are unbundling after-sales service contracts from instrument purchases, negotiating standalone maintenance agreements with third-party providers. This behavior is fragmenting the traditional vendor lock-in model that tied reagent consumption to original equipment manufacturer service relationships. The pattern is most visible among mid-cap United States-based precision medicine companies with dedicated procurement functions.
Global Cell Signaling Market Segmentation
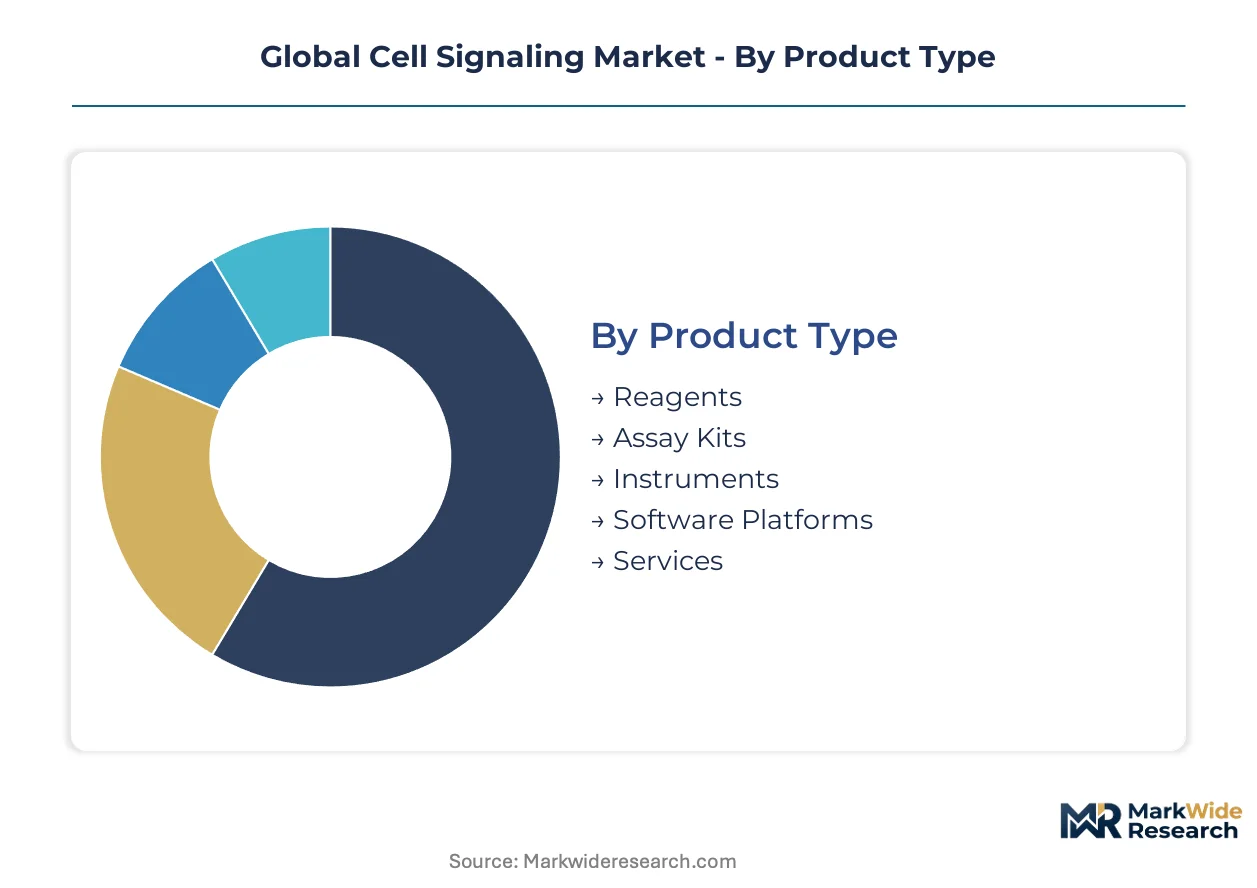
Cell signaling market segmentation reveals stark differences in purchase cycles and margin profiles across product layers. Reagents turn over in weeks while instruments lock capital for years, creating fundamentally different vendor-customer relationships.
Product Type:
Reagents cycle fastest with monthly replenishment rhythms, while instruments anchor decade-long capital planning horizons and software platforms refresh on 2-3 year enterprise license terms.
- Reagents:Antibodies, buffers, and detection substrates constitute the recurring revenue foundation with picomolar sensitivity specifications. Pharmaceutical sponsors in the United States and Germany concentrate procurement through master service agreements that bundle phosphorylation-specific antibodies with validation documentation.
- Assay Kits:Pre-validated ELISA and kinase activity panels compress development timelines for FDA submission-ready data packages. Biotechnology firms in Japan are standardizing on kit formats to bypass internal validation bottlenecks that delay IND filings.
- Instruments:Mass spectrometry and fluorescence imaging platforms represent the capital-intensive entry barrier.
- Software Platforms:AI-compatible analytics for multi-omics data integration are expanding fastest.
- Services:Contract validation and compliance advisory support regulatory submission requirements.
Reagents anchor the volume base while software platforms gain share at the steepest rate.
Technology:
Detection modalities span cost tiers from benchtop ELISA readers to million-dollar mass spectrometry suites, with each tier serving distinct throughput and sensitivity requirements.
- Fluorescence Imaging:High-content screening systems enable spatial resolution of protein localization dynamics. Academic institutes in Germany leverage these platforms for live-cell kinase tracking studies that demand subcellular precision.
- Mass Spectrometry:Single-cell phosphoproteomics sensitivity reaches attomolar detection thresholds. Pharmaceutical companies in the United States deploy these systems for biomarker discovery pipelines requiring absolute quantification.
- Microarray Analysis:Multiplexed pathway profiling suits discovery-stage screening.
- Flow Cytometry:High-throughput single-cell analysis dominates immunology workflows.
- ELISA:Plate-based detection remains the workhorse for routine quantification.
ELISA sustains the broadest installed base while mass spectrometry climbs the fastest.
Application:
Oncology research commands premium pricing for validated reagents, while stem cell applications operate on tighter academic budgets with longer evaluation cycles.
- Oncology Research:Kinase inhibitor development drives demand for phosphorylation-specific assays with batch-to-batch consistency guarantees. Contract research organizations in Japan specialize in MAPK/ERK and PI3K/Akt/mTOR pathway validation for accelerated FDA approval timelines.
- Drug Discovery:Target identification and lead optimization consume the highest reagent volumes. Biotechnology firms in Germany concentrate high-content screening investments in this segment to support precision medicine pipelines.
- Neurobiology:Synaptic signaling studies require specialized tissue preparation protocols.
- Immunology:Cytokine signaling analysis supports autoimmune therapeutic development.
- Stem Cell Research:Pluripotency marker detection serves regenerative medicine programs.
Drug discovery absorbs the largest absolute spend while oncology research expands most quickly.
End User:
Pharmaceutical procurement functions negotiate enterprise-wide reagent contracts, while academic purchasing remains fragmented across individual laboratory budgets.
- Pharmaceutical Companies:Integrated drug development organizations mandate ISO 13485-certified reagents for regulated environments. Sponsors in the United States synchronize assay validation with FDA accelerated approval pathways to compress clinical timelines.
- Contract Research Organizations:Outsourced validation services aggregate demand across multiple sponsor programs. CROs in Germany are deploying single-cell phosphoproteomics platforms to differentiate their service offerings.
- Biotechnology Firms:Mid-tier companies increasingly lease instruments rather than purchase.
- Academic Institutes:Research grant funding constrains capital equipment acquisition.
Pharmaceutical companies dominate absolute procurement value while contract research organizations are expanding their technology footprint fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement functions concentrate in three national clusters where precision medicine infrastructure density shapes vendor access patterns. Biotechnology firms in these markets negotiate enterprise reagent contracts while academic institutes fragment purchasing across laboratory budgets.
United States
FDA accelerated approval pathways compress clinical timelines for kinase inhibitor programs, pulling forward demand for validated phosphorylation assays. The agency's Good Laboratory Practice standards determine market access for products used in regulated drug development. Greater Boston hosts the densest concentration of contract research organizations deploying single-cell phosphoproteomics for biomarker discovery pipelines.
Germany
EMA clinical trial assay validation guidelines shape procurement criteria for pharmaceutical sponsors operating across European development programs. The country's national pharmaceutical regulator enforces ISO 13485 certification baselines for in vitro diagnostic applications. Academic institutes in Bavaria leverage high-content screening systems for live-cell kinase tracking studies demanding subcellular precision.
Japan
PMDA consultation pathways for oncology drug development synchronize assay validation requirements with sponsor submission timelines. METI research infrastructure investments anchor regional procurement gravity for advanced imaging systems. Contract research organizations in the Kanto region specialize in MAPK/ERK and PI3K/Akt/mTOR pathway validation for accelerated regulatory submissions.
China
NMPA tightened SAMR registration requirements for research-use-only reagents, redirecting procurement toward domestic alternatives. The country's national medical products administration now demands import documentation that extends procurement cycles for foreign suppliers. Biotechnology clusters in the Yangtze River Delta concentrate demand for mass spectrometry platforms serving precision medicine pipelines.
United Kingdom
MHRA post-Brexit regulatory autonomy has recalibrated assay validation requirements for sponsors targeting UK-specific approval pathways. The national medicines regulator maintains alignment with EMA standards while developing distinct consultation procedures. London-based pharmaceutical sponsors negotiate enterprise-wide reagent contracts bundling phosphorylation-specific antibodies with validation documentation.
Global Cell Signaling Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct capability tiers. Instrument vendors leverage embedded service contracts to lock in multi-year reagent pull-through, while reagent suppliers compete on antibody validation rigor and batch-to-batch consistency guarantees. The market structure rewards backward integration into assay development and captive supply of detection substrates. Dominant competitive moves include strategic partnerships for multi-omics data integration and geographic expansion through SAMR-registered domestic alternatives in China.
Within the full-spectrum platform tier, Thermo Fisher Scientific Inc. anchors instrument placement strategies through bundled maintenance agreements. Bio-Rad Laboratories Inc. and Cell Signaling Technology Inc. exemplify contrasting archetypes: the former represents vertical integration across hardware and consumable layers, while the latter occupies a position defined by specialization in phosphorylation-specific research workflows. These three entities collectively illustrate how vendor-customer switching costs crystallize around either capital equipment intensity or reagent validation rigor.
| Leading Market Players |
|---|
| Bio-Rad Laboratories Inc. |
| Cell Signaling Technology Inc. |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Danaher Corporation |
| QIAGEN |
| Bio-Techne Corporation |
| PerkinElmer Inc. |
| Becton, Dickinson and Company |
| Others |
Supply & Pricing Matrix
Greater Boston's contract research organization cluster concentrates single-cell phosphoproteomics capacity, translating instrument scarcity into premium pricing power for validated assay kits serving FDA submission pathways. The region's embedded service contracts lock reagent pull-through across multi-year horizons, compressing negotiation leverage for mid-tier biotechnology firms.
Pricing Analysis
Certification level (ISO 13485/FDA-grade) creates the primary spread between premium and standard reagent tiers, with validated phosphorylation-specific antibodies commanding substantial markups over research-use-only alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by batch-to-batch consistency guarantees and documentation depth. Cost compression in the standard tier is intensifying because domestic Chinese suppliers are gaining SAMR registration traction. Academic institutes exhibit highest price sensitivity, while pharmaceutical sponsors prioritize certification reliability over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard for instrument vendors serving mid-cap biotechnology firms, easing capital constraints that previously froze out ownership economics. Manufacturing concentration rests on the United States, Germany, and Japan for precision instrumentation, while China and South Korea anchor consumable production at scale. Critical dependencies include rare-earth optical components, high-purity solvents, and recombinant antibody cell lines. Single-source vulnerability concentrates in specialized fluorescence detector assemblies. Distribution runs through direct field service organizations for instruments and master service agreements for reagent replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across kinase inhibitor program pipelines creates niche entry points for specialized assay developers, as pharmaceutical sponsors disaggregate validation requirements across multiple supplier relationships rather than consolidating with full-spectrum platform vendors.
For Market Incumbents: Insulate reagent pull-through by embedding multi-year service contracts with maintenance bundling that raises switching costs for biotechnology firm customers. Deepen backward integration into antibody production to control batch-to-batch variability that threatens regulatory submission timelines. Priority investment targets ISO 13485 certification expansion for in vitro diagnostic applications, as EMA and FDA convergence on quality management standards raises compliance barriers for unqualified competitors. For New Entrants and Emerging Players: Mid-tier contract research organizations in Japan represent the most penetrable entry point, as these entities seek differentiated single-cell phosphoproteomics capabilities to compete with established biomarker discovery providers. Leasing partnerships for mass spectrometry platforms unlock asset-light access to biotechnology firms previously excluded from capital ownership. Go-to-market positioning should emphasize accelerated validation documentation aligned with PMDA consultation timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among assay kit manufacturers with master service agreements anchoring monthly replenishment rhythms at pharmaceutical sponsors. Long-term viability favors suppliers with demonstrated antibody validation rigor and backward integration into detection substrate production. The signal to watch is NMPA SAMR registration momentum among domestic Chinese alternatives, which could redirect procurement gravity and compress margin pools for import-dependent foreign suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Antibody Validation Rigor Investment | Batch-to-batch consistency guarantees anchor premium positioning for phosphorylation-specific reagent suppliers serving FDA submission pathways. |
| Asset-Light Instrument Leasing | Extended payment terms unlock mid-tier biotechnology firm access to mass spectrometry platforms previously restricted by capital constraints. |
| EU AI Act Compliance Documentation | Pre-validated algorithm interpretability records become procurement differentiators for European pharmaceutical sponsors selecting image analysis platforms. |
| SAMR Registration Expansion | Domestic certification in China redirects procurement toward registered alternatives as NMPA tightens import documentation requirements. |
| Multi-Omics Data Integration Partnership | AI-compatible analytics capabilities address pharmaceutical sponsor mandates for high-content screening dataset interoperability. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, assay validation scientists, and procurement managers at contract research organizations anchored the qualitative base. Primary interview findings triangulated against FDA 510(k) filings, EMA clinical trial assay validation guidelines, ClinicalTrials.gov protocol specifications, and ISO 13485 certification databases. Secondary validation incorporated SEC 10-K instrument revenue disclosures, SAMR registration records, and precision medicine infrastructure investment announcements. Bottom-up segment sizing and top-down market reconstruction cross-checked for consistency.
Scenario-bracketing around FDA accelerated approval pathway utilization rates and AI-driven image analysis adoption curves bounded the projection range across the analysis window. Segmentation modeling incorporated product type, detection technology, application area, and end-user procurement archetype dimensions. CAGRs derived from historical instrument placement trajectories, reagent replenishment velocity patterns, and software platform enterprise license renewal rates. Kinase inhibitor pipeline density and precision medicine cluster infrastructure investments served as industry-specific demand-side inputs.
Practitioners should monitor NMPA import policy shifts, EU AI Act enforcement granularity, and antibody batch failure rates at contract research organizations for early signals of forecast revision triggers. The analysis assumes sustained pharmaceutical R&D intensity and continued regulatory convergence on quality management standards. Macroeconomic contraction in biotechnology venture funding, abrupt tariff escalation on optical components, or fundamental breakthroughs in label-free detection modalities would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Exonucleases Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Strand Displacement Amplicon (SDA) Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market