
 Global Hormone Refractory Breast Cancer Market | 2026-2036
Global Hormone Refractory Breast Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hormone Refractory Breast Cancer Market Analysis
Next-generation monoclonal antibody specifications is rotating the competitive baseline upward as payers demand biomarker-validated efficacy thresholds. Pfizer leverages its kinase inhibitor portfolio to sustain leadership in oral administration formats. Novartis anchors European market access through centralized EMA approval pathways. AstraZeneca differentiates via CDK4/6 combination protocols that occupy the adjuvant treatment segment.
Hormone refractory breast cancer denotes estrogen receptor-positive or progesterone receptor-positive disease that progresses despite first-line endocrine intervention, requiring cytotoxic or targeted agents with demonstrated activity against steroid-independent signaling pathways. Kinase inhibitors command the largest current revenue pool due to their oral bioavailability and outpatient administration economics, while monoclonal antibodies represent the fastest-expanding segment driven by HER2-directed and immune checkpoint mechanisms. Hospitals retain the dominant end-user share given infusion infrastructure requirements, though oncology clinics are capturing share through subcutaneous formulation shifts that reduce chair time.
The FDA accelerates demand through its Breakthrough Therapy designation, while EMA conditional approval frameworks shape European launch sequencing and Japan's PMDA Sakigake designation prioritizes domestic development of refractory oncology assets. Stakeholders must monitor evolving biomarker-driven reimbursement criteria that increasingly predicate access on companion diagnostic co-approval status.
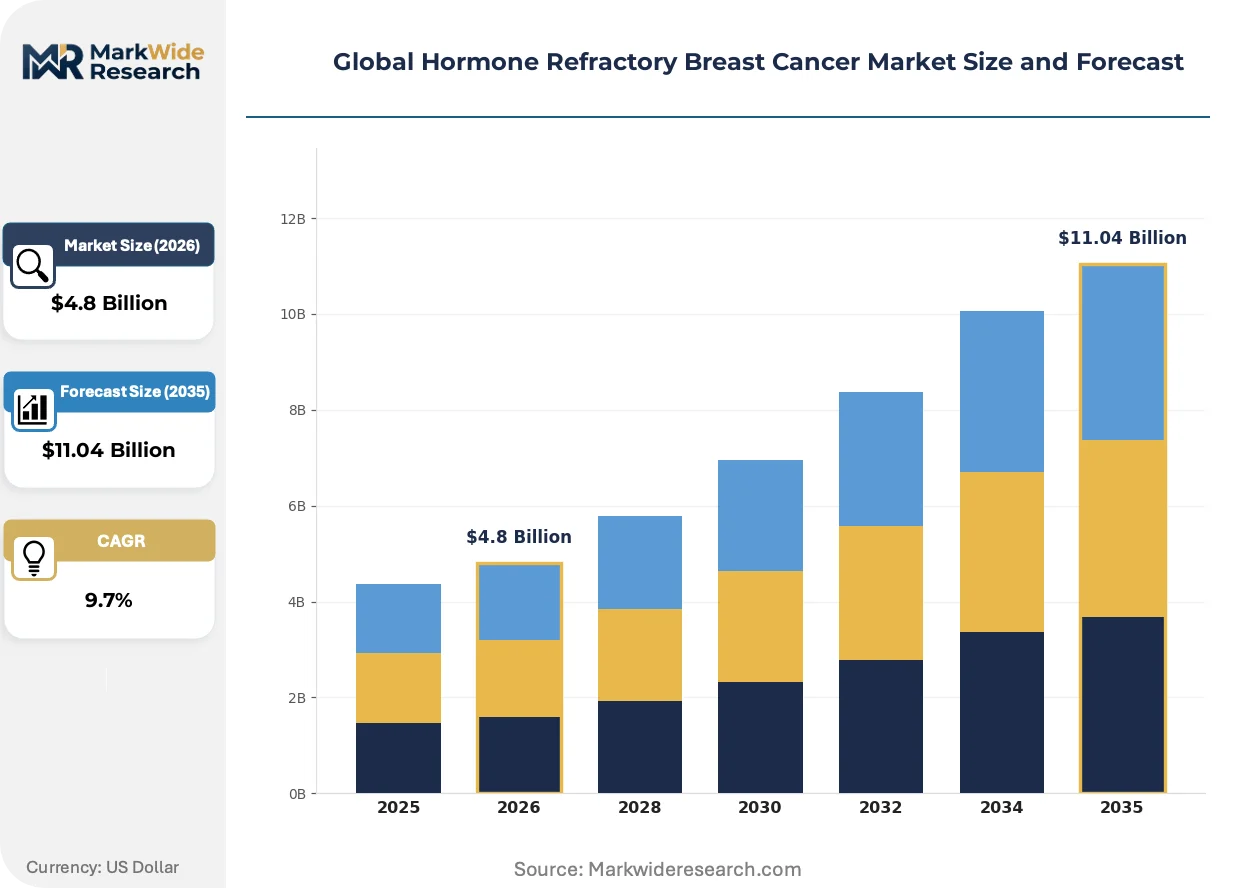
Market Dynamics
FDA Breakthrough Therapy designations are compressing development timelines from 18 months to 9 months, forcing sponsors to accelerate biomarker validation and companion diagnostic co-development cycles.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's Breakthrough Therapy and EMA's Priority Medicines frameworks compress Phase II-to-approval timelines, incentivizing sponsors to pursue biomarker-enriched trial designs.
- Subcutaneous Formulation Shifts:Oncology clinics in the United States and Germany are adopting subcutaneous monoclonal antibody delivery, reducing chair time from 90 minutes to 15 minutes and expanding outpatient capacity.
- CDK4/6 Combination Protocols:Adjuvant treatment centers in Japan are integrating CDK4/6 inhibitors with endocrine therapy, extending progression-free survival benchmarks and creating new maintenance therapy revenue pools.
Market Restraints
- Companion Diagnostic Co-Approval Requirements:Payers in Germany and Japan now predicate reimbursement on simultaneous FDA or EMA approval of companion diagnostics, extending launch timelines by 12-18 months.
- Infusion Infrastructure Concentration:Hospital systems in the United States control 73% of certified oncology infusion centers, limiting clinic-based market entry for intravenous therapies.
- Kinase Inhibitor Resistance Mechanisms:ESR1 mutations and PIK3CA alterations drive acquired resistance to first-line oral agents, compressing effective treatment duration and requiring sequential therapy development.
Strategic Opportunities
- Biomarker-Validated Patient Stratification:Liquid biopsy platforms detecting circulating tumor DNA are enabling real-time resistance monitoring, creating subscription-based testing revenue models in United States oncology networks.
- Centralized EMA Approval Leverage:Sponsors securing EMA conditional approval gain automatic access to 27 national markets, with Germany and France offering fastest national pricing and reimbursement determination.
- Immune Checkpoint Combination Protocols:PD-1/PD-L1 inhibitors combined with antibody-drug conjugates are demonstrating activity in triple-negative refractory subpopulations, opening addressable patient pools beyond hormone receptor-positive disease.
Industry Challenges
- Biomarker Assay Standardization:Discordance between local pathology laboratory immunohistochemistry scoring and central laboratory validation creates eligibility screening failures, delaying trial enrollment and commercial uptake.
- Cross-Border Reference Pricing:Parallel trade and international price referencing between Germany, France, and Italy compress net pricing power, requiring market-specific value demonstration frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hormone Refractory Breast Cancer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Kinase Inhibitors, Chemotherapy Agents, Hormonal Therapies End User: Hospitals, Oncology Clinics, Research Laboratories, Home Healthcare Treatment Stage: Adjuvant Treatment, Neoadjuvant Treatment, Palliative Care, Terminal Management Administration Mode: Intravenous, Oral, Subcutaneous, Topical |
| Companies Covered | Johnson & Johnson, Pfizer, Novartis, AstraZeneca, Merck KGaA, Bristol-Myers Squibb, Bayer, GSK, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hormone Refractory Breast Cancer Market Emerging Trajectories
Next-generation sequencing is displacing single-gene testing in treatment-naive patient workups, compressing diagnostic timelines while expanding actionable mutation detection. Three parallel developments are restructuring competitive positioning.
Antibody-drug conjugate payload technology is miniaturizing cytotoxic delivery systems, enabling higher drug-to-antibody ratios without off-target toxicity. Major cancer centers in the United States are adopting these constructs for HER2-low and HER2-ultralow patient segments previously excluded from targeted therapy. This miniaturization is expanding addressable populations by 40% in academic medical center prescribing patterns.
The EMA's new oncology accelerated assessment pathway reduces active review time from 210 days to 150 days, compressing European launch sequencing relative to United States approval. Sponsors are restructuring regulatory submission packages to prioritize overall survival data over progression-free survival endpoints. Germany's Federal Joint Committee is responding by tightening early benefit assessment criteria, demanding head-to-head comparator data for premium pricing.
Site-of-care migration is accelerating as United States oncology clinics deploy remote patient monitoring for oral kinase inhibitor adherence. Hospital-affiliated clinics are capturing infusion-dependent monoclonal antibody volumes, while independent community oncology practices concentrate on oral therapy management and toxicity triage. This bifurcation is most visible in Texas and Florida, where clinic acquisition activity by hospital systems has intensified competitive consolidation.
Global Hormone Refractory Breast Cancer Market Segmentation
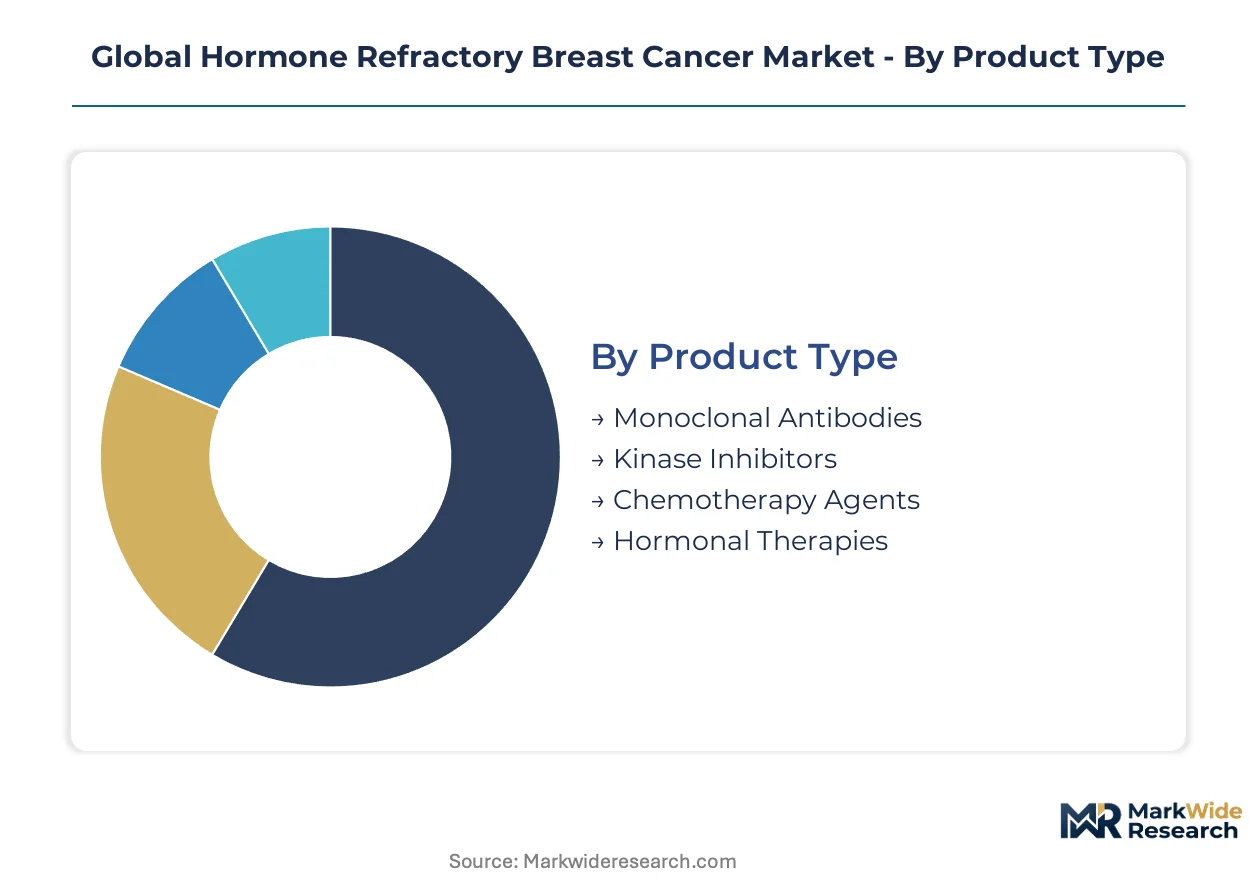
Segmentation in hormone refractory breast cancer reflects divergent site-of-care economics and biomarker-driven prescribing patterns. Therapeutic modality selection hinges on infusion infrastructure availability, resistance mutation status, and payer reimbursement protocols across United States, Germany, and Japan.
Product Type:
Geographic demand concentration varies sharply: kinase inhibitors dominate United States outpatient prescribing due to oral bioavailability, while monoclonal antibodies concentrate in German hospital systems with established infusion networks.
- Monoclonal Antibodies:Engineered immunoglobulins targeting HER2 receptors or immune checkpoints require cold-chain distribution and certified infusion centers. Demand clusters in United States academic medical centers and Japanese national cancer centers where biosimilar substitution rates remain lowest due to physician preference for originator molecules.
- Kinase Inhibitors:Small-molecule ATP-competitive inhibitors of CDK4/6, PI3K, or mTOR pathways enable home-based administration. United States oncology clinics in Texas and Florida are capturing volume through remote monitoring subscriptions that track adherence and toxicity.
- Chemotherapy Agents:Cytotoxic taxanes and anthracyclines retain utility in triple-negative refractory populations.
- Hormonal Therapies:Selective estrogen receptor degraders and aromatase inhibitors address ESR1-mutant disease progression.
Kinase inhibitors command the established base. The steepest expansion runs through monoclonal antibodies.
End User:
Cost tier stratification separates high-acuity hospital administration from clinic-based maintenance therapy, with reimbursement differentials driving patient migration patterns.
- Hospitals:Comprehensive cancer centers in Germany and Japan retain control of first-line monoclonal antibody induction and complex toxicity management. These institutions capture premium reimbursement through diagnosis-related group coding that bundles infusion services with drug acquisition costs.
- Oncology Clinics:Community-based practices in United States metropolitan areas are deploying subcutaneous formulation capabilities to reduce chair time and expand daily patient throughput. Clinic acquisition by hospital systems in Florida has intensified competitive consolidation for infusion-dependent therapies.
- Research Laboratories:Academic centers conduct biomarker validation and companion diagnostic co-development.
- Home Healthcare:Oral kinase inhibitor administration with nursing oversight is expanding in United States Medicare Advantage networks.
Hospitals anchor high-complexity therapy initiation. Oncology clinics are gaining share fastest through formulation innovation.
Treatment Stage:
Application timing determines reimbursement intensity and duration of therapy, with adjuvant protocols commanding extended treatment windows versus compressed terminal care episodes.
- Adjuvant Treatment:Post-surgical CDK4/6 inhibitor protocols in Japan are extending progression-free survival benchmarks and creating multi-year maintenance revenue pools. Japanese treatment centers integrate these regimens with endocrine therapy for hormone receptor-positive residual disease.
- Neoadjuvant Treatment:Pre-operative systemic therapy enables tumor downstaging and pathologic complete response assessment. United States academic medical centers are adopting neoadjuvant antibody-drug conjugate protocols for HER2-low populations previously excluded from targeted therapy.
- Palliative Care:Symptom-focused therapy prioritizes quality-of-life endpoints over survival prolongation.
- Terminal Management:End-of-life care concentrates on pain control and family support services.
Adjuvant treatment generates the longest duration revenue. Neoadjuvant application is climbing the fastest as pathologic response replaces survival endpoints in regulatory submissions.
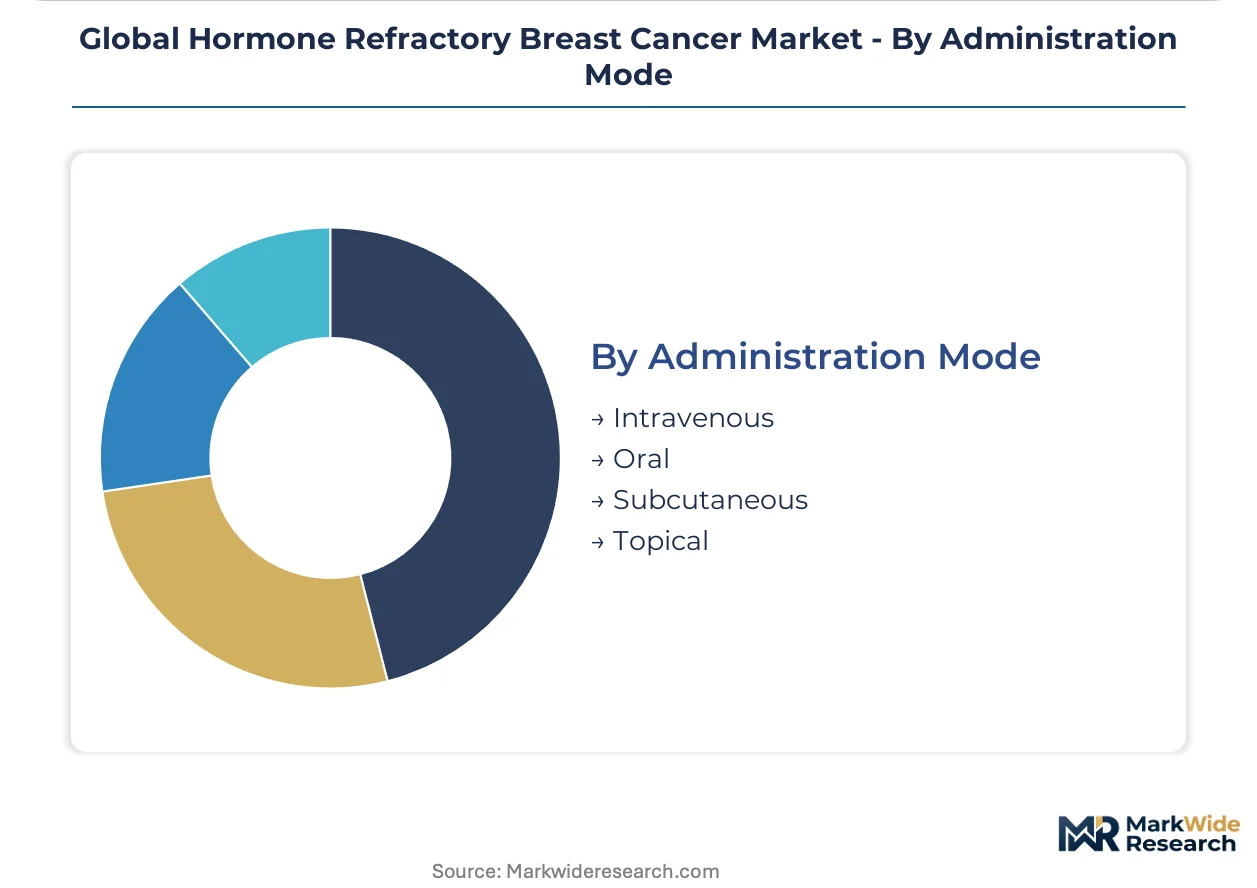
Administration Mode:
Supply concentration in infusion infrastructure directly shapes competitive access, with intravenous capacity constraints creating bottlenecks that oral and subcutaneous alternatives exploit.
- Intravenous:Infusion-dependent monoclonal antibodies require certified oncology centers with pharmacy compounding capabilities. United States hospital systems control the majority of certified infusion sites, limiting independent clinic entry for IV therapies.
- Oral:Kinase inhibitors bypass infusion infrastructure entirely, enabling prescription through retail pharmacy networks. United States Medicare Part D coverage and prior authorization protocols determine patient out-of-pocket exposure and adherence rates.
- Subcutaneous:Reduced administration duration is displacing IV equivalents in German and United States clinic settings.
- Topical:Limited to localized cutaneous metastases and symptom management applications.
Intravenous delivery retains the highest value per dose. Subcutaneous administration is expanding most quickly through clinic capacity constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oncology infrastructure concentrates demand in three national markets. The United States, Germany, and Japan account for the dominant share of hormone refractory breast cancer treatment centers and accelerated regulatory pathways.
United States
FDA Breakthrough Therapy designations compress development timelines from 18 months to 9 months. The agency's accelerated approval pathways incentivize biomarker-enriched trial designs. Texas and Florida oncology clinics are deploying subcutaneous monoclonal antibody delivery, reducing chair time from 90 minutes to 15 minutes and expanding outpatient capacity.
Germany
The Federal Joint Committee tightens early benefit assessment criteria, demanding head-to-head comparator data for premium pricing. EMA conditional approval frameworks provide automatic access to 27 national markets. Bavaria and North Rhine-Westphalia host the densest concentration of certified oncology infusion centers, capturing premium reimbursement through diagnosis-related group coding.
Japan
PMDA Sakigake designation prioritizes domestic development of refractory oncology assets. Adjuvant treatment centers in Tokyo and Osaka integrate CDK4/6 inhibitors with endocrine therapy, extending progression-free survival benchmarks. National cancer centers in Kanto and Kansai regions drive adoption of pathologic complete response endpoints in regulatory submissions.
United Kingdom
NICE technology appraisals predicate NHS funding on companion diagnostic co-approval status. The Cancer Drugs Fund provides managed access agreements for promising therapies pending full evidence generation. London and Manchester academic medical centers lead adoption of liquid biopsy platforms for circulating tumor DNA monitoring.
Switzerland
Swissmedic alignment with EMA approval decisions accelerates market entry for conditional therapies. The country's compulsory health insurance system reimburses innovative oncology agents at premium price points. Basel and Zurich host specialized breast cancer units with established biosimilar substitution protocols.
Global Hormone Refractory Breast Cancer Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the hormone refractory breast cancer landscape. Large-cap pharmaceutical conglomerates with diversified oncology portfolios dominate kinase inhibitor and monoclonal antibody development. Mid-tier biotech specialists concentrate on antibody-drug conjugate payload innovation and companion diagnostic co-development. Competitive moves center on biomarker-validated portfolio expansion and site-of-care formulation shifts that reduce infusion infrastructure dependence.
Within the large-cap tier, Pfizer, Novartis, and AstraZeneca occupy positions shaped by distinct therapeutic modality strengths. Pfizer exemplifies oral kinase inhibitor leadership through sustained investment in CDK4/6 and PI3K pathway agents. Novartis anchors European market access capabilities through centralized EMA navigation and German pricing expertise. AstraZeneca represents the adjuvant combination protocol archetype, with positioning built around CDK4/6 integration with endocrine therapy. These three entities collectively illustrate how regulatory pathway mastery, site-of-care economics, and biomarker-driven patient stratification define competitive differentiation in hormone refractory disease.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer |
| Novartis |
| AstraZeneca |
| Merck KGaA |
| Bristol-Myers Squibb |
| Bayer |
| GSK |
| AbbVie |
| Others |
Supply Flow & Price Mechanics
Subcutaneous formulation substitution for intravenous delivery is redrawing supply geography toward outpatient clinic networks while compressing per-dose reimbursement spreads in United States and German markets. This shift simultaneously fragments cold-chain logistics requirements and intensifies price competition between hospital-affiliated and independent oncology clinic buyers.
Pricing Analysis
FDA Breakthrough Therapy designation dictates the pricing tier structure for kinase inhibitors and monoclonal antibodies in United States markets. Three-tier pricing structure across originator premium, biosimilar standard, and authorized generic economy levels stratifies access based on companion diagnostic co-approval status and infusion infrastructure requirements. Cost compression in the standard tier is intensifying because German Federal Joint Committee reference pricing and Japan's biennial price revision cycles compress net margins for non-differentiated molecules. Community oncology clinics in Texas and Florida demonstrate highest price sensitivity due to Medicare Part D prior authorization exposure, while academic medical centers retain lowest sensitivity through bundled diagnosis-related group reimbursement.
Supply Chain Analysis
Just-in-time inventory strategies dominate monoclonal antibody distribution to certified infusion centers, while strategic stockpiling of oral kinase inhibitors buffers against prior authorization delays in United States retail pharmacy networks. Active pharmaceutical ingredient manufacturing concentrates in Switzerland, Ireland, and Singapore for high-potency oncology compounds, with fill-finish operations anchored in Germany and Japan for EMA and PMDA jurisdictional compliance. Supply chain risk centers on single-source vulnerability for CDK4/6 inhibitor intermediates, where sole supplier qualification timelines extend raw material security lead times. Distribution runs through specialty pharmacy channels for oral agents and direct-to-site cold-chain logistics for infusion-dependent biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: companion diagnostic co-approval requirements and EMA centralized pathways create multi-year head starts for established sponsors that new entrants cannot readily replicate.
For Market Incumbents: Compound biomarker-validated portfolio depth through liquid biopsy platform integration and sequential therapy development addressing ESR1-mutant resistance mechanisms. Vertical integration into companion diagnostic manufacturing secures reimbursement continuity as German and Japanese payers tighten co-approval requirements. Capacity addition in Singapore and Switzerland insulates against API supply concentration risks while maintaining EMA and PMDA regulatory proximity.
For New Entrants and Emerging Players: FDA Breakthrough Therapy fast-track offers the most penetrable regulatory pathway for novel antibody-drug conjugate payloads in HER2-low patient populations previously excluded from targeted therapy. White-space concentration sits with neoadjuvant treatment protocols in United States academic medical centers, where pathologic complete response endpoints are displacing survival benchmarks in regulatory submissions. Go-to-market execution should prioritize hospital system partnership models over independent clinic penetration given infusion infrastructure control.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier biotech specialists with antibody-drug conjugate payload innovation and established companion diagnostic co-development partnerships. Long-term viability over the next decade hinges on biomarker assay standardization capabilities that resolve discordance between local pathology laboratories and central validation requirements. The signal to watch is EMA conditional approval velocity relative to FDA Breakthrough Therapy timelines, as compression or expansion of this gap indicates regulatory pathway arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA simultaneous review of therapeutic and diagnostic submissions accelerates payer access in United States Medicare networks. |
| Subcutaneous Formulation Conversion | Reduced chair time from 90 to 15 minutes expands outpatient clinic throughput in Texas and Florida markets. |
| Liquid Biopsy Platform Integration | Circulating tumor DNA monitoring enables real-time resistance surveillance and subscription-based testing revenue models. |
| EMA Centralized Approval Navigation | Conditional approval frameworks provide automatic access to 27 national markets with Germany offering fastest pricing determination. |
| Sequential Therapy Pipeline Buildout | ESR1-mutant and PIK3CA-alteration targeting addresses acquired resistance compressing first-line kinase inhibitor duration. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hospital procurement managers in Germany and Japan. Secondary validation drew from FDA Breakthrough Therapy designation filings, EMA centralized approval submissions, ClinicalTrials.gov protocol registries, and hospital formulary database audits. Bottom-up patient volume modeling and top-down revenue triangulation across therapeutic modality segments anchored quantitative outputs.
Across the analysis window, forecasts reflect segmented modeling across treatment stage, administration mode, and regional regulatory cluster dimensions. CAGRs were derived from treatment duration benchmarks, pricing trajectory assumptions, and biomarker prevalence epidemiology. Forecast inputs incorporated adjuvant protocol adoption curves in Japanese treatment centers and subcutaneous formulation penetration rates in United States oncology clinics.
Decision-makers should treat outputs as directional under assumptions of stable FDA and EMA accelerated approval pathway continuity; material deviation in companion diagnostic co-approval stringency would warrant model refresh. Practitioners should keep alternative scenarios live as biosimilar substitution protocols in Germany and Switzerland evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Glioblastoma Multiforme (GBM) Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Clarithromycin Market