
 Global Red Biotechnology Market | 2026-2036
Global Red Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Red Biotechnology Market Foresight
Subscription-based access to biologics manufacturing platforms is hardening as a core revenue layer in red biotechnology. F. Hoffmann-La Roche Ltd leverages its diagnostics-biologics integration to control end-to-end patient identification and therapy delivery. Amgen Inc. anchors its position through in-house production of biosimilar and novel biologic active ingredients. Pfizer Inc. extends its reach via contract manufacturing partnerships that sustain capacity utilization across multi-product facilities.
Red biotechnology encompasses the application of recombinant DNA, cell fusion, and bioprocessing techniques to develop therapeutic proteins, vaccines, and cell-based treatments, typically requiring mammalian or microbial expression systems operating under strict temperature, pH, and sterility parameters. Its primary commercial purpose centers on producing medicines that target specific disease mechanisms at the molecular level with reduced off-target effects compared to small-molecule drugs. Monoclonal antibodies occupy the largest revenue pool due to established manufacturing infrastructure and broad oncology and autoimmune indications. Cell therapies represent the fastest-expanding segment, driven by CAR-T approvals and emerging allogeneic platforms that promise off-the-shelf administration. Recombinant proteins maintain mature, margin-compressed positioning as biosimilar competition intensifies across insulin, growth factors, and blood-clotting factors.
The FDA's accelerated approval framework and the EMA's PRIME designation scheme compress development timelines for breakthrough biologics while raising post-market evidence requirements. China's NMPA has aligned its biologics review standards with ICH guidelines, enabling multinational sponsors to leverage unified clinical datasets across regulatory jurisdictions. REACH and the EU GMP Annex 1 revision impose escalating purity and environmental release standards on biologics manufacturing operations. Stakeholders must monitor how regulator convergence on real-world evidence requirements reshapes investment priorities across early-stage pipeline assets.
Market Dynamics
Cell therapy manufacturing is electrifying capacity allocation decisions as autologous production workflows demand facility designs incompatible with traditional biologics infrastructure, forcing sponsors to choose between captive investment and contract manufacturing reliance.
Growth Catalysts
- FDA Accelerated Approval:Compressed development timelines for breakthrough biologics pull venture capital into early-stage oncology pipelines. Sponsors exploit post-market evidence requirements to secure conditional commercialization.
- Allogeneic Platform Maturation:Off-the-shelf CAR-T manufacturing promises batch-scale economics unavailable in patient-specific autologous systems. Contract manufacturers in Germany and Singapore are expanding dedicated cleanroom suites.
- China NMPA Harmonization:Alignment with ICH guidelines enables multinational sponsors to submit unified clinical datasets across regulatory jurisdictions, reducing duplicate trial expenditure.
Market Restraints
- Plasma Supply Concentration:Fractionation feedstock availability constrains recombinant protein output. Collection infrastructure clusters in the United States and Germany, exposing manufacturers to geographic supply disruption.
- EU GMP Annex 1 Revision:Escalating sterility assurance and environmental release standards force facility retrofitting. Legacy mammalian cell culture suites face compliance-driven obsolescence.
- Biosimilar Price Compression:Insulin and growth factor markets face margin erosion from interchangeable substitutes. Reference product sponsors are defending position through device-drug combination patents.
Strategic Opportunities
- India CDMO Expansion:Underpenetrated biologics manufacturing capacity offers cost arbitrage for late-stage process development. BIS certification alignment with WHO prequalification standards enables export qualification.
- Continuous Bioprocessing Convergence:Perfusion cell culture integrated with single-use downstream purification compresses batch cycle time. Equipment vendors are bundling integrated platform sales with process analytical technology.
- Japan PMDA Sakigake Designation:Priority review incentives for regenerative medicines accelerate reimbursement negotiation timelines. Domestic sponsors leverage early approval to secure hospital formulary placement.
Industry Challenges
- Vector Manufacturing Bottleneck:Viral plasmid production capacity scarcity delays gene therapy IND filings. Specialized transient transfection expertise concentrates among a limited supplier base.
- Cross-Border Cold Chain Integrity:Cell therapy logistics require liquid nitrogen vapor-phase maintenance across multiple customs jurisdictions. Temperature excursion liability allocation remains unresolved in standard contract terms.
- Analytics Standardization Delays:Potency assay variability between contract testing laboratories complicates comparability studies. Reference standard harmonization across FDA, EMA, and NMPA jurisdictions remains incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Red Biotechnology Market |
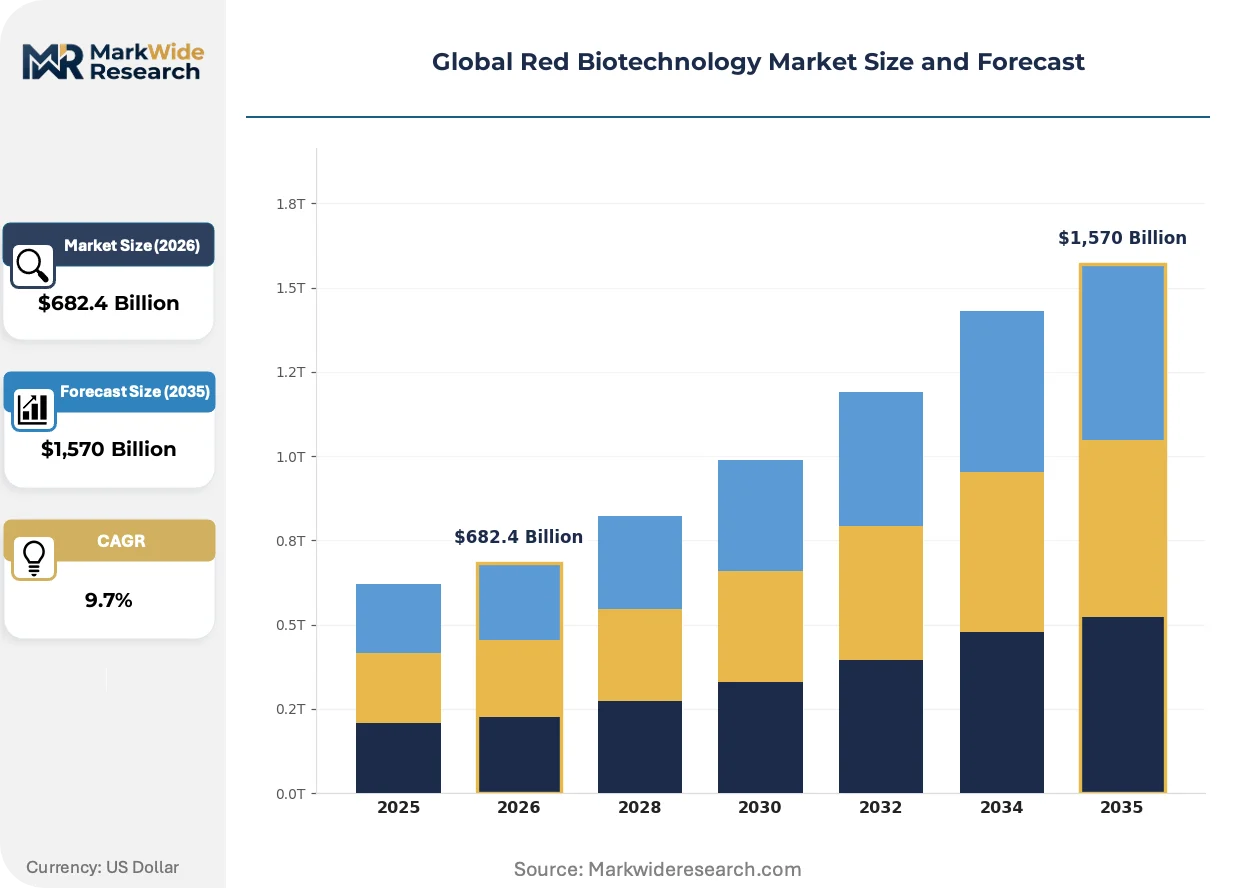
| Market Size in 2026 | $682.4 Billion |
| Market Size in 2035 | $1,570 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Cell Therapies, Recombinant Proteins, Antibiotics Therapy Area: Oncology, Infectious Diseases, Autoimmune Disorders, Genetic Disorders, Cardiovascular Diseases End User: Biopharmaceutical Companies, Contract Research Organizations, Diagnostic Laboratories, Blood Banks, Clinical Research Institutes Delivery Mode: Injectable, Oral, Topical, Inhalation, Transdermal |
| Companies Covered | F. Hoffmann-La Roche Ltd, Amgen Inc., Pfizer Inc., Merck KGaA, Gilead Sciences, Inc., AstraZeneca, Regeneron Pharmaceuticals, Inc., Biogen, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Red Biotechnology Market Shifts & Advancements
Manufacturing modality diversification is fragmenting competitive positioning as microbial expression, mammalian cell culture, and emerging cell-free systems each capture distinct therapeutic niches based on glycosylation complexity requirements.
Single-use bioreactor technology is electrifying facility deployment economics by eliminating stainless steel cleaning validation cycles. Emerging market sponsors in Brazil and South Korea are adopting skid-mounted production trains to compress capital deployment timelines. This shift enables distributed manufacturing networks that reduce cold chain dependency for temperature-sensitive cell therapies.
REACH substance registration requirements are forcing re-evaluation of chromatography resin chemistries and buffer additive compositions. Suppliers are reformulating proprietary ligands to eliminate candidate substances of very high concern. Downstream process developers in the Netherlands and Switzerland are prioritizing aqueous two-phase extraction methods to reduce organic solvent dependency.
Hospital-based point-of-care manufacturing is disrupting centralized production models for autologous cell therapies. Academic medical centers in the United States and Germany are installing closed-system processing devices to compress vein-to-vein timelines. This decentralization challenges traditional batch release and quality oversight workflows designed for large-scale centralized facilities.
Global Red Biotechnology Market Segmentation
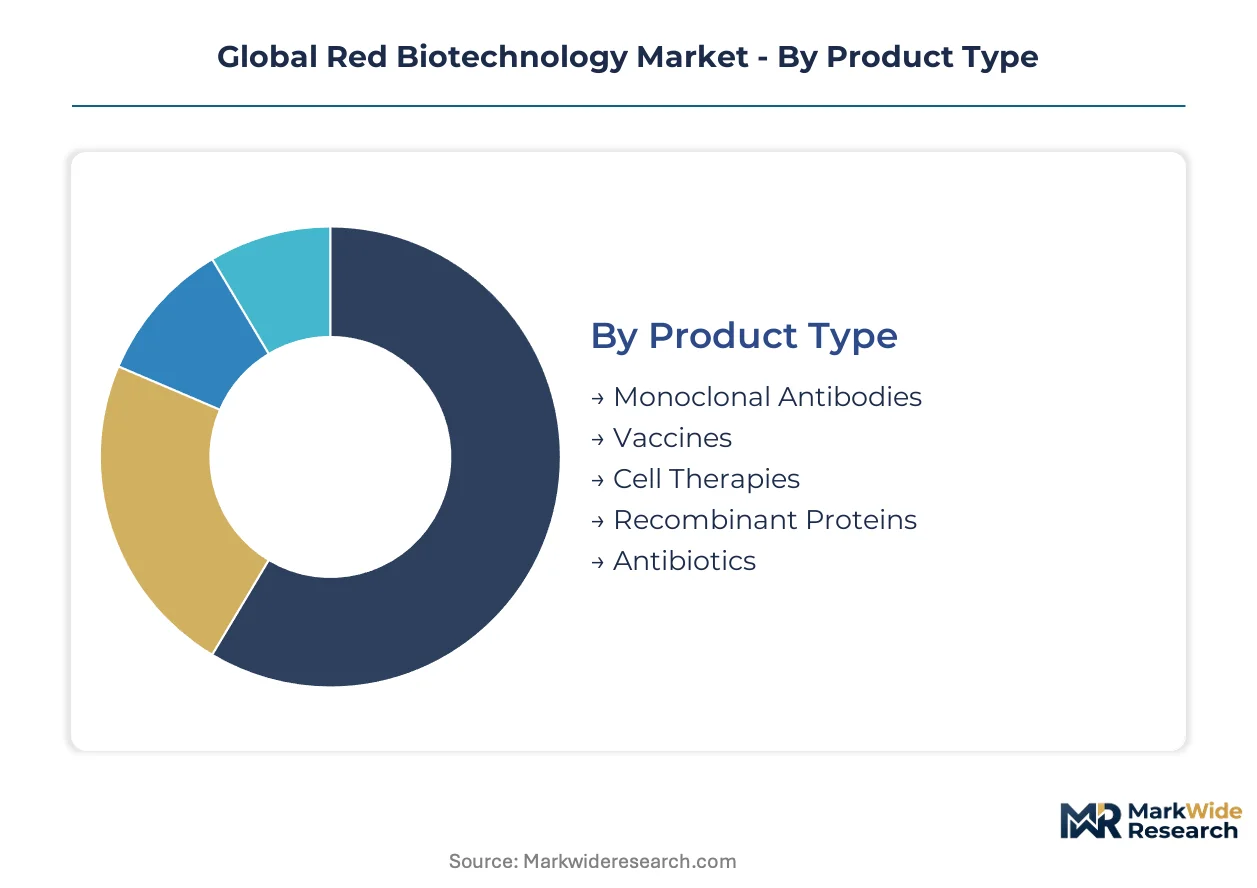
Red biotechnology markets fragment across therapeutic modality, clinical application, and delivery infrastructure. Each segmentation dimension reveals distinct margin structures, regulatory pathways, and capacity investment requirements that reshape competitive entry decisions.
Product Type:
Upgrade cycles in manufacturing technology are compressing facility depreciation schedules as sponsors replace stainless steel trains with single-use platforms.
- Monoclonal Antibodies:Glycosylated proteins produced in mammalian cell culture with established purification trains using protein A affinity chromatography. Demand clusters in the United States and Germany for oncology and autoimmune indications as biosimilar competition forces reference product sponsors toward subcutaneous formulation innovations.
- Cell Therapies:Living medicinal products requiring cryopreserved logistics and patient-specific or allogeneic manufacturing workflows. CAR-T demand concentrates in academic medical centers across the United States and China, with allogeneic platforms promising batch-scale economics that autologous systems cannot match.
- Vaccines:Antigen-based immunization products spanning recombinant protein subunits to live-attenuated viral vectors.
- Recombinant Proteins:Engineered hormones, growth factors, and clotting factors produced in microbial or mammalian systems.
- Antibiotics:Fermentation-derived antibacterial agents facing pricing pressure from generic substitution.
Monoclonal antibodies sit at the top of the volume ranking, with cell therapies climbing the fastest.
Therapy Area:
Cost tier differentiation separates premium-priced orphan indications from mass-market chronic disease therapies with compressed reimbursement.
- Oncology:Tumor-targeting biologics spanning checkpoint inhibitors to personalized cancer vaccines. Precision medicine infrastructure in the United States and Switzerland concentrates demand as companion diagnostic integration becomes mandatory for reimbursement.
- Autoimmune Disorders:Anti-inflammatory biologics targeting TNF-alpha, interleukin pathways, and B-cell depletion mechanisms. Rheumatology and dermatology practices in Germany and Japan drive volume as earlier intervention protocols expand eligible patient pools.
- Infectious Diseases:Prophylactic and therapeutic countermeasures against viral and bacterial pathogens.
- Genetic Disorders:Gene replacement and editing therapies for monogenic conditions.
- Cardiovascular Diseases:Anticoagulant and lipid-modifying biologics with mature competitive dynamics.
Oncology commands the premium pricing tier, with genetic disorders posting the steepest expansion trajectory.
End User:
Customer type determines procurement scale, with integrated biopharmaceutical sponsors capturing manufacturing economies unavailable to fragmented research service buyers.
- Biopharmaceutical Companies:Integrated drug developers with captive manufacturing capacity and in-house clinical trial infrastructure. Capacity utilization pressures in the United States and China are forcing portfolio rationalization toward higher-margin biologics.
- Contract Research Organizations:Externalized service providers managing clinical development and regulatory submission workflows. Sponsor demand in Germany and Singapore concentrates on vendors with integrated cell therapy logistics capabilities.
- Diagnostic Laboratories:Testing facilities requiring companion diagnostic reagents and reference standards.
- Blood Banks:Collection and processing centers for plasma-derived therapeutics.
- Clinical Research Institutes:Academic centers conducting investigator-initiated trials and early-phase studies.
Biopharmaceutical companies anchor procurement volume, with contract research organizations gaining share fastest.
Delivery Mode:
Supply concentration in sterile injectable manufacturing is reshaping facility investment priorities as oral biologic formulations remain technically constrained.
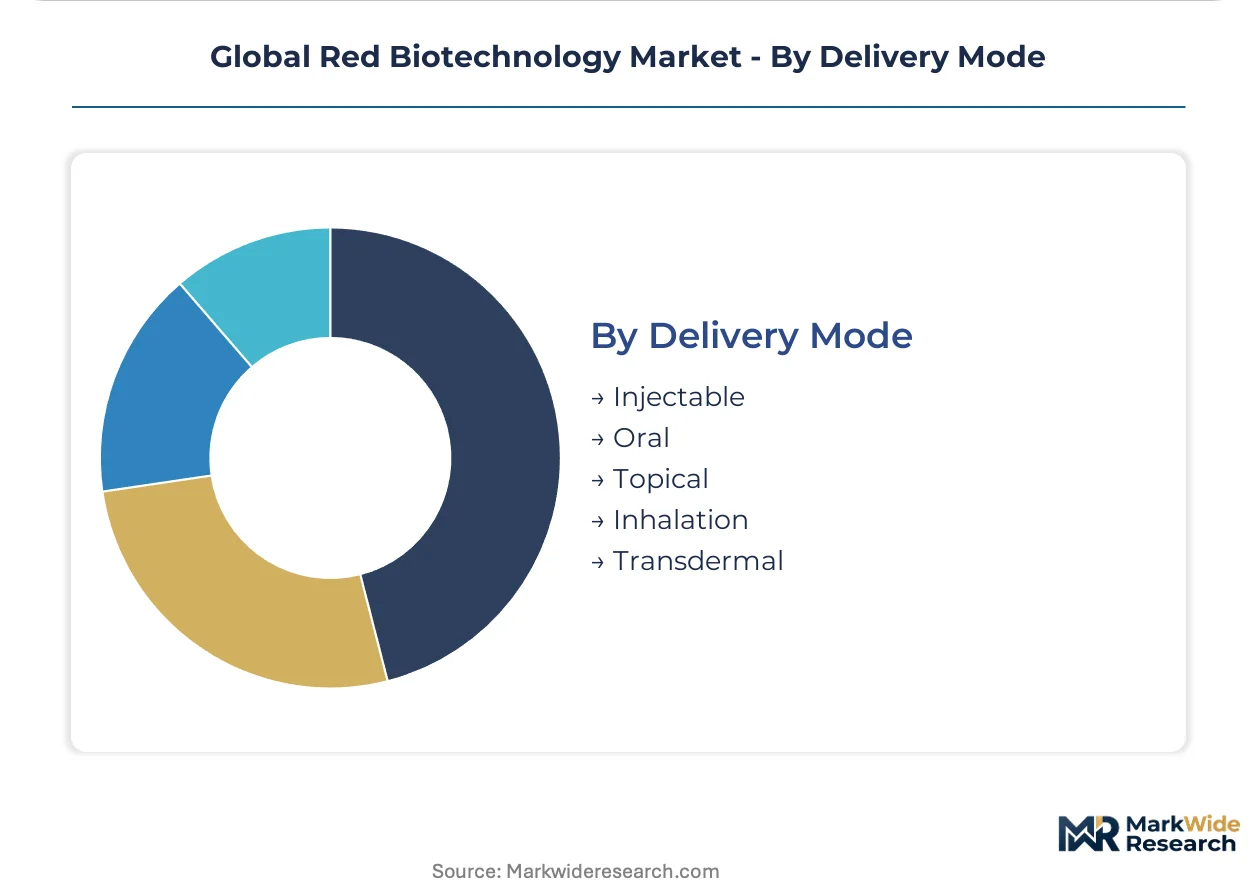
- Injectable:Parenteral administration via intravenous infusion or subcutaneous injection for large-molecule biologics. Aseptic fill-finish capacity in the United States, Ireland, and Switzerland concentrates production as regulatory scrutiny of particulate contamination intensifies.
- Oral:Gastrointestinal delivery systems for peptide and protein formulations with limited bioavailability. Formulation innovation in Japan targets permeation enhancers that bypass enzymatic degradation.
- Topical:Dermal and mucosal application for localized therapeutic effects.
- Inhalation:Pulmonary delivery for respiratory-targeted biologics.
- Transdermal:Microneedle and patch systems for sustained release.
Injectable dominates current volume, with transdermal platforms advancing most quickly toward commercial viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA harmonization with ICH guidelines has compressed trial timelines faster than Germany's EMA-aligned processes, yet both markets now compete for autologous cell therapy manufacturing investment.
United States
FDA accelerated approval pathways pull venture capital into early-stage oncology pipelines. The agency's post-market evidence requirements allow conditional commercialization for breakthrough biologics. Academic medical centers in Boston and the San Francisco Bay Area are installing closed-system processing devices to compress vein-to-vein timelines for CAR-T therapies.
Germany
Contract manufacturers in Frankfurt and Munich are expanding dedicated cleanroom suites for allogeneic platform production. The EU GMP Annex 1 revision forces facility retrofitting with escalating sterility assurance standards. Legacy mammalian cell culture suites in the Rhine-Ruhr region face compliance-driven obsolescence as sponsors shift toward single-use platforms.
China
Multinational sponsors leverage unified clinical datasets across regulatory jurisdictions after NMPA alignment with ICH guidelines. Shanghai and Suzhou host the largest clinical trial infrastructures for advanced therapeutic medicinal products. Domestic biopharmaceutical companies are rationalizing portfolios toward higher-margin biologics amid capacity utilization pressures.
Japan
PMDA Sakigake designation accelerates reimbursement negotiation timelines for regenerative medicines. Domestic sponsors secure hospital formulary placement through early approval pathways. The Kanto region around Tokyo concentrates precision medicine infrastructure as companion diagnostic integration becomes mandatory for reimbursement.
India
Underpenetrated biologics manufacturing capacity offers cost arbitrage for late-stage process development. BIS certification alignment with WHO prequalification standards enables export qualification. Hyderabad and Bangalore are attracting contract manufacturing partnerships as sponsors seek to sustain capacity utilization across multi-product facilities.
Global Red Biotechnology Market Competitive Landscape
Top-tier vendors anchor diagnostics-biologics integration, while mid-tier specialists compete on manufacturing modality diversification. The vendor base clusters around three strategic archetypes: integrated pharmaceutical conglomerates with captive manufacturing, pure-play biologics innovators with specialized expression systems, and contract manufacturers offering subscription-based platform access. Dominant competitive moves include facility retrofitting for EU GMP Annex 1 compliance and geographic expansion into underpenetrated CDMO markets.
Among Swiss and German-based pharmaceutical groups, F. Hoffmann-La Roche Ltd and Merck KGaA exemplify the integrated archetype through end-to-end control from patient identification to therapy delivery. Amgen Inc. represents the in-house production model with captive supply of biosimilar and novel biologic active ingredients. These three entities occupy positions that reflect contrasting responses to cell therapy manufacturing electrification and allogeneic platform maturation.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Amgen Inc. |
| Pfizer Inc. |
| Merck KGaA |
| Gilead Sciences, Inc. |
| AstraZeneca |
| Regeneron Pharmaceuticals, Inc. |
| Biogen |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply & Pricing Matrix
Single-use bioreactor adoption across the United States, Germany, and China is compressing capital deployment timelines while fragmenting supplier power toward equipment vendors and resin chemists. This manufacturing modality shift simultaneously lowers facility entry costs and concentrates critical consumables sourcing among a limited vendor base.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for contract manufacturing services as sponsors exploit cost arbitrage for late-stage process development. Pricing stratifies across premium GMP-certified, standard FDA-aligned, and economy BIS-qualifying tiers based on sterility assurance levels and regulatory jurisdiction. Cost compression in recombinant protein segments is intensifying because biosimilar substitution erodes reference product margins. Emerging biopharmaceutical sponsors exhibit highest price sensitivity, while established oncology developers prioritize regulatory speed over unit cost.
Supply Chain Analysis
FDA, EMA, and NMPA GMP certification gating concentrates plasma collection infrastructure in the United States and Germany, exposing fractionation output to geographic supply disruption. Viral vector production draws from specialized transient transfection expertise, chromatography resin chemistries, and cryopreserved logistics networks. Single-source vulnerability permeates plasmid supplier tiers where transient transfection expertise concentrates among limited contract manufacturers. Distribution runs through cold chain specialists maintaining liquid nitrogen vapor-phase integrity across customs jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Red Biotechnology Market functions as a stable compounder anchored by irreversible therapeutic modality shifts toward cell-based and gene-based interventions that command durable pricing power.
For Market Incumbents: Lock in autologous manufacturing capacity through captive facility investment or exclusive contract manufacturing partnerships before allogeneic platforms commoditize patient-specific workflows. Defend against biosimilar erosion by accelerating subcutaneous formulation innovations and companion diagnostic integration that raises switching costs for payers. For New Entrants and Emerging Players: Begin with underpenetrated allogeneic platform development targeting solid tumor indications where CAR-T efficacy remains limited. India and Brazil offer the most penetrable CDMO geography for sponsors seeking WHO prequalification-aligned capacity. A licensing-first go-to-market angle minimizes capital intensity while securing downstream offtake commitments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier contract manufacturers with EU GMP Annex 1 retrofit completion and established cell therapy logistics capabilities. Long-term viability hinges on positioning ahead of regenerative medicine reimbursement standardization across Japan, Germany, and the United States. Watch FDA breakthrough therapy designation velocity as an inflection indicator for venture deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Allogeneic Platform Maturation | Batch-scale economics promise manufacturing margins unavailable in autologous systems. |
| EU GMP Annex 1 Compliance Retrofit | Facility upgrading separates viable contract manufacturers from compliance-driven obsolescence. |
| Companion Diagnostic Integration | Precision medicine infrastructure in the United States and Japan secures reimbursement access. |
| Continuous Bioprocessing Adoption | Perfusion culture integrated with single-use purification compresses batch cycle times. |
| Point-of-Care Manufacturing Deployment | Hospital-based closed-system processing disrupts centralized autologous production models. |
Research Methodology
Bottom-up therapeutic modality modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers were validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Secondary sources include customs data on biologics trade flows, SEC 10-K disclosures from listed biopharmaceutical sponsors, and WHO prequalification status reports.
Input-output matrices map patient population incidence, treatment penetration rates, and pricing trajectories across oncology, autoimmune, and genetic disorder segments. The projection horizon spans therapeutic modality evolution from monoclonal antibodies through cell therapies to gene editing platforms. CAGRs were derived from facility capacity expansion announcements, clinical trial initiation velocities, and reimbursement approval timelines. Forecast inputs incorporate regulatory pathway acceleration under FDA breakthrough therapy and EMA PRIME designations.
Caveats apply where vector manufacturing bottlenecks, cross-border cold chain failures, or potency assay standardization delays could materially shift the outlook. Forecasts reflect assumptions regarding allogeneic platform technical maturation and sustained plasma collection infrastructure stability. A model refresh is warranted upon material change in FDA accelerated approval evidentiary requirements or NMPA biologics review timeline convergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Gestational Trophoblastic Disease Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Antimicrobial Peptides Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Testicular Cancer Drugs Market