
 Europe Cancer Biomarkers Market | 2026-2036
Europe Cancer Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cancer Biomarkers Market Foresight
Specialized molecular pathology talent is bifurcating the competitive landscape across Europe. F. Hoffmann-La Roche Ltd leverages its centralized diagnostics infrastructure to sustain high-throughput biomarker testing across multiple EU member states. Thermo Fisher Scientific anchors its position through deep R&D partnerships with academic medical centers in France and the Netherlands. bioMérieux differentiates through specialized microbiology-oncology crossover assays that occupy niche clinical workflows.
Cancer biomarkers are measurable biological molecules—proteins, genetic sequences, metabolites, or epigenetic modifications—detected in tissue, blood, or other body fluids that indicate normal or pathological processes, with specificity thresholds typically exceeding 85% for clinical-grade assays. Their primary purpose is to enable early cancer detection, stratify patient risk, monitor therapeutic response, and guide targeted therapy selection in precision oncology. Genetic biomarkers lead the product landscape due to their direct linkage to actionable oncogenic mutations, while next-generation sequencing commands the technology tier as the dominant platform for multiplexed genomic profiling in comprehensive cancer panels. Protein biomarkers retain substantial volume in routine clinical laboratories, though metabolomic biomarkers represent the fastest-emerging segment for early-stage screening applications.
The European Medicines Agency oversees biomarker qualification through its novel methodologies pathway, while the EU In Vitro Diagnostic Regulation mandates stricter clinical evidence standards for companion diagnostics. REACH and GDPR impose parallel obligations on reagent chemical safety and patient genomic data handling that reshape product development timelines. Stakeholders must monitor how EMA biomarker qualification decisions intersect with national health technology assessment processes to anticipate reimbursement access for new assay platforms.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing product development timelines while liquid biopsy platforms fragment testing workflows across European clinical networks. This regulatory-pressure-technology-tension is forcing assay developers to restructure evidence-generation strategies.
Growth Catalysts
- IVDR Compliance Mandate:The EU In Vitro Diagnostic Regulation drives laboratories toward certified companion diagnostic platforms, accelerating replacement of legacy LDTs with standardized assays.
- Liquid Biopsy Expansion:Non-invasive circulating tumor DNA testing is penetrating Germany's precision oncology networks, enabling serial monitoring without repeated tissue biopsies.
- Academic-Industry Partnerships:French and Dutch medical centers are co-developing next-generation sequencing panels, transferring research-grade biomarkers into clinical workflows.
Market Restraints
- Reagent Supply Concentration:Polymerase and nucleotide supply chains concentrate among North American and Asian specialty chemical suppliers, exposing European assay manufacturers to input volatility.
- Technical Validation Burden:The EMA's novel methodologies pathway demands extensive analytical and clinical performance data, extending qualification timelines for novel biomarker classes.
- Substitution Risk from Imaging:Advanced radiomics and functional MRI techniques compete for early detection applications, particularly in lung and liver cancer screening programs.
Strategic Opportunities
- Metabolomic Screening White Space:Untapped demand for pre-symptomatic detection in Poland and Romania creates openings for volatile organic compound breath-based assays.
- GDPR-Compliant Data Architectures:Federated learning platforms that process genomic data without centralization address privacy constraints while enabling multi-site biomarker discovery.
- Microbiome-Oncology Convergence:Gut microbiota signatures as immunotherapy response predictors represent an emerging application with limited competing assay developers.
Industry Challenges
- Bioinformatics Talent Scarcity:European molecular pathology programs produce insufficient computational biologists to interpret complex multi-omics outputs at scale.
- Legacy LDT Integration Friction:Hospital laboratories face technical debt from decades of in-house assay development that resists standardization onto regulated IVD platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cancer Biomarkers Market |
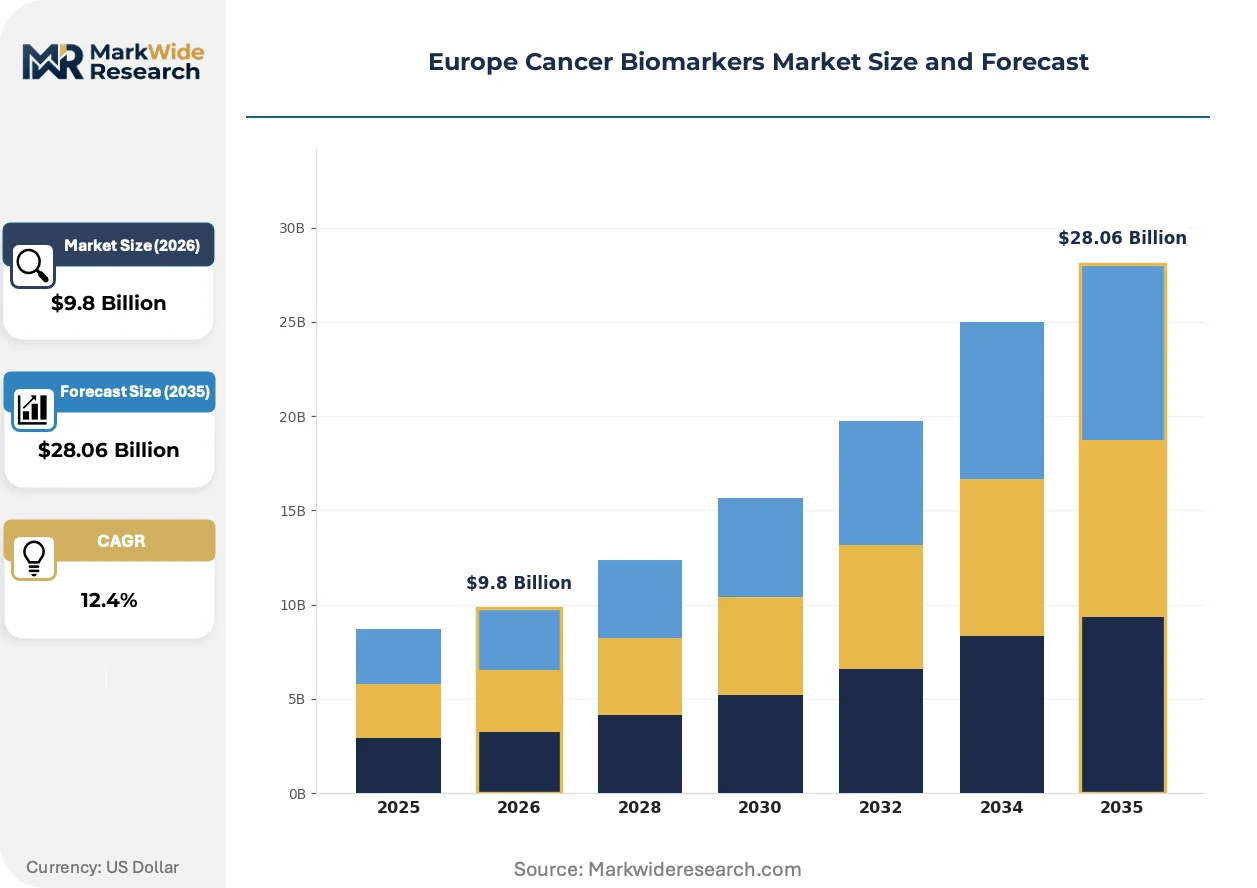
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $28.06 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Biomarkers, Genetic Biomarkers, Metabolomic Biomarkers, Epigenetic Biomarkers Technology: Next-Generation Sequencing, ELISA, PCR, Microarrays End User: Clinical Laboratories, Research Institutes, Hospitals, Diagnostics Centers Application: Early Detection, Prognosis, Treatment Monitoring, Drug Development |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Thermo Fisher Scientific, Illumina, bioMérieux, QIAGEN, Agilent Technologies, Hologic, Bio-Rad Laboratories, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cancer Biomarkers Market Shifts & Advancements
Multiplexed genomic profiling is fragmenting the traditional single-analyte testing paradigm while regulatory data requirements reshape competitive moats. Three convergent forces are redefining how biomarker value is captured and delivered.
Next-generation sequencing is decomposing the centralized reference laboratory model that dominated cancer diagnostics for two decades. Community hospitals in the United Kingdom and Spain are adopting benchtop sequencers, enabling same-day turnaround for comprehensive genomic profiling. This distributed architecture compresses logistics costs while fragmenting volume among smaller testing sites.
REACH chemical safety regulations are forcing reagent manufacturers to reformulate buffer compositions and stabilizing chemistries. The European Chemicals Agency's substance restrictions extend to nucleic acid extraction kits and sequencing reagents, requiring reformulation of established product lines. Assay developers in Germany and France are responding by qualifying alternative chemistries ahead of sunset dates.
Oncology departments are unbundling biomarker testing from pharmaceutical procurement decisions, creating independent assay selection committees. This governance shift transfers purchasing authority from pathology directors to tumor board clinicians who prioritize turnaround time and actionability. The Netherlands and Denmark exhibit the most advanced manifestations of this behavioral change, with formalized biomarker stewardship programs.
Europe Cancer Biomarkers Market Segmentation
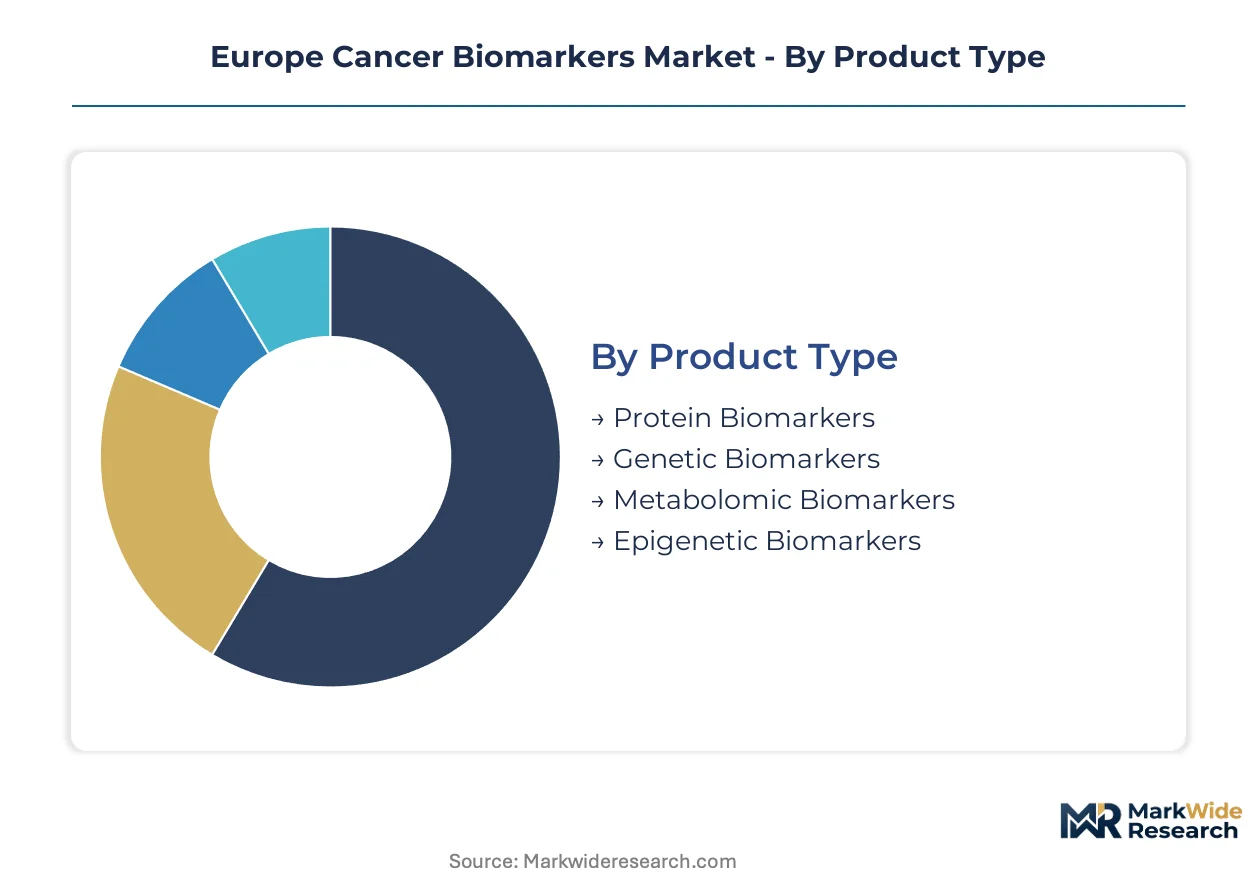
Biomarker segmentation in Europe reflects divergent regulatory pathways and reimbursement logic across product categories. Assay developers must align portfolio investments with IVDR certification timelines and national health technology assessment criteria.
Product Type:
Substitution pressure from liquid biopsy platforms and radiomics imaging varies sharply across molecular classes, forcing strategic repositioning.
- Genetic Biomarkers:DNA sequence variations and copy number alterations detectable through circulating tumor DNA or tissue biopsy. German precision oncology networks concentrate demand for comprehensive genomic profiling panels that guide targeted therapy selection. EMA companion diagnostic requirements compress development timelines for novel mutation assays.
- Protein Biomarkers:Circulating proteins and tissue-expressed antigens measured through immunoassay platforms. Routine clinical laboratories across France and the United Kingdom retain substantial volume for PSA, CA-125, and HER2 testing despite genomic displacement pressure.
- Metabolomic Biomarkers:Small-molecule metabolites and volatile organic compounds detectable in breath or biofluids. Emerging screening applications in Poland and Romania drive pilot programs for pre-symptomatic detection.
- Epigenetic Biomarkers:DNA methylation patterns and histone modifications indicating transcriptional state changes. Research-grade applications dominate current utilization pending analytical validation.
Genetic biomarkers anchor the volume base while metabolomic biomarkers gain share at the steepest rate.
Technology:
Capital intensity and technical workforce requirements fragment adoption patterns across European healthcare systems.
- Next-Generation Sequencing:Massively parallel sequencing platforms enabling multiplexed genomic profiling. Community hospitals in the United Kingdom and Spain deploy benchtop instruments for same-day turnaround, compressing logistics costs while fragmenting testing volume.
- PCR:Polymerase chain reaction for targeted mutation detection with rapid turnaround. French and Dutch diagnostics centers standardize on qPCR for single-gene companion diagnostics with established reimbursement codes.
- ELISA:Enzyme-linked immunosorbent assay for protein quantification in high-throughput workflows. Legacy installations in German hospital laboratories resist displacement despite genomic platform expansion.
- Microarrays:Hybridization-based detection for copy number variation and gene expression profiling. Academic medical centers in the Netherlands maintain specialized applications for research-to-clinical translation.
PCR retains the installed base while next-generation sequencing expands most quickly through distributed deployment models.
End User:
Procurement authority migration from pathology directors to tumor board clinicians restructures purchasing criteria across site types.
- Clinical Laboratories:Independent and hospital-affiliated sites performing routine biomarker testing. IVDR compliance investments accelerate consolidation of legacy LDTs onto certified IVD platforms.
- Hospitals:Integrated delivery networks with in-house molecular pathology capabilities. United Kingdom NHS trusts and Spanish hospital groups adopt decentralized sequencing to reduce send-out volumes.
- Research Institutes:Academic centers conducting biomarker discovery and clinical validation. French and Dutch medical centers transfer research-grade panels into clinical workflows through EMA novel methodologies pathways.
- Diagnostics Centers:Specialized outpatient facilities focused on cancer screening and monitoring. German precision oncology networks concentrate liquid biopsy demand in centralized reference models.
Clinical laboratories anchor the volume base while hospitals gain share at the steepest rate through in-house platform investments.
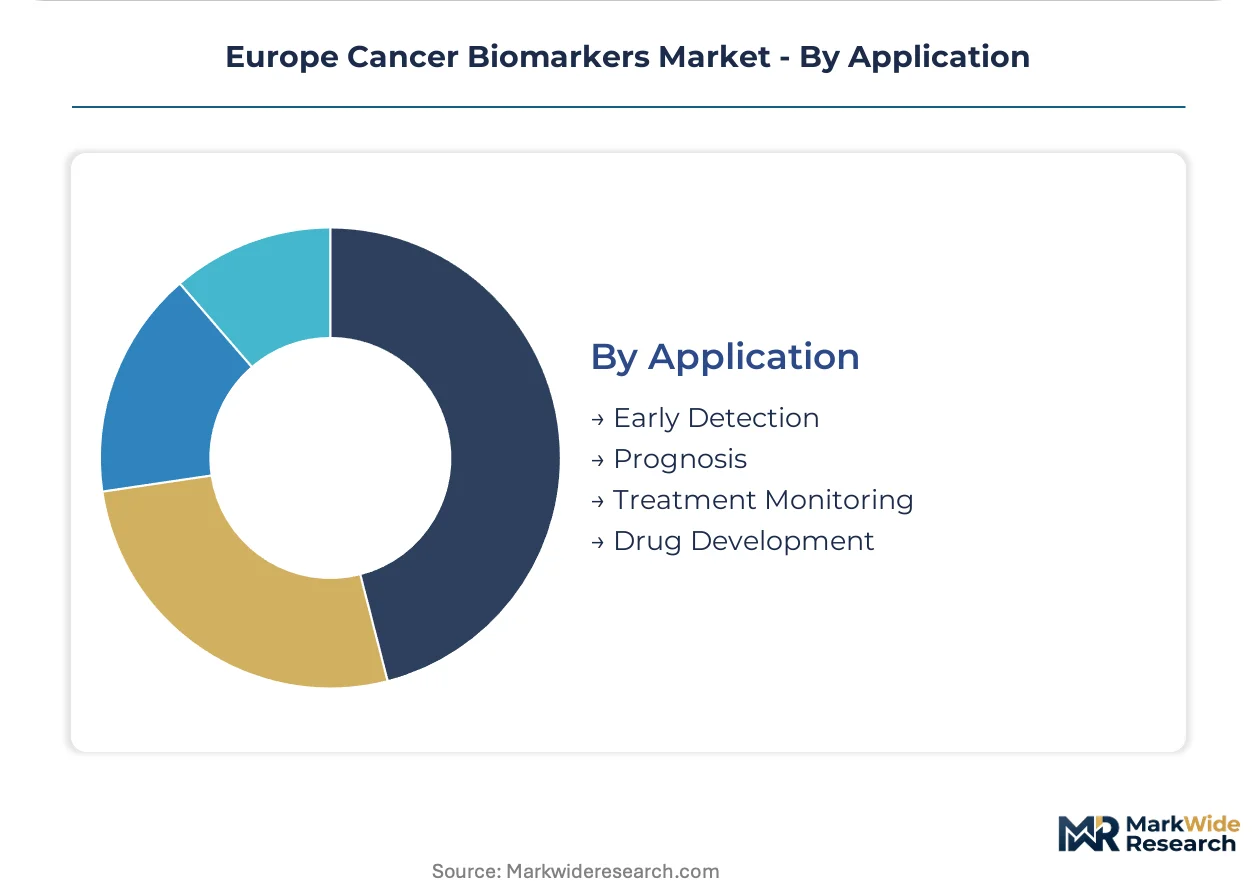
Application:
Reimbursement granularity and evidence requirements vary across clinical use cases, shaping assay development prioritization.
- Early Detection:Population screening and high-risk patient monitoring for pre-symptomatic identification. Metabolomic and circulating tumor DNA approaches compete with established imaging programs in lung and liver cancer.
- Treatment Monitoring:Serial biomarker measurement to assess therapeutic response and resistance emergence. Liquid biopsy platforms enable Germany's precision oncology networks to track clonal evolution without repeated tissue sampling.
- Prognosis:Risk stratification for disease recurrence and survival prediction. Multi-gene expression signatures face health technology assessment scrutiny for incremental value demonstration.
- Drug Development:Biomarker-driven patient selection and pharmacodynamic assessment in clinical trials. EMA qualification pathways support novel methodology adoption for regulatory submissions.
Treatment monitoring anchors the volume base while early detection climbs the fastest through screening program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Medicines Agency anchors regulatory coordination across member states, while national health technology assessment bodies determine market access at the country level. Germany's precision oncology networks generate concentrated demand for companion diagnostic platforms. France and the Netherlands lead academic-industry translation partnerships.
Germany
Precision oncology networks in Munich and Heidelberg drive demand for comprehensive genomic profiling panels. The Federal Institute for Drugs and Medical Devices enforces IVDR compliance timelines that accelerate laboratory consolidation. Berlin-Brandenburg hosts centralized reference laboratories processing liquid biopsy volumes for serial monitoring applications.
France
Paris and Lyon academic medical centers co-develop next-generation sequencing panels with industrial partners. The National Agency for Food, Environmental and Occupational Health Safety oversees clinical trial frameworks for novel biomarker qualification. The Île-de-France cluster concentrates contract research organizations supporting EMA submission pathways.
United Kingdom
NHS trusts in London and Manchester adopt decentralized benchtop sequencers to reduce send-out volumes. The Medicines and Healthcare products Regulatory Agency manages post-Brexit divergence from EU regulatory frameworks. The Cambridge-Oxford corridor maintains specialized research-to-clinical translation infrastructure for multi-omics applications.
Netherlands
Rotterdam and Utrecht diagnostics centers pioneer biomarker stewardship programs that transfer purchasing authority to tumor board clinicians. The Healthcare Inspectorate monitors laboratory quality standards under IVDR implementation. The Randstad region concentrates hospital networks deploying federated learning architectures for GDPR-compliant genomic data processing.
Spain
Barcelona and Madrid hospital groups expand in-house molecular pathology capabilities to capture testing volume. The Spanish Agency for Medicines and Health Products coordinates with regional health authorities on companion diagnostic reimbursement. The Catalonia cluster specializes in circulating tumor DNA assay validation for treatment monitoring protocols.
Europe Cancer Biomarkers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on assay specificity and turnaround velocity. Swiss and American conglomerates anchor the upper tier through centralized diagnostics infrastructure and multi-omics platform portfolios. Mid-cap specialists differentiate through microbiology-oncology crossover applications or regional compliance expertise. Consolidation pressure intensifies as IVDR certification costs favor scaled evidence-generation capabilities. Strategic partnerships with academic medical centers and liquid biopsy technology licensing represent the dominant competitive vectors.
Among Swiss-anchored conglomerates, F. Hoffmann-La Roche Ltd occupies a position exemplifying centralized infrastructure leverage across multiple EU member states. Thermo Fisher Scientific and QIAGEN represent the American-German axis of platform specialists that anchor research-to-clinical translation partnerships in France and the Netherlands. These three entities exemplify distinct archetypes: the integrated diagnostics conglomerate, the multi-omics platform provider, and the sample-to-insight workflow specialist respectively.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Illumina |
| bioMérieux |
| QIAGEN |
| Agilent Technologies |
| Hologic |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German reference laboratories and North American reagent suppliers lock in polymerase access while fixing cost visibility across IVDR transition periods. These contracts insulate European assay developers from nucleotide spot-market volatility that would otherwise compress margins during regulatory recertification cycles.
Pricing Analysis
Geographic price spreads of 15-25% separate German precision oncology networks from Polish and Romanian screening programs. Three-tier pricing structure across premium, standard, and economy levels tracks IVDR certification status and turnaround velocity. Pricing pressure stems from REACH-mandated reagent reformulation costs that manufacturers pass downstream. Hospital laboratories exhibit highest price sensitivity due to fixed reimbursement codes, while pharmaceutical sponsors in drug development tolerate premium tiers for EMA-aligned data packages.
Supply Chain Analysis
Polymerase manufacturing concentration in the United States and South Korea creates single-source vulnerability for European assay kit producers. Nucleotides, fluorescent dyes, and magnetic bead chemistries draw from specialized chemical suppliers in China and Japan. Tariff exposure on Chinese-sourced raw materials intensifies as REACH substance restrictions sunset legacy formulations. Distribution runs through centralized reference laboratories in Berlin-Brandenburg and Munich that consolidate liquid biopsy volumes before downstream fragmentation to community sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Europe's cancer biomarkers landscape creates niche entry points as IVDR compliance bifurcates the installed base between certified IVD platforms and legacy LDTs. The migration of procurement authority from pathology directors to tumor board clinicians opens behavioral segmentation opportunities.
For Market Incumbents: Secure centralized diagnostics infrastructure in Germany and France through capacity reservation contracts with precision oncology networks. Threats from benchtop sequencer displacement in United Kingdom NHS trusts demand countermeasures through same-day turnaround service-level guarantees. Backward integration into reagent formulation buffers REACH-driven input cost volatility. For New Entrants and Emerging Players: Differentiate on metabolomic screening white space in Poland and Romania where breath-based volatile organic compound assays face limited incumbent competition. The pre-symptomatic detection application remains penetrable through GDPR-compliant federated learning architectures that address privacy constraints without centralization. Go-to-market traction requires EMA novel methodologies pathway navigation partnerships with French academic medical centers. For Investors and Strategic Acquirers: Liquid biopsy technology licensors with validated circulating tumor DNA platforms represent the acquisition target archetype with strongest strategic optionality. Long-term viability across the analysis window hinges on biomarker stewardship program adoption in Netherlands and Denmark hospital networks. Watch for IVDR certification completion rates as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Certification Pathway | EMA companion diagnostic requirements compress timelines for novel mutation assay commercialization. |
| Academic Medical Center Partnership | French and Dutch research-to-clinical translation pipelines feed qualified biomarker panels into regulated workflows. |
| Liquid Biopsy Technology Licensing | Circulating tumor DNA platforms enable serial monitoring without repeated tissue sampling in German networks. |
| GDPR-Compliant Data Architecture | Federated learning platforms process genomic data without centralization across Netherlands hospital networks. |
| REACH-Aligned Reagent Reformulation | European Chemicals Agency substance restrictions force buffer chemistry qualification ahead of sunset dates. |
Research Methodology
A standing panel of molecular pathology laboratory directors, EMA regulatory affairs specialists, hospital procurement managers, and precision oncology network coordinators provided ongoing calibration across primary fieldwork. Secondary validation drew from EMA qualification pathway documentation, EU IVDR implementation guidance, ClinicalTrials.gov biomarker-driven trial records, and national health technology assessment body reimbursement determinations. Bottom-up assay volume modeling triangulated against top-down market sizing from reagent manufacturer disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by biomarker class, technology platform, end-user site type, and clinical application, with additional modeling of IVDR certification status tiers. CAGRs derived from logistic diffusion curves fitted to platform adoption patterns in United Kingdom and Spanish community hospital settings. Forecast inputs incorporated liquid biopsy penetration assumptions and radiomics substitution elasticity in lung cancer screening programs.
Forecasts assume regulatory continuity in EMA biomarker qualification and EU IVDR enforcement regimes; material policy shifts would require re-modeling of laboratory consolidation trajectories. Specific risk factors include REACH substance restriction expansion, single-source reagent supply disruptions, and health technology assessment body rejection of multi-gene expression signatures. Practitioners should keep alternative scenarios live as IVDR transition timelines and national reimbursement decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Pharmacogenomics Technology Market
Genomics
North America Genetic Testing Market
Genomics
Global Metagenomics Market
Genomics
Genomics Personalized Health Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Global Microarray Analysis Market
Genomics
Genetic Material Market
Genomics
Tumor-Sequencing Blood Testing Market
Genomics
Next Generation Sequencing (NGS) Informatics Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Oligonucleotide Pool Market
Genomics
Next Generation Molecular Assay Market
Genomics
Sequencing Electrophoresis Systems Market
Genomics
Molecular Biomarkers for Cancer Detection Market