
 Germany Computational Biology Market | 2026-2036
Germany Computational Biology Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Computational Biology Market Insights
The gap between enterprise-grade computational platforms and open-source toolkits is repositioning procurement patterns across German life sciences. Thermo Fisher Scientific leverages integrated instrument-software bundles to anchor high-throughput genomics workflows in major research clusters. QIAGEN competes through specialized sample-to-insight pipelines that dominate clinical bioinformatics. Certara sustains its position with mechanistic modeling expertise that pharmaceutical clients prize for regulatory submissions.
Computational biology applies algorithmic methods, statistical models, and high-performance computing infrastructure to analyze molecular datasets, predict protein structures, and simulate biological pathways at scale. Its primary purpose lies in compressing discovery timelines and reducing experimental failure rates across pharmaceutical and agricultural biotechnology. Drug discovery applications command the deepest investment pools, while machine learning capabilities are expanding fastest as German institutions adopt neural architectures for target deconvolution. Cloud-based deployment models are gaining traction among mid-sized biotechnology firms seeking elastic compute without capital-intensive infrastructure.
Germany's Federal Institute for Drugs and Medical Devices and the EU's EMA framework impose stringent validation standards on computational predictions used in regulatory filings, elevating demand for auditable software platforms. The EU AI Act introduces additional conformity requirements for high-risk AI applications in healthcare, compelling vendors to document training data provenance and model drift. Stakeholders must weigh the trade-off between proprietary platform depth and interoperable standards as procurement criteria harden across German research consortia.
Market Dynamics
Algorithmic drug discovery pipelines are compressing validation cycles across German pharmaceutical clusters, forcing vendors to rebuild software architectures around EU AI Act conformity requirements and auditable model provenance standards.
Growth Catalysts
- EU AI Act Conformity Pathways:The EU AI Act mandates documentation standards for high-risk healthcare algorithms, creating procurement pull for platforms with built-in audit trails across Berlin and Munich research consortia.
- Cloud Elasticity for Mid-Sized Biotech:German biotechnology firms with limited capital budgets are adopting SaaS deployment models to access high-performance compute without infrastructure ownership.
- Mechanistic Modeling Demand:Pharmaceutical sponsors require physiologically-based pharmacokinetic simulations for regulatory submissions to Germany's Federal Institute for Drugs and Medical Devices.
Market Restraints
- Specialized Talent Scarcity:The intersection of molecular biology and machine learning expertise remains concentrated in Heidelberg and Munich academic clusters, constraining vendor scaling.
- Validation Cost Burden:EMA-aligned documentation requirements for computational predictions impose multi-year qualification timelines that deter mid-market software entrants.
- Legacy System Interoperability:Established laboratory information management systems in German research hospitals resist API integration with modern AI platforms.
Strategic Opportunities
- Clinical Bioinformatics Expansion:Diagnostic laboratories in Bavaria and Baden-Württemberg are building in-house computational pipelines for precision oncology, creating demand for sample-to-insight workflow tools.
- AgTech Algorithm Transfer:Protein structure prediction methods proven in pharmaceutical applications are migrating to crop science research at German agricultural biotechnology institutes.
- Digital Care Act Reimbursement:Germany's Digital Care Act creates reimbursement pathways for algorithm-supported diagnostic tools, opening commercialization routes previously blocked by payment uncertainty.
Industry Challenges
- Model Drift Monitoring:Deployed machine learning pipelines require continuous validation against evolving biological datasets, demanding dedicated MLOps infrastructure that stretches biotech operational budgets.
- Cross-Border Data Governance:GDPR constraints on genomic data transfer complicate multi-site collaborations between German research institutions and international pharmaceutical partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Computational Biology Market |
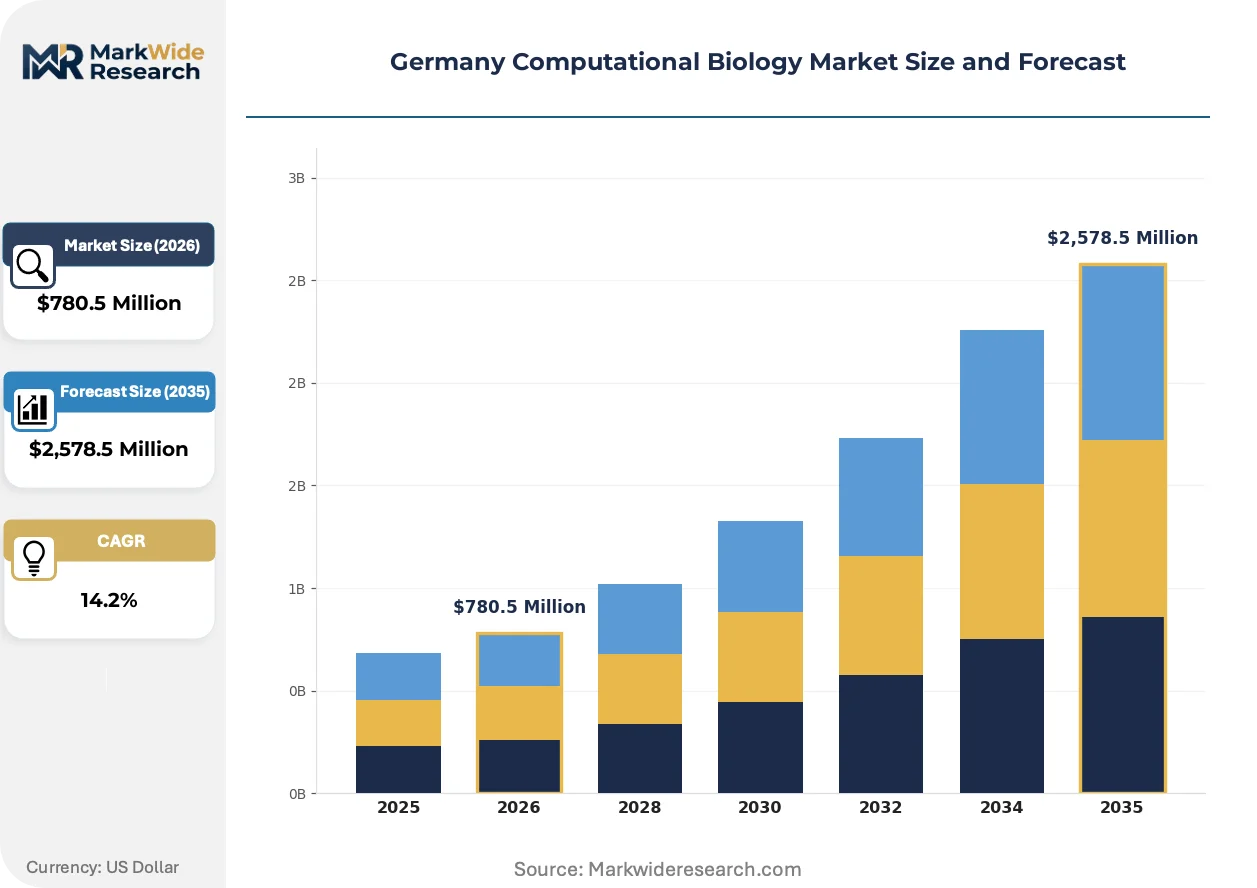
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $2,578.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Drug Discovery, Genomics, Proteomics, Personalized Medicine Technology: Machine Learning, Bioinformatics, High-Performance Computing, Cloud Computing End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Academic Organizations Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Software as a Service |
| Companies Covered | QIAGEN, Thermo Fisher Scientific, BIO-RAD, Certara, Genedata (Danaher), Dassault Systèmes, Illumina, Roche Holding, Schrödinger, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Computational Biology Market Trends and Innovations
Federated learning architectures and containerized bioinformatics workflows are redistributing computational capacity away from centralized supercomputing centers toward institutional edge deployments across German life sciences.
AlphaFold-derived protein structure databases are decentralizing access to molecular predictions that previously required months of experimental crystallography. Mid-sized German biotechnology firms now integrate these pre-computed structures into target validation workflows within weeks rather than quarters. This compression is decentralizing competitive advantage from well-capitalized pharmaceutical incumbents toward nimble algorithm-native entrants.
The EU AI Act's risk classification framework for healthcare algorithms is forcing vendors to restructure development pipelines around documented training data provenance and post-market monitoring obligations. German software providers serving regulated pharmaceutical clients are rebuilding quality management systems to capture model versioning and performance drift metrics. Small molecule discovery platforms face the steepest compliance burden, while research-use-only tools navigate lighter conformity requirements.
Pharmaceutical procurement teams in Berlin and Munich are unbundling software licenses from hardware instrumentation, reversing the integrated bundle preference that dominated prior purchasing cycles. Buyers now evaluate computational platforms on API interoperability and modular workflow composition rather than vendor ecosystem lock-in. This behavioral shift pressures instrument manufacturers to open software architectures or surrender market position to specialized bioinformatics vendors.
Germany Computational Biology Market Segmentation
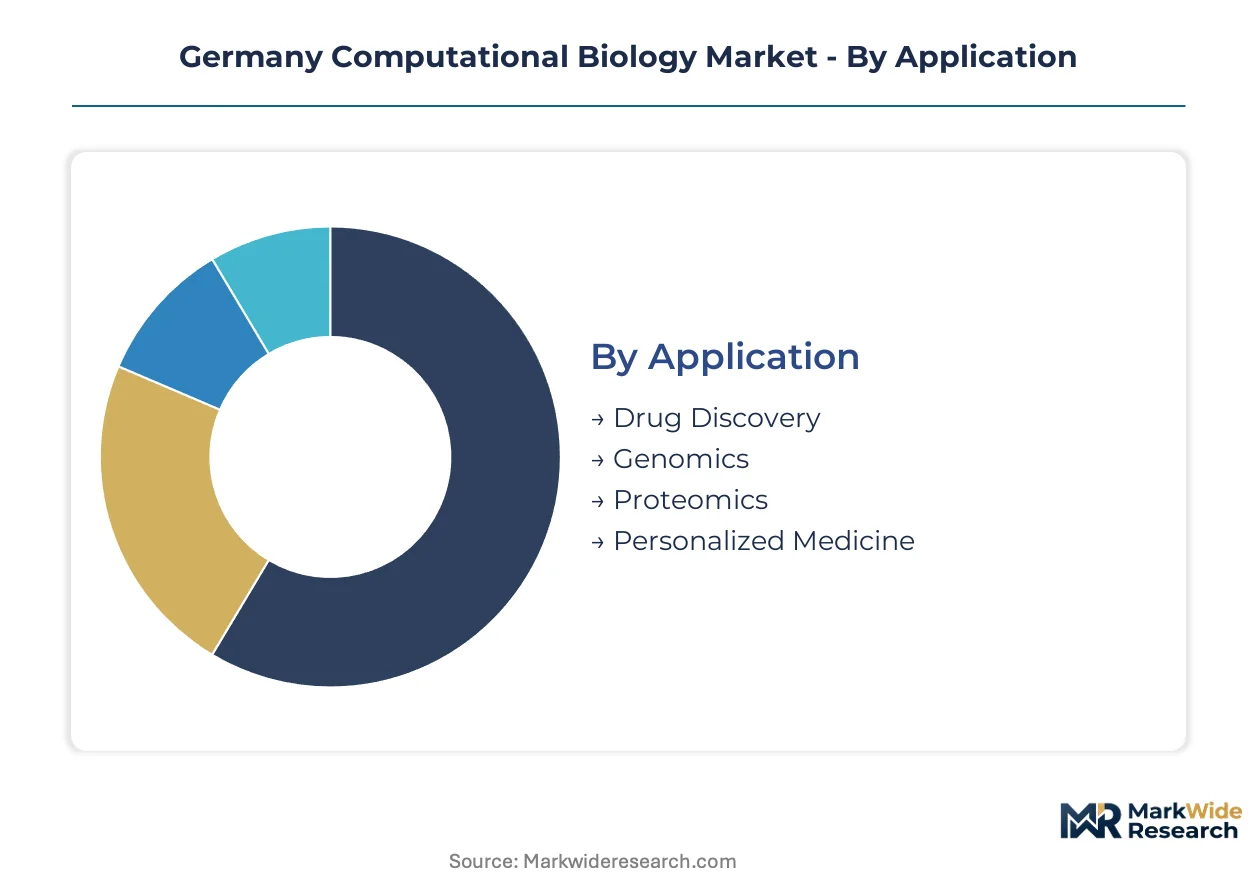
Segmentation in Germany's computational biology market reveals how procurement priorities diverge across regulatory exposure, infrastructure maturity, and end-user sophistication. Pharmaceutical sponsors in Berlin and Munich demand validated platforms for EMA submissions, while mid-sized biotechnology firms prioritize elastic compute models that bypass capital constraints.
Application:
Replacement cycles for legacy discovery platforms accelerate as EU AI Act documentation requirements render older tools non-compliant for high-risk healthcare algorithms.
- Drug Discovery:Machine learning pipelines compress candidate validation timelines from months to weeks. Demand concentrates among pharmaceutical companies in Munich and Heidelberg seeking mechanistic modeling capabilities for Federal Institute for Drugs and Medical Devices submissions.
- Genomics:High-throughput sequence analysis requires integrated instrument-software bundles for population-scale studies. Research clusters in Berlin prioritize platforms with auditable provenance trails for GDPR-compliant genomic data processing.
- Proteomics:Mass spectrometry data interpretation relies on cloud-based peptide identification algorithms.
- Personalized Medicine:Variant interpretation tools support precision oncology diagnostic workflows in Bavarian clinical laboratories.
Volume placements concentrate in drug discovery; the faster expansion belongs to personalized medicine.
Technology:
Cost tier stratification separates enterprise-grade platforms with dedicated support from open-source toolkits requiring in-house expertise.
- Machine Learning:Neural architectures for target deconvolution demand specialized MLOps infrastructure. Biotechnology firms in Baden-Württemberg adopt containerized training pipelines to monitor model drift against evolving biological datasets.
- Bioinformatics:Sample-to-insight workflows dominate clinical applications with stringent turnaround requirements. QIAGEN's specialized pipelines anchor procurement decisions in diagnostic settings across German university hospitals.
- High-Performance Computing:On-premise clusters serve institutions with sensitive genomic data sovereignty constraints.
- Cloud Computing:SaaS deployment models enable mid-sized firms to access elastic compute without infrastructure ownership.
Enterprise commitments favor high-performance computing; cloud computing gains share fastest among capital-constrained entrants.
End User:
Customer type determines compliance burden intensity, with regulated pharmaceutical sponsors demanding full audit trails versus academic researchers accepting lighter documentation.
- Pharmaceutical Companies:Mechanistic modeling expertise supports physiologically-based pharmacokinetic simulations for regulatory filings. Certara sustains position through submission-grade documentation that EMA reviewers accept without qualification.
- Biotechnology Firms:Agile algorithm-native entrants leverage AlphaFold-derived structures to decentralize competitive advantage from well-capitalized incumbents.
- Research Institutions:Federated learning architectures redistribute computational capacity toward institutional edge deployments.
- Academic Organizations:Open-source toolkits with community support dominate basic science applications.
Procurement volume clusters with pharmaceutical companies; biotechnology firms are climbing the fastest as algorithmic methods mature.
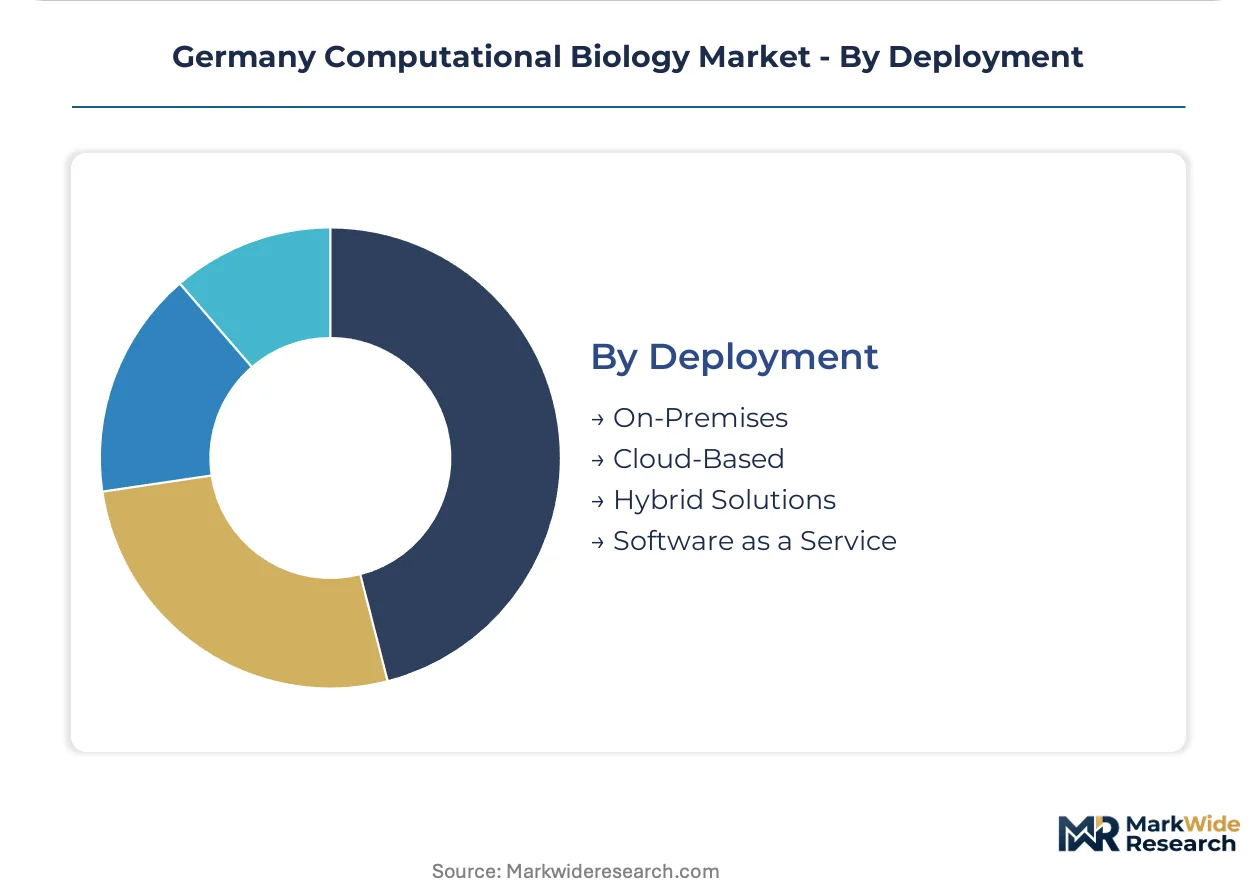
Deployment:
Maturity gradients separate established on-premise installations from emerging hybrid architectures that balance data sovereignty with compute elasticity.
- On-Premises:Dedicated infrastructure serves institutions with GDPR-sensitive genomic datasets requiring physical data residency. Heidelberg academic clusters maintain captive compute for population genetics studies involving cross-border collaboration restrictions.
- Cloud-Based:Elastic scaling supports variable workload intensity without capital commitment. Mid-sized biotechnology firms in Munich adopt SaaS models to access enterprise-grade platforms during peak discovery phases.
- Hybrid Solutions:Split architectures process sensitive data locally while bursting compute-intensive tasks to cloud infrastructure.
- Software as a Service:Subscription pricing aligns vendor incentives with customer success metrics.
Legacy installations concentrate in on-premises; cloud-based deployment shows the steepest expansion trajectory as procurement teams unbundle software from hardware instrumentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors Germany's computational biology activity, hosting dense pharmaceutical R&D clusters where machine learning pipelines compress target validation timelines. Berlin follows with academic consortia building federated learning architectures for population-scale genomics.
Bavaria
Pharmaceutical sponsors in Munich and Heidelberg drive demand for mechanistic modeling platforms that satisfy the Federal Institute for Drugs and Medical Devices submission requirements. The EU AI Act's high-risk algorithm classification elevates procurement standards for auditable software across Bavarian research hospitals. Diagnostic laboratories in Nuremberg and Erlangen are constructing in-house computational pipelines for precision oncology workflows.
North Rhine-Westphalia
Cologne and Düsseldorf biotechnology clusters prioritize cloud-based deployment models to access elastic compute without capital-intensive infrastructure ownership. Germany's Digital Care Act creates reimbursement pathways for algorithm-supported diagnostic tools that previously faced commercialization barriers. Life sciences incubators in the Ruhr region are transferring protein structure prediction methods from pharmaceutical applications toward agricultural biotechnology research.
Baden-Württemberg
Stuttgart and Karlsruhe mid-sized biotechnology firms adopt containerized training pipelines to monitor model drift against evolving biological datasets. GDPR constraints on genomic data transfer complicate multi-site collaborations between Heidelberg academic institutions and international pharmaceutical partners. The state's automotive engineering heritage is cross-pollinating into simulation software for biological pathway modeling.
Berlin-Brandenburg
Research consortia in Berlin prioritize platforms with provenance trails for GDPR-compliant genomic data processing in population genetics studies. Charité university hospital resists API integration with modern AI platforms due to entrenched laboratory information management systems. The capital's startup density is producing algorithm-native entrants that leverage AlphaFold-derived structures to decentralize competitive advantage from well-capitalized incumbents.
Hesse
Frankfurt pharmaceutical procurement teams are unbundling software licenses from hardware instrumentation, reversing prior integrated bundle preferences. The state's central location supports data residency requirements for institutions processing GDPR-sensitive genomic datasets. Darmstadt technical universities are supplying specialized talent at the intersection of molecular biology and machine learning expertise that constrains vendor scaling elsewhere.
Germany Computational Biology Market Competitive Landscape
Capital-heavy instrument manufacturers compete with asset-light software specialists for procurement budgets across German life sciences. Thermo Fisher Scientific leverages integrated bundles to anchor high-throughput genomics workflows, while QIAGEN dominates clinical bioinformatics through sample-to-insight pipelines. Three archetypes define positioning: instrument-software bundlers, specialized workflow vendors, and mechanistic modeling experts. Competitive moves center on API interoperability expansion and quality management system rebuilding for EU AI Act conformity.
Within the specialized workflow tier, QIAGEN and Certara occupy distinct positions. QIAGEN represents the clinical bioinformatics archetype with diagnostic-setting penetration across German university hospitals. Certara exemplifies the regulatory submission specialist archetype through mechanistic modeling documentation that EMA reviewers accept without qualification. Thermo Fisher Scientific anchors the instrument-software bundler archetype, though procurement teams in Berlin and Munich are unbundling licenses from hardware and evaluating platforms on modular workflow composition rather than ecosystem lock-in.
| Leading Market Players |
|---|
| QIAGEN |
| Thermo Fisher Scientific |
| BIO-RAD |
| Certara |
| Genedata (Danaher) |
| Dassault Systèmes |
| Illumina |
| Roche Holding |
| Schrödinger |
| Others |
Pricing and Supply Chain Analysis
GPU compute costs cascade through SaaS pricing tiers for machine learning platforms, compressing margins for vendors serving mid-sized biotechnology firms while enterprise buyers with captive infrastructure negotiate from positions of hardware ownership.
Pricing Analysis
Throughput-based pricing anchors enterprise contracts, where pharmaceutical sponsors in Munich pay per validated candidate rather than per seat license. Three-tier pricing structure across premium, standard, and economy levels separates EMA-submission-grade platforms with full audit trails from research-use-only toolkits. Pricing pressure stems from open-source alternatives eroding the middle tier. Mid-sized biotechnology firms exhibit highest price sensitivity, while regulated pharmaceutical sponsors prioritize compliance over cost.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure compel German vendors to qualify both AWS and Azure deployments for EU data residency compliance. GPU hardware concentrates in Taiwan, USA, and South Korea; specialized bioinformatics software development clusters in Germany, Switzerland, and USA. Supply chain risk centers on single-source vulnerability for NVIDIA accelerators. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and channel partners for mid-market biotechnology penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act erects a cost-of-compliance moat that favors established vendors with rebuilt quality management systems over bootstrap entrants lacking documentation infrastructure.
For Market Incumbents: Extend API interoperability investments to capture procurement teams unbundling software from hardware instrumentation. Consolidate position through acquisition of specialized MLOps firms addressing model drift monitoring requirements. The threat of algorithm-native entrants leveraging AlphaFold-derived structures demands vertical integration into federated learning architectures. For New Entrants and Emerging Players: The mid-tier price-point gap between Thermo Fisher Scientific bundles and academic open-source toolkits offers white-space for containerized workflow vendors. Target Baden-Württemberg biotechnology clusters seeking elastic compute without EMA-grade compliance burdens. Go-to-market through cloud-native SaaS subscriptions with usage-based scaling. For Investors and Strategic Acquirers: Vendor quality management system rebuilds for EU AI Act conformity are the leading indicator that regulatory technology capabilities will determine exit multiples. Long-term viability favors mechanistic modeling specialists with submission-grade documentation over point-solution machine learning platforms. Acquisition target archetype: clinical bioinformatics vendors with Bavarian hospital penetration. Watch for MLOps infrastructure investments as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Quality management system rebuilds capture procurement from regulated pharmaceutical sponsors. |
| API Interoperability Expansion | Modular workflow composition satisfies Berlin and Munich procurement teams unbundling licenses. |
| Cloud Infrastructure Dual-Qualification | AWS and Azure deployments ensure GDPR-compliant data residency for genomic datasets. |
| MLOps Capability Acquisition | Model drift monitoring infrastructure addresses operational budget constraints in biotechnology firms. |
| Federated Learning Architecture Deployment | Edge computing redistribution captures Heidelberg academic cluster collaborations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and platform engineers. EMA submission databases, BfArM guidance documents, ClinicalTrials.gov entries, and German biotechnology association reports supplied validation layers. Bottom-up platform deployment counts triangulated against top-down pharmaceutical R&D spending allocations.
Segment-level modeling tracked application, technology, end user, and deployment dimensions across the analysis window. Drug discovery versus clinical diagnostics split informed by regulatory pathway differentiation. CAGRs derived from weighted average of historical platform adoption curves and forward-looking procurement pipeline assessments. Cloud elasticity assumptions and EU AI Act implementation timelines shaped trajectory inflections.
Underlying measurement precision varies by segment; pharmaceutical company deployments carry tighter precision than academic organization estimates. Forecasts reflect documented assumptions regarding regulatory implementation speed and cloud infrastructure availability. Deviation in EU AI Act enforcement intensity or GPU supply constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
North America Computational Biology Market
Bioinformatics
Bioinformatics Software Market
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
Bioinformatics Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
China Computational Biology Market
Bioinformatics
Global Biological Data Visualization Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
US Computational Biology Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
Global Computational Biology Market