
 Cancer Stem Cells Market | 2026-2036
Cancer Stem Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Stem Cells Market Intelligence
The unbundling of cell isolation kits from analysis software is decoupling the initial cell sorting process from downstream molecular analysis. This shift allows researchers greater flexibility in experimental design. Thermo Fisher Scientific Inc. leverages its extensive portfolio in both instrumentation and consumables to offer integrated workflows. STEMCELL Technologies Inc. specializes in culture media and cell separation products, anchoring its position in the research-use-only segment.
Cancer stem cells are a subpopulation of malignant cells with self-renewal capabilities that drive tumor growth and relapse. Identified by cell surface markers like CD133 or CD44, they are key targets for therapies designed to prevent cancer recurrence. The cell surface markers product segment is a primary focus, supporting high-value applications in drug discovery and targeted therapy. Flow cytometry technology dominates cell sorting, while single-cell sequencing represents the fastest-growing analytical method.
Regulatory frameworks from the US FDA and the European EMA dictate stringent validation requirements for any diagnostic or therapeutic product derived from cancer stem cells. China's NMPA has established specific guidelines for cell therapy products, influencing market access and clinical trial design. Stakeholder success will depend on navigating evolving ethical guidelines and securing intellectual property for novel CSC biomarkers and therapeutic targets.
Market Dynamics
The convergence of single-cell analytical technologies with the development pipelines of targeted oncology therapies is the central force defining market structure. This integration accelerates the identification of novel biomarkers and therapeutic targets for drug discovery programs in leading pharmaceutical companies.
Growth Catalysts
- Advanced Analytics:Progress in single-cell sequencing and multi-omic analysis enables more precise characterization of cancer stem cell heterogeneity, supporting drug discovery programs.
- Academic Research Focus:Concentrated research activity within oncology innovation hubs in the United States, Germany, and Japan provides steady demand for specialized cell isolation and analysis tools.
- Government Funding:Increased public funding for precision medicine and cancer research initiatives, particularly in North America and Europe, directly supports foundational CSC studies.
Market Restraints
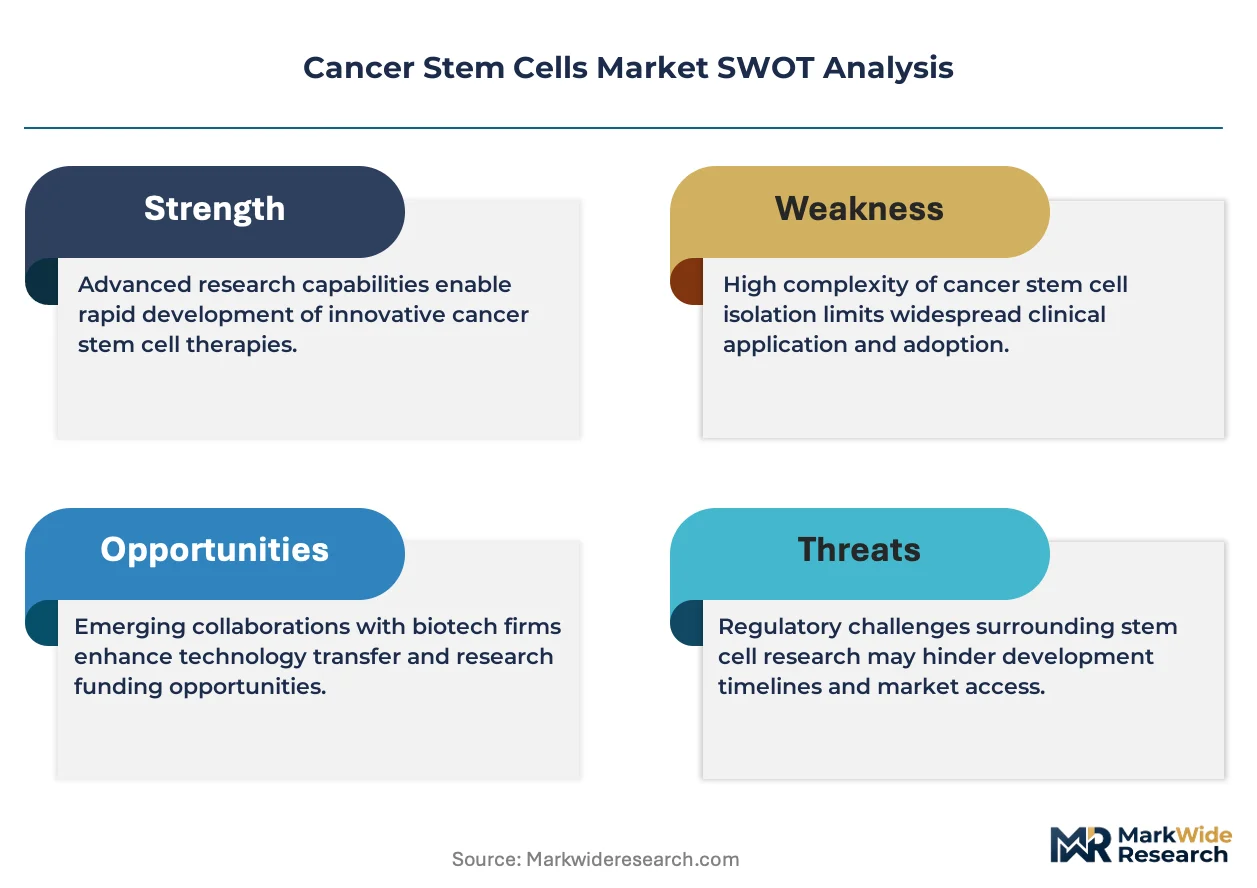
- Cellular Heterogeneity:The inherent plasticity and diverse marker expression of cancer stem cells complicate consistent isolation and targeting, creating significant technical hurdles for therapeutic development.
- High Research Costs:The capital-intensive nature of technologies like flow cytometry and single-cell sequencing limits their accessibility to well-funded research institutions and pharmaceutical firms.
- Regulatory Scrutiny:Stringent validation protocols from bodies like the US FDA and European EMA for biomarker qualification create long and costly pathways to clinical application.
Strategic Opportunities
- Companion Diagnostics:Developing CSC-based biomarkers as companion diagnostics for targeted therapies offers a high-value application beyond basic research use.
- AI-Powered Analytics:Integrating artificial intelligence platforms with high-throughput screening data can accelerate the identification of novel CSC-specific pathways and drug targets.
- Emerging Asian Markets:Expanding research capabilities and government investment in biotechnology in countries like South Korea and Singapore present new growth corridors for specialized reagents and instruments.
Industry Challenges
- Protocol Standardization:A lack of universally accepted protocols for the isolation, culture, and characterization of CSCs leads to issues with data reproducibility across different research labs.
- Intellectual Property Complexity:Navigating the dense and often overlapping intellectual property landscape for novel CSC biomarkers presents a significant legal and strategic challenge for commercial developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Stem Cells Market |
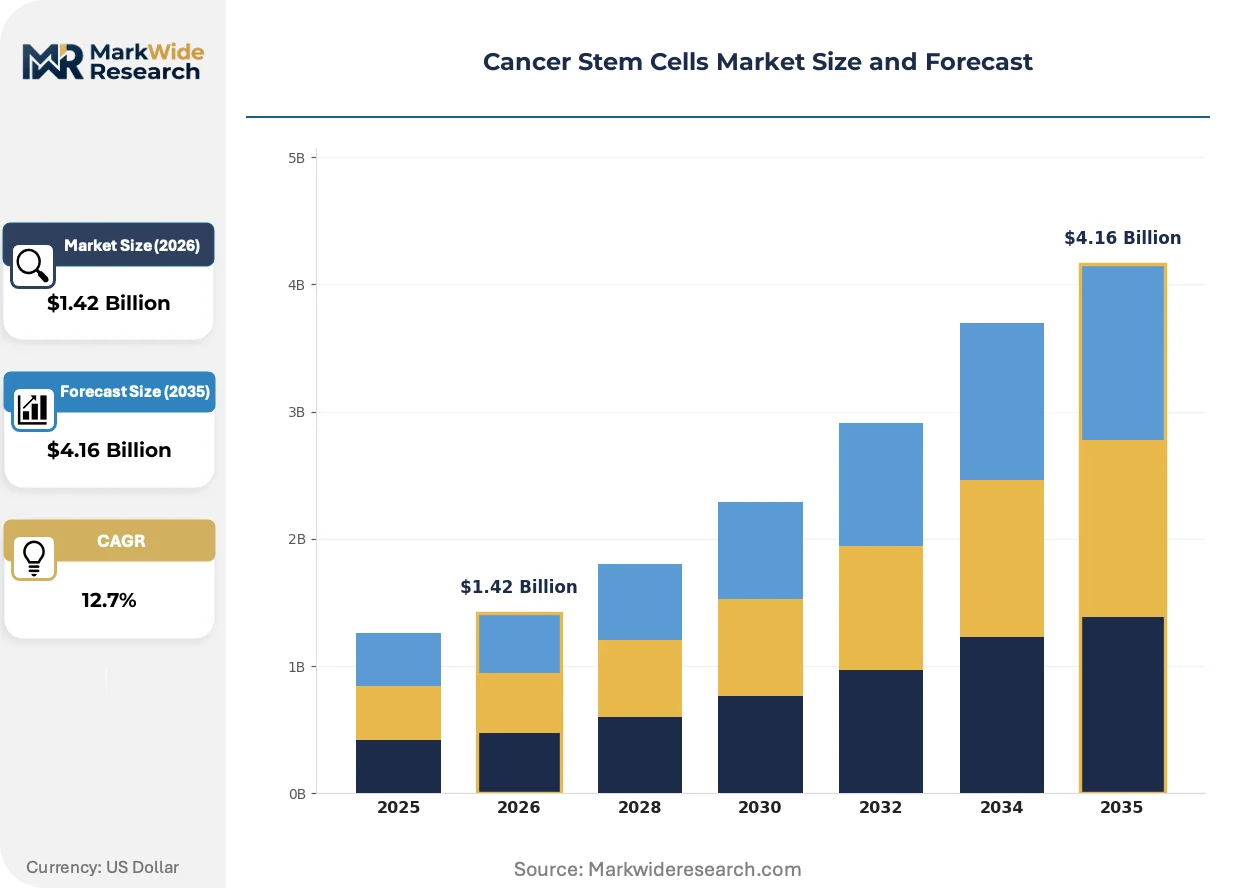
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.16 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Surface Markers, Drug Resistance Proteins, Transcription Factors, Epigenetic Regulators, Others Application: Drug Discovery, Molecular Diagnostics, Targeted Therapy, Cancer Research, Biomarker Identification End User: Biotechnology Firms, Pharmaceutical Companies, Academic Research Centers, Contract Research Organizations Technology: Flow Cytometry, Immunohistochemistry, Cell Sorting, Single-cell Sequencing, Imaging Cytometry |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, STEMCELL Technologies Inc., AbbVie Inc., Lonza Group AG, Miltenyi Biotec, FUJIFILM Irvine Scientific, Lineage Cell Therapeutics, Inc., MacroGenics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Stem Cells Market Strategic Shifts & Innovations
A fundamental shift from mere identification toward functional characterization is underway. This evolution links CSC biology directly to therapeutic response and resistance, moving the field closer to clinical utility.
Single-cell multi-omics technologies provide simultaneous readouts of the genome, transcriptome, and proteome from individual cells. Pharmaceutical R&D teams are adopting these for deep cellular profiling. This approach is modularizing the drug discovery workflow, separating high-throughput screening from subsequent deep-dive functional validation of promising hits.
China's NMPA has implemented specific technical guidelines for the research and evaluation of cell therapy products. This framework imposes rigorous preclinical and clinical data requirements, influencing trial design and market entry strategies. The regulations affect developers of advanced therapies aiming for access to the Chinese oncology market.
Research laboratories are increasingly unbundling the purchase of cell isolation kits from proprietary analysis software, demanding greater interoperability. This decouples wet-lab cell sorting from downstream bioinformatic analysis, disrupting integrated vendor ecosystems. The trend is most prominent in academic centers in the United States and Germany with strong bioinformatic capabilities.
Cancer Stem Cells Market Segmentation
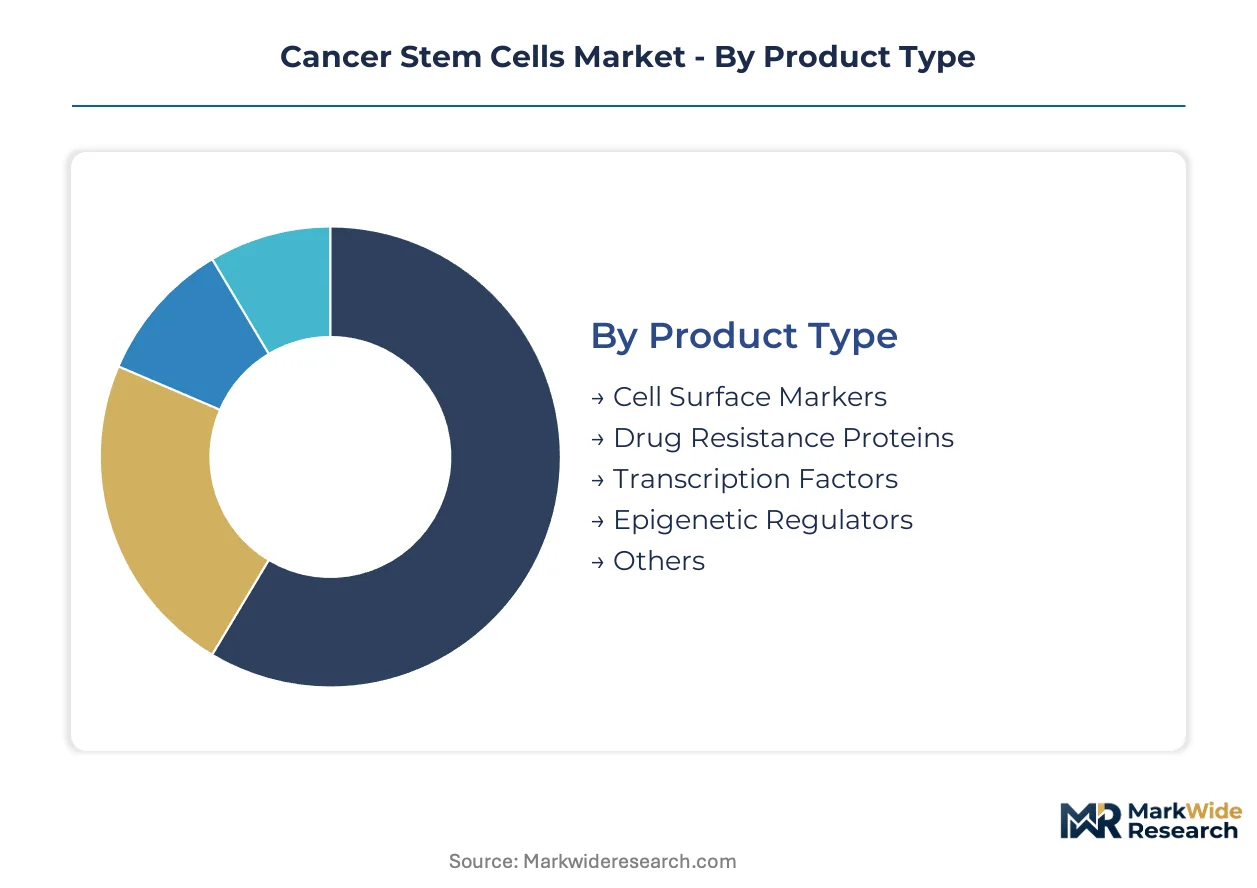
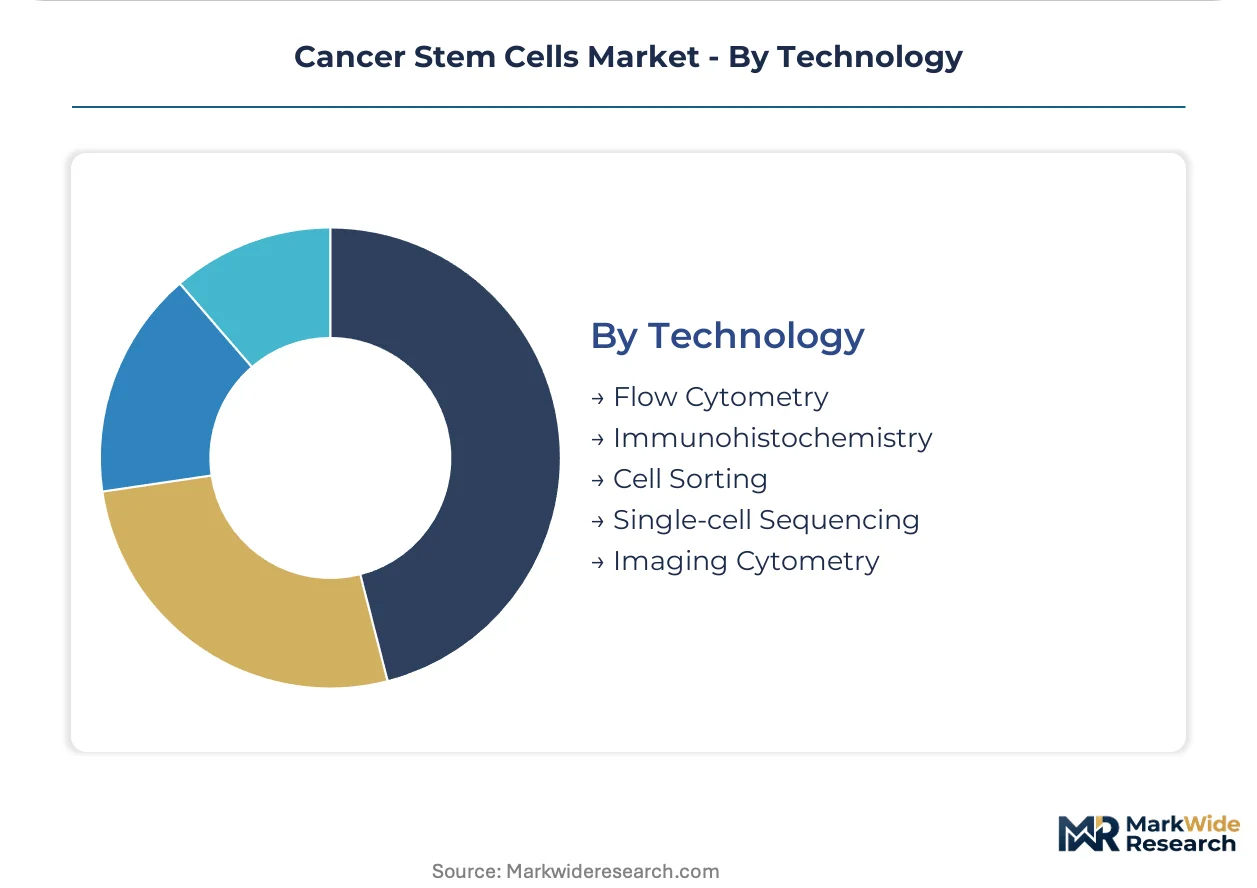
The Cancer Stem Cells market segmentation provides a granular view of the diverse product types, applications, end users, and technologies driving innovation. This detailed analysis highlights areas of concentrated investment and technological advancement, essential for understanding market dynamics. Pinpointing specific segments clarifies where value creation and research efforts are most intense.
Product Type:
The market for cancer stem cell product types faces varying regulatory scrutiny, with biomarkers intended for diagnostic use requiring rigorous validation by bodies like the US FDA and European EMA.
- Cell Surface Markers:These are proteins expressed on the cell membrane, such as CD133 and CD44, used to identify and isolate cancer stem cells. Demand for these markers is concentrated in drug discovery programs within pharmaceutical companies, supporting the development of highly specific targeted therapies.
- Drug Resistance Proteins:These proteins mediate cellular mechanisms that allow cancer cells, including CSCs, to evade therapeutic agents. Research on these proteins is vital for overcoming treatment failure, with significant investment from biotechnology firms in the United States exploring novel therapeutic approaches.
- Transcription Factors:These proteins regulate gene expression, controlling CSC self-renewal and differentiation, drawing interest from academic research in Germany.
- Epigenetic Regulators:These molecules modify DNA or histones without altering the underlying sequence, influencing CSC plasticity and therapeutic response.
- Others:This category includes various novel markers and targets under early-stage investigation, often driven by university research in Japan.
Leading the category by volume: Cell Surface Markers. Growing fastest: Drug Resistance Proteins.
Application:
Application segments are differentiated by their direct impact on clinical outcomes versus foundational research, influencing the investment profiles of stakeholders.
- Drug Discovery:This application involves identifying and validating novel therapeutic targets and agents specifically against cancer stem cells. Pharmaceutical companies in both Europe and North America dedicate substantial resources to this area, aiming to develop curative treatments that prevent tumor relapse.
- Targeted Therapy:This segment focuses on developing and applying therapies that specifically eliminate cancer stem cells while sparing healthy cells. Clinical trials in the United States and Germany are actively evaluating CSC-targeting agents designed to improve patient outcomes and reduce recurrence rates.
- Molecular Diagnostics:This involves using CSC biomarkers for patient stratification and monitoring treatment response, particularly in academic centers.
- Cancer Research:Basic and translational studies into CSC biology drive demand for tools and reagents, primarily within university laboratories globally.
- Biomarker Identification:This application focuses on discovering new CSC-specific markers for diagnostic or therapeutic purposes, a high-value activity for biotech firms.
Drug Discovery commands the largest portion of research expenditure. Targeted Therapy exhibits the steepest expansion trajectory.
End User:
The end-user landscape reflects varying levels of research infrastructure and commercialization capabilities, shaping demand for specialized tools and services.
- Pharmaceutical Companies:These large entities possess significant capital and infrastructure for extensive drug development pipelines, including preclinical and clinical trials targeting cancer stem cells. Their demand centers on high-throughput screening solutions and validated CSC models to accelerate therapeutic innovation.
- Academic Research Centers:Universities and government-funded institutions are primary drivers of foundational CSC research, focusing on basic biology and biomarker discovery. These centers in the United States, Germany, and Japan require specialized reagents and analytical platforms for intricate experimental designs.
- Biotechnology Firms:These companies specialize in developing innovative CSC-related products and services, often collaborating with larger pharmaceutical partners.
- Contract Research Organizations:CROs provide specialized research services to pharmaceutical and biotech clients, offering expertise in CSC isolation and characterization studies.
Pharmaceutical Companies represent the largest customer base. Biotechnology Firms are gaining share fastest.
Technology:
Technology segments are distinguished by their analytical precision and throughput, directly influencing the cost and complexity of cancer stem cell studies.
- Single-cell Sequencing:This advanced technology enables the genomic, transcriptomic, and proteomic profiling of individual cancer stem cells, revealing intricate heterogeneity. Pharmaceutical R&D teams in North America are increasingly adopting this method for deep cellular characterization in drug target identification.
- Flow Cytometry:This established technology allows for high-throughput analysis and sorting of cells based on surface marker expression. Academic research centers globally rely on flow cytometry for initial CSC enrichment and purification due to its robust and reliable performance.
- Immunohistochemistry:This technique visualizes CSC markers within tissue sections, providing spatial context for tumor microenvironment studies.
- Cell Sorting:This encompasses various methods for isolating specific cell populations, a fundamental step in CSC research and therapeutic development.
- Imaging Cytometry:This combines microscopy with flow cytometry principles, offering morphological and functional data on individual CSCs.
Flow Cytometry accounts for the largest installed base. Single-cell Sequencing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cancer Stem Cells market exhibits a clear divide where advanced research and development primarily concentrate in established economies, while emerging markets are gradually building capabilities. Consumption of specialized tools and reagents for CSC research is highest in countries with strong academic and pharmaceutical sectors. This creates a supply dynamic favoring innovation hubs.
United States
Academic research and pharmaceutical R&D for targeted therapies drive demand in the United States. The US FDA imposes stringent validation requirements for CSC diagnostic and therapeutic products. Boston and the San Francisco Bay Area host numerous biotech firms advancing biomarker discovery.
Germany
German academic oncology research, especially on transcription factors and epigenetic regulators, fuels significant demand. The European EMA dictates stringent validation protocols for CSC-based products. Munich and Heidelberg are major centers for cancer research, attracting substantial public and private investment.
Japan
Japanese university research into novel CSC markers and early-stage investigation generates consistent demand. METI supports biotechnology research, fostering innovation in regenerative medicine. Tokyo and Kyoto universities lead specialized oncology research, advancing functional characterization.
China
China's expanding research capabilities and government investment in biotechnology support cell therapy development. The NMPA has established specific guidelines for cell therapy products, influencing market entry. Shanghai and Beijing are rapidly developing biotech hubs, attracting investment in oncology research.
United Kingdom
Growing university research and a developing biotechnology sector focused on precision oncology contribute to demand in the United Kingdom. The UK MHRA oversees clinical trials and product approvals for novel cancer stem cell therapies. Cambridge and London possess prominent research institutions and biotech clusters for CSC studies.
Cancer Stem Cells Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure. The landscape includes large life science companies offering integrated workflows and niche biotechnology firms providing specialized reagents. Key archetypes are broad portfolio providers, research-use-only specialists, and therapeutic developers. Strategic partnerships and portfolio diversification are dominant competitive moves.
Within the broad portfolio providers, Thermo Fisher Scientific Inc. exemplifies a strategy of offering extensive instrumentation and consumable solutions. STEMCELL Technologies Inc. anchors the research-use-only segment, specializing in culture media and cell separation products. Germany-based Merck KGaA, with its life science division, occupies a position bridging research tools and broader pharmaceutical development. These companies represent varied approaches to serving the cancer stem cell market through different scales and specializations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| STEMCELL Technologies Inc. |
| AbbVie Inc. |
| Lonza Group AG |
| Miltenyi Biotec |
| FUJIFILM Irvine Scientific |
| Lineage Cell Therapeutics, Inc. |
| MacroGenics, Inc. |
| Others |
Cost & Logistics Intelligence
Specialized reagent manufacturing costs, particularly for highly purified antibodies and growth factors, cascade through the supply chain, influencing the pricing tiers of cancer stem cell research tools. This cost structure directly affects the accessibility of advanced technologies for various research institutions.
Pricing Analysis
Margin tightening across basic research reagents reflects increased competition and the unbundling of cell isolation kits from analysis software. The dominant pricing model is tiered, separating premium research-grade reagents and specialized services from standard-use kits and consumables. Price differentiation stems from the quality grade of the product, such as validated research-grade versus clinical-grade materials, and the brand premium commanded by established suppliers like Thermo Fisher Scientific. Pharmaceutical companies exhibit lower price sensitivity for high-value drug discovery tools, while academic research centers often prioritize cost-effectiveness for routine experiments.
Supply Chain Analysis
Domestic content mandates, particularly in the United States and Germany for certain biomedical components, are reshaping sourcing strategies for specialized reagents. The supply chain for cancer stem cell research tools concentrates in innovation hubs like the United States, Germany, and Japan, which host key manufacturers of antibodies, culture media, and single-cell sequencing consumables. Raw material dependencies include highly purified antibodies, specific growth factors, and specialized enzymes essential for cell isolation and characterization. Single-source vulnerability for proprietary reagents represents a structural risk. Distribution runs through direct sales channels to large pharmaceutical companies and academic institutions, supplemented by specialized distributors for smaller research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents as a consolidation play, where the high capital intensity of single-cell sequencing technologies and stringent regulatory pathways are forcing weaker players out.
For Market Incumbents:
Hedge against the threat of emerging AI analytics platforms by acquiring niche software development firms specializing in bioinformatics. Deepen vertical integration into specialized reagent manufacturing to control costs and intellectual property for novel CSC biomarkers. Strategic partnerships with academic research centers can accelerate clinical validation of new tools and therapeutic targets. Invest heavily in R&D for multi-omic integration to maintain a competitive edge in deep cellular profiling.
For New Entrants and Emerging Players:
China's NMPA guidelines for cell therapy products open a window for specialized contract research organizations focusing on preclinical validation. Target the underpenetrated segment of AI-powered analytics platforms for high-throughput screening data, offering solutions that accelerate novel CSC pathway identification. Collaborate with academic centers in Germany and Japan to co-develop standardized protocols for CSC isolation and characterization. A strong go-to-market angle involves offering interoperable software solutions that integrate seamlessly with existing laboratory instrumentation.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers seeking to capitalize on the long-term growth trajectory of targeted oncology therapies. Acquisition targets should include biotechnology firms with proprietary CSC biomarker panels or advanced single-cell sequencing platforms. Firms developing companion diagnostics for CSC-targeting agents also represent high-value opportunities. The signal to watch is the increasing number of FDA approvals for CSC-targeting therapies, indicating successful clinical translation and market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates the validation of novel CSC-targeting agents for market entry. |
| Platform Integration | Enhances data analysis capabilities for multi-omics, improving drug discovery efficiency. |
| Licensing Agreement | Secures intellectual property for promising CSC biomarkers, expanding product portfolios. |
| Acquisition of Specialist Firm | Integrates advanced AI analytics to streamline target identification and validation processes. |
| Regulatory Approval Pathway | Ensures market access for CSC-based companion diagnostics, supporting personalized medicine. |
Research Approach
Multi-period observation of oncology R&D spending and patent filings for CSC technologies anchored the trend analysis, supplemented by interviews with key stakeholders. Primary research involved discussions with pharmaceutical R&D executives, academic principal investigators, biotech founders, and regulatory specialists. Secondary validation drew from scientific literature databases, company annual reports, clinical trial registries, and government funding databases, triangulating findings through both bottom-up and top-down approaches.
Segment-weighting across product type, application, end user, technology, and regional R&D intensity formed the core of the forecasting framework across the analysis window. Compound annual growth rates were derived through regression analysis of historical market data and projected market drivers. Key forecast inputs included global oncology drug development pipelines and the adoption rates of single-cell analytical technologies within research institutions.
Caveats apply where unforeseen technological breakthroughs, major regulatory changes in cell therapy, or significant shifts in public research funding could materially shift the outlook. Forecasts reflect assumptions documented through extensive industry engagement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Gene Electroporators Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Stem Cell Reconstructive Market