
 Global Mononucleosis Diagnostic Market | 2026-2036
Global Mononucleosis Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mononucleosis Diagnostic Market Foresight
Primary care and urgent care clinic demand is consolidating as the fastest-growing end-use channel for mononucleosis diagnostics. Abbott Laboratories leverages its point-of-care platform breadth to capture outpatient volume. Thermo Fisher Scientific sustains laboratory-grade PCR assay leadership through extensive distribution infrastructure. Quidel Corporation specializes in rapid immunoassay formats that target same-visit diagnosis workflows.
Mononucleosis diagnostics encompass serological, molecular, and cell-based methods that detect Epstein-Barr virus infection through heterophile antibody response or viral DNA amplification using real-time PCR with 95% specificity thresholds. These tools serve clinical confirmation of infectious mononucleosis and blood donor screening protocols. Rapid test kits and ELISA kits dominate current volume due to established reimbursement and minimal equipment requirements. PCR assays represent the fastest-expanding segment as laboratories adopt multiplex respiratory panels that include EBV targets.
The FDA regulates in vitro diagnostic devices under 21 CFR Part 809, while the EMA's In Vitro Diagnostic Regulation enforces post-market surveillance and clinical evidence standards across European member states. Japan's PMDA maintains distinct analytical sensitivity requirements for imported serological kits. Stakeholders must monitor evolving multiplex assay reimbursement decisions and shifting reference laboratory consolidation patterns.
Market Dynamics
The FDA's 2024 infectious disease assay validation guidance is compressing serological test approval timelines while elevating analytical sensitivity thresholds, forcing manufacturers to revalidate legacy platforms or cede urgent care volume to molecular alternatives.
Growth Catalysts
- Point-of-care platform expansion:Urgent care networks in the United States are replacing send-out serology with same-visit heterophile and EBV DNA detection, capturing patient volume that previously flowed to hospital laboratories.
- EMA post-market surveillance mandates:The In Vitro Diagnostic Regulation's clinical evidence requirements are accelerating laboratory consolidation across Germany, France, and Italy, concentrating procurement power among multi-site health systems.
- Multiplex respiratory panel adoption:Real-time PCR with EBV targets is displacing standalone mononucleosis assays as laboratories seek operational efficiency through syndromic testing infrastructure.
Market Restraints
- Reimbursement compression:CMS and commercial payers in the United States are narrowing coverage for standalone serological tests, squeezing margin on rapid immunoassay formats.
- Supply concentration in PCR reagents:Polymerase and probe manufacturing concentrates among three dominant chemical suppliers, exposing assay producers to input cost volatility and allocation constraints.
- Serological cross-reactivity limitations:Heterophile antibody tests exhibit false-negative rates in early infection and cross-reactivity with CMV, constraining clinical utility in pediatric and immunocompromised populations.
Strategic Opportunities
- Japan's expanded EBV screening protocols:PMDA's distinct analytical sensitivity requirements for imported serological kits create first-mover advantage for manufacturers validating high-specificity platforms to Japanese reference standards.
- At-home sample collection integration:Dried blood spot and saliva-based self-collection kits are converging with telehealth workflows, opening direct-to-patient channels previously blocked by CLIA-waived test restrictions.
- Blood donor screening protocol expansion:Nucleic acid testing mandates from the FDA and EMA for transfusion-transmitted infection panels are embedding EBV detection into high-volume donor testing infrastructure.
Industry Challenges
- IVDR technical documentation burden:European Notified Bodies face capacity constraints reviewing performance evaluation reports, extending time-to-market for new serological kits by 12-18 months.
- Legacy LIS integration complexity:Hospital laboratories operate on fragmented middleware architectures, complicating bidirectional data flow for multiplex PCR results and delaying instrument placement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mononucleosis Diagnostic Market |
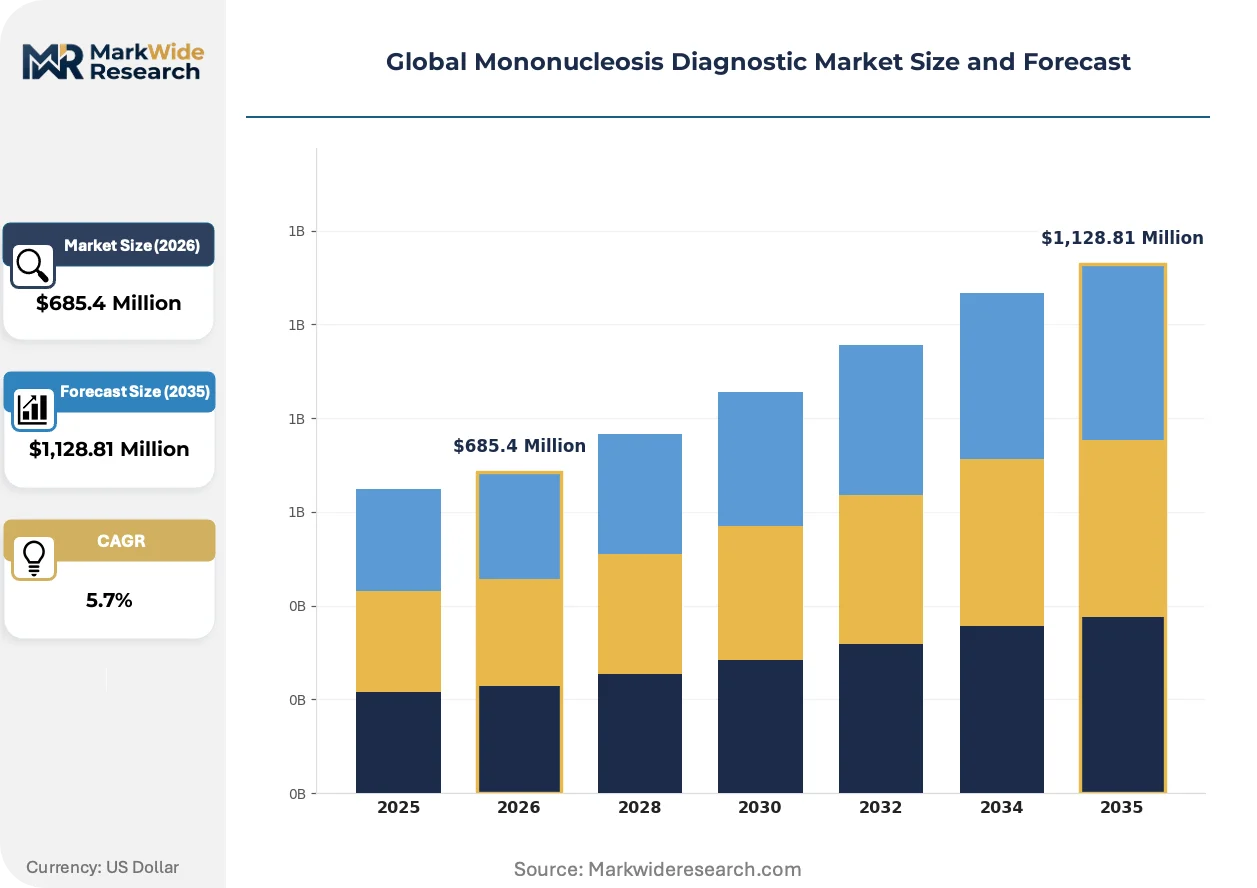
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,128.81 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, ELISA Kits, Western Blot, PCR Assays, Immunofluorescence Assays, Cell Culture Application: Infectious Disease Diagnosis, Blood Screening, Immunological Research, Clinical Trials, Point of Care Testing, Epidemiological Studies End User: Diagnostic Laboratories, Blood Banks, Research Institutes, Specialty Clinics, Academic Hospitals, Public Health Organizations Distribution Channel: Direct Sales, Distributors, Online Platforms, Pharmacy Chains, Medical Device Stores, Institutional Procurement |
| Companies Covered | Cardinal Health, Quidel Corporation, Abbott Laboratories, Meridian Bioscience, Sekisui Diagnostics, Thermo Fisher Scientific, Danaher Corporation, Siemens, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mononucleosis Diagnostic Market Shifts & Advancements
Isothermal amplification chemistries and smartphone-connected readers are compressing the cost and skill barriers that historically confined molecular diagnostics to centralized laboratories, redistributing testing authority toward ambulatory settings.
Loop-mediated isothermal amplification (LAMP) for EBV DNA detection operates at constant temperature without thermal cyclers, enabling cartridge-based formats that urgent care clinics in the United States and Germany are piloting for same-visit diagnosis. This platform is decentralizing molecular testing from hospital core laboratories to physician office settings, collapsing the turnaround time advantage that centralized PCR previously held.
REACH regulation amendments targeting per- and polyfluoroalkyl substances (PFAS) are constraining fluoropolymer availability for PCR consumables, forcing reagent manufacturers to reformulate optical components and validate alternative materials. European IVD producers are accelerating supplier qualification programs to maintain CE marking compliance, with Germany's largest assay manufacturers reporting 6-9 month reformulation timelines.
Hospital systems in the United States are unbundling infectious disease testing from traditional reference laboratory contracts, negotiating direct purchasing agreements with point-of-care platform vendors. This procurement fragmentation is visible most acutely in the Southeast, where regional health networks are consolidating 20-30 urgent care sites under unified assay standardization protocols, displacing the historical dominance of national reference laboratory networks.
Global Mononucleosis Diagnostic Market Segmentation
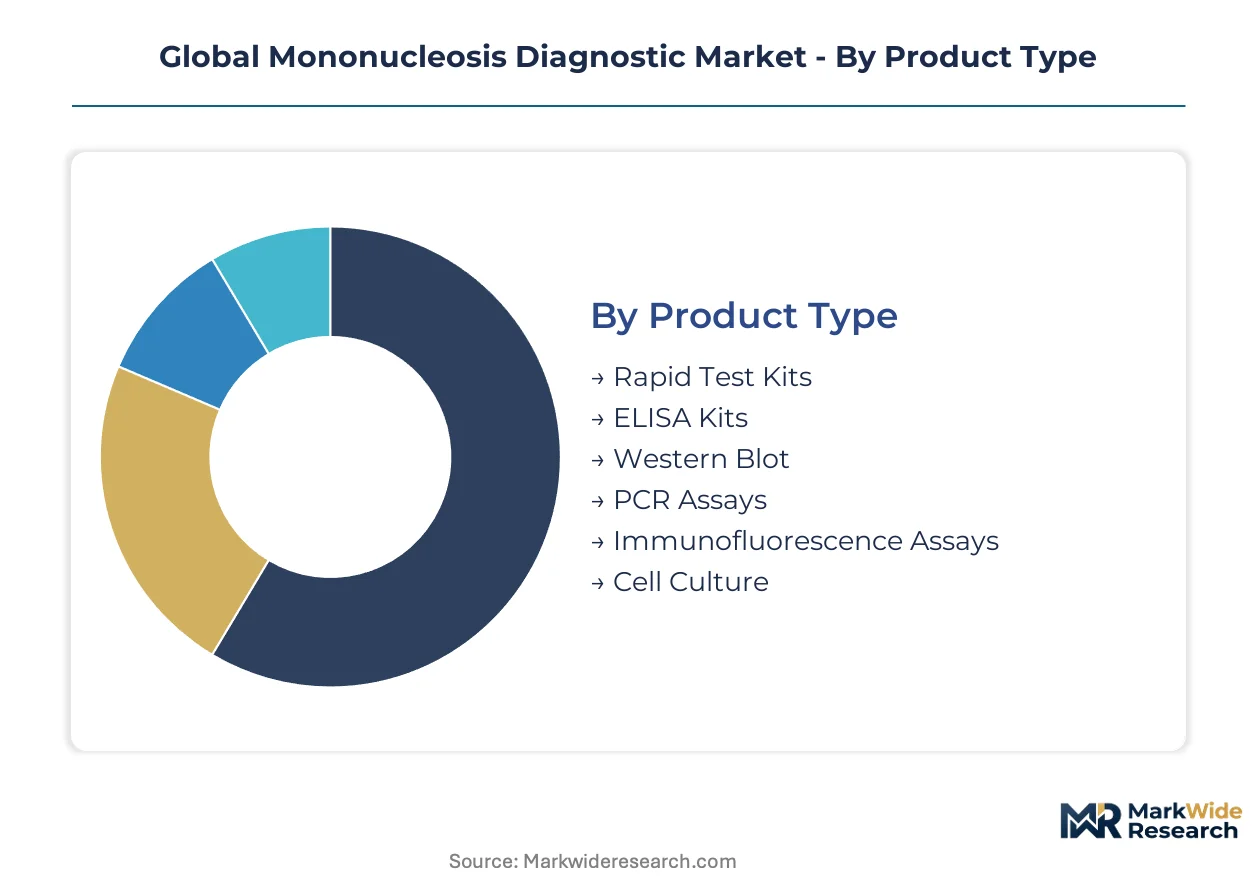
Mononucleosis diagnostic procurement splits across six distinct product formats, six application settings, six end-user channels, and six distribution pathways. Upgrade cycles vary dramatically—rapid immunoassays refresh every 18-24 months while PCR platforms lock laboratories into 5-7 year instrument commitments.
Product Type:
Replacement cycles accelerate fastest where CLIA-waived status and cartridge obsolescence pressure urgent care networks to rotate inventory quarterly.
- Rapid Test Kits:Lateral flow cassettes detecting heterophile antibodies within 10 minutes. Demand clusters in United States urgent care chains where same-visit billing maximizes reimbursement capture.
- ELISA Kits:Enzyme-linked immunosorbent assays quantifying EBV VCA-IgM and EBNA-IgG with 96-well microplate formats. Hospital laboratories in Germany favor these for batch efficiency and EMA-documented traceability.
- Western Blot:Confirmatory serological method resolving antibody band patterns. Research institutes deploy these for atypical case resolution where rapid tests return indeterminate.
- PCR Assays:Real-time amplification of EBV DNA with fluorogenic probe detection. Multiplex respiratory panels in Japan and the United States embed these targets, displacing standalone ordering.
- Immunofluorescence Assays:Microscopic visualization of antibody-antigen complexes on fixed cell substrates. Academic hospitals maintain these for fellowship training and complex case workups.
- Cell Culture:Traditional method isolating EBV-transformed lymphoblastoid lines. Reference laboratories preserve limited capacity for antiviral susceptibility testing and variant characterization.
Rapid Test Kits sit at the top of the volume ranking, with PCR Assays climbing the fastest.
Application:
Cost tiering separates high-frequency screening from premium-priced research applications where grant funding insulates against reimbursement pressure.
- Infectious Disease Diagnosis:Primary clinical confirmation of acute EBV infection through seroconversion patterns. Physician offices in the United States drive volume through CLIA-waived rapid platforms.
- Blood Screening:Nucleic acid testing of donor units for transfusion-transmitted EBV. FDA and EMA mandates embed these assays into high-throughput donor testing infrastructure.
- Immunological Research:Investigation of EBV latency mechanisms and lymphoproliferative disorders. NIH-funded laboratories in the United States and Max Planck institutes in Germany sustain this segment.
- Clinical Trials:Endpoint adjudication for Epstein-Barr virus vaccine and antiviral development. Contract research organizations standardize on central laboratory PCR for regulatory submission packages.
- Point of Care Testing:Same-visit diagnosis workflows in ambulatory settings. Urgent care networks in Japan pilot smartphone-connected readers for telehealth integration.
- Epidemiological Studies:Population-level seroprevalence mapping and outbreak tracing. Public health agencies deploy these for college campus screening protocols.
Infectious Disease Diagnosis commands the highest procedure volume, while Point of Care Testing expands most quickly.
End User:
Customer concentration favors multi-site health systems negotiating enterprise pricing against fragmented independent laboratory networks.
- Diagnostic Laboratories:High-throughput reference facilities processing send-out serology and molecular confirmation. Quest and LabCorp networks in the United States dominate procurement scale.
- Blood Banks:Transfusion services screening donor units for transmissible pathogens. German Red Cross blood services and Japanese Red Cross Society operate centralized testing laboratories.
- Research Institutes:Academic and government facilities investigating EBV oncogenesis. Broad Institute and RIKEN Center maintain dedicated virology cores.
- Specialty Clinics:Infectious disease and hematology practices managing complicated mononucleosis. These sites favor rapid platforms with electronic health record integration.
- Academic Hospitals:Teaching institutions combining clinical service with fellowship training. University of Tokyo Hospital and Charité Berlin maintain full method portfolios.
- Public Health Organizations:State and municipal health departments conducting surveillance and outbreak response. CDC and ECDC reference laboratories set analytical performance standards.
Diagnostic Laboratories sit at the top of the volume ranking, with Specialty Clinics gaining share fastest.
Distribution Channel:
Supply concentration in polymerase manufacturing reshapes channel economics, favoring direct relationships over distributor intermediaries for PCR reagent procurement.
- Direct Sales:Manufacturer-to-institution contracts for high-volume instrument and reagent agreements. Abbott and Thermo Fisher deploy dedicated account teams for health system consolidation.
- Distributors:Regional and national intermediaries stocking rapid test kits and ELISA consumables. McKesson and Cardinal Health in the United States maintain cold chain logistics for temperature-sensitive reagents.
- Online Platforms:E-commerce procurement for small laboratories and research groups. Amazon Business and specialized life science marketplaces enable spot purchasing with credit card workflows.
- Pharmacy Chains:Retail access points for over-the-counter or prescription-required rapid tests. CVS and Walgreens in the United States pilot CLIA-waived testing in select locations.
- Medical Device Stores:Specialty suppliers serving physician office laboratories with equipment and consumables. These channels emphasize technical support and application training.
- Institutional Procurement:Group purchasing organizations aggregating demand across hospital networks. Premier and Vizient in the United States negotiate multi-year sole-source agreements.
Direct Sales sits at the top of the volume ranking, with Online Platforms climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting diagnostic kit production toward jurisdictions with streamlined validation pathways, as manufacturers seek to compress time-to-market for EBV serological platforms while maintaining FDA and EMA equivalence.
United States
Urgent care networks in Texas and Florida are consolidating procurement under enterprise contracts for CLIA-waived rapid platforms. The FDA's 2024 infectious disease assay guidance is elevating analytical sensitivity thresholds for heterophile antibody tests. The Southeast regional health network cluster—spanning Atlanta, Charlotte, and Nashville—is standardizing same-visit EBV DNA detection across 20-30 ambulatory sites.
Germany
Hospital laboratories in Bavaria and North Rhine-Westphalia favor ELISA batch formats for EBV VCA-IgM quantification. The EMA's In Vitro Diagnostic Regulation mandates post-market surveillance documentation that extends Notified Body review timelines. The Rhine-Main biotech corridor around Frankfurt hosts reference laboratories consolidating multi-site health system procurement.
Japan
Specialty clinics in Tokyo and Osaka are piloting smartphone-connected readers for telehealth-integrated diagnosis. The PMDA maintains distinct analytical sensitivity requirements for imported serological kits that exceed FDA benchmarks. The Kansai medical device manufacturing cluster is reformulating optical components to comply with REACH PFAS amendments.
United Kingdom
NHS Trusts in London and the Midlands are unbundling infectious disease testing from legacy reference laboratory contracts. The MHRA operates transitional recognition arrangements for CE-marked devices post-Brexit. The Cambridge-Oxford-London life science triangle anchors contract research organizations standardizing central laboratory PCR for clinical trial endpoints.
India
Diagnostic chains in Maharashtra and Karnataka are expanding point-of-care capacity for EBV screening in tier-2 cities. The CDSCO's medical device rules classify rapid immunoassays under import licensing requirements with staged implementation. The Hyderabad-Visakhapatnam pharmaceutical corridor is attracting contract manufacturers seeking cost-advantaged reagent production.
Global Mononucleosis Diagnostic Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to secure polymerase supply chains and accelerate multiplex assay development. The vendor base concentrates among three tiers: diversified life science conglomerates with distribution infrastructure, mid-cap specialists in rapid immunoassay formats, and regional reagent suppliers serving price-sensitive markets. Two strategic archetypes predominate: platform-integrated players leveraging instrument placement to lock in revenue streams, and assay-only specialists competing on test menu breadth. Competitive moves center on direct purchasing agreements with health systems and technology licensing for isothermal amplification chemistries.
Among diversified conglomerates, Abbott Laboratories and Thermo Fisher Scientific occupy positions as archetypal platform-integrated competitors, while Quidel Corporation exemplifies the rapid immunoassay specialist model. These three entities anchor the competitive structure through contrasting approaches to urgent care penetration and laboratory-grade assay development.
| Leading Market Players |
|---|
| Cardinal Health |
| Quidel Corporation |
| Abbott Laboratories |
| Meridian Bioscience |
| Sekisui Diagnostics |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Siemens |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up diagnostic distributors have consolidated procurement leverage across United States urgent care networks, compressing manufacturer margins while simultaneously demanding guaranteed reagent supply commitments that lock producers into fixed-price contracts regardless of polymerase input volatility.
Pricing Analysis
Distributor margin compression dominates the channel economics for rapid immunoassay formats, with McKesson and Cardinal Health extracting 25-35 point spreads that leave manufacturers defending profitability through volume tier rebates. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared PCR assays from CLIA-waived rapid kits and unregulated research-use-only reagents. Cost compression in the economy tier is intensifying because CMS reimbursement narrowing for standalone serological tests forces urgent care networks toward bundled panel pricing. Independent physician offices exhibit highest price sensitivity, while academic hospitals with grant-funded research cores demonstrate lowest sensitivity to per-test costs.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese polymerase manufacturers who supply thermostable DNA polymerases and fluorogenic probe chemistries to assay producers worldwide. Manufacturing concentrates in Germany, Japan, and the United States for precision optical components and certified diagnostic-grade reagents. Raw material dependencies include Taq polymerase enzymes, FAM-labeled hydrolysis probes, and medical-grade fluoropolymers for PCR consumables. Tariff exposure runs through REACH PFAS amendment compliance costs that European producers must absorb or pass downstream. Distribution runs through direct sales for high-volume health system contracts and regional distributors for fragmented urgent care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by recurring reagent pull-through from installed PCR and point-of-care instrument bases, with replacement cartridge demand insulating revenue from cyclical diagnostic ordering volatility.
For Market Incumbents: Anchor defensive positioning through backward integration into polymerase manufacturing or captive supply agreements with German and Japanese chemical suppliers, insulating against allocation constraints that threaten multiplex assay production. Secure exclusive placement contracts with consolidating Southeast United States health networks before reference laboratories recover lost urgent care volume. FDA analytical sensitivity threshold elevation represents the primary regulatory threat requiring legacy platform revalidation investment. For New Entrants and Emerging Players: Underserved independent specialty clinics in Japan's Osaka-Kobe corridor present immediate white-space opportunity given PMDA's distinct sensitivity requirements that incumbent multinationals have been slow to address. Dried blood spot self-collection kits for telehealth-integrated workflows offer the most penetrable application segment, with minimal CLIA-waived competition and direct-to-patient pricing power. Pursue licensing partnerships with isothermal amplification chemistry holders to bypass thermal cycler instrument barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap rapid immunoassay specialists facing reimbursement compression but possessing established CLIA-waived test menus and urgent care channel relationships. Long-term viability frames around 5-10 year consolidation of point-of-care molecular platforms displacing legacy serology. Monitor FDA guidance implementation timelines as the critical inflection signal for platform transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Multiplex EBV Panel | Accelerates urgent care adoption through same-visit billing capture under evolving CMS reimbursement protocols. |
| CE Marking Pathway under IVDR | Unlocks German and French hospital laboratory procurement through EMA-mandated post-market surveillance documentation. |
| Hospital System Partnership | Secures instrument placement commitments with Southeast United States networks consolidating 20-30 ambulatory sites. |
| Software Companion Development | Enables smartphone-connected reader integration for Japanese telehealth pilots and remote result interpretation. |
| Reimbursement Strategy | Positions assays for coverage expansion as blood donor screening protocols embed EBV nucleic acid testing mandates. |
Research Methodology
Direct dialogue with clinical laboratory directors, urgent care network procurement officers, diagnostic assay R&D heads, and FDA regulatory consultants grounded the qualitative assessment, supplemented by EMA guidance documents, FDA 510(k) clearance databases, CMS reimbursement schedules, and PMDA approval records. Secondary validation drew from hospital procurement databases, GPO contract disclosures, and published clinical performance studies. Bottom-up and top-down triangulation reconciled instrument placement data with reagent consumption estimates.
Bottom-up modeling aggregated point-of-care platform installations, replacement cartridge velocities, and multiplex panel adoption curves across the projection horizon. Segmentation dimensions included product format, application setting, end-user channel, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to molecular platform displacement of serological methods. Industry-specific inputs incorporated IVDR transition timelines, PFAS reformulation deadlines, and telehealth regulatory clarifications.
Underlying measurement precision varies by segment; PCR assay volumes carry tighter precision than rapid immunoassay estimates due to centralized reporting requirements. Forecasts reflect assumptions regarding reimbursement stability, polymerase supply continuity, and regulatory timeline adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Amoxicillin Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Neurotrophins Market