
 Cell Proliferation Kit Market | 2026-2036
Cell Proliferation Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Proliferation Kit Market Analysis
Market Context
Modular assay bundling is broadening buyer choice as vendors package proliferation reagents with complementary detection chemistries in configurable workflows. Thermo Fisher Scientific leverages its upstream cell culture portfolio to anchor bundled offerings across academic and pharmaceutical accounts. Merck KGaA competes through specialized positions in label-free impedance-based proliferation monitoring, while Bio-Rad Laboratories sustains channel control via its established distribution network in North American research institutions.
Technical Definition and Segment Structure
Cell proliferation kits comprise standardized reagent systems that quantify cellular division rates through metabolic activity indicators, DNA synthesis markers, or direct cell counting protocols, typically employing tetrazolium salt reduction, bromodeoxyuridine analog incorporation, or fluorescent dye dilution as core detection mechanisms. These kits serve primarily to enable reproducible, high-throughput measurement of cell growth kinetics in drug screening, toxicology assessment, and basic research applications. Colony forming unit assays occupy mature positions in stem cell quality control workflows where regulatory submission requirements sustain premium pricing, while EdU-based systems represent the fastest-expanding technology segment due to superior multiplexing compatibility with flow cytometry platforms. Pharmaceutical companies constitute the deepest margin pool among end users, driven by integrated screening operations that prioritize assay standardization over per-test cost minimization.
Regulatory Framework and Outlook
The FDA governs cell proliferation kits used in diagnostic or drug development contexts through in vitro diagnostic and investigational new drug pathway requirements, while ISO 13485 quality management standards shape manufacturing protocols for clinical-grade product lines. The EPA and OSHA additionally influence kit formulation through chemical substance reporting and laboratory safety mandates affecting reagent handling protocols. Stakeholders must monitor evolving FDA guidance on cell-based assay qualification as proliferation readouts gain traction in immuno-oncology potency assays, since regulatory acceptance criteria will determine which detection technologies achieve preferred status in biologics license applications.
Market Dynamics
Pharmaceutical assay standardization mandates are compressing vendor margins while elevating technical entry barriers, forcing kit manufacturers to restructure R&D spend toward FDA-validated workflow documentation rather than novel chemistry development.
Growth Catalysts
- NIH oncology funding concentration:Federally backed cancer centers in the United States maintain bulk procurement contracts for EdU and MTT-based detection systems, creating stable demand anchors for premium reagent suppliers.
- ISO 13485 clinical-grade certification:Quality management standards for in vitro diagnostic manufacturing enable kit vendors to command price premiums in biologics license application workflows.
- Impedance-based label-free monitoring:Real-time proliferation tracking without metabolic dyes reduces assay artifacts and expands compatibility with live-cell imaging platforms in stem cell quality control.
Market Restraints
- Tetrazolium salt input cost volatility:MTT and XTT precursor chemical supply concentrates among specialty chemical producers in Germany and China, exposing kit manufacturers to raw material price swings.
- FDA cell-based assay validation friction:Updated guidance on proliferation readout qualification extends development timelines and requires redundant qualification studies for multiplexed detection formats.
- Flow cytometry substitution pressure:Direct cell counting instruments with automated gating algorithms reduce reliance on colorimetric or fluorescent kit-based quantification in high-throughput screening.
Strategic Opportunities
- India biopharma contract research expansion:CDSCO-aligned clinical trial growth creates demand for standardized proliferation assays in biosimilar development and comparability studies.
- 3D organoid culture convergence:Spheroid proliferation monitoring requires adapted reagent penetration chemistries, opening white space for matrix-compatible EdU formulations.
- EU Green Deal chemical substitution mandates:REACH restrictions on hazardous reagents create regulatory tailwind for aqueous-based, non-toxic metabolic indicator development.
Industry Challenges
- Multiplex assay design talent scarcity:Shortage of specialists combining flow cytometry panel optimization with proliferation kinetics modeling limits vendor innovation velocity.
- Legacy LIMS integration complexity:Pharmaceutical screening facilities require API-compatible data export formats, forcing kit vendors to maintain multiple software adapter development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Proliferation Kit Market |
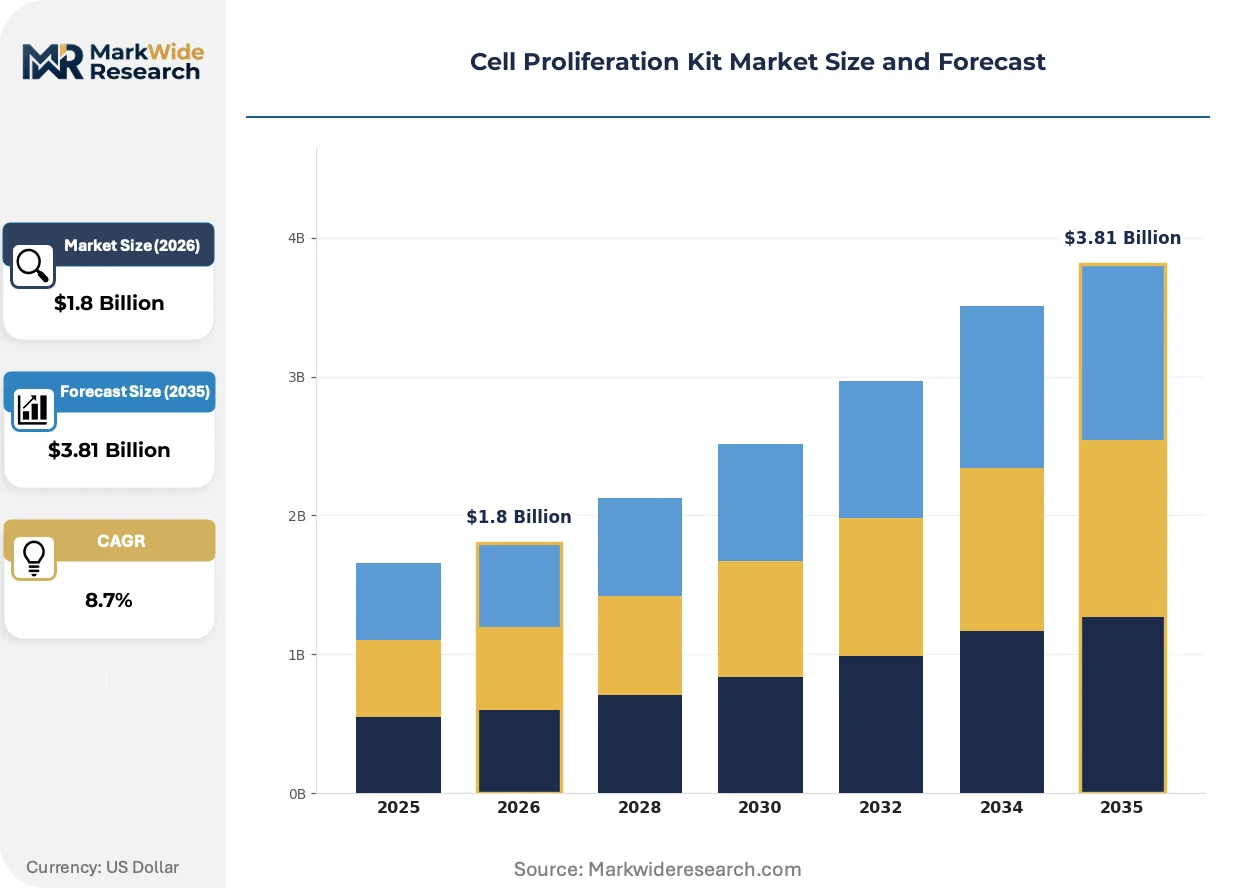
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colony Forming Unit, Cell Counting Kit, MTT Assay, EdU Assay Technology: Flow Cytometry, Microplate Reader, Imaging Systems, Fluorescence Microscopy End User: Pharmaceutical Companies, Academic Research Institutes, Clinical Laboratories, Biotechnology Firms Application: Drug Discovery, Cancer Research, Stem Cell Research, Toxicity Testing |
| Companies Covered | Thermo Fisher Scientific Inc, Merck KGaA, Bio-Rad Laboratories Inc, Becton, Dickinson and Company, Agilent Technologies Inc, PerkinElmer Inc, GE Healthcare, F. Hoffmann-La Roche AG, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Proliferation Kit Market Emerging Trajectories
Detection chemistry convergence with automated imaging platforms is compressing assay turnaround times while elevating data granularity expectations among pharmaceutical screening operations.
Click-chemistry EdU detection is integrating copper-catalyzed azide-alkyne cycloaddition with fluorescent azide reporters to enable DNA synthesis quantification without antibody-based amplification steps. Contract research organizations in the United States and Germany are adopting these streamlined workflows to reduce hands-on time in high-throughput compound screening. The technology is integrating proliferation readouts with simultaneous apoptosis and cell cycle analysis in single-tube multiplex configurations.
REACH substance restriction amendments are phasing out tetrazolium salt formulations containing hazardous reduction products, compelling kit manufacturers to reformulate around resazurin or water-soluble tetrazolium alternatives. European pharmaceutical and academic buyers now prioritize reagent safety data sheet compliance over per-test cost in procurement evaluations. The regulatory shift most acutely affects legacy MTT-based product lines, which face accelerated obsolescence in EU member state markets.
Consolidated procurement through group purchasing organizations is displacing direct vendor relationships in North American academic medical centers. These aggregators negotiate multi-year reagent supply contracts spanning proliferation kits, cell culture media, and detection instrumentation. The purchasing pattern shift concentrates volume with bundled suppliers and marginalizes standalone reagent vendors lacking upstream cell culture portfolio depth.
Cell Proliferation Kit Market Segmentation
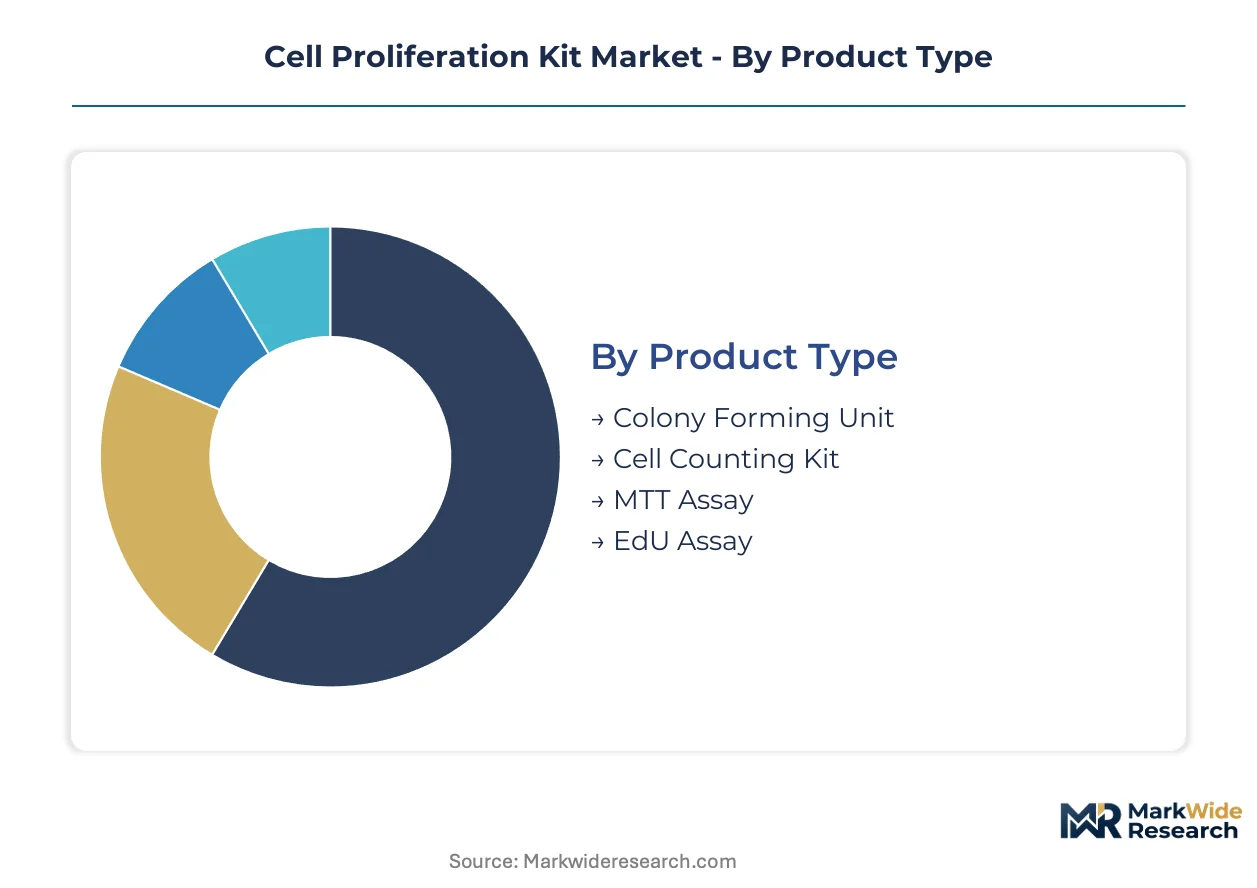
Cell proliferation kit segmentation reflects divergent buyer priorities across standardized screening workflows and specialized research applications. Technology choices determine reagent compatibility requirements, while end-user procurement scale shapes vendor pricing architectures and service bundling strategies.
Product Type:
Volume leadership concentrates in metabolic indicator formats, while premium positioning clusters around DNA synthesis markers with multiplexing capabilities.
- EdU Assay:5-ethynyl-2'-deoxyuridine detection via copper-catalyzed click chemistry enables antibody-free DNA synthesis quantification with superior flow cytometry compatibility. Pharmaceutical high-throughput screening operations in the United States prioritize EdU systems for simultaneous proliferation and apoptosis panel integration.
- MTT Assay:Tetrazolium salt reduction measures mitochondrial dehydrogenase activity as a metabolic proxy for viable cell mass. REACH substance restrictions in Germany and France are accelerating reformulation toward water-soluble tetrazolium alternatives to preserve EU market access.
- Cell Counting Kit:Pre-optimized reagent cocktails reduce protocol development burden for academic laboratories with limited assay validation resources.
- Colony Forming Unit:Long-culture endpoint assays retain regulatory submission utility in stem cell quality control despite extended turnaround times.
Today's leader: MTT Assay. Tomorrow's challenger: EdU Assay.
Technology:
Detection platform selection hinges on throughput requirements versus single-cell resolution needs across pharmaceutical and academic buyer segments.
- Flow Cytometry:Multiparametric analysis platforms enable simultaneous proliferation, cell cycle, and immunophenotyping readouts from single samples. NIH-funded cancer centers in the United States drive concentrated demand for EdU-compatible flow cytometry workflows in immuno-oncology potency assays.
- Microplate Reader:Absorbance and fluorescence detection systems anchor standardized screening operations with lowest per-sample cost structures. Biotechnology firms in India leverage microplate-based MTT and resazurin assays for biosimilar comparability studies under CDSCO-aligned protocols.
- Imaging Systems:Automated microscopy platforms capture spatial proliferation dynamics in 3D organoid cultures with matrix penetration adaptations.
- Fluorescence Microscopy:Manual imaging retains niche positioning in exploratory research settings requiring subcellular localization detail.
Flow cytometry commands the steepest expansion trajectory as multiplexed immuno-oncology assays proliferate.
End User:
Procurement scale and compliance requirements create distinct customer tiers with divergent vendor service expectations.
- Pharmaceutical Companies:Integrated screening operations prioritize assay standardization and FDA-validated documentation over per-test cost minimization. Bulk procurement contracts span multi-year reagent supply with embedded technical support and LIMS integration services.
- Academic Research Institutes:Grant-funded laboratories favor modular kit configurations with publication-grade validation data and open-protocol flexibility.
- Clinical Laboratories:ISO 13485-certified kit requirements sustain premium pricing for diagnostic-grade proliferation assays in biologics license application workflows.
- Biotechnology Firms:Venture-backed development programs balance assay sophistication with capital efficiency in early-stage pipeline screening.
Pharmaceutical companies extract maximum vendor concession through consolidated procurement leverage.
Application:
Research focus areas determine reagent performance specifications and regulatory documentation burdens.
- Drug Discovery:High-throughput compound screening demands 96- and 384-well format compatibility with automated liquid handling integration. Contract research organizations in Germany and the United States specify EdU-based workflows for reduced hands-on time in hit-to-lead progression.
- Cancer Research:Immuno-oncology potency assays require proliferation readouts with cytokine secretion correlation in single-tube configurations.
- Stem Cell Research:Colony forming unit assays retain mandatory status in regulatory submission packages for cell therapy products.
- Toxicity Testing:REACH and EPA chemical safety assessment protocols drive demand for standardized metabolic indicator kits with inter-laboratory validation data.
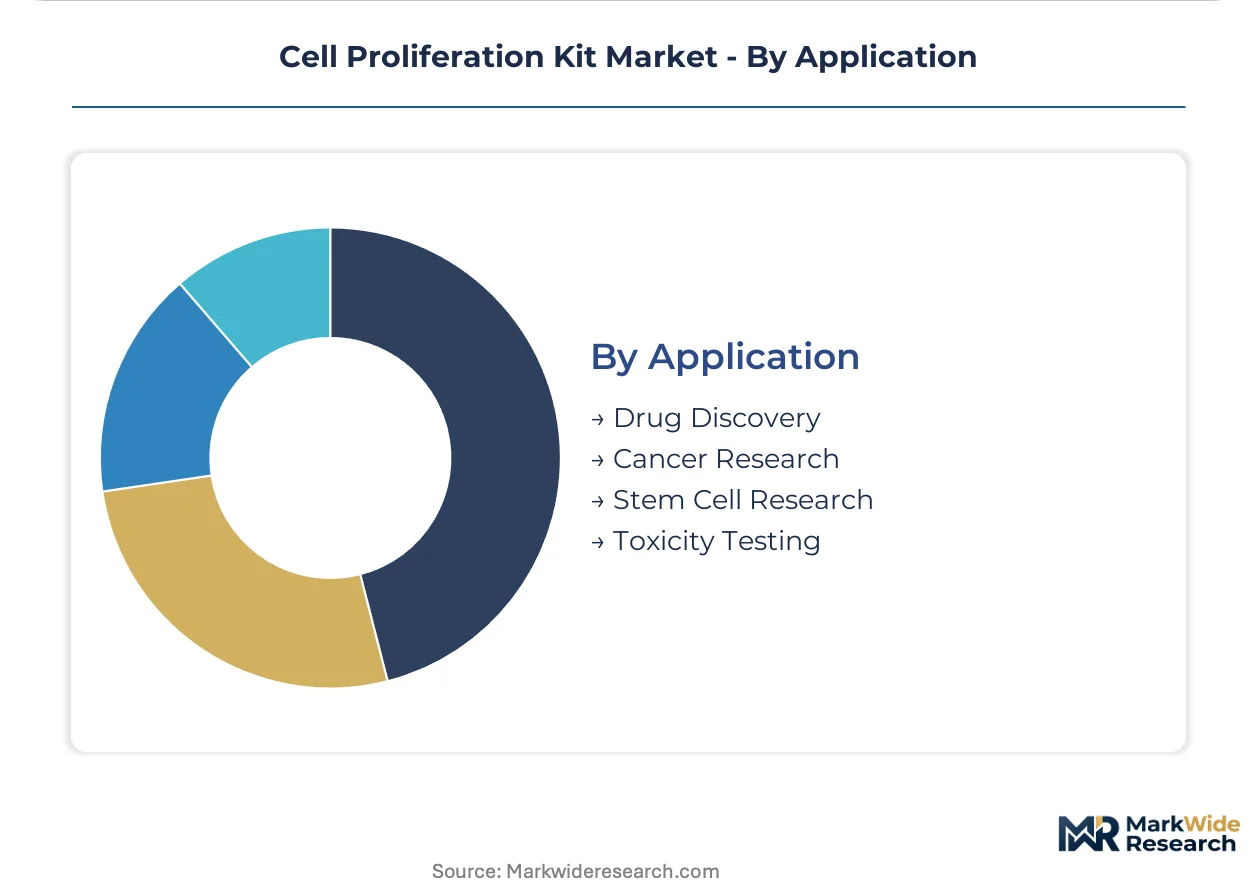
Drug discovery absorbs the largest reagent volume; cancer research exhibits the fastest technology upgrade cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell proliferation kit manufacturing originated in German chemical laboratories during the 1980s, where tetrazolium salt reduction assays were first commercialized for pharmaceutical screening. The industry's geographic footprint now spans five concentrated demand centers.
United States
NIH-funded cancer centers in Boston and San Francisco drive bulk procurement of EdU-based detection systems for immuno-oncology potency assays. FDA guidance on cell-based assay validation shapes kit documentation requirements for biologics license applications. The Cambridge-Boston corridor anchors contract research organization demand for multiplexed proliferation workflows.
Germany
REACH substance restrictions accelerate reformulation of MTT assays toward water-soluble tetrazolium alternatives in pharmaceutical manufacturing. ECHA chemical safety mandates elevate reagent safety data sheet compliance above per-test cost in procurement decisions. The Rhine-Main cluster around Frankfurt sustains specialty chemical production for assay precursor supply.
China
NMPA-aligned clinical trial growth expands demand for standardized proliferation assays in biosimilar development programs. National pharmaceutical regulator standards for in vitro diagnostic manufacturing enable domestic kit vendors to compete in export markets. The Yangtze River Delta biopharma corridor concentrates contract research organization screening operations.
India
CDSCO-aligned biosimilar comparability studies create procurement demand for MTT and resazurin assay systems in Mumbai and Hyderabad development facilities. Central Drugs Standard Control Organization clinical trial regulations mandate standardized proliferation readouts for regulatory submissions. The Genome Valley cluster outside Hyderabad anchors stem cell quality control assay adoption.
United Kingdom
MHRA post-Brexit alignment with FDA assay validation standards preserves pharmaceutical export market access for London-based biotech firms. NHS-funded academic medical centers in Oxford and Cambridge prioritize ISO 13485-certified kits for translational research applications. The Golden Triangle research cluster sustains premium reagent demand through consolidated group purchasing organization contracts.
Cell Proliferation Kit Market Vendor Landscape
Premium-margin players sit above commodity-margin players across assay standardization and regulatory documentation capabilities. The vendor base organizes into three tiers: diversified life science conglomerates with upstream cell culture portfolios, specialized detection chemistry developers, and regional reagent formulators serving price-sensitive academic accounts. Strategic moves concentrate on assay bundling with complementary detection platforms and ISO 13485 certification investment for clinical-grade product lines.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA exemplify the integrated portfolio archetype, leveraging upstream cell culture reagent control to anchor bundled proliferation assay offerings. Bio-Rad Laboratories Inc. occupies a position within the specialized instrumentation tier, sustaining channel relationships through established distribution networks in North American research institutions. These three entities represent divergent competitive vectors: full-workflow integration, label-free detection specialization, and regional channel density.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Merck KGaA |
| Bio-Rad Laboratories Inc |
| Becton, Dickinson and Company |
| Agilent Technologies Inc |
| PerkinElmer Inc |
| GE Healthcare |
| F. Hoffmann-La Roche AG |
| Promega Corporation |
| Others |
Supply Flow & Price Mechanics
Specialist chemists in the Rhine-Main cluster command wage premiums that propagate through clinical-grade kit pricing, widening the spread between ISO 13485-certified formulations and academic-grade alternatives. Labor-cost differentials between German chemical synthesis hubs and Asian formulation centers stratify vendor margins across premium and economy tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated documentation bundles from basic reagent-only configurations. Price differentiation hinges on ISO 13485 certification status and embedded technical support services. Cost compression in the standard tier is intensifying because pharmaceutical procurement consolidation forces volume discounts. Academic laboratories exhibit highest price sensitivity; clinical laboratories demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Boston, and Shanghai orchestrate hub-and-spoke patterns that position bulk reagents within 48-hour delivery windows of major pharmaceutical clusters. Tetrazolium salt precursors draw from specialty chemical producers in Germany and China, while fluorescent dye intermediates rest on Japanese and South Korean suppliers. Single-source vulnerability concentrates in EdU click-chemistry catalyst supply. Distribution runs through life science distributors with integrated cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in clinical-grade certification tiers where regulatory documentation requirements sustain pricing power against commodity reagent alternatives.
For Market Incumbents: To counter REACH-mandated tetrazolium reformulation costs, anchor bundled offerings through upstream cell culture portfolio control and accelerate ISO 13485 certification investment for biologics license application workflows. Backward integration into specialty chemical precursor production in the Rhine-Main cluster defends margin position against raw material volatility. For New Entrants and Emerging Players: Mid-tier biotechnology firms in India and China represent an underserved buyer archetype seeking CDSCO-aligned and NMPA-compliant assay systems without premium vendor pricing. White-space targets include matrix-compatible EdU formulations for 3D organoid cultures and aqueous-based metabolic indicators for EU Green Deal compliance. Go-to-market execution should leverage regional contract research organization partnerships for reference customer development. For Investors and Strategic Acquirers: Diversified life science conglomerates are the most active acquirer in this space, targeting specialized detection chemistry developers with flow cytometry panel optimization capabilities. Long-term viability favors vendors with clinical-grade certification infrastructure and LIMS integration competence. Watch FDA guidance evolution on proliferation readout qualification in immuno-oncology potency assays as the inflection indicator for technology preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Enables premium pricing in biologics license application workflows. |
| EdU Click-Chemistry Platform Integration | Reduces hands-on time for high-throughput pharmaceutical screening operations. |
| REACH-Compliant Reformulation Program | Preserves EU market access as tetrazolium restrictions tighten. |
| LIMS API Development Partnership | Secures pharmaceutical procurement contracts through data interoperability. |
| 3D Organoid Reagent Adaptation | Captures white-space demand in stem cell quality control applications. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and the United Kingdom, with primary inputs from each market cluster. The research combines structured interviews with drug development executives, regulatory affairs leads, GPO contracts managers, and academic laboratory directors with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up reagent volume estimates and top-down market sizing triangulate to produce converged figures.
Rate-of-change decomposition separates volume effects from mix-shift and pricing dynamics across the analysis window. Segmentation dimensions include product type, detection technology, end-user procurement scale, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating NIH funding trajectories, pharmaceutical pipeline screening intensity, and regulatory timeline assumptions for assay validation guidance.
Underlying measurement precision varies by segment; pharmaceutical company and clinical laboratory end-use categories carry tighter precision than academic research estimates due to procurement transparency. Forecasts reflect documented assumptions regarding regulatory acceptance criteria and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Biobank Equipment Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Bioprocess Analyzers and Technology Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Bioprocessing Analytics Equipment Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Lab Automation in Bioanalysis Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Tissue Processor Equipment Market