
 Portable Bioprocessing Bioreactors Market | 2026-2036
Portable Bioprocessing Bioreactors Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Bioprocessing Bioreactors Market Analysis
ISO 13485 certification is unwinding the competitive landscape for portable bioprocessing bioreactors, forcing smaller entrants to invest heavily in quality management systems before securing pharmaceutical contracts. Thermo Fisher Scientific leverages its broad life sciences portfolio to anchor recurring consumable revenue alongside hardware placements. Sartorius AG differentiates through deep specialization in single-use technologies that integrate with its portable bioreactor platforms. Merck KGaA competes by extending its process development services into equipment leasing models that lower capital barriers for biotech startups.
Portable bioprocessing bioreactors are self-contained, mobile culture vessels engineered for aseptic cell propagation and microbial fermentation, typically featuring working volumes under fifty liters with integrated sensors for dissolved oxygen, pH, and temperature monitoring. These systems employ single-use liner technologies or sterilizable stainless-steel chambers to eliminate cross-contamination between batches, serving primarily as scale-down tools for process optimization and as flexible production units for clinical material supply. Stirred tank configurations dominate current installations due to their mechanical familiarity and established scale-up correlations, while wave-mixed platforms are capturing expanding interest in shear-sensitive mammalian cell applications where gentle mixing preserves product integrity. Continuous flow technology is emerging as the fastest-growing segment, driven by intensified interest in perfusion-based manufacturing that maximizes volumetric productivity within constrained facility footprints.
The FDA enforces current Good Manufacturing Practice requirements that dictate validation protocols for portable systems used in commercial biologics production, while the EPA monitors wastewater discharge from bioprocessing facilities that affects site selection for mobile units. EMA's evolving guidance on single-use technologies in sterile manufacturing creates compliance complexity for vendors seeking transatlantic market access. Stakeholders must monitor how evolving pharmacopeial standards for extractables and leachables testing reshape material specifications and supplier qualification burdens across their installed base.
Market Dynamics
Single-use liner technologies are compressing batch turnaround times and eliminating CIP/SIP validation burdens, forcing stainless-steel incumbent vendors to restructure equipment leasing terms or lose biotech startup accounts to disposable platform specialists.
Growth Catalysts
- EMA guidance evolution:The agency's updated sterile manufacturing directives for single-use technologies are accelerating pharmaceutical qualification timelines for portable systems across European contract manufacturing facilities.
- Perfusion intensification:Continuous flow bioreactor configurations are capturing investment from mammalian cell therapy producers seeking volumetric productivity gains in constrained cleanroom footprints.
- Boston-San Francisco corridor:Biotech cluster density in these metropolitan areas is concentrating early deployment capital for scale-down process development tools among venture-funded startups.
Market Restraints
- Film resin supply concentration:Specialized fluoropolymer and multilayer film supply for single-use liners concentrates among a handful of chemical suppliers, exposing bioreactor vendors to input cost volatility and allocation rationing.
- Extractables validation burden:USP Class VI and ISO 10993 biocompatibility testing timelines extend supplier qualification cycles, delaying new material introductions by twelve to eighteen months.
- Stainless-steel substitution threat:Modular hard-piped systems retain cost advantages for high-volume commercial manufacturing, limiting portable disposable penetration beyond clinical-scale production.
Strategic Opportunities
- India CDMO expansion:Contract development organizations in Hyderabad and Bengaluru are adopting portable platforms to serve global biotech clients seeking lower-cost clinical material supply without fixed infrastructure investment.
- Cell and gene therapy convergence:Viral vector production and patient-specific autologous cell processing are creating demand for closed-system portable bioreactors that integrate with automated fill-finish lines.
- Process Analytical Technology mandates:FDA's continued PAT enforcement for commercial biologics is creating specification pull for portable systems with embedded Raman spectroscopy and real-time titer monitoring.
Industry Challenges
- Aseptic processing skill scarcity:Qualified operators capable of maintaining Grade A/B environments during portable system setup and sampling remain concentrated among legacy biologics manufacturers, constraining CDMO expansion velocity.
- Legacy MES integration friction:Portable bioreactor data architectures often require custom middleware development to communicate with established manufacturing execution systems at large pharmaceutical sites, extending deployment timelines.
- ISO 13485 certification timeline:Smaller equipment vendors face eighteen-to-twenty-four-month quality management system implementation periods before securing pharmaceutical supplier status, compressing runway for revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Bioprocessing Bioreactors Market |
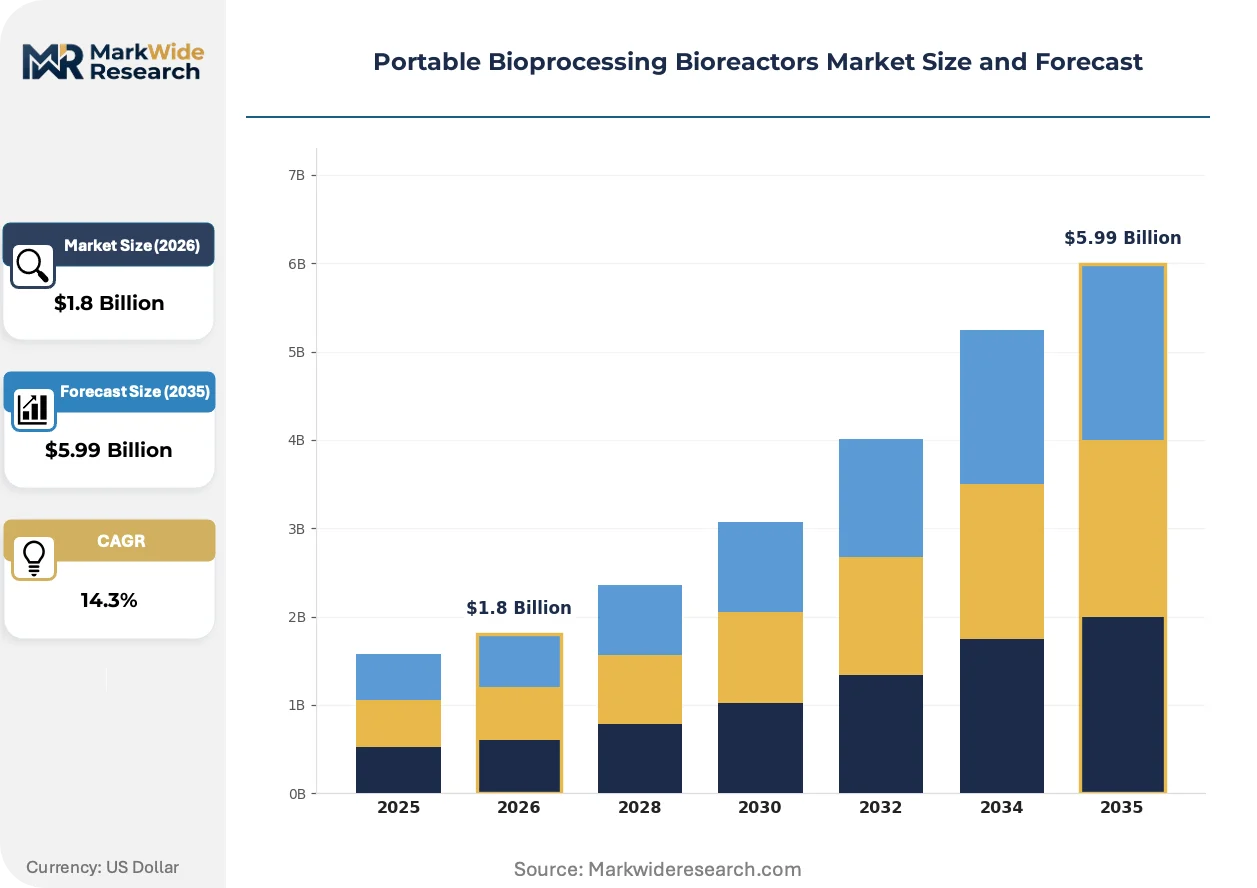
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stirred Tank, Wave-Mixed, Fixed Bed, Batch Technology: Continuous Flow, Disposables, Cell Culture, Fermentation Application: Biopharmaceuticals, Nutraceuticals, Diagnostics, Research End User: Academic Institutions, Pharmaceutical Companies, Biotech Firms, Contract Manufacturing Organizations |
| Companies Covered | Thermo Fisher Scientific, Sartorius AG, Merck KGaA, Eppendorf AG, Cytiva, PBS Biotech, Solaris Biotech, Applikon Biotechnology, Infors HT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Bioprocessing Bioreactors Market Emerging Trajectories
Real-time sensor fusion and disposable electrochemical probes are collapsing the latency between process deviation and corrective intervention, redefining operational excellence benchmarks for distributed biologics manufacturing.
Wave-mixed bioreactor platforms with low-shear agitation mechanisms are displacing conventional stirred-tank configurations in monoclonal antibody process development workflows. Mammalian cell therapy developers are adopting these systems at triple-digit annual placement rates to preserve product integrity in shear-sensitive cultures. This displacement is compressing the addressable market for mechanical agitation hardware and redirecting R&D investment toward film formulation and sensor integration.
FDA's draft guidance on continuous manufacturing quality considerations is tightening validation expectations for portable systems deployed in commercial supply chains. The agency's emphasis on residence time distribution and process dynamics modeling is forcing vendors to develop standardized scale-down correlation packages. Biologics manufacturers with existing commercial approvals are responding by retrofitting portable units with enhanced process analytical technology suites to preempt inspection observations.
Biotech startups are unbundling equipment procurement from consumable supply agreements, rejecting traditional captive sourcing models that lock in liner and sensor purchases at premium markups. This disintermediation is pressuring incumbent vendors to separate hardware pricing from recurring revenue streams and offer transparent component-level sourcing. The pattern is most visible among Series B-funded cell therapy companies in Massachusetts and California, where capital efficiency mandates override vendor loyalty preferences.
Portable Bioprocessing Bioreactors Market Segmentation
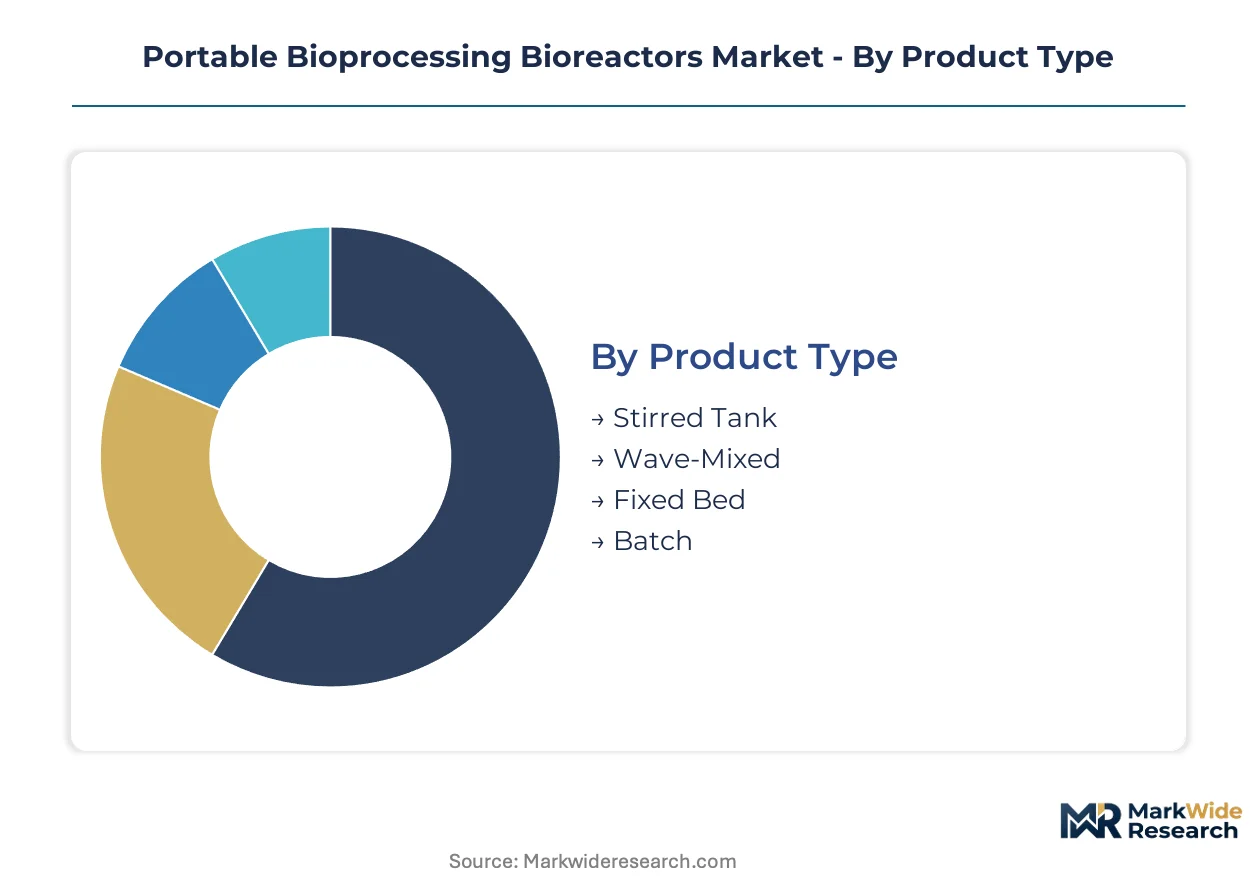
Portable bioprocessing bioreactor segmentation reveals how technology choices cascade through validation requirements, consumable economics, and facility constraints. Product configuration and end-user procurement patterns determine margin capture across hardware, liners, and service revenue streams.
Product Type:
Margin pools concentrate in configurations that minimize validation burden while preserving scale-up fidelity to commercial manufacturing.
- Stirred Tank:Mechanical agitation systems with impeller-driven mixing replicate conventional manufacturing geometries for direct process transfer. Demand clusters among pharmaceutical companies in Massachusetts and California seeking familiar hydrodynamic correlations for monoclonal antibody development. Stainless-steel and single-use variants both command premium positioning where established scale-up protocols reduce regulatory risk.
- Wave-Mixed:Rocking-motion platforms employ low-shear fluid dynamics that preserve viability in shear-sensitive mammalian cultures. Cell therapy developers in Boston and San Francisco corridors are adopting these systems at accelerating rates for autologous processing workflows where product integrity dictates equipment selection.
- Fixed Bed:Packed-bed configurations support adherent cell culture with continuous perfusion capabilities for viral vector production.
- Batch:Traditional fed-batch systems retain cost advantages for high-titer microbial fermentation in nutraceutical applications.
The dominant share belongs to Stirred Tank, while Wave-Mixed is closing the gap fastest.
Technology:
Technology selection tracks directly against facility footprint constraints and the shift toward intensified manufacturing modalities.
- Continuous Flow:Perfusion-enabled systems maximize volumetric productivity through cell retention devices and steady-state operation. CDMOs in Hyderabad and Bengaluru are deploying these platforms to serve global biotech clients seeking clinical material without fixed infrastructure commitment.
- Disposables:Single-use liner technologies eliminate CIP/SIP validation cycles and compress batch turnaround times. The EPA's wastewater discharge monitoring affects site selection for mobile units employing these systems, particularly where effluent treatment capacity is limited.
- Cell Culture:Mammalian expression platforms dominate biopharmaceutical applications requiring post-translational modification capabilities.
- Fermentation:Microbial systems retain cost efficiency for simpler protein products and diagnostic reagent manufacturing.
Continuous Flow commands the steepest expansion trajectory as perfusion intensification reshapes productivity benchmarks.
Application:
Application segmentation reflects divergent regulatory stringency and batch size requirements across end markets.
- Biopharmaceuticals:Commercial and clinical-stage therapeutic protein production imposes current Good Manufacturing Practice compliance with FDA-validated protocols. EMA's evolving sterile manufacturing guidance for single-use technologies creates qualification complexity for vendors seeking transatlantic market access in this segment.
- Nutraceuticals:Dietary supplement and functional food ingredient manufacturing operates under reduced regulatory burden with faster qualification timelines.
- Diagnostics:Reagent and control material production for assay development requires consistent lot-to-lot performance.
- Research:Preclinical process development and academic investigation prioritizes flexibility over commercial validation.
Biopharmaceuticals retains the revenue concentration, though Research volumes expand most quickly among venture-funded startups.
End User:
End-user segmentation captures divergent procurement authority, capital availability, and technical sophistication across buyer types.
- Contract Manufacturing Organizations:CDMOs prioritize platform flexibility to serve multiple client programs without cross-contamination risk. ISO 13485 certification requirements compress competitive dynamics, forcing smaller equipment vendors through eighteen-to-twenty-four-month quality system implementation before securing pharmaceutical supplier status.
- Biotech Firms:Venture-funded startups in Boston and San Francisco corridors unbundle hardware procurement from consumable supply agreements, rejecting captive sourcing models that lock in premium liner pricing.
- Pharmaceutical Companies:Established biologics manufacturers retrofit portable units with enhanced process analytical technology suites to preempt FDA inspection observations on continuous manufacturing quality.
- Academic Institutions:University research programs emphasize capital efficiency and training value over commercial-scale performance.
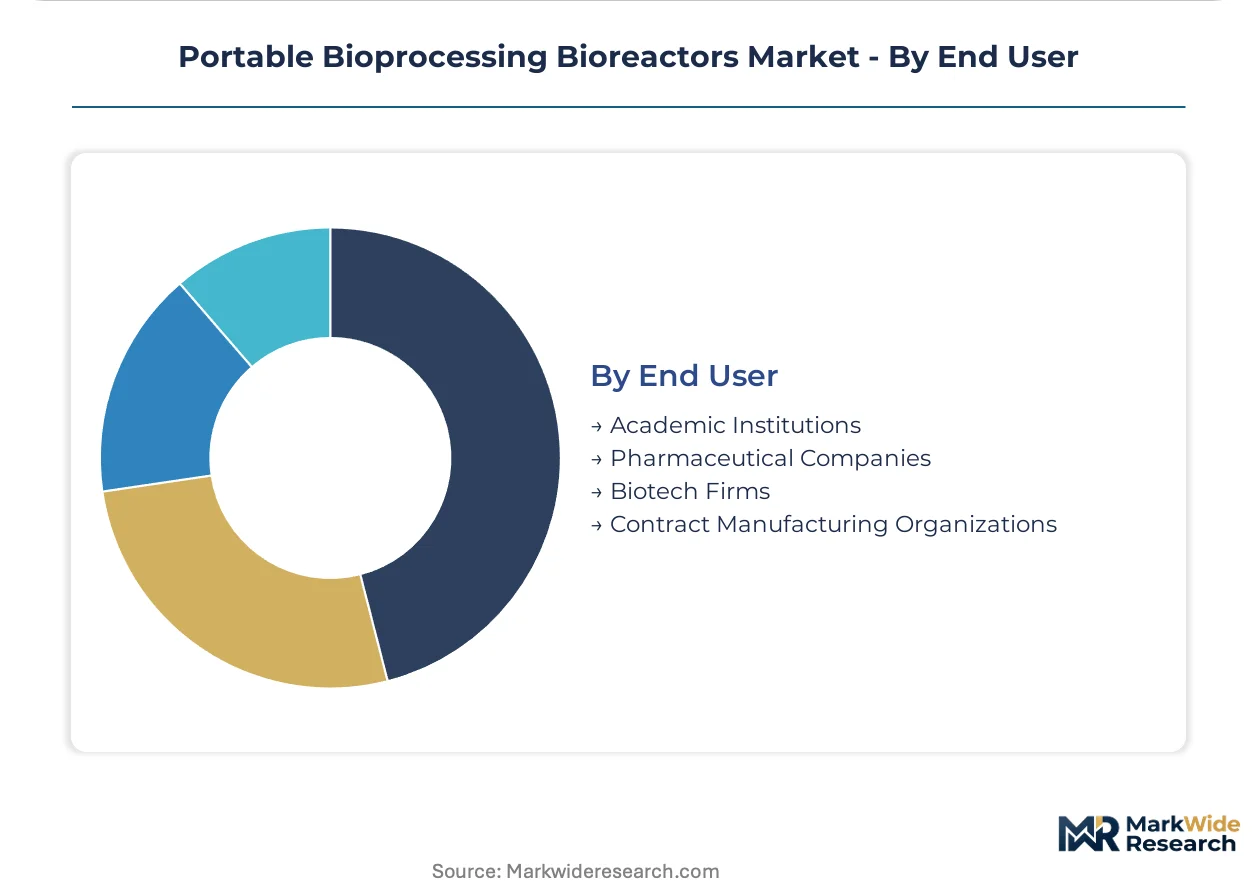
Contract Manufacturing Organizations anchor hardware placement volumes, while Biotech Firms are gaining procurement influence fastest through venture-funded expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA process analytical technology mandates and EMA sterile manufacturing guidance are reshaping equipment procurement patterns across major biopharma clusters. National regulators in Germany, Switzerland, and India are tightening quality system requirements for single-use platform vendors. Venture capital concentration in specific metropolitan corridors is accelerating portable bioreactor deployment for clinical-scale production.
United States
FDA current Good Manufacturing Practice enforcement drives validation protocol investments among Boston and San Francisco biotech startups. The agency's draft guidance on continuous manufacturing quality considerations is tightening expectations for residence time distribution modeling. Massachusetts-based cell therapy developers are retrofitting portable units with enhanced Raman spectroscopy suites to preempt inspection observations.
Germany
EMA evolving guidance on single-use technologies in sterile manufacturing creates transatlantic compliance complexity for equipment vendors seeking European market access. The country's national pharmaceutical regulator emphasizes extractables and leachables testing timelines that extend supplier qualification cycles. Baden-Württemberg industrial clusters concentrate precision engineering capabilities for sensor-integrated bioreactor fabrication.
Switzerland
Swissmedic quality management system requirements compress competitive dynamics for smaller equipment entrants seeking pharmaceutical supplier status. The country's pharmaceutical regulator maintains stringent ISO 13485 certification timelines that filter vendor participation. Basel-area biologics manufacturers are deploying portable platforms for flexible clinical material supply without fixed infrastructure commitment.
India
CDSCO quality system harmonization efforts are accelerating pharmaceutical qualification timelines for contract manufacturing organizations in Hyderabad and Bengaluru. The national pharmaceutical regulator is aligning sterile manufacturing directives with international standards to attract global biotech outsourcing. Telangana-based CDMOs are adopting continuous flow portable systems to serve international clients seeking lower-cost clinical production.
China
NMPA biocompatibility testing requirements for single-use materials reshape supplier qualification burdens across the installed equipment base. The national pharmaceutical regulator is tightening pharmacopeial standards for extractables validation that delay new material introductions. Yangtze River Delta biotech parks are concentrating early deployment capital for scale-down process development tools among domestic startups.
Portable Bioprocessing Bioreactors Market Vendor Landscape
Player mix skews toward diversified life sciences conglomerates with broad consumable portfolios alongside specialized single-use technology pure-plays. Market structure exhibits tiered consolidation where premium-tier vendors anchor recurring revenue through captive liner supply agreements. Two strategic archetypes dominate: full-stack platform providers integrating hardware with process development services, and component specialists focusing on film formulation and sensor miniaturization. Dominant competitive moves include strategic partnerships between equipment vendors and film resin suppliers to secure input material allocation, plus geographic expansion through equipment leasing models that lower capital barriers for biotech startups.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA occupy positions that exemplify platform breadth anchored by recurring consumable revenue streams. Sartorius AG represents the specialization archetype, with its corporate structure signaling deep focus on single-use integration. These three entities collectively illustrate how vendor strategy bifurcates between portfolio scale and technology depth in portable bioprocessing equipment supply.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius AG |
| Merck KGaA |
| Eppendorf AG |
| Cytiva |
| PBS Biotech |
| Solaris Biotech |
| Applikon Biotechnology |
| Infors HT |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month ISO 13485 certification timelines concentrate pricing power among incumbent vendors with established quality management systems, while compressing margins for smaller entrants forced to absorb upfront compliance costs before securing pharmaceutical contracts. This lead-time asymmetry shapes procurement negotiations across contract manufacturing organizations and venture-funded biotech startups alike.
Pricing Analysis
Certification level creates the primary spread between premium-tier and economy-tier equipment offerings, with FDA-validated and EMA-compliant systems commanding substantial markups over research-grade alternatives. Hardware pricing stratifies across premium, standard, and economy tiers based on sensor integration density and process analytical technology readiness, while consumable supply agreements generate recurring revenue streams that subsidize upfront equipment placement. Cost compression in the research-grade segment intensifies as biotech startups unbundle hardware procurement from captive liner sourcing. Contract manufacturing organizations exhibit the lowest price sensitivity due to client-billable cost recovery mechanisms, whereas academic institutions and early-stage startups prioritize capital efficiency over performance specifications.
Supply Chain Analysis
Strategic stockpiling of specialized fluoropolymer films and multilayer liner materials dominates inventory strategy among equipment vendors exposed to allocation rationing from concentrated chemical suppliers. Manufacturing of precision sensors and single-use bioreactor chambers draws from Germany, Switzerland, and the United States for precision engineering capabilities, while specialized film resins source from Japan and the United States for biocompatibility compliance. Supply chain risk centers on single-source vulnerability for USP Class VI certified materials where qualification timelines delay alternative supplier onboarding. Distribution runs through direct sales forces for large pharmaceutical accounts and specialized life sciences distributors for mid-market biotech and academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable bioprocessing bioreactors represent a high-growth disruption as continuous flow perfusion technology reshapes productivity benchmarks and FDA process analytical technology mandates accelerate equipment refresh cycles across commercial biologics manufacturing.
For Market Incumbents: Compound recurring revenue defensibility by deepening captive supply agreements for single-use liners and sensors, while accelerating backward integration into film resin formulation to offset raw material allocation risk from concentrated chemical suppliers. Invest in enhanced Raman spectroscopy and real-time titer monitoring capabilities to preempt regulatory inspection observations on continuous manufacturing quality. Prioritize ISO 13485 certification maintenance as a competitive moat against emerging entrants facing eighteen-to-twenty-four-month quality system implementation timelines. For New Entrants and Emerging Players: Lead with specialized wave-mixed configurations for shear-sensitive mammalian cell therapy applications where incumbent stirred-tank platforms face displacement pressure. Target Hyderabad and Bengaluru contract manufacturing organizations adopting portable platforms for global biotech outsourcing, where lower-cost clinical material supply creates white-space opportunity. Pursue equipment leasing models that lower capital barriers for venture-funded startups in the Boston-San Francisco corridor, bypassing traditional hardware procurement cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across single-use technology pure-plays as recurring consumable revenue scales faster than fixed manufacturing overhead. Acquisition targets should prioritize vendors with established pharmaceutical supplier status and integrated sensor platforms compatible with automated fill-finish lines. Monitor EMA guidance evolution on single-use technologies in sterile manufacturing as the signal indicating transatlantic market access expansion or contraction for emerging equipment platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Resin Supply | Mitigates allocation rationing risk from concentrated fluoropolymer suppliers serving single-use liner production. |
| Process Analytical Technology Suite Enhancement | Addresses FDA draft guidance on continuous manufacturing quality considerations for commercial biologics supply. |
| Equipment Leasing Model Expansion | Lowers capital barriers for venture-funded biotech startups in Massachusetts and California biotech clusters. |
| ISO 13485 Certification Acceleration | Compresses eighteen-to-twenty-four-month quality system timelines to secure pharmaceutical supplier status faster. |
| Wave-Mixed Platform R&D Investment | Captures displacement opportunity in shear-sensitive mammalian cell therapy process development workflows. |
Methodological Framework
The analysis maps stirred tank, wave-mixed, fixed bed, and continuous flow configurations, each validated through interviews with bioprocess engineering directors, regulatory affairs leads at equipment vendors, contract manufacturing organization procurement managers, and academic research facility directors. Primary fieldwork combined with secondary validation from FDA guidance documents, EMA sterile manufacturing directives, ISO 13485 certification databases, and pharmacopeial standards for extractables and leachables testing. Bottom-up equipment placement tracking and top-down biologics manufacturing capacity modeling enable triangulation across independent analytical approaches.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling incorporating product configuration, technology modality, application regulatory stringency, and end-user procurement authority dimensions. CAGRs derive from installed base growth rates, replacement cycle analysis, and intensification trends in perfusion-based manufacturing. Industry-specific forecast inputs include venture capital deployment patterns in Boston and San Francisco biotech corridors and CDMO expansion velocity in Hyderabad and Bengaluru.
The analysis sits within stated boundaries; outcomes outside sustained FDA process analytical technology enforcement and EMA single-use technology guidance stability would require recalibration. Forecasts reflect assumptions regarding biocompatibility testing timeline continuity and film resin supply availability. Revision becomes warranted when regulatory inspection observation patterns or raw material allocation rationing cross thresholds that alter equipment qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Airlift Bioreactors Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
Gel Column Agglutination Test System Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Global Transfection Technologies Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Bioprocessing Analytics Equipment Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Low Endotoxin Gelatin Market