
 Bioprocess Analyzers and Technology Market | 2026-2036
Bioprocess Analyzers and Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Bioprocess Analyzers and Technology Market Outlook
OEM-direct and distribution partnerships for bioprocess instrumentation is reconfiguring as vendors consolidate channel access to large biopharma accounts. Thermo Fisher Scientific dominates North American direct sales with dedicated field application scientists embedded at client sites. Sartorius AG anchors European supply through regional distribution centers serving CMO clusters in Germany and Switzerland. Danaher Corporation leverages its Pall Life Sciences integration to control filtration-to-analytics workflow bundling.
Bioprocess analyzers and technology encompass automated instrumentation systems that measure critical quality attributes during biopharmaceutical manufacturing, including real-time glucose, lactate, and dissolved oxygen monitoring with parts-per-billion detection thresholds. These systems enable process analytical technology compliance and closed-loop control of cell culture and fermentation processes. Cell culture analyzers lead product type revenue due to monoclonal antibody production scale-up, while mass spectrometry technology segments capture premium positioning through multi-attribute method capabilities. Contract Manufacturing Organizations represent the fastest-expanding end user category as externalized biologics capacity demands integrated analytical suites.
FDA process analytical technology guidance and EMA good manufacturing practice Annex 1 revisions shape instrument validation requirements and real-time release testing adoption pathways. ISO 13485 quality management standards and EU MDR conformity procedures govern device classification and market access for analyzer hardware sold into diagnostic-adjacent workflows. Stakeholders must monitor evolving pharmacopoeial standards for biosimilar analytical equivalence as regulators tighten comparability protocol expectations.
Market Dynamics
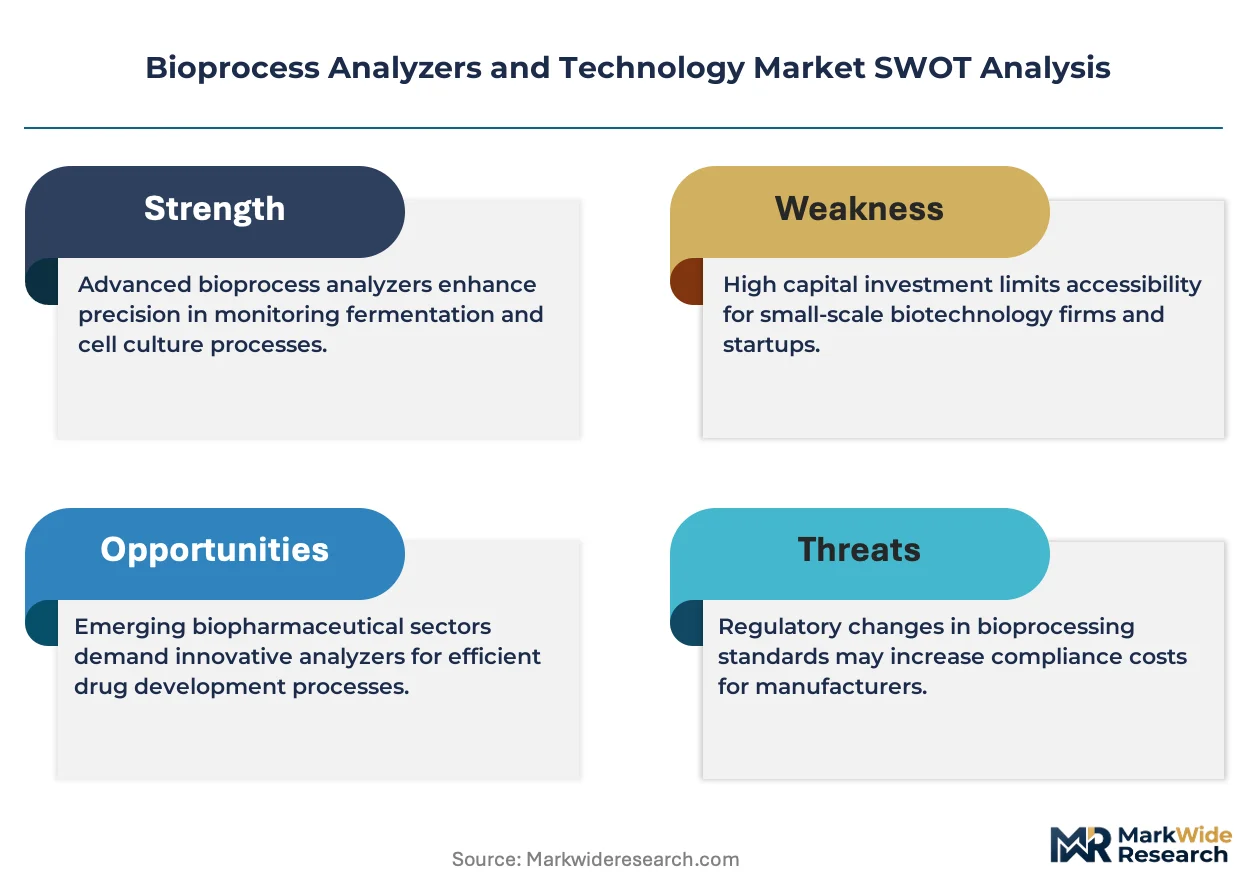
Real-time monitoring mandates from FDA process analytical technology guidance are compressing validation cycles and forcing analyzer vendors to embed compliance-ready software architectures directly into hardware platforms.
Growth Catalysts
- Biologics outsourcing surge:Contract Manufacturing Organizations in Massachusetts and North Carolina are commissioning integrated analytical suites to capture externalized monoclonal antibody production contracts.
- EMA GMP Annex 1 revisions:The European Medicines Agency's contamination control requirements are accelerating real-time microbial monitoring adoption across sterile bioprocessing workflows.
- Multi-attribute mass spectrometry:Cell culture quality control teams are adopting high-resolution mass spec platforms to replace multiple compendial assays with single-run critical quality attribute verification.
Market Restraints
- Sensor consumable cost volatility:Single-use electrochemical probe pricing fluctuates with platinum group metal spot markets, compressing gross margins for high-throughput cell culture operations.
- Optical component supply concentration:Laser diode and photodetector manufacturing concentrates in East Asian foundries, exposing lead times to geopolitical trade friction.
- Validation protocol rigidity:FDA process analytical technology guidance requires extensive method equivalence studies that extend analyzer deployment timelines by 12-18 months versus traditional at-line testing.
Strategic Opportunities
- Continuous bioprocessing penetration:Perfusion cell culture adoption in Switzerland and Germany creates demand for real-time glucose-lactate feedback control systems with sub-minute response latency.
- ISO 13485 diagnostic adjacency:In vitro diagnostic manufacturers are repurposing bioprocess analyzers for cell therapy release testing, opening hardware platforms to regulated medical device workflows.
- Biosimilar comparability protocols:Pharmacopoeial tightening of analytical equivalence standards is forcing biosimilar developers to upgrade from offline HPLC to integrated at-line mass spectrometry suites.
Industry Challenges
- Field application scientist scarcity:Vendors struggle to staff embedded technical support at large biopharma accounts given the specialized intersection of bioprocessing science and analytical instrumentation expertise.
- Legacy distributed control system integration:Brownfield manufacturing facilities face protocol translation complexity when connecting modern OPC-UA-enabled analyzers to 1990s-era proprietary automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioprocess Analyzers and Technology Market |
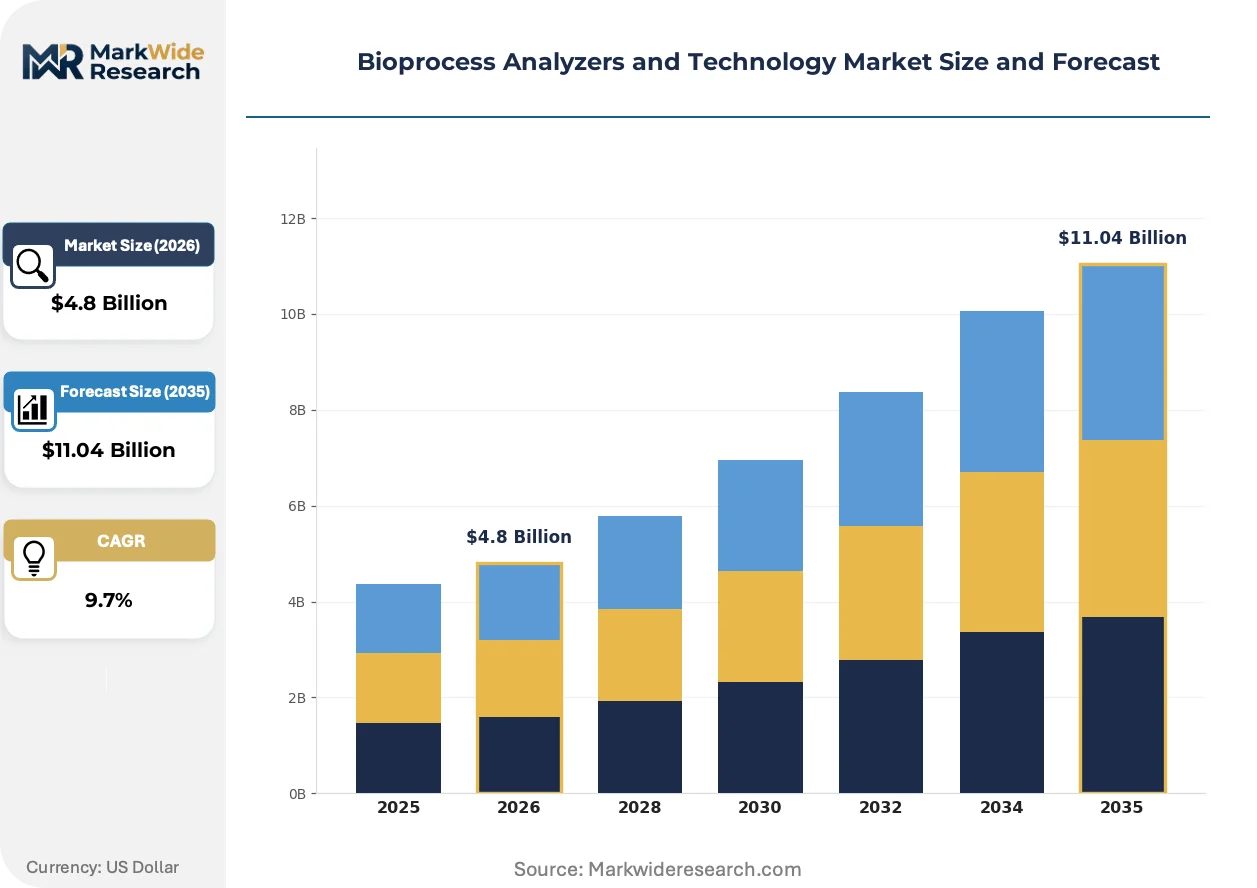
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Culture Analyzers, PCR Analyzers, Spectrophotometers, Autosamplers Technology: Chromatography, Mass Spectrometry, Electrochemical, NIR Spectroscopy End User: Pharmaceutical Companies, Academic Research Institutes, Biotechnology Firms, Contract Manufacturing Organizations Application: Protein Purification, Quality Control, Process Monitoring, Cell Viability |
| Companies Covered | Thermo Fisher Scientific Inc., Sartorius AG, Merck KGaA, Danaher Corporation, GE Healthcare, Roche Diagnostics International AG, Nova Biomedical Corporation, Eppendorf SE, Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioprocess Analyzers and Technology Market Strategic Shifts
Analyzer architectures are converging around embedded intelligence and cloud-native data architectures that compress the gap between measurement and process control action.
Raman spectroscopy is hybridizing with machine learning inference engines to enable real-time titer prediction without sample preparation delays. Biopharma process development groups in the United States are piloting these hybrid systems during clone selection campaigns. The technology is compressing analytical development timelines from months to weeks by eliminating method transfer steps between R&D and manufacturing.
EMA good manufacturing practice Annex 1 revisions are mandating continuous viable particle monitoring in Grade A environments. European fill-finish operators are replacing traditional settle plates with optical bio-fluorescence sensors to meet the new contamination control expectations. German CMO clusters are leading adoption, driven by Swissmedic inspection precedents that penalize retrospective environmental monitoring data gaps.
Service unbundling is fragmenting traditional analyzer procurement into hardware, software, and validation subscription components. Large biopharma accounts in Massachusetts are negotiating separate contracts for instrument platforms, cloud data hosting, and compliance documentation. This pattern is most visible among top-twenty pharmaceutical manufacturers with captive metrology groups capable of self-executing installation qualification protocols.
Bioprocess Analyzers and Technology Market Segmentation
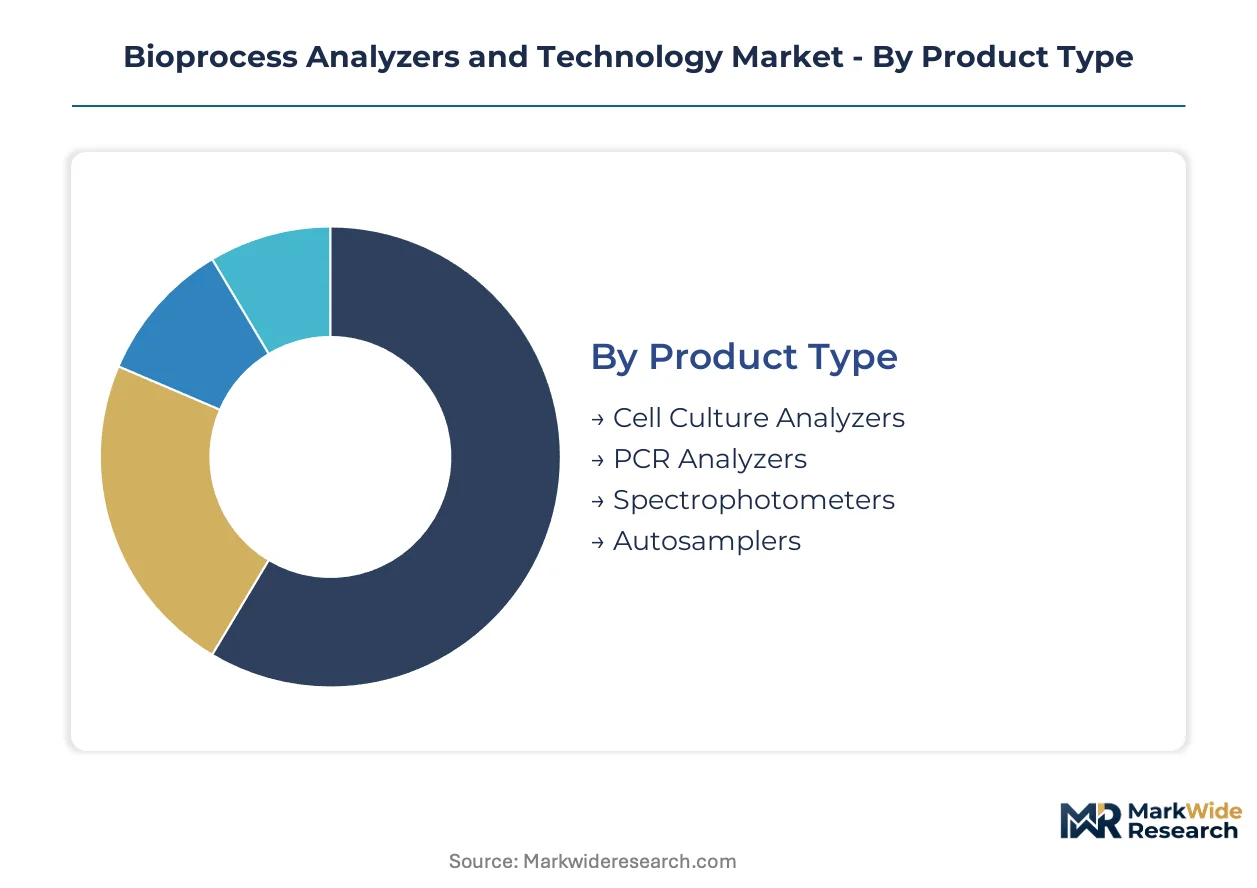
Segmentation in bioprocess analyzers reveals how instrumentation specialization aligns with distinct manufacturing workflows and compliance requirements. Each dimension—product architecture, detection physics, customer procurement patterns, and application criticality—creates discrete competitive arenas with different margin profiles and technical barriers.
Product Type:
Instrumentation selection tracks the biologics manufacturing pipeline from upstream cell culture through downstream purification and release testing.
- Cell Culture Analyzers:Automated systems monitor glucose, lactate, dissolved oxygen, and pH in bioreactor environments with parts-per-billion detection thresholds. Monoclonal antibody production scale-up in Massachusetts and North Carolina drives procurement of multi-parameter probes with integrated feedback control loops.
- Spectrophotometers:UV-Vis and fluorescence platforms quantify protein concentration and aggregate formation during downstream processing. Biotechnology firms in Germany favor diode-array configurations for rapid multi-wavelength scanning during formulation development.
- PCR Analyzers:Quantitative thermal cyclers detect host cell DNA contamination with femtogram sensitivity for regulatory compliance.
- Autosamplers:Robotic liquid handlers integrate with chromatography and mass spectrometry platforms to enable unattended at-line testing during extended perfusion runs.
The dominant share belongs to Cell Culture Analyzers, while Spectrophotometers are closing the gap fastest through adoption in continuous bioprocessing workflows.
Technology:
Detection modality selection reflects the trade-off between analytical specificity, method transfer complexity, and capital deployment requirements.
- Mass Spectrometry:High-resolution platforms enable multi-attribute monitoring of glycosylation patterns, charge variants, and molecular weight in single analytical runs. Contract Manufacturing Organizations in Switzerland are replacing multiple compendial assays with integrated mass spec suites to compress batch release timelines.
- Chromatography:HPLC and UPLC systems separate and quantify product-related impurities with pharmacopoeial compliance. Academic research institutes in the United States deploy these platforms for biosimilar comparability protocol development.
- Electrochemical:Amperometric and potentiometric sensors provide real-time ion and metabolite monitoring with minimal calibration drift.
- NIR Spectroscopy:Non-destructive photon-based platforms enable at-line moisture and content uniformity testing without sample destruction.
Mass Spectrometry commands the steepest expansion trajectory as regulatory pressure intensifies for comprehensive critical quality attribute verification.
End User:
Procurement authority and technical sophistication vary sharply across customer categories, shaping vendor engagement models and service bundling strategies.
- Contract Manufacturing Organizations:External biologics manufacturers commission integrated analytical suites to attract outsourcing contracts from large pharmaceutical sponsors. CMO clusters in North Carolina and Germany are standardizing on vendor-agnostic data architectures to accommodate diverse client quality systems.
- Pharmaceutical Companies:Captive biologics divisions at top-twenty manufacturers deploy analyzers across internal process development and commercial manufacturing networks.
- Biotechnology Firms:Venture-backed developers prioritize flexible platform configurations that scale from clinical material production through commercial launch.
- Academic Research Institutes:University and government laboratories focus on open-architecture systems supporting method innovation and publication requirements.
Contract Manufacturing Organizations are gaining share fastest as biologics outsourcing accelerates, though Pharmaceutical Companies retain the largest installed base.
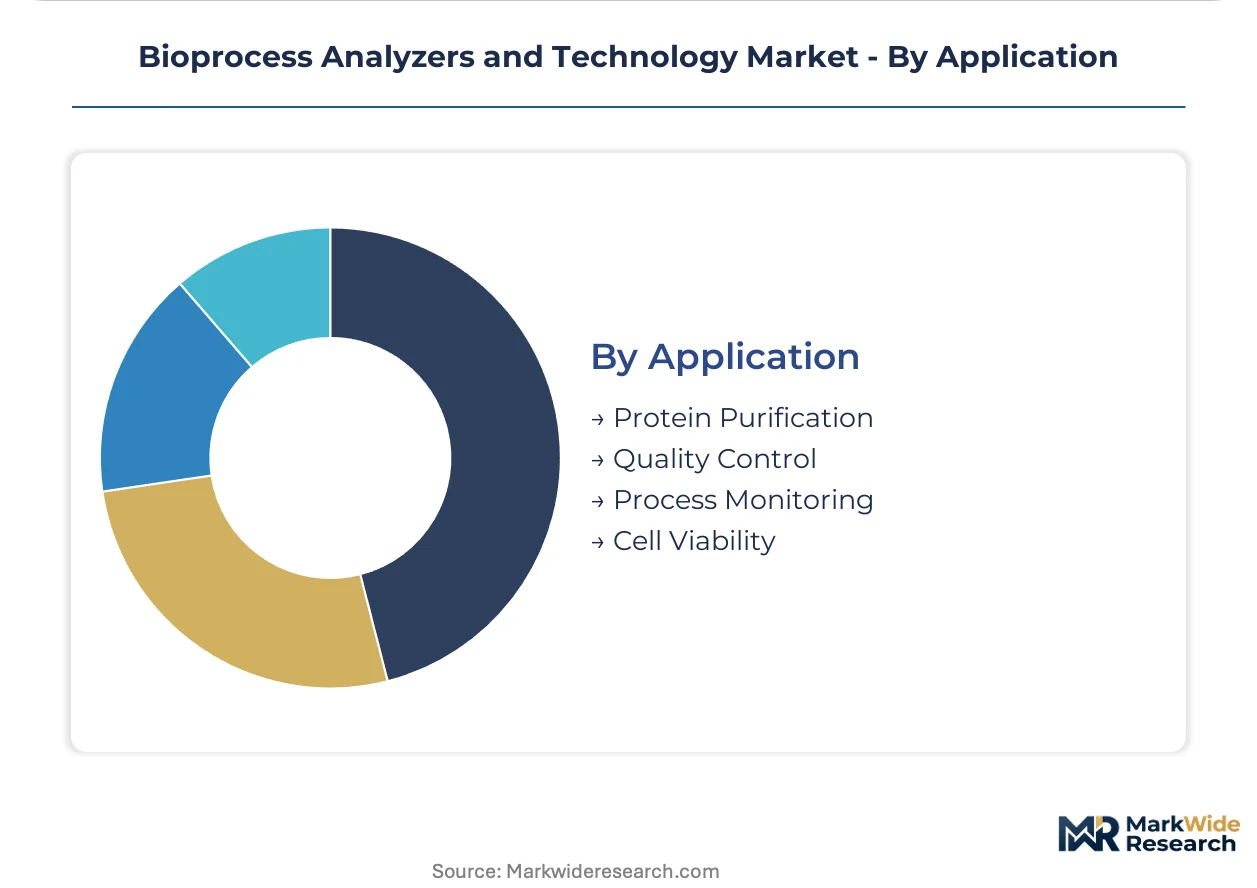
Application:
Workflow positioning determines analyzer specification requirements, from real-time process control through retrospective quality verification.
- Process Monitoring:Real-time glucose-lactate feedback systems with sub-minute response latency enable closed-loop control of perfusion cell culture. German CMOs are piloting these configurations for continuous manufacturing compliance with EMA good manufacturing practice Annex 1 revisions.
- Quality Control:Release testing platforms verify identity, purity, and potency against pharmacopoeial specifications prior to batch disposition.
- Protein Purification:In-line UV and conductivity monitors track column performance and fraction collection during chromatographic separation.
- Cell Viability:Automated trypan blue and fluorescence-based counters quantify viable cell density for seed train and production bioreactor inoculation decisions.
Process Monitoring leads deployment value, while Quality Control applications are expanding most quickly through real-time release testing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Boston's specialized cold-chain infrastructure underwrites Massachusetts' dominance in biologics manufacturing, while direct transatlantic shipping lanes connect German CMO clusters to US East Coast demand centers.
United States
Massachusetts and North Carolina biopharma manufacturing clusters drive instrument procurement for monoclonal antibody production scale-up. FDA process analytical technology guidance mandates real-time monitoring adoption across sterile bioprocessing workflows. Greater Boston's Kendall Square corridor hosts embedded field application scientists from major vendors serving captive biologics divisions.
Germany
Regional distribution centers serving CMO clusters in Baden-Württemberg and Bavaria anchor European supply chain configuration for filtration-to-analytics workflow bundling. EMA good manufacturing practice Annex 1 revisions accelerate real-time microbial monitoring adoption across sterile fill-finish operations. Swissmedic inspection precedents drive German CMO investment in optical bio-fluorescence sensors for Grade A environmental monitoring.
Switzerland
Continuous bioprocessing penetration in Basel-region biologics facilities creates demand for real-time glucose-lactate feedback control systems with sub-minute response latency. Swissmedic inspection protocols penalize retrospective environmental monitoring data gaps, forcing upgrade cycles. The country's pharmaceutical manufacturing density supports premium positioning for multi-attribute mass spectrometry platforms.
China
NMPA regulatory harmonization with ICH quality guidelines drives adoption of closed-loop process control architectures in domestic biologics manufacturing. Yangtze River Delta biopharma parks commission integrated analytical suites to attract multinational outsourcing contracts. Shanghai's Zhangjiang Hi-Tech Park concentrates cell culture analyzer deployment for biosimilar production scale-up.
India
CDSCO tightening of biosimilar analytical equivalence standards forces developers to upgrade from offline HPLC to integrated at-line mass spectrometry suites. Karnataka and Telangana biotech corridors expand CMO analytical capabilities to capture externalized biologics capacity demand. Hyderabad's Genome Valley hosts contract research organizations piloting ISO 13485 diagnostic-adjacent workflows for cell therapy release testing.
Bioprocess Analyzers and Technology Market Competitive Environment
On the supply side, the industry is consolidating around instrumentation conglomerates with captive filtration and separation portfolios, while mid-scale specialists defend position through embedded technical service models. Three archetypes dominate: diversified life science conglomerates controlling workflow bundling, European precision instrumentation houses with regional distribution density, and North American analytical platform vendors with direct field application scientist deployment. Competitive moves concentrate on strategic partnerships for data architecture integration and vertical integration into single-use consumables manufacturing.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify supply-side concentration through workflow control spanning filtration to analytics. Sartorius AG occupies a position among European precision instrumentation houses with regional distribution center networks. These three anchors represent distinct strategic postures: North American direct sales embedding, integrated Pall Life Sciences filtration-to-analytics bundling, and German-Swiss CMO cluster service density.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Sartorius AG |
| Merck KGaA |
| Danaher Corporation |
| GE Healthcare |
| Roche Diagnostics International AG |
| Nova Biomedical Corporation |
| Eppendorf SE |
| Agilent Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese bioprocess analyzer component foundries is compressing pricing power for optical sensor modules while simultaneously incentivizing vendor consolidation around captive consumables manufacturing. This utilization dynamic rewards integrated suppliers with backward control over electrochemical probe production while squeezing pure-play hardware vendors into service-heavy contract structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations between large biopharma accounts and instrumentation vendors. Premium tiers bundle embedded field application scientists and validation documentation; standard tiers trade service intensity for hardware-only pricing; economy tiers serve academic institutes with minimal after-sales support. Cost compression in the economy tier is intensifying because single-use sensor consumables now absorb platinum group metal spot volatility directly. Contract Manufacturing Organizations exhibit the highest price sensitivity due to competitive outsourcing contract margins, while top-twenty pharmaceutical manufacturers prioritize compliance bundling over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for laser diode and photodetector procurement. Manufacturing concentrates in Taiwan, South Korea, and Japan for optical components essential to Raman spectroscopy platforms. Raw material dependencies include platinum group metals for electrochemical probes, high-purity fused silica for flow cells, and rare-earth phosphors for fluorescence detection modules. Single-source vulnerability persists for field-programmable gate arrays used in embedded signal processing. Distribution runs through regional distribution centers in Germany and Massachusetts serving CMO clusters with vendor-agnostic data architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioprocess analyzers sit in early-cycle expansion as FDA process analytical technology guidance mandates real-time monitoring adoption across sterile bioprocessing workflows. This regulatory tailwind accelerates replacement of at-line testing with closed-loop control architectures.
For Market Incumbents: Build switching-cost moats through embedded field application scientist deployment at large biopharma accounts. Consolidate position by acquiring single-use consumables manufacturers to capture probe replacement revenue streams. Threaten pure-play hardware vendors with integrated Pall Life Sciences-style filtration-to-analytics bundling that locks in workflow control.
For New Entrants and Emerging Players: Indian CDSCO regulatory tightening creates immediate white-space opportunity as biosimilar developers upgrade from offline HPLC to at-line mass spectrometry suites. Target ISO 13485 diagnostic-adjacent workflows in Hyderabad's Genome Valley for cell therapy release testing contracts. Lead with cloud-native data architectures that accommodate diverse client quality systems without legacy distributed control system integration burdens.
For Investors and Strategic Acquirers: Capital is best deployed toward European precision instrumentation houses with regional distribution density serving German and Swiss CMO clusters. Long-term viability hinges on continuous bioprocessing penetration in perfusion cell culture applications. Watch Swissmedic inspection precedents as the signal indicating upgrade cycle acceleration for environmental monitoring sensors.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Field Application Scientist Deployment | Thermo Fisher Scientific's Kendall Square embedding locks in Massachusetts biopharma accounts through technical dependency. |
| Single-Use Consumables Backward Integration | Captive probe manufacturing insulates margins from platinum group metal spot market volatility. |
| Cloud-Native Data Architecture Partnership | Vendor-agnostic platforms accommodate diverse CMO client quality systems without protocol translation complexity. |
| ISO 13485 Diagnostic Adjacency Certification | Cell therapy release testing opens hardware platforms to regulated medical device workflows with premium pricing. |
| Continuous Bioprocessing Control System Development | Sub-minute glucose-lactate feedback latency captures EMA GMP Annex 1 compliance-driven upgrade cycles. |
Study Parameters
Operator-level perspectives from bioprocess engineers, field application scientists, CMO quality directors, and regulatory affairs leads anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from FDA guidance documents, EMA GMP Annex 1 revisions, ISO 13485 certification records, and pharmacopoeial standard updates. Bottom-up instrumentation unit economics triangulated against top-down biologics manufacturing capacity expansion announcements.
Scenario-bracketing framed demand projections across the analysis window using regulatory adoption curves and continuous bioprocessing penetration rates. Segmentation dimensions modeled include product architecture, detection physics, end-user procurement authority, and application criticality from process monitoring through quality control. CAGRs derived from instrument replacement cycles and new facility commissioning schedules, with specific inputs from monoclonal antibody production scale-up announcements and biosimilar analytical equivalence protocol tightening.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified life science conglomerates into single-use consumables manufacturing would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Botanical Extraction Equipment Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market