
 Cell Culture Media, Sera, and Reagents Market | 2026-2036
Cell Culture Media, Sera, and Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Culture Media, Sera, and Reagents Market Analysis
Contract development and manufacturing organizations is bifurcating as biotech firms bring media preparation in-house to protect proprietary cell lines and reduce lot-to-lot variability. Thermo Fisher Scientific leverages its Gibco brand portfolio and global distribution network to dominate research-grade media supply. Lonza Group specializes in chemically defined formulations for biologics manufacturing, anchoring its position in regulated pharmaceutical workflows. Merck KGaA competes through its MilliporeSigma division with integrated filtration and media systems that reduce contamination risk.
Cell culture media, sera, and reagents constitute formulated nutrient solutions, supplements, and auxiliary chemicals that sustain mammalian, insect, or microbial cell viability and proliferation under controlled laboratory conditions, typically comprising amino acids, vitamins, salts, and buffers balanced against pH and osmolality parameters for specific cell line requirements. These products enable industrial-scale production of monoclonal antibodies, viral vectors, and cell therapies where batch consistency directly determines therapeutic yield and regulatory compliance. Liquid formulations lead volume consumption due to ready-to-use convenience in high-throughput pharmaceutical screening, while lyophilized formats capture margin pools in specialized stem cell research where extended shelf stability offsets premium pricing. Pharmaceutical companies represent the dominant end-user channel by value, though CROs are expanding fastest as virtual biotech companies outsource entire development pipelines without captive manufacturing infrastructure.
FDA guidance on chemistry, manufacturing, and controls for cell and gene therapy products is elevating documentation requirements for media traceability and raw material qualification, compelling suppliers to invest in supply chain transparency. EMA's Annex 1 revision on sterile manufacturing and the EU's forthcoming pharmaceutical strategy reinforce chemically defined, animal-component-free formulations as baseline market access requirements. REACH restrictions on substance hazards and ISO 13485 quality management standards further constrain formulation flexibility for European suppliers. Stakeholders must monitor regulatory divergence between FDA expedited pathways and EMA's evolving advanced therapy medicinal products framework when allocating R&D investment across formulation portfolios.
Market Dynamics
Biotech firms are internalizing media preparation capabilities to shield proprietary cell line IP from contract manufacturing exposure, compressing traditional CDMO revenue pools while elevating demand for chemically defined, animal-component-free formulations that satisfy tightening FDA and EMA documentation requirements.
Growth Catalysts
- Gene therapy manufacturing scale-up:Viral vector production lines in the United States, China, and Germany require specialized serum-free media formulations that command premium positioning.
- EMA Annex 1 revision:The updated sterile manufacturing mandate accelerates displacement of fetal bovine serum with chemically defined alternatives across European biologics facilities.
- Stem cell research expansion:Academic and commercial regenerative medicine programs in Japan and South Korea drive lyophilized media consumption for extended shelf stability.
Market Restraints
- Fetal bovine serum supply concentration:South American collection networks dominate raw serum sourcing, exposing buyers to geopolitical disruption and lot-to-lot variability risks.
- High-purity amino acid input costs:Pharmaceutical-grade raw material pricing volatility compresses margin structures for mid-tier media suppliers.
- FDA chemistry, manufacturing, and controls documentation:Extended qualification timelines for cell and gene therapy media formulations delay product commercialization by 18-24 months.
Strategic Opportunities
- India biologics manufacturing emergence:CDSCO regulatory alignment with ICH standards opens contract manufacturing demand for export-compliant chemically defined media.
- Perfusion bioreactor technology convergence:Continuous manufacturing platforms require specialized feed formulations that sustain cell viability at high densities over extended production cycles.
- Direct-to-laboratory distribution channels:E-commerce platforms bypass traditional distributor markups for research-grade media in academic and startup biotech segments.
Industry Challenges
- Cell culture scientist talent scarcity:Formulation chemistry and scale-up biology expertise concentrates at incumbent suppliers, constraining new entrant hiring pipelines.
- ISO 13485 certification timelines:Medical device-grade quality management system implementation extends 12-18 months for media suppliers targeting cell therapy device integration.
- Legacy ERP integration friction:Electronic batch record systems from incumbent manufacturing execution platforms resist seamless data exchange with modern cloud-based inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Culture Media, Sera, and Reagents Market |
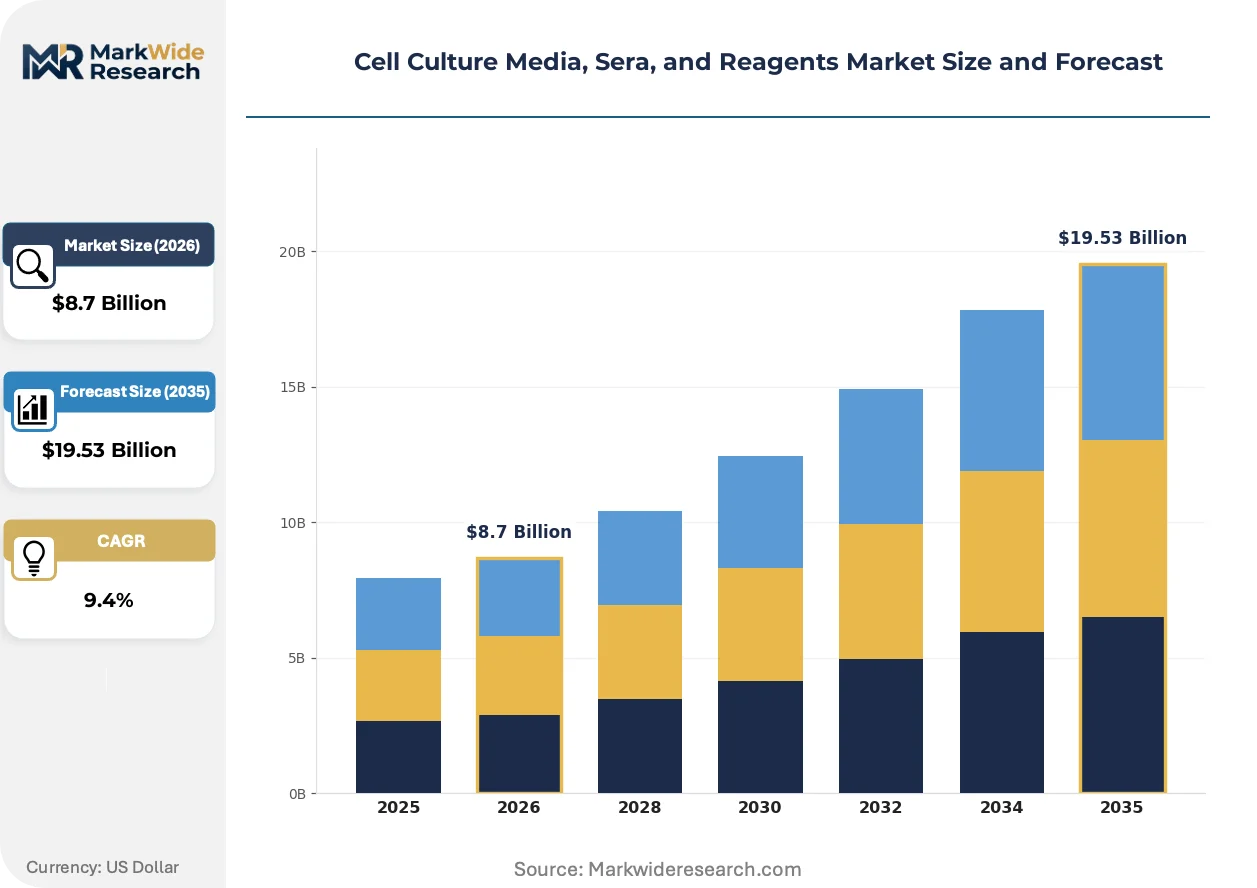
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Salts, Buffers End User: Pharmaceutical Companies, Academic Institutions, CROs, Biotech Firms Application: Drug Development, Vaccine Production, Toxicity Testing, Stem Cell Research Form: Liquid, Powder, Frozen, Lyophilized |
| Companies Covered | Lonza Group, Corning Incorporated, Thermo Fisher Scientific, Becton Dickinson and Company, FUJIFILM Corporation, Merck KGaA, Sartorius AG, Avantor, Inc., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Culture Media, Sera, and Reagents Market Emerging Trajectories
Automation and artificial intelligence are compressing media formulation development cycles while regulatory pressure on animal-derived components accelerates investment in synthetic alternatives and precision fermentation platforms.
Machine learning-driven media optimization is fragmenting traditional formulation development workflows. Algorithms trained on cell line-specific metabolomic data now predict nutrient requirements faster than empirical screening. Biotech firms with captive computational biology teams are bringing this capability in-house. The technology is fragmenting historical supplier lock-in by enabling customer-side formulation customization.
REACH restrictions on substance hazards are constraining formulation flexibility for European suppliers. The ECHA regulatory framework now requires extensive toxicity documentation for novel chemical additives in cell culture applications. German and Swiss media manufacturers are responding by accelerating substitution programs for flagged compounds ahead of sunset dates.
Consolidated procurement contracts are displacing transactional spot purchasing among large pharmaceutical manufacturers. Multi-year supply agreements with built-in volume commitments and price collars now dominate biologics manufacturing procurement. This pattern is most visible in United States-based monoclonal antibody production facilities where supply security outweighs unit cost optimization.
Cell Culture Media, Sera, and Reagents Market Segmentation
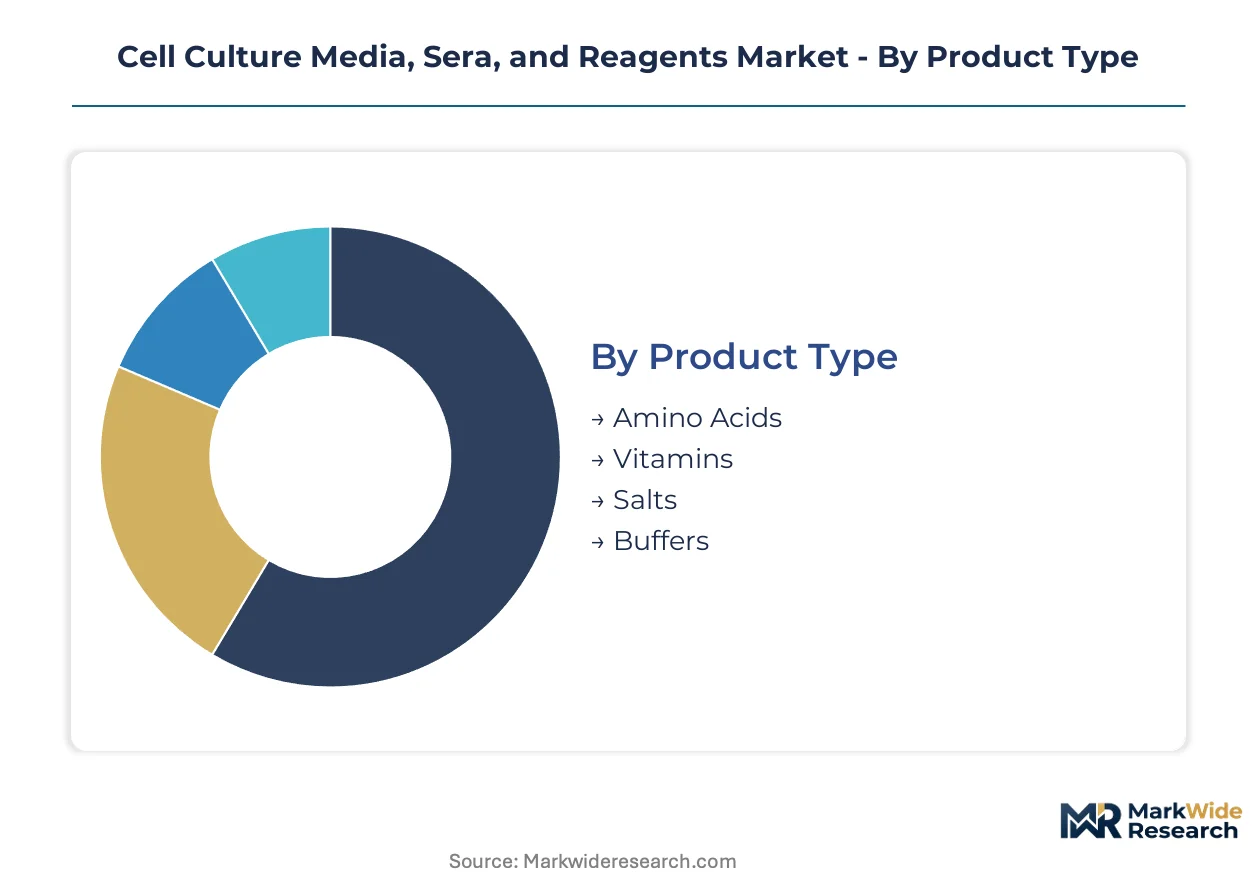
Formulation choices in cell culture media directly determine regulatory pathway eligibility and manufacturing economics. Segment boundaries shift as FDA and EMA documentation requirements tighten around animal-component traceability and raw material qualification protocols.
Product Type:
FDA chemistry, manufacturing, and controls guidance elevates documentation burdens unevenly across input categories, with amino acid traceability commanding the most extensive supplier qualification protocols.
- Amino Acids:Pharmaceutical-grade amino acids constitute the largest cost component in chemically defined formulations. Biologics manufacturers in the United States and Germany demand extensive impurity profiling and origin documentation to satisfy FDA and EMA submission requirements.
- Vitamins:Heat-labile vitamin formulations require cold-chain logistics that constrain supplier geography. Japanese and South Korean stem cell research programs drive premium consumption of stabilized vitamin derivatives with extended potency guarantees.
- Salts:Balanced salt solutions provide osmotic stability across mammalian and insect cell platforms.
- Buffers:pH buffering systems anchor formulation stability during scale-up bioreactor operations.
Established volume favors amino acids; emerging adoption favors vitamins.
End User:
Procurement authority concentrates differently across customer types, with pharmaceutical companies wielding consolidated contract leverage while biotech firms prioritize formulation flexibility over unit cost.
- Pharmaceutical Companies:Large-scale monoclonal antibody manufacturers negotiate multi-year supply agreements with built-in volume commitments and technical service provisions. United States-based production facilities anchor global demand concentration for chemically defined, animal-component-free formulations.
- Biotech Firms:Virtual and mid-cap biotechnology companies lack captive manufacturing infrastructure, outsourcing entire media preparation workflows to specialized suppliers. These customers prioritize rapid formulation customization and IP protection over per-liter pricing.
- Academic Institutions:Research universities and medical schools consume research-grade media through distributor networks or direct e-commerce procurement.
- CROs:Contract research organizations serve as procurement intermediaries for sponsor companies without internal cell culture capabilities.
Pharmaceutical companies dominate contract value; biotech firms are climbing the fastest.
Application:
EMA Annex 1 sterile manufacturing mandates and FDA cell and gene therapy guidance create divergent formulation specifications across therapeutic categories.
- Drug Development:Small-molecule and biologic drug discovery programs require high-throughput screening media with batch-to-batch consistency guarantees. Toxicology studies demand chemically defined formulations to eliminate confounding variables from serum lot variability.
- Vaccine Production:Viral vector manufacturing for gene therapy applications commands specialized serum-free media formulations. Production facilities in China and Germany are scaling capacity to meet COVID-19 pandemic-era capacity expansion commitments.
- Toxicity Testing:Regulatory toxicology laboratories require standardized media for OECD-compliant in vitro assays.
- Stem Cell Research:Pluripotent and induced pluripotent stem cell protocols demand specialized growth factor supplementation.
Vaccine production captures investment attention; stem cell research offers steepest expansion trajectory.
Form:
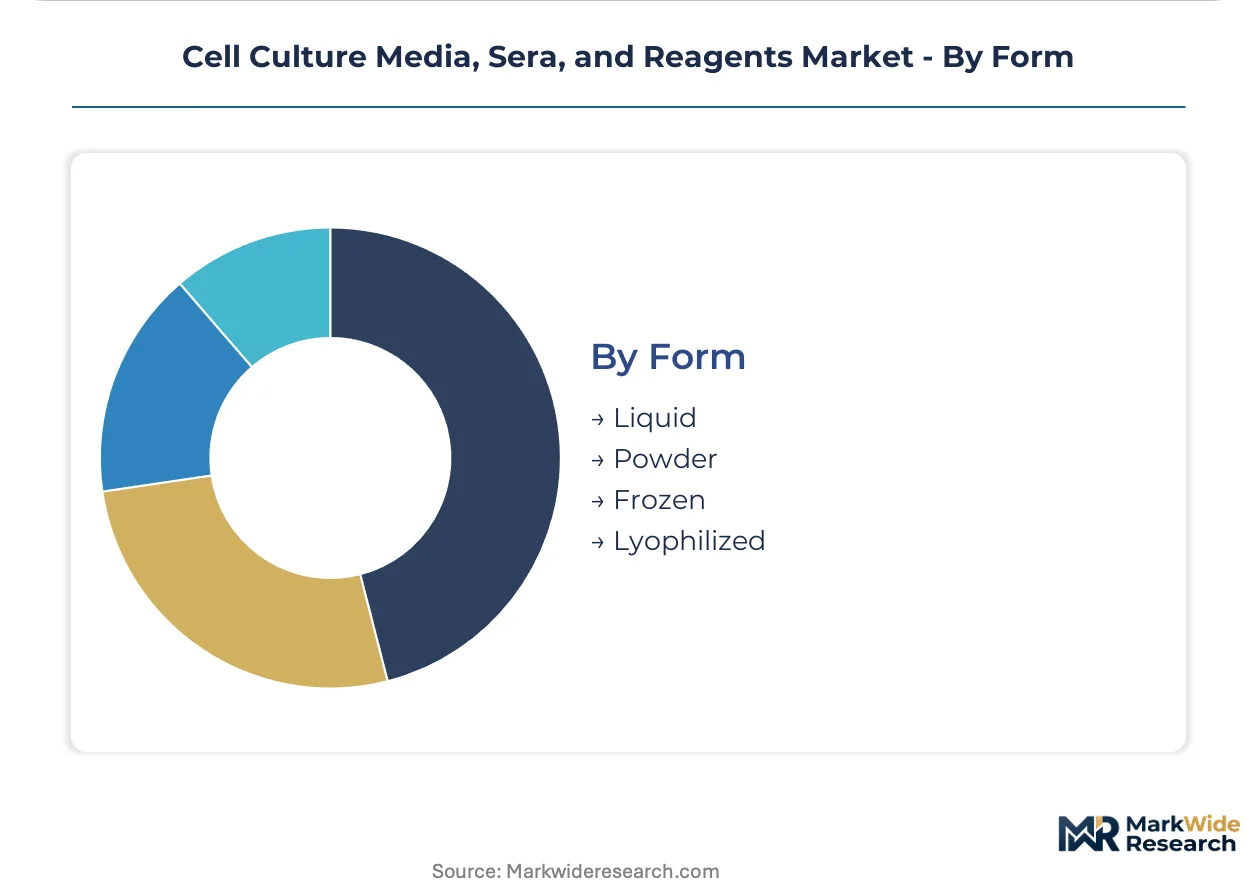
Physical formulation determines shelf stability, shipping economics, and end-user preparation burden, with liquid formats dominating high-throughput pharmaceutical workflows.
- Liquid:Ready-to-use liquid media eliminate reconstitution steps in high-throughput screening and GMP manufacturing environments. United States biologics facilities consume the majority of research-grade and clinical-grade liquid volumes due to concentration of monoclonal antibody production.
- Lyophilized:Freeze-dried formulations extend shelf stability for specialized stem cell and primary cell applications where lot consistency outweighs preparation inconvenience. Japanese regenerative medicine programs drive premium positioning for lyophilized specialty media.
- Powder:Dry powder concentrates reduce shipping weight for international distribution to remote research sites.
- Frozen:Deep-frozen formulations preserve heat-labile growth factors for primary cell culture applications.
Liquid commands operational scale; lyophilized gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers and gene therapy developers concentrate procurement authority in the United States, Germany, and China, where biologics production clusters and tightening FDA and EMA documentation requirements reshape supplier qualification protocols.
United States
Monoclonal antibody production facilities in Massachusetts and North Carolina drive demand for chemically defined, animal-component-free formulations. FDA chemistry, manufacturing, and controls guidance for cell and gene therapy products mandates extensive media traceability documentation. The Greater Boston biotech corridor anchors viral vector manufacturing scale-up for gene therapy pipelines.
Germany
EMA Annex 1 sterile manufacturing revisions accelerate displacement of fetal bovine serum across Bavarian and North Rhine-Westphalia biologics facilities. REACH restrictions on substance hazards constrain formulation flexibility for domestic suppliers. The Rhine-Main biotechnology cluster concentrates perfusion bioreactor adoption for continuous manufacturing platforms.
China
NMPA regulatory alignment with ICH standards opens domestic biologics manufacturing to export-compliant chemically defined media. Viral vector production lines in Suzhou and Shanghai scale capacity to meet gene therapy pipeline demand. The Yangtze River Delta anchors contract manufacturing organization expansion for international pharmaceutical outsourcing.
Japan
Regenerative medicine programs in Kanto and Kansai regions drive premium consumption of lyophilized specialty media for induced pluripotent stem cell applications. PMDA guidelines on advanced therapy medicinal products elevate raw material qualification requirements. The Tokyo-Yokohama corridor concentrates academic and commercial stem cell research infrastructure.
India
CDSCO regulatory harmonization with ICH standards attracts contract manufacturing investment from multinational pharmaceutical firms. Biologics production facilities in Maharashtra and Telangana expand in-house cell culture capabilities. The Hyderabad-Visakhapatnam pharmaceutical belt scales serum-free media consumption for biosimilar manufacturing.
Cell Culture Media, Sera, and Reagents Market Vendor Landscape
Player mix skews toward diversified life science conglomerates with integrated filtration and media systems, while specialized chemical suppliers occupy formulation niches. Market structure concentrates around three archetypes: research-grade portfolio generalists, chemically defined formulation specialists, and integrated bioprocessing system providers. Dominant competitive moves include strategic partnerships for continuous manufacturing feed development and geographic expansion into emerging biologics manufacturing clusters.
Among diversified life science conglomerates, Thermo Fisher Scientific, Merck KGaA, and Danaher Corporation exemplify the integrated system provider archetype. Thermo Fisher Scientific occupies a position anchored by global distribution infrastructure. Merck KGaA represents the European formulation specialist model with integrated quality management systems. Danaher Corporation sits within the analytical and bioprocessing convergence tier. These three conglomerates anchor competitive positioning through supply chain breadth rather than formulation depth alone.
| Leading Market Players |
|---|
| Lonza Group |
| Corning Incorporated |
| Thermo Fisher Scientific |
| Becton Dickinson and Company |
| FUJIFILM Corporation |
| Merck KGaA |
| Sartorius AG |
| Avantor, Inc. |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
Bioreactor-scale manufacturing economics concentrate purchasing power among monoclonal antibody producers in the United States and Germany, compressing unit costs for chemically defined formulations while elevating price floors for serum-free alternatives that satisfy FDA and EMA documentation requirements. This scale asymmetry stratifies the supplier base between volume-leveraged pharmaceutical contracts and premium-positioned specialty media for gene therapy applications.
Pricing Analysis
Cost-plus contracts with pharmaceutical-grade amino acid indexation dominate large-volume agreements, tying media pricing to raw material volatility while capping supplier margins. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified chemically defined formulations from research-grade alternatives and commodity basal media. Pricing pressure stems from South American fetal bovine serum supply instability and REACH-driven substitution costs. Academic institutions exhibit highest price sensitivity due to grant-funded procurement constraints, while gene therapy developers prioritize batch consistency over per-liter expenditure.
Supply Chain Analysis
Six-to-twelve-month lead times for pharmaceutical-grade amino acid qualification constrain formulation flexibility and elevate safety stock requirements across European and North American manufacturing sites. Raw material sourcing concentrates in China for amino acid precursors, Germany for high-purity salts, and the United States for vitamin derivatives. South American collection networks for fetal bovine serum introduce single-source vulnerability from geopolitical disruption and lot-to-lot variability. Distribution runs through authorized distributor networks for research-grade volumes and direct procurement channels for GMP-certified pharmaceutical contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell culture media market exhibits cyclical recovery characteristics as gene therapy manufacturing capacity buildouts absorb excess supply and EMA Annex 1 implementation drives replacement demand for animal-component-free formulations.
For Market Incumbents: Compound formulation IP advantages by accelerating chemically defined media development for perfusion bioreactor platforms before mid-tier suppliers achieve scale. Deepen backward integration into amino acid purification to offset raw material volatility and defend margin position against emerging Chinese suppliers. Prioritize ISO 13485 certification investment for cell therapy device integration opportunities. For New Entrants and Emerging Players: CDSCO regulatory fast-track alignment offers white-space access to India's expanding biologics manufacturing belt, where multinational pharmaceutical outsourcing creates demand for export-compliant chemically defined media. Target lyophilized specialty formulations for Japanese regenerative medicine programs where incumbent presence remains limited. Pursue direct-to-laboratory e-commerce distribution to bypass established distributor markups in academic and startup biotech segments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated filtration-media system providers with captive quality management infrastructure over pure-play formulation suppliers. Long-term viability hinges on continuous manufacturing feed development capabilities and geographic diversification beyond United States-Germany-China concentration. Monitor NMPA regulatory harmonization progress as inflection indicator for Chinese domestic supplier competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Chemically Defined Formulation Development | EMA Annex 1 compliance mandates accelerate displacement of fetal bovine serum across European biologics facilities. |
| Perfusion Bioreactor Feed Optimization | Continuous manufacturing platforms in Germany and the United States require specialized high-density cell viability formulations. |
| ISO 13485 Quality Management Certification | Medical device-grade standards enable cell therapy device integration and expand addressable market for media suppliers. |
| Direct-to-Laboratory E-Commerce Expansion | Bypassing traditional distributor networks captures margin pools in academic and virtual biotech customer segments. |
| Backward Integration into Amino Acid Purification | Captive supply of pharmaceutical-grade raw materials reduces lot-to-lot variability and defends against input cost volatility. |
Methodological Framework
A standing panel of bioprocess development directors, regulatory affairs specialists at CDMOs, pharmaceutical procurement managers, and academic cell culture facility heads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA chemistry manufacturing and controls guidance documents, EMA Annex 1 revision drafts, NMPA regulatory alignment notices, and customs trade data for amino acid and vitamin derivative imports. Bottom-up segment sizing triangulated against top-down industry expenditure estimates from pharmaceutical manufacturing capital allocation disclosures.
Consistency checks validated volume and value outputs against external benchmarks including bioreactor capacity expansion announcements, gene therapy pipeline progression data, and sterile manufacturing facility investment tracking. The analytical framework modeled formulation type, end-user procurement authority, therapeutic application, and physical format dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro biologics manufacturing output trajectories, incorporating viral vector production scale-up assumptions and stem cell research funding patterns as industry-specific inputs.
Decision-makers should treat outputs as directional under sustained FDA-EMA regulatory convergence and stable amino acid supply chain configurations; material deviation in geopolitical risk exposure or accelerated perfusion technology adoption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Biobank Equipment Market
Biotechnology Equipment
Global Laboratory Centrifuge Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Moving Bed Bioreactor Market