
 US Cell Culture Media Market | 2026-2036
US Cell Culture Media Market Size, Share, and Industry Trends Forecast 2026-2036
US Cell Culture Media Market Insights
Biopharmaceutical manufacturing is restructuring US cell culture media demand as gene therapy and biosimilar production scales up. Thermo Fisher Scientific leverages its Gibco brand portfolio to dominate upstream raw material supply chains. Danaher anchors liquid media volumes through Cytiva's HyClone platforms in mammalian cell workflows. Merck KGaA competes on chemically defined formulations tailored to perfusion bioreactor applications.
Cell culture media comprises nutrient-rich aqueous solutions formulated with amino acids, vitamins, inorganic salts, glucose, and supplemental growth factors that support in vitro cell proliferation, protein expression, and viral vector propagation for biopharmaceutical production. Serum-free media leads product type revenue due to regulatory pressure on lot-to-lot consistency and bovine spongiform encephalopathy risk mitigation. Specialty media for cell and gene therapy applications represents the fastest-expanding segment as AAV and lentiviral vector manufacturing demands custom chemistries. Contract research organizations drive online sales channel growth through consolidated procurement platforms.
FDA Center for Biologics Evaluation and Research enforces chemistry, manufacturing, and controls documentation that pushes manufacturers toward chemically defined, animal-component-free formulations. US Pharmacopeia standards for raw material characterization and traceability shape supplier qualification protocols and create barriers for uncertified entrants. Stakeholders must monitor emerging gene therapy manufacturing scale-up requirements and corresponding media volume forecasts to align capacity investments with modality-specific formulation demand.
Market Dynamics
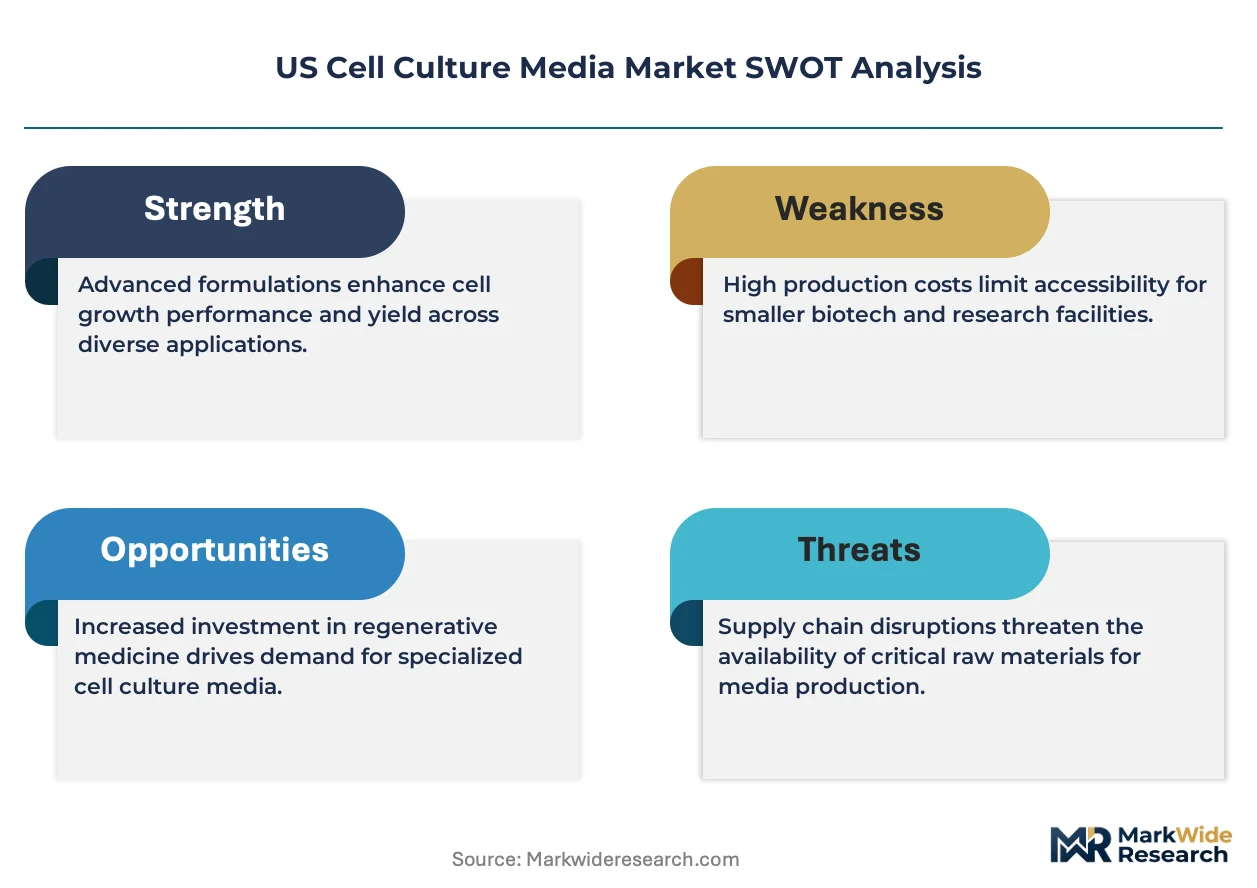
FDA chemistry, manufacturing, and controls documentation for cell and gene therapy products is forcing biopharmaceutical manufacturers toward chemically defined, animal-component-free media formulations. This regulatory pressure restructures supplier qualification protocols and creates tiered competitive barriers based on raw material traceability capabilities.
Growth Catalysts
- IRA biomanufacturing incentives:Domestic production tax credits accelerate capacity buildouts in mammalian cell culture facilities across Massachusetts and North Carolina research corridors.
- Perfusion bioreactor adoption:Continuous manufacturing platforms demand specialized media formulations with extended stability profiles and optimized nutrient delivery chemistries.
- Bovine spongiform encephalopathy risk protocols:Serum-free media eliminates animal-derived component variability while satisfying FDA lot-to-lot consistency requirements for commercial biologics.
Market Restraints
- Raw material supply concentration:Amino acid and vitamin precursor sourcing concentrates among three domestic chemical suppliers, creating vulnerability to pharmaceutical-grade input disruptions.
- Specialty media formulation complexity:Custom chemistries for AAV and lentiviral vector manufacturing require 18-24 month development cycles that delay commercial scale-up timelines.
- Capital intensity of GMP media production:ISO 5 cleanroom suites and automated fill-finish lines demand $40-80 million facility investments that constrain mid-tier manufacturer expansion.
Strategic Opportunities
- Texas and Maryland biotech corridor expansion:Emerging cell therapy clusters in Houston and Gaithersburg present underpenetrated demand for regional media manufacturing and just-in-time distribution.
- Contract development and manufacturing organization consolidation:CDMO procurement platforms favor suppliers offering integrated media-bioreactor analytics and predictive shelf-life modeling.
- AI-driven formulation optimization:Machine learning platforms accelerate media development by predicting nutrient depletion kinetics and metabolite accumulation profiles.
Industry Challenges
- Cell culture scientist talent scarcity:Specialized expertise in chemically defined media development and perfusion process optimization outpaces university training pipeline output.
- Multi-site qualification complexity:Biopharmaceutical sponsors require identical media performance across geographically dispersed manufacturing sites with varying water quality and environmental conditions.
- Legacy serum-dependent process conversion:Established monoclonal antibody lines require extensive revalidation when transitioning to animal-component-free alternatives, extending regulatory submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cell Culture Media Market |
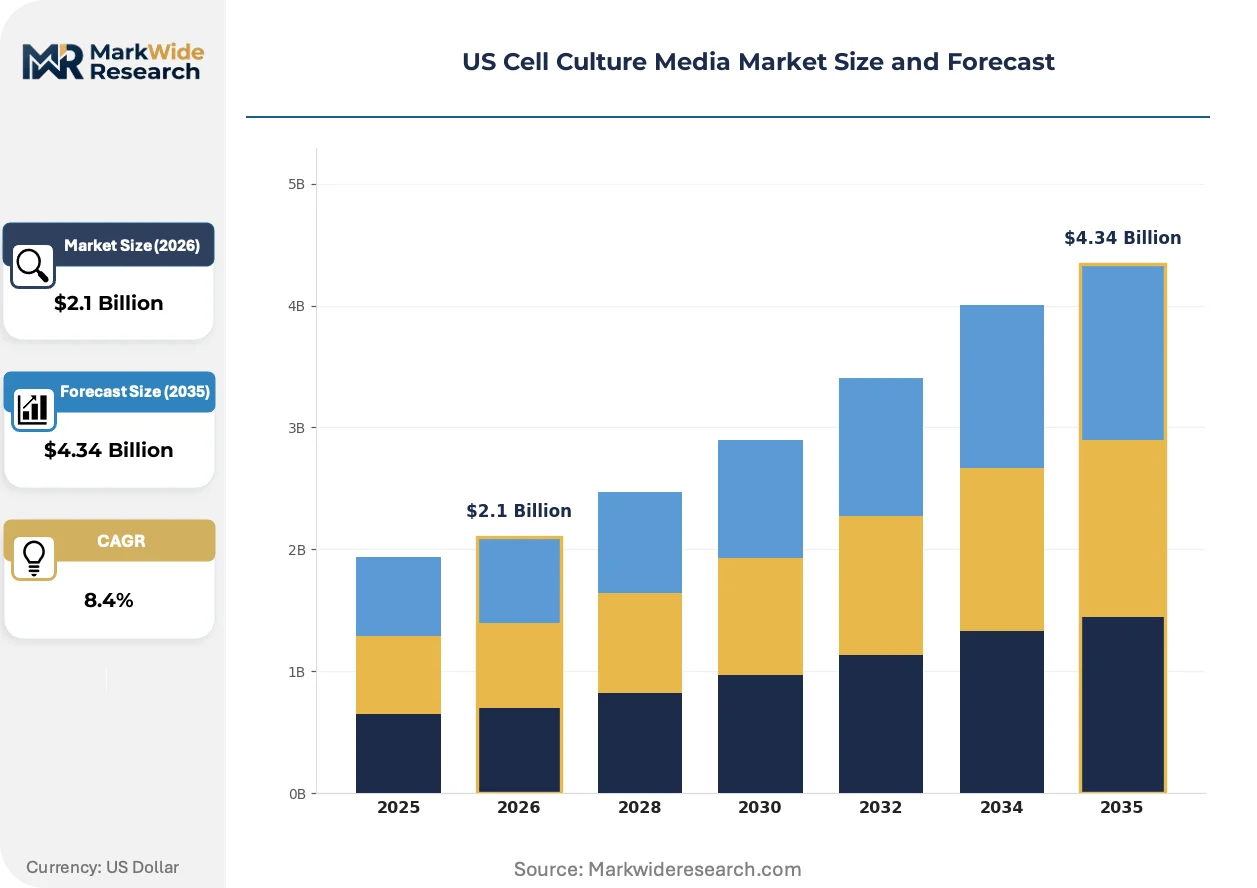
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Media, Powder Media, Serum-free Media, Specialty Media End User: Biopharmaceutical Companies, Academic Institutions, Research Laboratories, Contract Research Organizations Application: Vaccine Production, Drug Development, Regenerative Medicine, Toxicity Testing Distribution Channel: Direct Sales, Online Sales, Third-party Distributors, Retail |
| Companies Covered | Thermo Fisher Scientific, Inc., Merck KGaA, Danaher, Sartorius AG, Corning Incorporated, Lonza, FUJIFILM Irvine Scientific, Cytiva, Becton, Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cell Culture Media Market Trends and Innovations
Single-use bioreactor systems and continuous manufacturing platforms are restructuring media consumption patterns and formulation requirements. These hardware advances demand media chemistries with enhanced stability, reduced foaming, and precise nutrient control mechanisms.
Electrochemical dissolved oxygen and pH sensors integrated with automated media feed systems is electrifying real-time bioprocess control. Gene therapy manufacturers in California and Massachusetts deploy these platforms to maintain optimal cell density during extended perfusion runs. The technology compresses batch failure rates while enabling higher cell-specific productivity targets.
FDA guidance on chemistry, manufacturing, and controls for gene therapy products mandates comprehensive raw material characterization and supplier qualification. This documentation burden elevates entry barriers for uncertified media suppliers while rewarding incumbents with established quality management systems. Cell and gene therapy developers respond by consolidating procurement around suppliers with pre-validated master cell banks and extensive regulatory filing support.
Consolidated procurement through contract research organization platforms displaces direct manufacturer relationships in mid-scale biopharmaceutical operations. CDMOs leverage volume aggregation to negotiate formulation customization and dedicated manufacturing slots. This concentration is most visible in the Boston-Cambridge cluster where outsourced cell therapy manufacturing exceeds in-house capacity.
US Cell Culture Media Market Segmentation
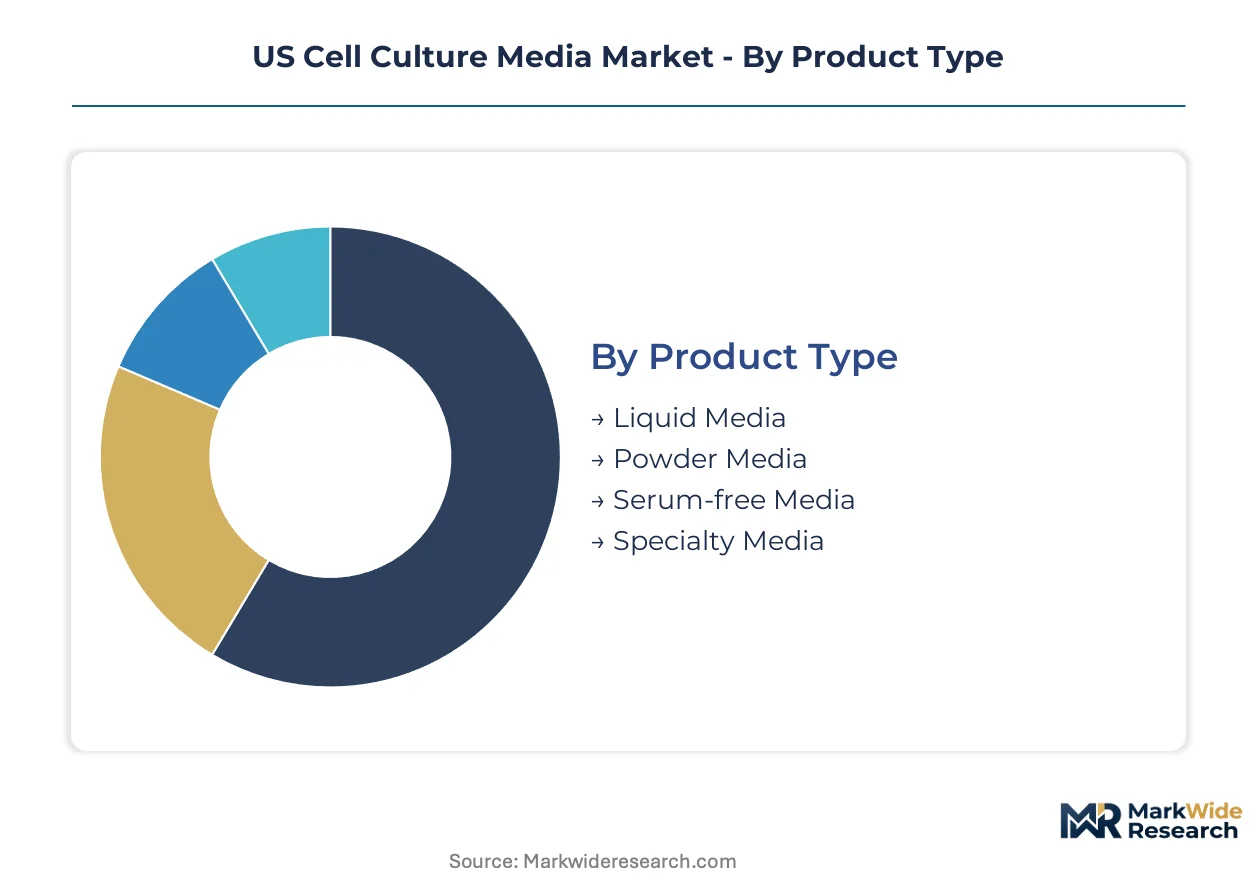
Media formulation requirements diverge sharply across end-use applications, with FDA chemistry, manufacturing, and controls documentation dictating qualification burdens for each segment. Product format selection hinges on bioreactor configuration, storage infrastructure, and supply chain reliability priorities.
Product Type:
FDA lot-to-lot consistency requirements and ISO 5 cleanroom certification burdens vary substantially across formulation formats, with animal-component-free documentation most stringent for serum-free and specialty variants.
- Serum-free Media:Chemically defined formulations eliminate bovine spongiform encephalopathy risk while satisfying FDA documentation for commercial biologics. Massachusetts and California biotech corridors concentrate demand as monoclonal antibody manufacturers convert legacy serum-dependent processes.
- Specialty Media:Custom chemistries engineered for AAV and lentiviral vector propagation support cell and gene therapy manufacturing. Perfusion bioreactor adoption in Texas and Maryland emerging clusters drives formulation customization for extended stability profiles.
- Liquid Media:Ready-to-use aqueous solutions reduce preparation time in high-throughput screening operations.
- Powder Media:Lyophilized formats offer extended shelf stability for facilities with variable cold chain infrastructure.
Leading the category by volume: Serum-free Media. Growing fastest: Specialty Media.
End User:
Procurement scale and qualification rigor separate institutional buyers, with GMP-grade documentation requirements creating tiered supplier access.
- Biopharmaceutical Companies:Internal manufacturing operations demand validated master cell banks and extensive regulatory filing support. North Carolina and Massachusetts facilities anchor volume through integrated media-bioreactor procurement platforms.
- Contract Research Organizations:Consolidated procurement platforms aggregate mid-scale demand and negotiate formulation customization. Boston-Cambridge cluster CDMOs exceed in-house cell therapy manufacturing capacity.
- Academic Institutions:Research-grade formulations predominate with less stringent animal-component documentation.
- Research Laboratories:Smaller batch sizes prioritize catalog availability over custom chemistry development.
Biopharmaceutical Companies command the largest procurement volumes. Contract Research Organizations are expanding most quickly as outsourced manufacturing displaces in-house capacity.
Application:
Regulatory pathway complexity and batch size requirements determine media specification intensity across therapeutic modalities.
- Drug Development:Monoclonal antibody and biosimilar pipelines consume chemically defined media at commercial scale. FDA guidance on cell and gene therapy products accelerates formulation standardization across Massachusetts and California manufacturing sites.
- Regenerative Medicine:Stem cell expansion and ex vivo cell therapy processing demand specialty media with precise growth factor profiles. Houston and Gaithersburg clusters present underpenetrated regional demand.
- Vaccine Production:Viral vector manufacturing platforms require serum-free formulations for downstream purification compatibility.
- Toxicity Testing:High-throughput screening applications prioritize cost efficiency over GMP-grade documentation.
Drug Development retains the dominant volume position. Regenerative Medicine shows the steepest expansion trajectory as cell therapy manufacturing scales up.
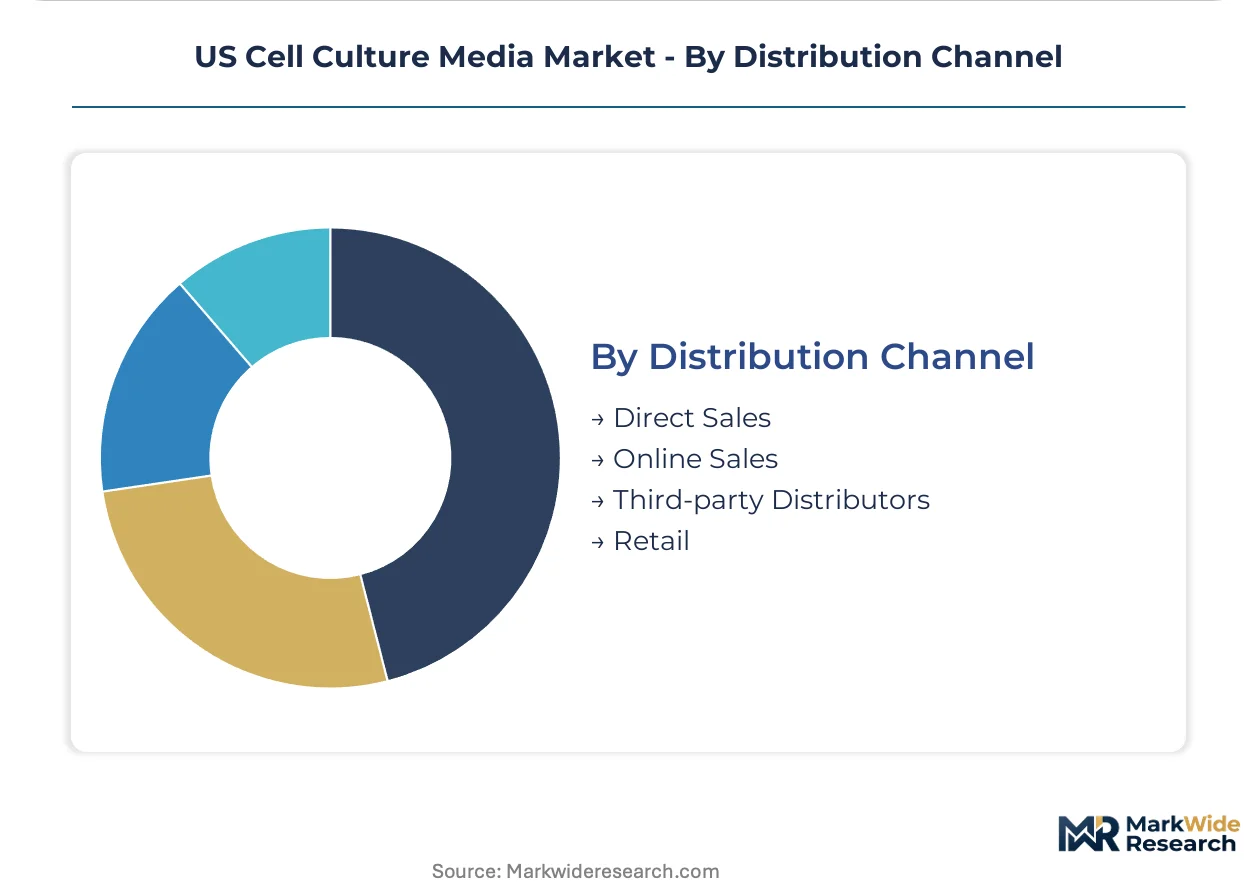
Distribution Channel:
Customer scale and technical service requirements determine channel selection, with direct relationships reserved for the largest GMP-grade consumers.
- Direct Sales:Biopharmaceutical sponsors with dedicated manufacturing slots negotiate formulation customization and predictive shelf-life modeling. Thermo Fisher Scientific and Danaher anchor these relationships through technical field support teams.
- Online Sales:CRO procurement platforms and academic buyers consolidate catalog purchasing through e-commerce interfaces. Consolidated procurement displaces direct manufacturer relationships in mid-scale operations.
- Third-party Distributors:Regional logistics providers serve facilities without cold chain infrastructure for direct supplier relationships.
- Retail:Minimal presence limited to small research-grade consumables through scientific supply cooperatives.
Direct Sales captures the highest value per transaction. Online Sales is gaining share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and IRA tax credits concentrate cell culture media demand in designated biopharmaceutical corridors. Massachusetts and California anchor volume through monoclonal antibody manufacturing clusters. Emerging cell therapy production in Texas and Maryland reshapes regional distribution requirements.
Massachusetts
Greater Boston's contract manufacturing density drives serum-free media procurement at commercial scale. FDA Center for Biologics Evaluation and Research maintains regional field offices that accelerate chemistry, manufacturing, and controls documentation reviews. Cambridge and Worcester biotech parks host perfusion bioreactor installations requiring specialized media formulations with extended stability profiles.
California
San Francisco Bay Area gene therapy developers consume specialty media for AAV and lentiviral vector manufacturing. California Institute for Regenerative Medicine grants accelerate cell therapy manufacturing scale-up across South San Francisco and Emeryville. San Diego's biotech corridor expands chemically defined media demand through biosimilar production facilities.
North Carolina
Research Triangle Park biomanufacturing anchors mammalian cell culture media volumes through integrated procurement platforms. IRA domestic production tax credits accelerate facility buildouts in Durham and Raleigh. CDMO concentration in the region favors suppliers offering predictive shelf-life modeling and dedicated manufacturing slots.
Texas
Houston's emerging cell therapy cluster presents underpenetrated demand for regional media manufacturing and just-in-time distribution. Texas Enterprise Fund incentives attract gene therapy developers to the Texas Medical Center. The Woodlands and Austin biotech corridors expand specialty media requirements for regenerative medicine applications.
Maryland
Gaithersburg and Rockville cell therapy manufacturing drives formulation customization for stem cell expansion protocols. National Institute of Standards and Technology proximity accelerates raw material characterization standardization. Baltimore-Washington corridor CDMOs consolidate procurement through volume aggregation platforms.
US Cell Culture Media Market Competitive Landscape
Top-tier vendors anchor the premium GMP-grade segment, while mid-tier specialists occupy regional and application-specific niches. The US cell culture media market exhibits consolidated structure among chemically defined formulation leaders with fragmented competition in research-grade catalog products. Two strategic archetypes dominate: diversified life science conglomerates leveraging integrated supply chains, and focused media specialists competing on customization velocity. Competitive moves center on capacity expansion in IRA-designated zones and strategic partnerships with CDMO procurement platforms.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher represent the integrated supply chain archetype through their Gibco and Cytiva portfolios. Merck KGaA occupies a position exemplifying the European-headquartered specialist with chemically defined formulation capabilities. These three entities anchor competitive dynamics through technical field support teams and pre-validated master cell bank offerings that satisfy FDA documentation requirements for commercial biologics manufacturing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Merck KGaA |
| Danaher |
| Sartorius AG |
| Corning Incorporated |
| Lonza |
| FUJIFILM Irvine Scientific |
| Cytiva |
| Becton, Dickinson and Company |
| Others |
Pricing and Supply Chain Analysis
GMP-grade certification divergence separates pharmaceutical-grade media from research-grade catalog products, with this bifurcation manifesting in pricing premiums of 40-60% for validated master cell banks and in supply chain configurations that concentrate high-purity amino acid sourcing among three domestic chemical suppliers. FDA chemistry, manufacturing, and controls documentation requirements amplify this split, as biopharmaceutical sponsors demand identical media performance across multi-site manufacturing networks while academic buyers prioritize catalog availability over lot-to-lot consistency guarantees.
Pricing Analysis
Expedited lead-time premiums dominate pricing negotiations, with biopharmaceutical sponsors paying substantial markups for dedicated manufacturing slots and just-in-time delivery guarantees while spot purchasers of research-grade powder media access discounted inventory. Three-tier pricing structure across premium GMP-grade, standard serum-free, and economy research-grade levels reflects certification burden and validation support depth. Cost compression in standard serum-free tiers is intensifying because CDMO procurement platforms aggregate volume and negotiate formulation customization. Contract research organizations exhibit highest price sensitivity due to margin pressure in outsourced manufacturing, while gene therapy developers show lowest sensitivity given regulatory submission timelines that prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Direct-to-biopharmaceutical channels handle commercial-scale demand through technical field support teams and predictive shelf-life modeling, while online platforms and third-party distributors serve mid-scale CRO and academic buyers. Pharmaceutical-grade amino acid and vitamin precursor sourcing concentrates in the United States, Germany, and Switzerland, with custom synthesis capabilities for chemically defined formulations resting on Swiss and German specialty chemical expertise. Raw material dependencies include L-glutamine, D-glucose, and recombinant insulin growth factors. Single-source vulnerability in pharmaceutical-grade precursor supply creates exposure to batch contamination events or facility shutdowns. Distribution runs through temperature-controlled logistics networks with ISO 5 cleanroom handoff protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into raw material synthesis and master cell bank validation services is accelerating as incumbents seek upstream control over pharmaceutical-grade amino acid supply and downstream capture of regulatory filing support revenue.
For Market Incumbents: Extend technical field support coverage into emerging Texas and Maryland cell therapy clusters before regional CDMO procurement platforms consolidate supplier relationships. Lock in multi-year offtake agreements with amino acid precursor suppliers to defend against specialty chemical entrants from Europe. Perfusion bioreactor adoption represents the critical technology shift requiring co-developed media formulations. For New Entrants and Emerging Players: Mid-scale regenerative medicine developers in Houston and Austin present an underserved buyer archetype seeking regional media manufacturing with reduced cold chain complexity. Establish just-in-time distribution partnerships with Texas Medical Center logistics providers. Pursue AI-driven formulation optimization as the primary go-to-market angle to compress 18-24 month development cycles and attract venture-backed gene therapy sponsors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified life science conglomerates seeking chemically defined formulation capabilities and pre-validated master cell banks. Long-term viability hinges on regulatory filing support depth and CDMO procurement platform integration. Monitor FDA guidance publication velocity on cell and gene therapy chemistry, manufacturing, and controls as the critical inflection indicator for capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Synthesis | Captures pharmaceutical-grade precursor margins and insulates against Swiss-German supplier concentration. |
| AI-Driven Formulation Optimization Platform | Compresses media development timelines for AAV and lentiviral vector manufacturing sponsors. |
| Regional Manufacturing Footprint in Texas | Positions suppliers to serve Houston cell therapy cluster with reduced cold chain logistics costs. |
| CDMO Procurement Platform Integration | Locks in volume aggregation through Boston-Cambridge outsourced manufacturing consolidation. |
| Perfusion Bioreactor Co-Development Program | Aligns extended stability media formulations with continuous manufacturing hardware advances. |
Research Methodology
Multi-period observation of FDA chemistry, manufacturing, and controls guidance publication patterns, perfusion bioreactor installation announcements, and CDMO procurement platform contract awards anchored the trend analysis, supplemented by interviews with cell culture scientists, regulatory affairs leads at gene therapy developers, GMP facility managers, and procurement directors at contract research organizations. Secondary validation drew from FDA Center for Biologics Evaluation and Research guidance documents, US Pharmacopeia raw material standards, IRA tax credit allocation announcements, and SEC filings of publicly traded life science conglomerates. Bottom-up media volume estimates by application and end-user segment triangulated against top-down market size assessments.
Segment-weighting across product type, end user, application, and distribution channel dimensions shaped the analytical framework, with modality-specific growth rates derived from gene therapy pipeline advancement and biosimilar approval velocity. Treatment line positioning, bioreactor configuration, and regional regulatory cluster intensity informed the segmentation model. CAGRs were computed from baseline volume estimates projected through the analysis window using biopharmaceutical manufacturing capacity expansion announcements and media consumption intensity ratios by therapeutic modality.
Revisions become necessary when FDA guidance timelines accelerate, raw material supply disruptions materialize, or gene therapy manufacturing scale-up requirements exceed current media volume forecasts. Practitioners should monitor IRA biomanufacturing tax credit allocation patterns and emerging cell therapy cluster formation in Texas and Maryland for early signals of regional demand redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
Biotechnology Instrumentation Market
Biotechnology Equipment
Global Biological Safety Cabinets Market
Biotechnology Equipment
Biobank Equipment Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Global Biotechnology Reagents Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Global Cryostat Microbiome Equipment Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market