
 Global Cell Counting Market | 2026-2036
Global Cell Counting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Counting Market Foresight
A shift from manual hemocytometer procurement toward multi-vendor automated platform contracts is realigning supply relationships across biopharmaceutical quality control. Danaher Corporation leverages its life sciences instrumentation breadth to sustain integrated workflow offerings from sample prep through data management. Thermo Fisher Scientific anchors its position through extensive direct service networks in North American research clusters. Sysmex Corporation competes on hematology analytical performance standards that translate into cell counting reliability claims.
Cell counting encompasses quantitative enumeration of viable and non-viable cells in suspension using electrical impedance, fluorescence detection, or image analysis methods with precision thresholds typically reaching ±5% coefficient of variation for automated systems. The technique underpins bioprocess monitoring, clinical diagnostics, and regulatory batch release testing where absolute cell density determines therapeutic dosing or culture passage timing. Automated cell counters occupy the largest revenue pool given their throughput advantages in high-volume biopharmaceutical manufacturing, while image-based cell counters represent the fastest-expanding segment as artificial intelligence-enhanced morphology classification penetrates academic and contract research settings. Flow cytometers retain premium positioning in multiparametric applications where simultaneous surface marker quantification justifies capital intensity.
FDA enforcement of current Good Manufacturing Practice for cell and gene therapy products elevates instrument validation requirements, directly expanding demand for 21 CFR Part 11-compliant software modules. EU MDR and EMA guidelines on advanced therapy medicinal products impose traceability standards that favor counters with embedded electronic records and audit trail functionality. ISO 13485 certification has become a baseline qualification criterion for vendor selection in clinical laboratory procurement. Stakeholders must weigh total cost of ownership against regulatory documentation depth when evaluating platform migrations from manual to automated counting infrastructure.
Market Dynamics
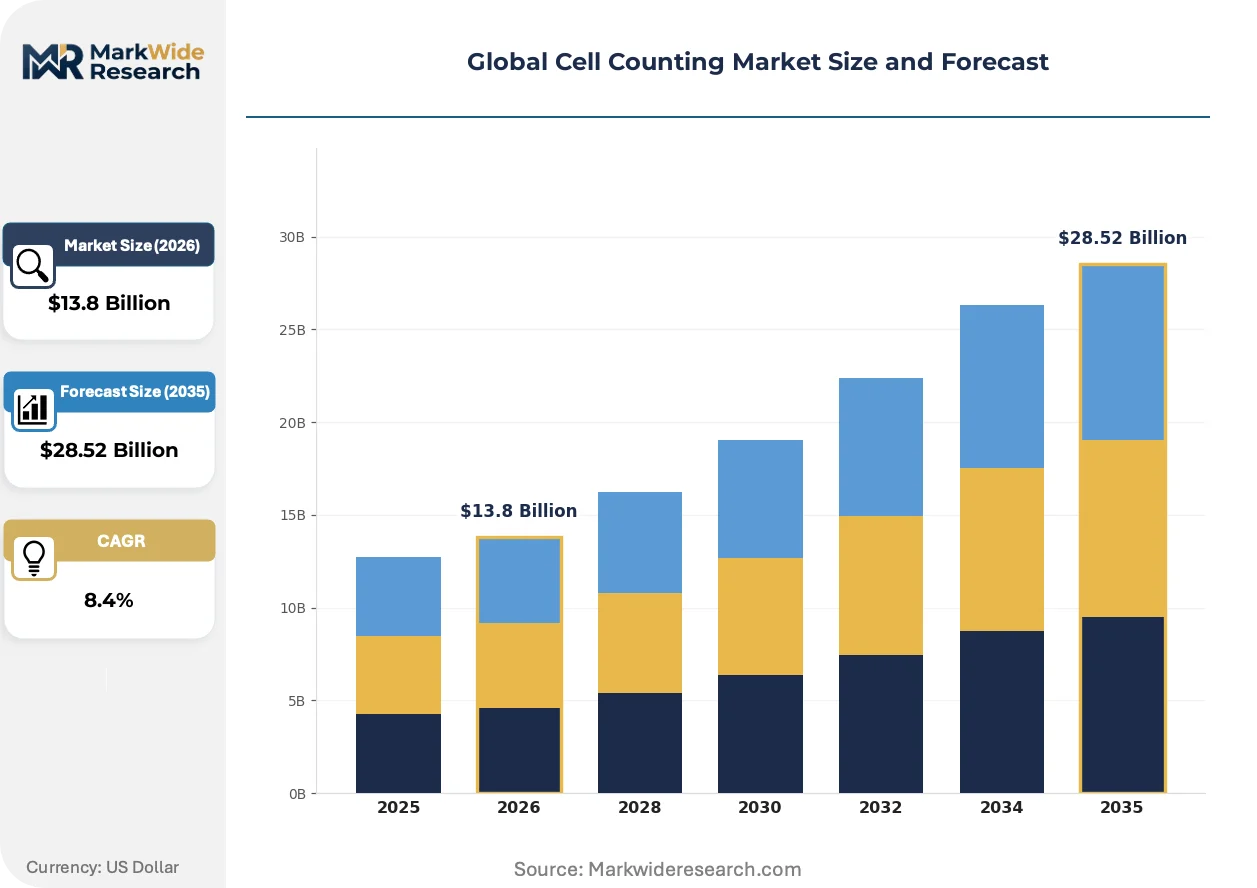
Automated cell counting platforms are displacing manual hemocytometer workflows as biopharmaceutical manufacturers scale cell therapy production and FDA 21 CFR Part 11 enforcement tightens documentation requirements for electronic batch records.
Growth Catalysts
- Cell Therapy Manufacturing Scale-Up:Commercial CAR-T and stem cell therapy production lines require high-throughput viability assessment, pulling automated counters into GMP suites.
- FDA 21 CFR Part 11 Compliance Mandates:Electronic records and audit trail functionality have become non-negotiable for IND-enabling studies and BLA submissions in the United States.
- Artificial Intelligence-Enhanced Morphology Classification:Machine learning algorithms now classify cell types with pathologist-grade accuracy, expanding image-based counter deployment in academic core facilities.
Market Restraints
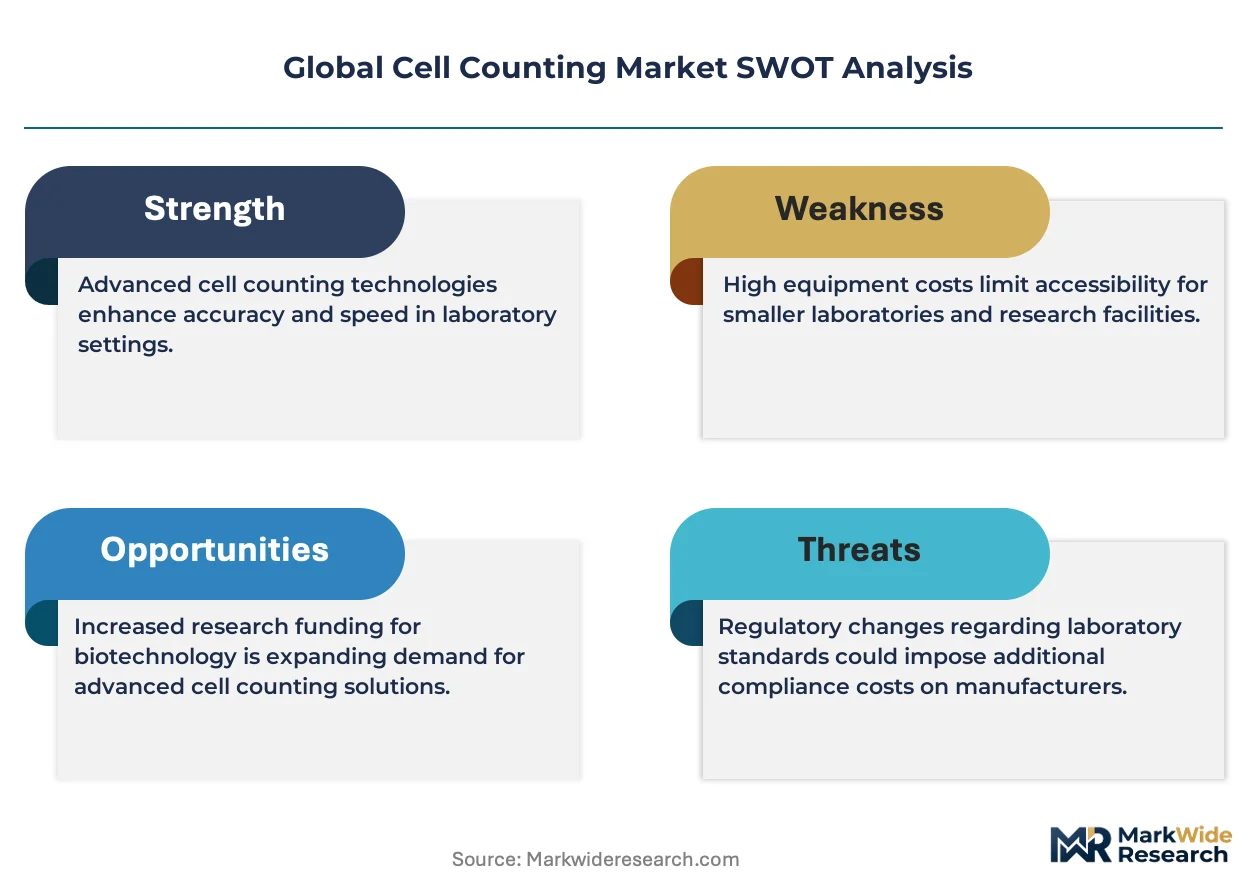
- Capital Equipment Intensity:Fully validated automated platforms with GMP software modules command price premiums that strain early-stage biotech capital budgets.
- Consumables Lock-In:Proprietary reagent cartridges and counting slides from dominant vendors create switching costs and limit multi-sourcing flexibility.
- Fluorescent Dye Supply Concentration:Key viability stains depend on specialized chemical intermediates with limited qualified suppliers in Germany and Switzerland.
Strategic Opportunities
- India Biopharma Contract Manufacturing:CDMO investments in Hyderabad and Bangalore lack validated automated counting infrastructure, creating first-mover installation windows.
- EU MDR Traceability Requirements:Advanced therapy medicinal product guidelines favor counters with embedded electronic records, rewarding vendors with pre-validated software stacks.
- Cloud-Connected Instrument Convergence:Edge computing and laboratory information management system integration enable remote monitoring and predictive maintenance revenue streams.
Industry Challenges
- GMP Software Validation Expertise Gap:Biopharmaceutical quality teams struggle to recruit personnel fluent in both cell biology and 21 CFR Part 11 computer system validation protocols.
- Legacy Hemocytometer Workflow Inertia:Academic labs resist capital expenditure despite throughput limitations, preferring familiar manual methods for grant-funded research.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Counting Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Cell Counters, Manual Hemocytometers, Flow Cytometers, Image-Based Cell Counters, Impedance Counters Technology: Fluorescence, Electrical Impedance, Image Analysis, Coulter Principle, Laser Scanning Application: Pharmaceutical Research, Biotechnology, Academic Research, Food & Beverage Testing, Environmental Monitoring End User: Clinical Laboratories, Research Institutes, Contract Research Organizations, Quality Control Labs, Biopharmaceutical Firms |
| Companies Covered | Agilent Technologies, Bio-Rad Laboratories, Danaher Corporation, PerkinElmer, Sysmex Corporation, Thermo Fisher Scientific, Merck KGaA, GE Healthcare, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Counting Market Shifts & Advancements
Deep learning architectures and regulatory digitization are compressing analytical timelines while reshaping how biopharmaceutical firms qualify and deploy cell counting infrastructure across distributed manufacturing networks.
Image-based cytometry is converging with convolutional neural networks trained on morphological feature sets, enabling label-free viability assessment. Contract development and manufacturing organizations in Massachusetts and North Carolina are piloting these systems for real-time bioprocess monitoring. The technology is converging with legacy impedance-based platforms, forcing vendors to defend installed bases through software subscription bundling.
EMA guidelines on computerized systems for advanced therapy medicinal products now require audit trail review procedures that exceed prior GMP annex expectations. European cell therapy developers must demonstrate data integrity controls across multi-site manufacturing networks. German and Swiss regulators are inspecting software validation documentation with heightened scrutiny, compressing vendor qualification timelines.
Biopharmaceutical procurement teams now unbundle instrument capital purchase from multi-year service and reagent contracts, shifting vendor relationships toward total cost of ownership negotiations. Academic core facilities in California and Massachusetts increasingly favor platform-agnostic reagent sourcing. This behavioral shift is most visible among National Institutes of Health-funded institutions seeking to maximize grant dollar efficiency through competitive consumables bidding.
Global Cell Counting Market Segmentation
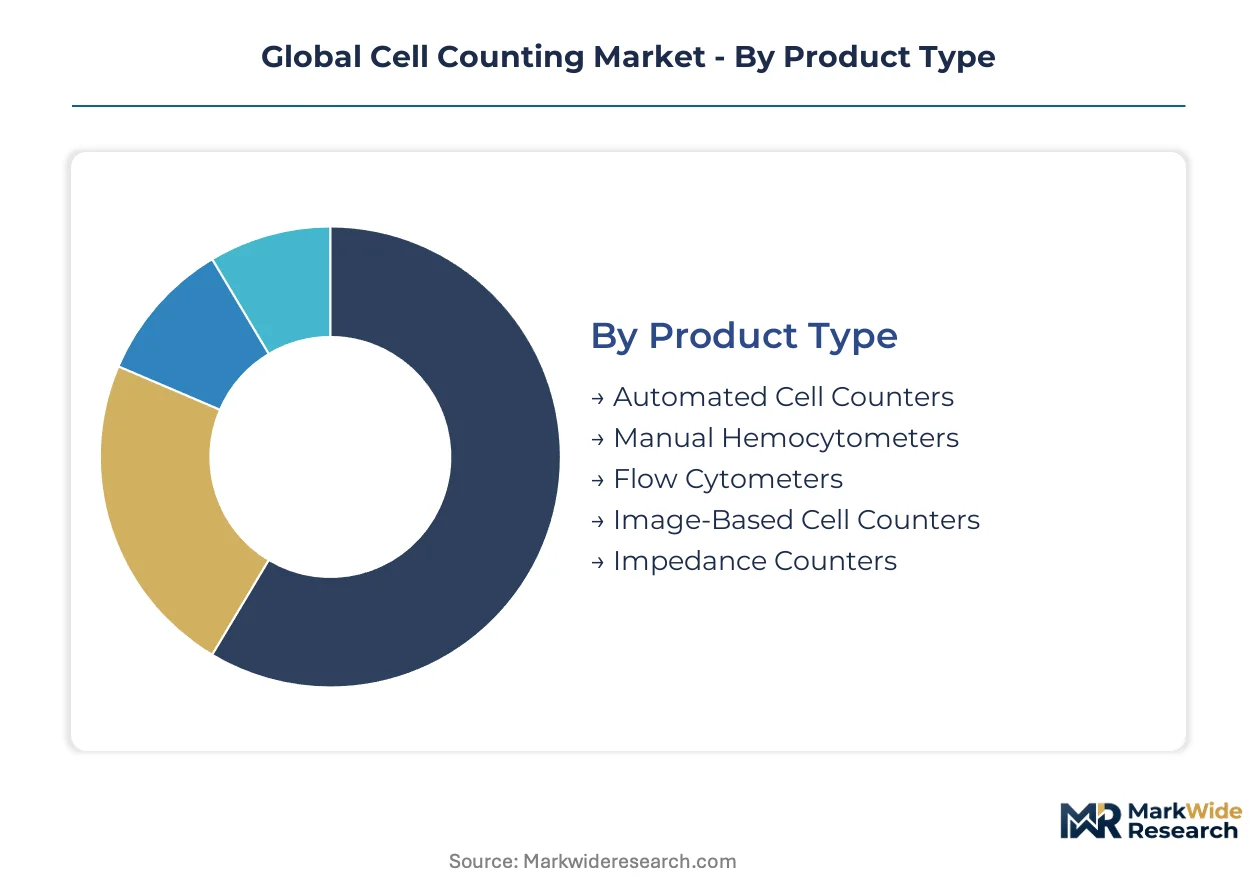
Cell counting market segmentation reflects divergent buyer priorities across capital intensity, throughput requirements, and regulatory validation depth. Procurement patterns in biopharmaceutical manufacturing differ fundamentally from academic core facility purchasing, creating distinct competitive dynamics within each category.
Product Type:
Capital expenditure thresholds and GMP validation requirements drive platform selection across end-use environments.
- Automated Cell Counters:Electrical impedance and fluorescence-based systems deliver throughput exceeding 10,000 samples daily with CV precision below 5%. Biopharmaceutical manufacturers in the United States and Germany deploy these platforms in GMP suites for CAR-T batch release testing where FDA 21 CFR Part 11 compliance is mandatory.
- Image-Based Cell Counters:Convolutional neural networks classify cellular morphology without fluorescent labels, reducing reagent costs and sample preparation time. Academic core facilities in California and Massachusetts adopt these systems for multiparametric stem cell characterization where grant-funded budgets constrain consumables spending.
- Flow Cytometers:Multiparametric instruments command premium positioning for surface marker quantification in immunotherapy development.
- Manual Hemocytometers:Glass chamber devices persist in resource-constrained settings despite throughput limitations and operator-dependent variability.
- Impedance Counters:Coulter principle systems dominate hematology reference laboratories requiring absolute cell volume measurements.
Automated cell counters lead on scale; image-based counters lead on momentum.
Technology:
Detection modality selection hinges on sample complexity, required parameters, and total cost of ownership over instrument lifecycle.
- Fluorescence:Viability dyes and antibody-conjugated fluorophores enable simultaneous enumeration of live, dead, and apoptotic populations. Biopharmaceutical quality control labs in Switzerland and Germany rely on fluorescence detection for advanced therapy medicinal product release per EMA guidelines.
- Electrical Impedance:Coulter principle measurements provide absolute cell volume and concentration without reagent dependency. Clinical hematology laboratories in Japan and South Korea standardize on impedance-based platforms for routine complete blood count workflows.
- Image Analysis:Brightfield and phase-contrast microscopy with algorithmic classification supports label-free assessment.
- Coulter Principle:Aperture-based impedance detection remains the gold standard for cell volume distribution analysis.
- Laser Scanning:Confocal and line-scanning architectures enable high-content screening applications in drug discovery.
Fluorescence detection dominates current installed base; image analysis climbs the fastest.
Application:
Regulatory stringency and sample throughput requirements fragment demand across use cases.
- Pharmaceutical Research:IND-enabling studies and bioprocess development require validated counting protocols with full audit trail documentation. Contract research organizations in Massachusetts and North Carolina invest in 21 CFR Part 11-compliant platforms to support sponsor BLA submissions.
- Biotechnology:Cell therapy manufacturing demands real-time viability monitoring for culture passage decisions and final product characterization. CDMO facilities in Hyderabad and Bangalore scale automated counting infrastructure to meet export market qualification standards.
- Academic Research:Grant-funded laboratories prioritize capital efficiency over throughput, sustaining manual method persistence.
- Food & Beverage Testing:Microbial enumeration for spoilage organism detection employs impedance and image-based systems.
- Environmental Monitoring:Algal and bacterial population assessment in water quality applications favors portable fluorescence platforms.
Pharmaceutical research commands highest price realization; biotechnology gains share fastest.
End User:
Procurement authority and validation expertise availability shape vendor relationship dynamics.
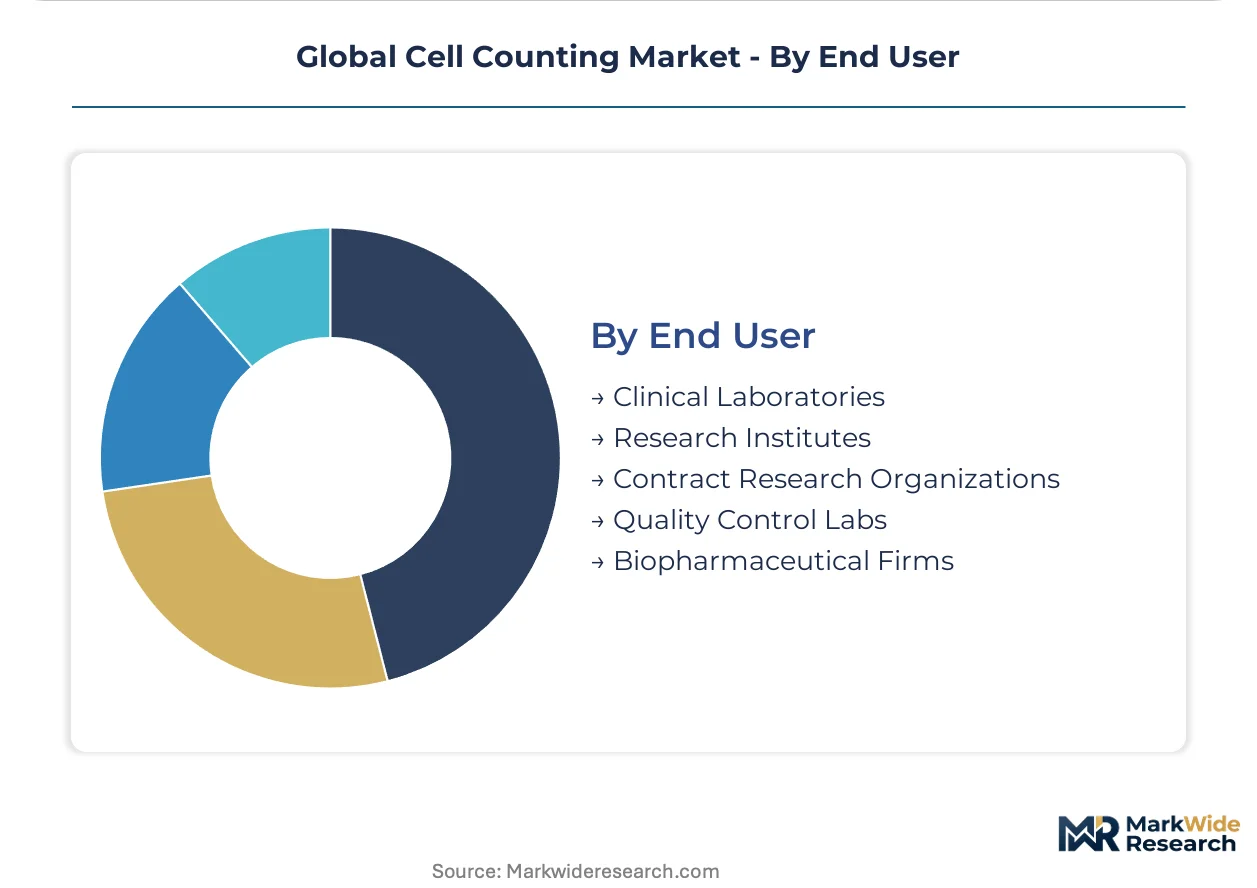
- Biopharmaceutical Firms:Integrated quality control and manufacturing organizations negotiate multi-year service contracts bundled with instrument capital purchase. FDA-regulated facilities in the United States require vendor-provided IQ/OQ/PQ documentation packages for automated platform qualification.
- Contract Research Organizations:Sponsor-facing service providers maintain instrument redundancy to ensure study continuity and regulatory inspection readiness. European CROs in Germany and the Netherlands invest in EMA-aligned computerized system validation to support advanced therapy medicinal product development.
- Clinical Laboratories:Hospital and reference labs prioritize throughput and LIS integration for high-volume hematology testing.
- Research Institutes:National laboratory and university core facilities balance capital constraints against multi-investigator access requirements.
- Quality Control Labs:In-process and release testing operations demand GMP-grade documentation and change control protocols.
Biopharmaceutical firms lead on contract value; contract research organizations lead on growth velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor generates concentrated demand for FDA-validated automated counting systems as cell therapy developers advance IND programs toward BLA submission. Precision medicine infrastructure investments in Germany, China, and Switzerland create parallel procurement pipelines for GMP-grade instrumentation.
United States
CAR-T manufacturing scale-up in Massachusetts and North Carolina drives automated counter deployment into GMP suites. FDA 21 CFR Part 11 enforcement tightens documentation requirements for electronic batch records in cell therapy production. The San Francisco Bay Area anchors West Coast demand through stem cell research institutes and contract development organizations.
Germany
Advanced therapy medicinal product developers in Heidelberg and Cologne require EMA-aligned computerized system validation for multi-site manufacturing networks. EU MDR traceability standards favor counters with embedded electronic records and audit trail functionality. Bavarian hematology reference laboratories standardize on impedance-based platforms for clinical diagnostics.
China
Domestic cell therapy developers in Shanghai and Suzhou expand automated counting procurement as NMPA strengthens GMP inspection protocols for regenerative medicine products. Government biotechnology investment programs accelerate infrastructure buildout in the Yangtze River Delta. Local CDMOs upgrade quality control capabilities to meet export market qualification standards.
Switzerland
Swissmedic oversight of advanced therapy manufacturing elevates instrument validation requirements for Basel-based pharmaceutical quality control operations. Precision medicine clusters in Zurich and Geneva drive demand for multiparametric counting platforms with ISO 13485 certification. Swiss chemical intermediates suppliers concentrate production of specialized fluorescent viability stains.
India
Contract manufacturing investments in Hyderabad and Bangalore lack validated automated counting infrastructure, creating installation windows for GMP-compliant platforms. CDSCO alignment with international GMP standards pressures domestic biopharmaceutical facilities toward electronic record systems. Karnataka's biotech parks attract multinational quality control technology vendors seeking first-mover positioning.
Global Cell Counting Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enhanced image analysis and cloud-connected service models. The vendor base consolidates around three to five integrated life sciences conglomerates with direct service networks in major research clusters. Strategic archetypes include full-workflow integrators, hematology analytical specialists, and reagent-dependent platform vendors. Dominant competitive moves encompass multi-year service contract bundling and predictive maintenance software subscriptions.
Within the integrated instrumentation tier, Danaher Corporation and Thermo Fisher Scientific occupy positions defined by life sciences breadth and North American service density. Sysmex Corporation exemplifies the hematology analytical specialist archetype, translating reliability standards from clinical diagnostics into biopharmaceutical applications. These three entities anchor competitive dynamics through differentiated channel strategies and validation documentation depth.
| Leading Market Players |
|---|
| Agilent Technologies |
| Bio-Rad Laboratories |
| Danaher Corporation |
| PerkinElmer |
| Sysmex Corporation |
| Thermo Fisher Scientific |
| Merck KGaA |
| GE Healthcare |
| Becton Dickinson and Company |
| Others |
Supply & Pricing Matrix
Fluorescent dye intermediates manufactured in Germany and Switzerland cascade through proprietary reagent cartridges into tiered instrument pricing, with biopharmaceutical quality control labs absorbing premium GMP-validation costs that academic core facilities reject.
Pricing Analysis
Input-cost pass-through from specialized chemical intermediates intensifies pricing pressure on fluorescence-based automated counters. A three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 11-compliant GMP platforms from research-grade systems and manual hemocytometers. Price differentiation hinges on software validation documentation depth and after-sales service bundling. Early-stage biotech buyers exhibit acute price sensitivity, while integrated biopharmaceutical manufacturers prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing requirements for viability stains and counting slides compel biopharmaceutical procurement teams to qualify secondary suppliers in Germany, Switzerland, and the United States. Raw material dependencies center on acridine orange derivatives, propidium iodide formulations, and precision-molded polymer slides. Single-source vulnerability concentrates in Swiss fluorescent dye chemistry where regulatory qualification timelines deter supplier switching. Distribution runs through direct vendor service networks anchored in Boston-Cambridge, Basel-Zurich, and Shanghai-Suzhou biotech clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory compliance costs into durable competitive moats, with FDA 21 CFR Part 11 enforcement tightening documentation requirements that automated platform vendors alone can satisfy.
For Market Incumbents: Cement installed base retention through predictive maintenance software subscriptions and multi-year reagent lock-in contracts. Defend against AI-enhanced image analysis entrants by accelerating convolutional neural network integration into legacy impedance platforms. Prioritize GMP software validation expertise acquisition in Heidelberg and Research Triangle Park service hubs. For New Entrants and Emerging Players: EU MDR traceability requirements in Germany and Switzerland open a window for cloud-connected instrument platforms with pre-validated electronic records. Target academic core facilities in California and Massachusetts where grant-funded budgets favor platform-agnostic reagent sourcing. Pursue white-label partnerships with Indian CDMOs in Hyderabad lacking validated automated counting infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where GMP software validation expertise scarcity constrains vendor qualification timelines. Position for five-to-ten year horizon value capture through acquisition of ISO 13485-certified image analysis specialists with FDA submission experience. Monitor NMPA inspection protocol tightening in China as inflection indicator for domestic platform upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Software Validation Partnership | FDA 21 CFR Part 11 pre-validation accelerates biopharmaceutical customer qualification timelines. |
| Cloud-Connected Instrument Platform Launch | Edge computing integration enables remote monitoring revenue streams for distributed manufacturing networks. |
| AI-Enhanced Morphology Classification Development | Convolutional neural networks reduce reagent costs for grant-funded academic core facilities. |
| Indian CDMO Service Network Expansion | Hyderabad and Bangalore installation windows address validated infrastructure gaps in contract manufacturing. |
| Fluorescent Dye Backward Integration | In-house production of acridine orange intermediates mitigates Swiss supplier concentration risk. |
Research Methodology
Multiple input streams — executive interviews with biopharmaceutical quality control directors, regulatory affairs leads, and academic core facility managers; secondary validation through FDA 483 observation databases, EMA advanced therapy medicinal product guidelines, and ISO 13485 certification registries; plus customs trade data on fluorescent dye imports — were reconciled through bottom-up and top-down triangulation.
Historical shipment data was cross-referenced against panel input from instrument procurement officers to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type, detection technology, application environment, and end-user procurement authority. CAGRs were derived from instrument installation base growth trajectories and reagent consumables attach rates. Industry-specific forecast inputs encompass CAR-T manufacturing capacity expansion in Massachusetts and North Carolina, plus NMPA GMP inspection intensity in Shanghai-Suzhou.
Revisions become necessary when regulatory enforcement intensity shifts, fluorescent dye supply disruptions materialize, or AI-enhanced image analysis accuracy crosses pathologist-grade thresholds. Deviation in FDA 21 CFR Part 11 audit frequency or EMA computerized system validation scrutiny would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Cell Cryopreservation Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Latin America Digital Biology Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Europe Serine Proteases Market