
 Real-Time Bioprocess Raman Analyzer Market | 2026-2036
Real-Time Bioprocess Raman Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Real-Time Bioprocess Raman Analyzer Market Analytics
Buyer concentration among contract manufacturing organizations is decoupling from traditional biopharmaceutical company procurement patterns as CDMOs build dedicated process analytical technology capabilities. Bruker Corporation leverages its spectroscopy heritage to anchor high-end integrated system deployments. Sartorius competes through bioreactor-analyzer bundling that tightens workflow control. Kaiser Optical Systems specializes in fiber-optic probe architectures that dominate upstream bioprocess monitoring.
Real-time bioprocess Raman analyzers employ non-destructive laser excitation in the near-infrared range to quantify metabolite, nutrient, and product concentrations within sterile bioreactor environments, achieving measurement cycles under thirty seconds for glucose, lactate, and antibody titer tracking. Integrated Systems command the widest installed base because they embed directly into distributed control architectures, while Portable Analyzers represent the fastest-expanding category as multi-site biopharma operators seek flexible validation transfer between production suites. Laboratory Instruments retain stable replacement demand from research institutions running offline method development.
FDA process analytical technology guidance and EMA quality-by-design frameworks mandate real-time release testing pathways that elevate Raman spectroscopy from optional to standard practice in commercial biologics facilities. ISO 13485 and GMP Annex 15 requirements in Europe and the United States enforce rigorous software validation and optical calibration protocols that filter out uncertified entrants. Stakeholders must monitor how evolving biosimilar approval pathways in multiple jurisdictions reshape the analyzer specification mix between standalone and fully integrated platforms.
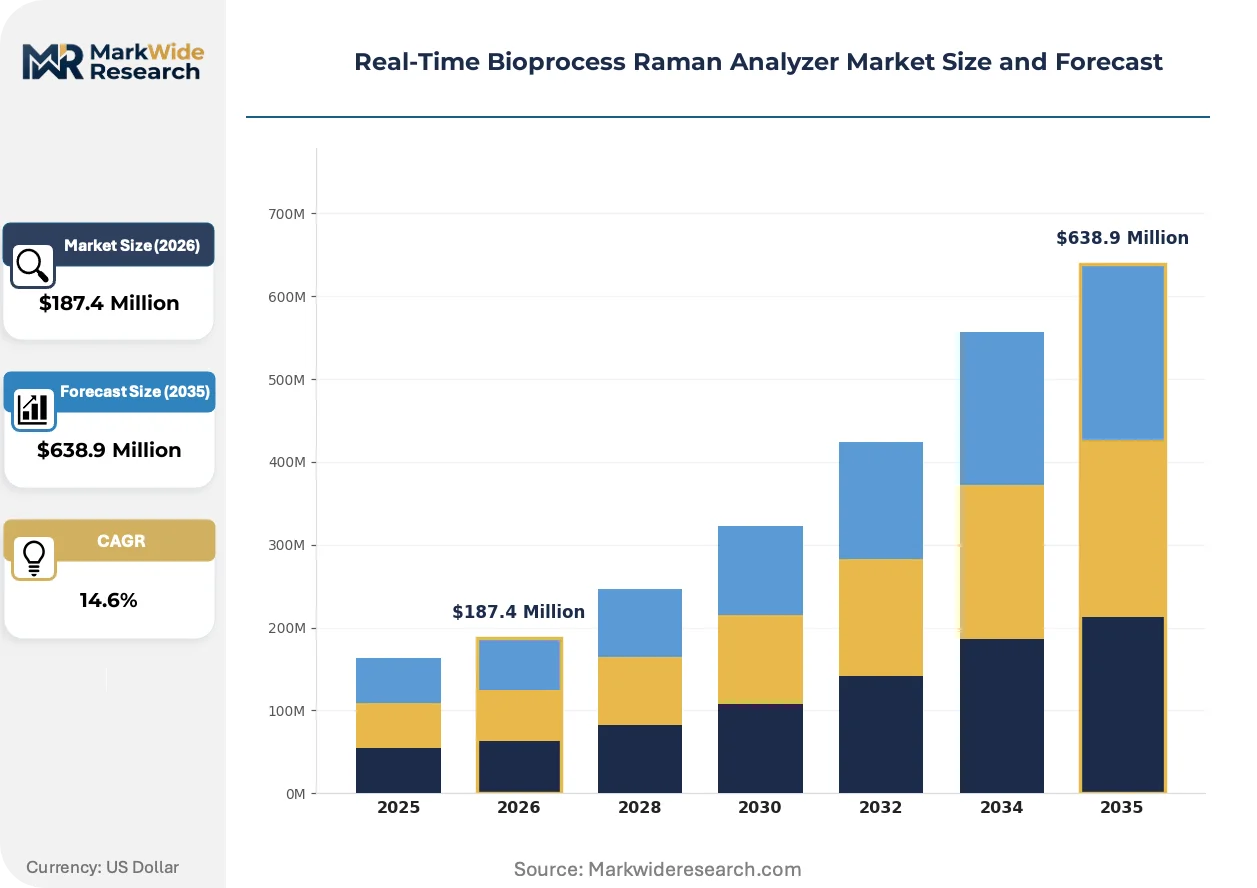
Market Dynamics
Contract manufacturing organizations are building captive process analytical technology capabilities that decouple their procurement from traditional biopharmaceutical patterns, creating a dual-track demand structure where CDMOs specify integrated Raman-DCS architectures while originators prioritize standalone validation flexibility.
Growth Catalysts
- FDA Process Analytical Technology Guidance:The framework mandates real-time release testing pathways that elevate Raman spectroscopy from optional to standard practice in commercial biologics facilities, forcing facility upgrades across the manufacturing base.
- Single-use bioreactor proliferation:Stainless steel displacement in mammalian cell culture creates probe-port standardization that favors fiber-optic Raman architectures designed for disposable vessel geometries.
- South Korean biologics clusters:Samsung Biologics and Celltrion expansion in Songdo and Incheon concentrates demand for in-line metabolite monitoring in high-titer antibody production suites.
Market Restraints
- Optical component supply concentration:German and Japanese laser source manufacturers control 785nm diode supply, creating single-source vulnerability for system builders outside established supply relationships.
- GMP Annex 15 software validation burden:European facilities face 18-24 month qualification timelines for algorithm updates, freezing analytical method evolution and extending replacement cycles.
- At-line HPLC residual preference:Quality control departments in legacy facilities resist Raman adoption for final release testing, limiting deployment to upstream process monitoring only.
Strategic Opportunities
- Biosimilar facility greenfield construction:India and Southeast Asia capacity builds specify integrated PAT from commissioning, bypassing the retrofit friction that slows adoption in mature markets.
- Continuous bioprocessing convergence:Perfusion culture platforms require sub-minute measurement cycles that only Raman delivers, creating technology lock-in for next-generation facility designs.
- CDMO service bundling:Analytical capability rental models allow mid-tier biopharma to access validated Raman methods without capital ownership, expanding addressable demand.
Industry Challenges
- Chemometric model transfer complexity:Facility-to-facility spectral calibration variance consumes 6-9 months of validation resource, delaying multi-site deployment programs.
- Hybrid skill scarcity:The intersection of spectroscopy physics, bioprocess engineering, and regulatory documentation expertise concentrates in Boston and Basel hiring pools, constraining scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real-Time Bioprocess Raman Analyzer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Portable Analyzers, Laboratory Instruments Deployment Model: On-Premise, Cloud-Based, Hybrid, Remote Monitoring Application Area: Pharmaceutical Manufacturing, Biologics Production, Chemical Analysis, Quality Control End User: Biopharmaceutical Companies, Research Institutions, Contract Manufacturing Organizations, Quality Assurance Labs |
| Companies Covered | Bruker Corporation, Agilent Technologies, Thermo Fisher Scientific, Kaiser Optical Systems, Horiba Group, Sartorius, Renishaw, METTLER TOLEDO, MarqMetrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real-Time Bioprocess Raman Analyzer Market Evolving Landscape
Real-time bioprocess Raman analyzers are absorbing software architectures from adjacent industrial spectroscopy markets, compressing the traditional boundary between laboratory method development and manufacturing deployment. Three interconnected developments are restructuring competitive positioning.
Deep learning chemometrics is absorbing pattern-recognition workloads previously handled by partial least squares algorithms, enabling glucose and lactate quantification in complex chemically-defined media without offline calibration sampling. CDMOs with high batch-frequency operations are adopting these neural architectures fastest, compressing model development from months to weeks and eroding the service revenue streams of incumbent analytical method consultants.
EMA's evolving quality-by-design framework is tightening documentation requirements for multivariate analytical methods, forcing Raman system vendors to embed automated model lifecycle management tools that track spectral drift and trigger revalidation protocols. Commercial biologics facilities in Germany and Ireland face the steepest compliance ramps, driving preference toward platforms with pre-validated algorithm change-control packages.
Biopharma procurement functions are unbundling analyzer hardware from chemometric service contracts, treating spectral modeling as a separable software subscription rather than captive installation deliverable. This pattern concentrates in multi-site operators headquartered in the United States, where centralized analytical method development teams demand portability across geographically distributed manufacturing networks.
Real-Time Bioprocess Raman Analyzer Market Segmentation
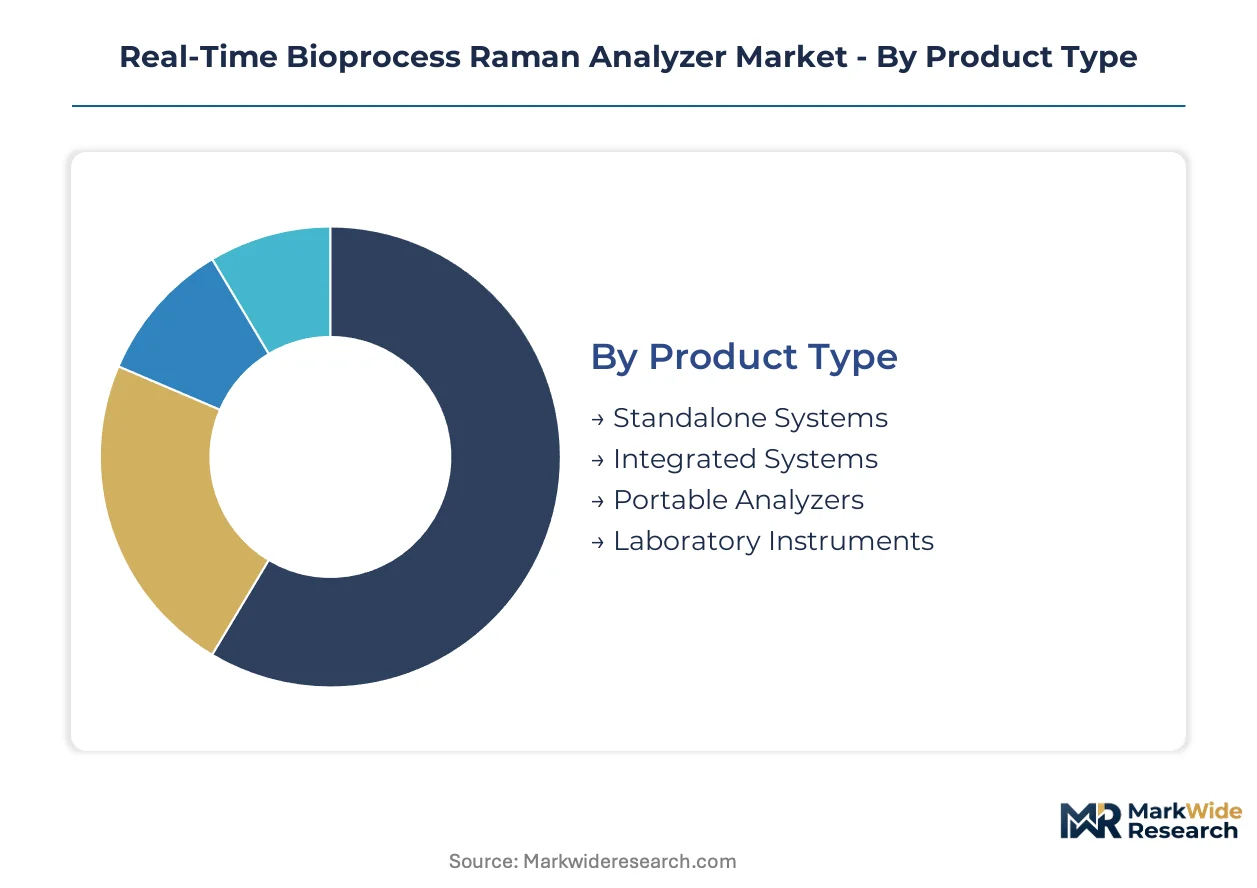
Facility upgrade cycles and validation transfer requirements create distinct procurement patterns across Raman analyzer categories. CDMOs prioritize integrated architectures while originators balance flexibility against capital efficiency in multi-site deployments.
Product Type:
Replacement cycles diverge sharply between stainless steel facilities and single-use greenfield sites, with probe-port standardization driving fiber-optic architecture preferences in newer installations.
- Integrated Systems:These embed directly into distributed control architectures with permanent probe installations in bioreactor vessels. Demand concentrates in Germany and South Korea where Samsung Biologics and Celltrion operate high-titer antibody suites requiring sub-minute glucose and lactate quantification.
- Portable Analyzers:Fiber-optic probe mobility enables validation transfer between production suites without permanent installation. Multi-site operators in the United States specify these for flexible deployment across geographically distributed manufacturing networks where centralized analytical teams demand method portability.
- Standalone Systems:Self-contained units serve mid-tier biopharma without captive process analytical technology capabilities.
- Laboratory Instruments:Offline method development tools anchor research institution procurement with stable replacement demand.
Integrated Systems sit at the top of the volume ranking, with Portable Analyzers climbing the fastest.
Deployment Model:
Data sovereignty requirements and GMP Annex 15 software validation burdens shape infrastructure decisions, with European facilities facing steeper compliance ramps than United States counterparts.
- On-Premise:Local server architectures isolate spectral data within facility firewalls. German and Irish commercial biologics plants mandate this configuration under EMA quality-by-design documentation requirements for multivariate analytical methods.
- Hybrid:Edge computing with cloud backup balances real-time processing against centralized model management. CDMOs with high batch-frequency operations adopt this architecture to compress chemometric model development timelines.
- Cloud-Based:Fully remote data processing serves research institutions without manufacturing compliance obligations.
- Remote Monitoring:Vendor-managed spectral analytics reduce in-house spectroscopy physics expertise requirements for mid-tier operators.
On-Premise deployments retain the largest installed base, though Hybrid configurations are gaining share fastest as CDMOs seek centralized method control.
Application Area:
Regulatory pathway differences between biologics and small molecules create specification variance, with FDA process analytical technology guidance elevating real-time release testing requirements in commercial antibody facilities.
- Biologics Production:Mammalian cell culture metabolite monitoring demands 785nm diode laser architectures for glucose, lactate, and antibody titer tracking. South Korean Songdo and Incheon clusters anchor demand as Samsung Biologics expands perfusion culture platforms.
- Pharmaceutical Manufacturing:Small-molecule synthesis monitoring employs simpler spectral libraries with shorter validation cycles. Indian biosimilar greenfield construction specifies integrated PAT from commissioning, bypassing retrofit friction seen in mature markets.
- Quality Control:Final release testing faces residual at-line HPLC preference in legacy facilities, limiting Raman penetration.
- Chemical Analysis:Process development applications serve research institutions with offline method validation.
Biologics Production commands the highest specification tier, with Pharmaceutical Manufacturing expanding most quickly in emerging biosimilar clusters.
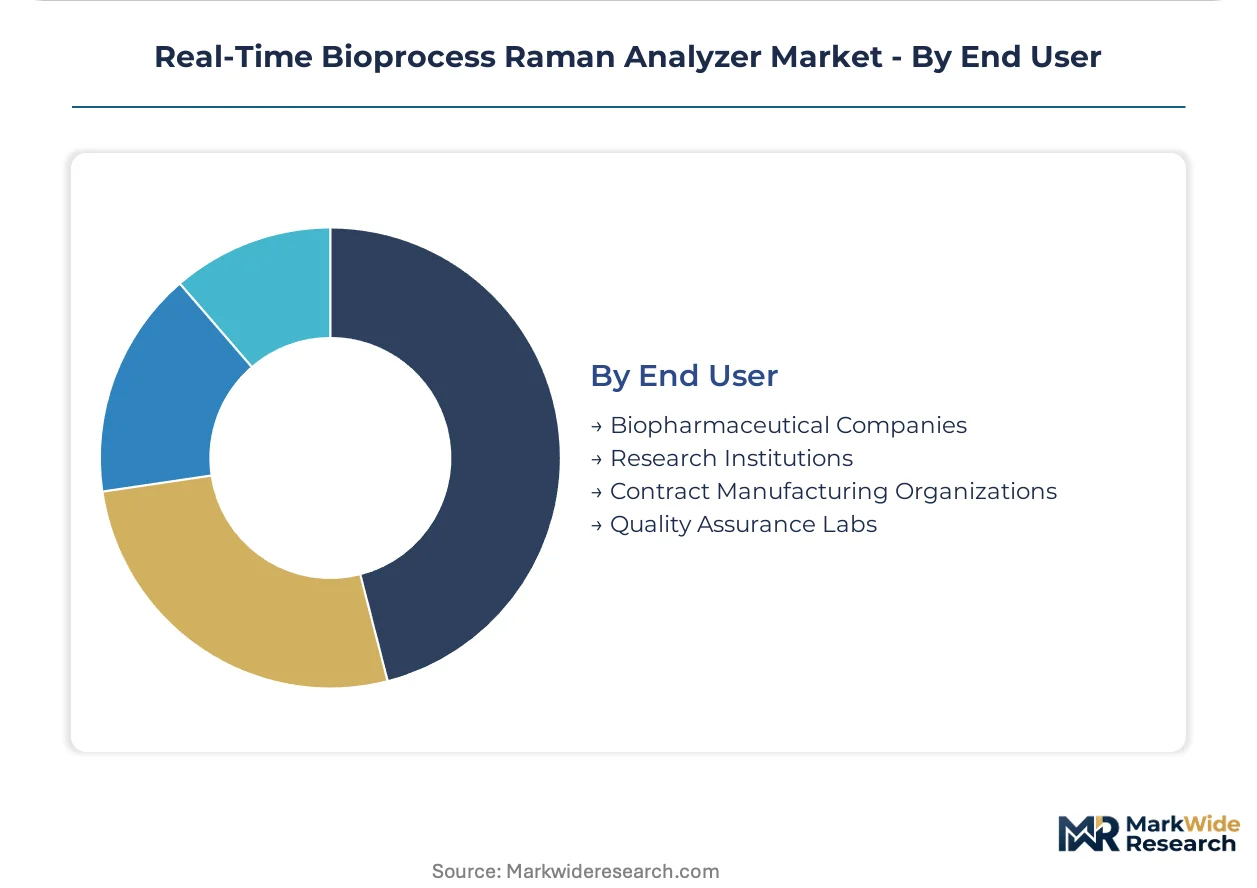
End User:
Procurement authority fragmentation between quality control departments and process engineering teams creates dual-track demand patterns, with CDMOs building captive analytical capabilities that decouple from originator purchasing cycles.
- Contract Manufacturing Organizations:High batch-frequency operations justify dedicated process analytical technology teams with neural chemometric architectures. CDMOs in Boston and Basel hiring pools concentrate hybrid spectroscopy-bioprocess expertise.
- Biopharmaceutical Companies:Originators prioritize standalone validation flexibility for multi-site method transfer. United States headquartered operators unbundle analyzer hardware from chemometric service contracts, treating spectral modeling as separable software subscriptions.
- Research Institutions:Offline method development drives Laboratory Instrument replacement demand with stable cyclical procurement.
- Quality Assurance Labs:At-line testing specifications lag upstream process monitoring adoption due to legacy HPLC validation infrastructure.
Contract Manufacturing Organizations anchor premium-tier procurement, with Biopharmaceutical Companies representing the steepest expansion trajectory as originators retrofit existing facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands tighter EMA compliance timelines than the United States, while South Korean biologics clusters outpace Japanese adoption in perfusion culture monitoring. National regulatory frameworks and industrial cluster concentration create distinct procurement patterns across major manufacturing geographies.
United States
FDA process analytical technology guidance mandates real-time release testing pathways that elevate Raman spectroscopy from optional to standard practice in commercial biologics facilities. Multi-site operators headquartered in the Boston and San Francisco Bay Area biotech corridors unbundle analyzer hardware from chemometric service contracts, treating spectral modeling as separable software subscriptions. Greater Boston hiring pools concentrate scarce hybrid spectroscopy-bioprocess expertise.
Germany
EMA quality-by-design frameworks enforce rigorous software validation and optical calibration protocols that filter out uncertified entrants. German commercial biologics facilities in Bavaria and North Rhine-Westphalia face 18-24 month qualification timelines for algorithm updates under GMP Annex 15 requirements. The Rhine-Main biopharma cluster anchors premium-tier integrated system deployments for high-titer antibody production.
South Korea
Samsung Biologics and Celltrion expansion in Songdo and Incheon concentrates demand for in-line metabolite monitoring in high-titer antibody production suites. MFDS biosimilar approval pathways reshape analyzer specification mixes between standalone and fully integrated platforms. The Incheon free economic zone hosts the densest perfusion culture platform deployments requiring sub-minute measurement cycles.
Switzerland
Swissmedic regulatory documentation requirements for multivariate analytical methods drive preference toward platforms with pre-validated algorithm change-control packages. Basel hiring pools compete with Boston for hybrid skill scarcity at the intersection of spectroscopy physics, bioprocess engineering, and regulatory documentation expertise. The Basel biopharma corridor anchors CDMO captive process analytical technology capability builds.
India
Biosimilar facility greenfield construction in Maharashtra and Telangana specifies integrated PAT from commissioning, bypassing the retrofit friction that slows adoption in mature markets. CDSCO evolving approval pathways for biosimilars reshape procurement timing for commercial manufacturing suites. The Hyderabad-Genome Valley biotech cluster leads emerging market adoption of neural chemometric architectures.
Real-Time Bioprocess Raman Analyzer Market Competitive Landscape
German and Japanese component suppliers anchor one tier through laser source concentration; United States and European system integrators hold deployment scale. The vendor base stratifies across spectroscopy heritage conglomerates, bioprocess workflow bundlers, and fiber-optic probe specialists. Three archetypes dominate: integrated platform providers, portable analyzer specialists, and chemometric software unbundlers. Competitive moves center on bioreactor-analyzer bundling contracts and centralized analytical method development service models.
Within the integrated platform tier, Bruker Corporation and Sartorius occupy positions shaped by adjacent instrumentation heritage. Kaiser Optical Systems exemplifies the fiber-optic probe specialization archetype that dominates upstream bioprocess monitoring architectures. Thermo Fisher Scientific represents the diversified life sciences conglomerate model with cross-portfolio analytical workflow integration. These three anchors illustrate how competitive positioning splits between spectroscopy physics depth and bioprocess workflow control breadth.
| Leading Market Players |
|---|
| Bruker Corporation |
| Agilent Technologies |
| Thermo Fisher Scientific |
| Kaiser Optical Systems |
| Horiba Group |
| Sartorius |
| Renishaw |
| METTLER TOLEDO |
| MarqMetrix |
| Others |
Value Network & Pricing Analysis
Captive integration into 785nm diode laser supply anchors both procurement security and pricing power for system builders with established German and Japanese supplier relationships. This vertical positioning insulates tier-one vendors from optical component volatility while forcing mid-tier competitors toward premium pricing or specification compromises.
Pricing Analysis
Capacity additions in South Korea and India are reshaping price floors for integrated Raman-DCS architectures as biosimilar greenfield facilities specify PAT from commissioning. Three-tier pricing structure across premium, standard, and economy levels separates fully validated GMP Annex 15 compliant platforms from laboratory-grade instruments. Cost compression in the standard tier intensifies because CDMOs unbundle hardware from chemometric service contracts. Contract manufacturing organizations exhibit the highest price sensitivity due to high batch-frequency operations, while research institutions show the least sensitivity given stable replacement cycles.
Supply Chain Analysis
785nm diode laser supply rests on German and Japanese specialty photonics manufacturers with single-source vulnerability for system builders outside established procurement channels. German laser source producers, Japanese optical component fabricators, and United States fiber-optic probe assemblers anchor upstream tiers. Distribution runs through bioprocess equipment distributors with regional service capabilities and direct OEM relationships for integrated platform deployments. Tariff exposure on precision optical components creates supply chain risk for European and North American system integrators dependent on East Asian component flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as FDA process analytical technology guidance and EMA quality-by-design frameworks shift procurement toward pre-validated algorithm change-control packages over commodity hardware.
For Market Incumbents: Anticipate neural chemometric architecture commoditization by CDMOs with captive analytical teams compressing model development timelines. Defend position through backward integration into 785nm diode supply relationships with German and Japanese producers. Prioritize certification investment in ISO 13485 and GMP Annex 15 pre-validated software packages to maintain premium positioning against emerging fiber-optic probe specialists. For New Entrants and Emerging Players: Capture analytical capability rental models allowing mid-tier biopharma to access validated Raman methods without capital ownership. The most penetrable segment sits in Indian biosimilar greenfield construction specifying integrated PAT from commissioning. Target the portable analyzer category for multi-site operators in the United States demanding validation transfer flexibility across geographically distributed manufacturing networks. For Investors and Strategic Acquirers: Roll-up economics work for fiber-optic probe specialists because chemometric software unbundling trends concentrate hardware procurement decisions on optical architecture performance. Long-term viability favors vendors with hybrid deployment model capabilities spanning on-premise GMP compliance and cloud-enabled method portability. Monitor CDMO captive process analytical technology buildouts as the signal indicating sustained premium-tier demand versus commoditization pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor-Analyzer Bundling | Sartorius tightens workflow control through integrated Raman-DCS architectures in Songdo antibody suites. |
| Neural Chemometric Platform Launch | Deep learning architectures compress model development from months to weeks for high-frequency CDMO operations. |
| Pre-Validated Algorithm Change-Control Package | EMA quality-by-design documentation requirements drive preference toward automated model lifecycle management tools. |
| Analytical Capability Rental Model | Mid-tier biopharma access validated Raman methods without capital ownership, expanding addressable demand. |
| Backward Integration into Laser Source Supply | German and Japanese 785nm diode relationships insulate tier-one vendors from optical component supply concentration. |
Research Methodology
Coverage spans the United States, Germany, South Korea, Switzerland, and India, with primary inputs from each geography combined with secondary validation. Primary interviews engaged bioprocess engineering directors, regulatory affairs leads at commercial biologics facilities, CDMO procurement executives, and fiber-optic probe development specialists. Secondary sources included FDA process analytical technology guidance documents, EMA quality-by-design framework publications, GMP Annex 15 software validation protocols, and MFDS biosimilar approval pathway filings. Bottom-up facility installation tracking and top-down biopharma capital expenditure analysis provided triangulation.
Rate-of-change decomposition across product type, deployment model, application area, and end user segments structured the analytical framework. CAGRs derived from weighted average of historical replacement cycles, greenfield facility commissioning schedules, and regulatory compliance timeline assumptions. Industry-specific inputs incorporated perfusion culture platform adoption rates in South Korean biologics clusters and CDMO captive analytical capability buildout trajectories in Boston and Basel hiring pools.
Optical component supply disruption, EMA software validation timeline extensions, and at-line HPLC residual preference in legacy quality control departments are the dominant revision risks. Material deviation in these triggers warrants pause and re-evaluation of integrated versus standalone platform demand splits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Bioprocessing Analytics Equipment Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market