
 Biobanking Equipment Market | 2026-2036
Biobanking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Biobanking Equipment Market Analysis
Pharmaceutical company procurement is expanding as cell and gene therapy developers build dedicated cryogenic storage infrastructure for clinical-grade specimens. Thermo Fisher Scientific dominates ultra-low temperature freezer manufacturing through in-house compressor technology and direct service networks. Becton, Dickinson and Company anchors automated sample handling with robotics integration for high-throughput biorepositories. PHC Holdings Corporation leverages Japanese precision engineering to sustain premium positioning in temperature stability systems.
Biobanking equipment comprises controlled-environment systems designed to preserve biological specimens at defined thermal setpoints, typically spanning mechanical cooling at minus 80 degrees Celsius and cryogenic preservation at liquid nitrogen temperatures below minus 150 degrees Celsius, with integrated monitoring to prevent thermal excursions that degrade nucleic acid or cellular integrity. Freezers occupy the largest installed base across research institutions, while automated inventory systems represent the fastest-expanding segment as biorepositories replace manual sample tracking with RFID-enabled retrieval to cut misidentification risk and labor cost. Cryogenic preservation technology leads margin pools due to specialized vessel engineering and recurring liquid nitrogen consumption contracts.
FDA 21 CFR Part 11 and EU MDR impose electronic record and device qualification standards that shape equipment validation protocols for clinical biobanks, while ISO 20387 establishes biobank-specific quality management that manufacturers must support through calibrated documentation packages. EMA's evolving guidance on advanced therapy medicinal products is tightening chain-of-custody requirements from collection through long-term storage. Stakeholders must monitor how decentralized manufacturing models for personalized cell therapies reshape cold chain infrastructure specifications and service expectations.
Market Dynamics
Cell therapy manufacturing workflows are forcing biobank operators to retool from static archival storage toward dynamic inventory systems capable of supporting continuous cold-chain custody for living therapeutic products.
Growth Catalysts
- EMA Advanced Therapy Guidance:Chain-of-custody mandates for ATMPs are compelling clinical biobanks to upgrade monitoring infrastructure and specimen tracking protocols.
- Liquid Nitrogen Cryopreservation:Long-term cellular viability requirements in regenerative medicine are expanding demand for vapor-phase nitrogen systems below minus 150 degrees Celsius.
- German Centralized Biobank Networks:Academic-clinical coordination hubs are aggregating procurement volumes and standardizing equipment specifications across multiple research institutions.
Market Restraints
- Helium Supply Concentration:Qatar and the United States control over 75 percent of global helium production, creating vulnerability for cryogenic cooling systems dependent on closed-cycle refrigeration.
- EU MDR Device Qualification:Extended conformity assessment timelines for Class IIb storage equipment are delaying product launches and freezing capital deployment cycles.
- Mechanical Freezer Energy Intensity:Ultra-low temperature units consuming 20-40 kWh daily face escalating operational costs as European electricity prices remain structurally elevated.
Strategic Opportunities
- India CDSCO Cell Therapy Framework:Emerging regulatory pathways for CAR-T manufacturing are creating first-mover openings for cryogenic infrastructure providers in academic medical centers.
- RFID-Enabled Automated Retrieval:Convergence of wireless inventory tracking with robotic sample handling is unlocking labor cost reductions in high-throughput biorepositories.
- Service Contract Unbundling:Liquid nitrogen consumption monitoring and predictive maintenance are splitting into standalone subscription offerings separate from equipment sales.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Specialized expertise in thermal insulation vessel design and cryogenic fluid dynamics remains concentrated among a narrow cohort of trained professionals.
- Legacy System Integration:Biorepositories with decades of manual inventory records face complex data migration requirements when retrofitting automated tracking platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobanking Equipment Market |
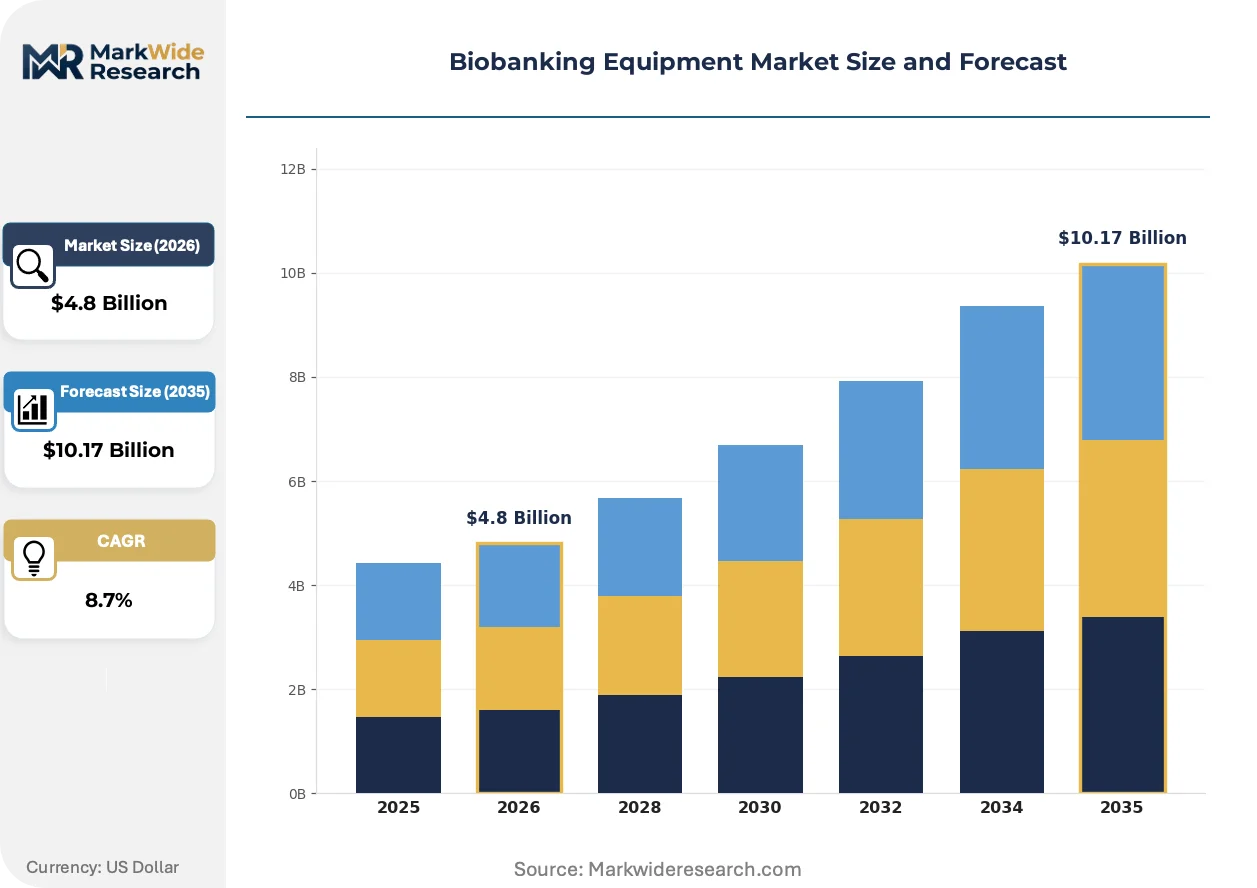
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freezers, Liquid Nitrogen Tanks, Centrifuges, Automated Inventory Systems End User: Research Institutions, Pharmaceutical Companies, Clinical Laboratories, Biotech Firms Technology: Mechanical Cooling, Cryogenic Preservation, RFID Tracking, Bioreactor Systems Application: Stem Cell Storage, DNA/RNA Preservation, Tissue Sample Management, Vaccine Development |
| Companies Covered | Thermo Fisher Scientific, Becton, Dickinson and Company, PHC Holdings Corporation, Hamilton Company, Merck KGaA, Qiagen, Azenta Life Sciences, Eppendorf SE, Haier Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobanking Equipment Market Emerging Trajectories
Digital specimen provenance systems are displacing paper-based chain-of-custody documentation across clinical-grade biobanks, while automation architectures compress labor dependencies in high-volume storage facilities.
Vapor-phase liquid nitrogen storage is overtaking liquid-phase immersion systems for cellular therapy applications. Cell therapy developers prefer vapor-phase configurations to eliminate cross-contamination risks during specimen retrieval. This shift is overtaking traditional liquid-phase vessel designs in new procurement specifications for clinical biobanks.
EU AI Act automated decision-making provisions are extending to biobank inventory algorithms that prioritize sample retrieval sequences. Equipment manufacturers must now document algorithmic transparency for systems recommending specimen handling priorities. German biobank networks are requiring vendor attestation of AI system conformity before procurement authorization.
Biopharmaceutical procurement departments are consolidating vendor relationships from fragmented equipment purchases toward integrated cold-chain partnerships. Single-source accountability for storage hardware, monitoring software, and consumable supply is displacing multi-vendor configurations. This concentration is most visible in United States cell therapy developers building dedicated GMP-compliant biorepositories.
Biobanking Equipment Market Segmentation
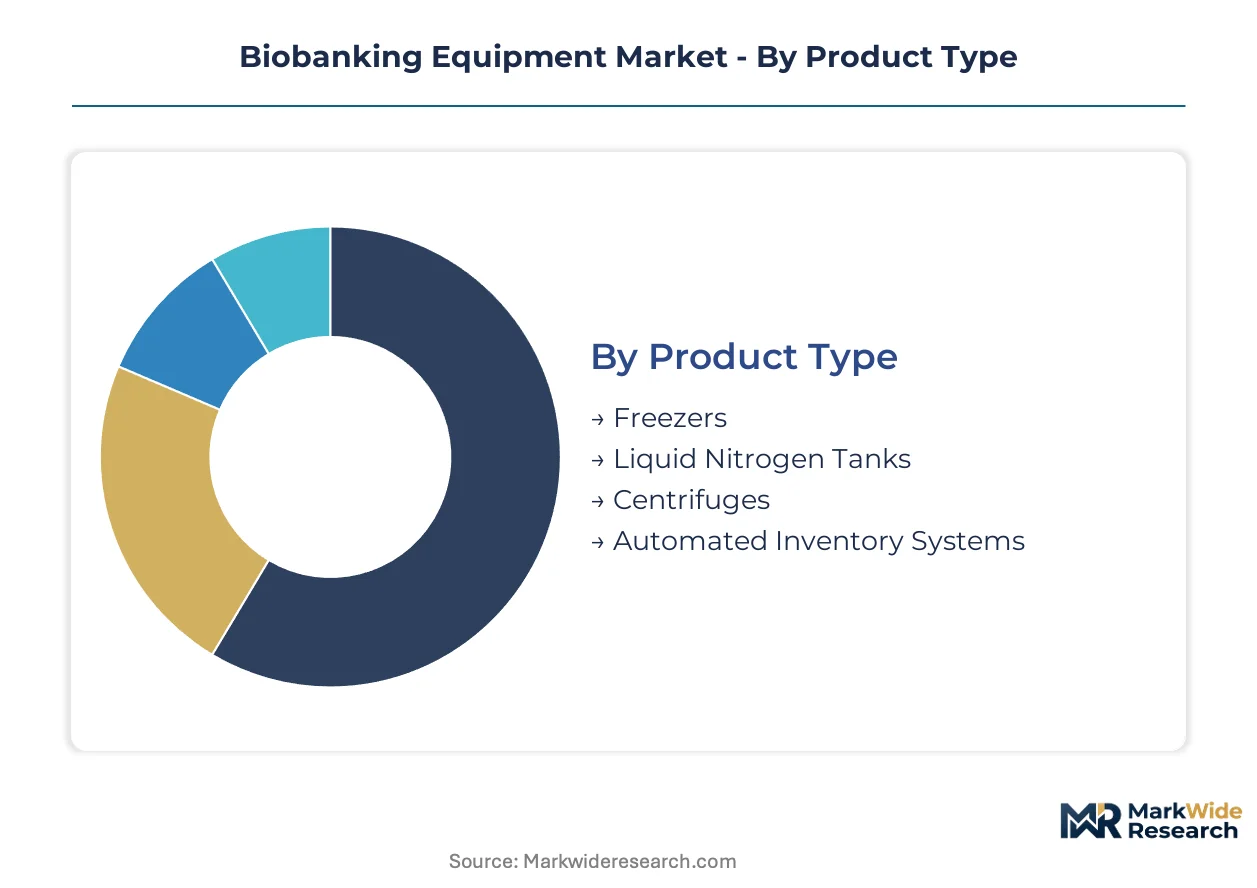
Equipment segmentation in biobanking reflects divergent thermal requirements across specimen types and the operational scale of end-use facilities. Procurement patterns vary sharply between academic repositories prioritizing capital efficiency and pharmaceutical developers building GMP-compliant infrastructure for cell therapy workflows.
Product Type:
Replacement cycles across product categories accelerate as temperature monitoring regulations tighten and energy efficiency standards advance in major markets.
- Freezers:Mechanical ultra-low temperature units operating at minus 80 degrees Celsius constitute the largest installed base across research institutions. German centralized biobank networks are standardizing procurement specifications for these units to streamline maintenance contracts and parts interoperability.
- Liquid Nitrogen Tanks:Vapor-phase and liquid-phase cryogenic vessels enable preservation below minus 150 degrees Celsius for long-term cellular viability. Cell therapy developers in the United States are specifying these systems for clinical-grade specimen storage to meet FDA chain-of-custody requirements.
- Centrifuges:Refrigerated centrifugation systems maintain specimen integrity during pre-storage processing protocols.
- Automated Inventory Systems:Robotic retrieval platforms with RFID tracking are displacing manual sample handling in high-throughput facilities.
Freezers sit at the top of the volume ranking, with automated inventory systems climbing the fastest.
End User:
Customer concentration patterns follow funding availability and regulatory exposure across the research-to-clinical continuum.
- Pharmaceutical Companies:Cell and gene therapy developers are constructing dedicated cryogenic infrastructure for clinical-grade specimen workflows. These facilities demand integrated hardware-software systems with validated electronic records to satisfy FDA 21 CFR Part 11 and EMA ATMP guidance.
- Research Institutions:University biorepositories and academic medical centers operate the largest population of legacy equipment. German biobank coordination hubs are aggregating procurement volumes across multiple institutions to negotiate service contract terms.
- Clinical Laboratories:Hospital-based biobanks face mounting pressure to upgrade monitoring systems for diagnostic specimen retention.
- Biotech Firms:Emerging cell therapy developers prioritize flexible leasing arrangements over capital purchases for early-stage infrastructure.
Research institutions maintain the deepest installed base, while pharmaceutical companies are expanding capacity most aggressively.
Technology:
Technology selection hinges on specimen thermal sensitivity thresholds and the regulatory classification of stored materials.
- Cryogenic Preservation:Liquid nitrogen systems deliver the thermal stability required for long-term cellular viability in regenerative medicine applications. Vapor-phase configurations are overtaking liquid-phase designs as cell therapy developers prioritize contamination risk mitigation.
- Mechanical Cooling:Compressor-based systems at minus 80 degrees Celsius dominate routine nucleic acid and protein preservation. These units face escalating operational cost pressure from European electricity price structures.
- RFID Tracking:Wireless inventory systems enable real-time specimen location and chain-of-custody documentation.
- Bioreactor Systems:Controlled-environment vessels support living cell culture prior to cryopreservation or therapeutic administration.
Mechanical cooling commands the broadest deployment, though cryogenic preservation is gaining share fastest in clinical-grade installations.
Application:
Application requirements diverge based on specimen biological complexity and intended downstream use.
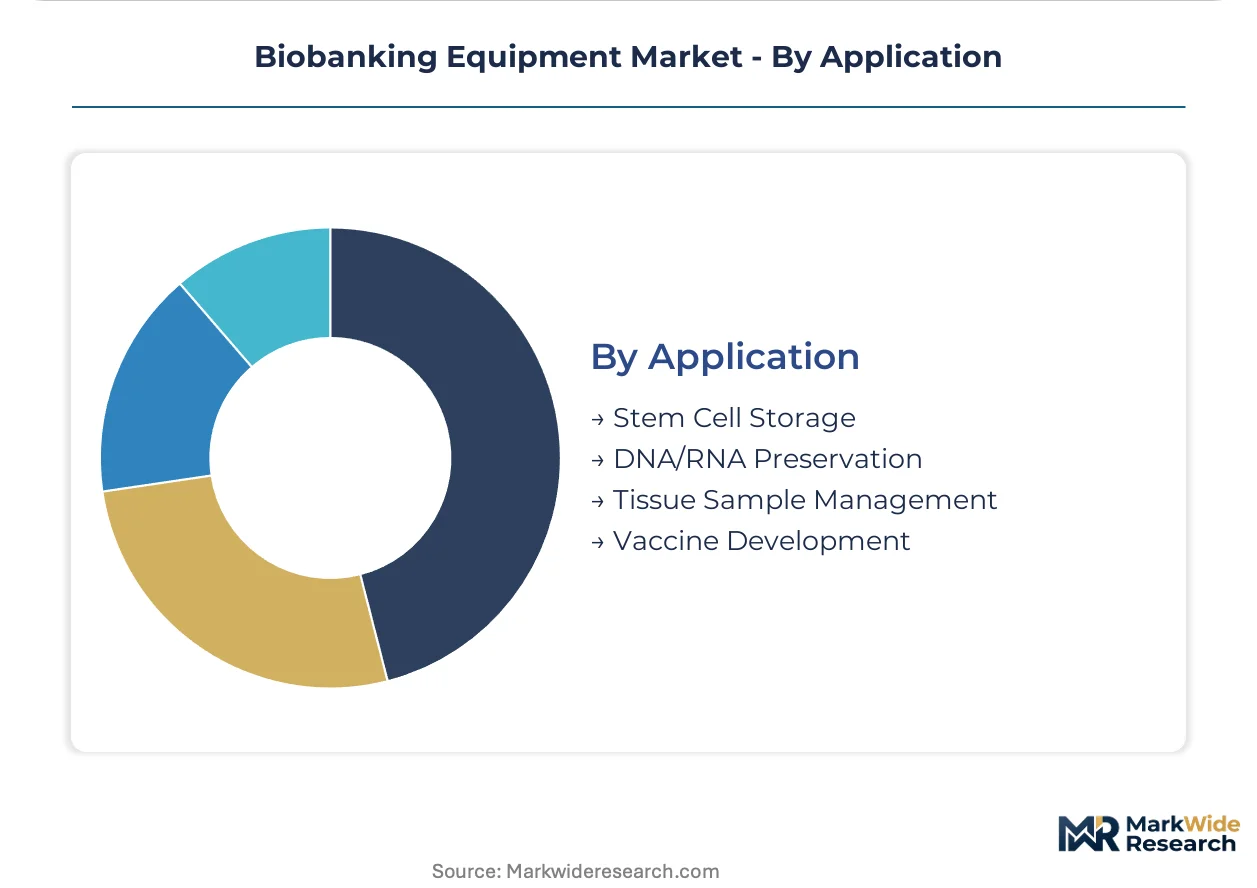
- Stem Cell Storage:Cryogenic preservation of pluripotent and differentiated cells demands vapor-phase nitrogen systems with validated thermal uniformity. EMA guidance on advanced therapy medicinal products is tightening monitoring requirements for these high-value specimens.
- DNA/RNA Preservation:Ultra-low temperature mechanical storage suffices for nucleic acid integrity maintenance across extended durations. Research institutions in Germany are consolidating specifications for these applications through centralized procurement frameworks.
- Tissue Sample Management:Formalin-fixed and frozen tissue repositories require humidity-controlled storage with barcode tracking integration.
- Vaccine Development:Temperature-stable storage supports preclinical and clinical trial material retention for infectious disease programs.
DNA/RNA preservation represents the largest application volume, with stem cell storage expanding most quickly as cell therapy pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment procurement as cell therapy developers migrate infrastructure investments toward jurisdictions with streamlined ATMP approval pathways and lower cost-of-compliance burdens.
United States
Cell therapy developers in Boston and San Francisco are building dedicated GMP-compliant biorepositories with integrated hardware-software systems. FDA 21 CFR Part 11 imposes electronic record standards that shape validation protocols for clinical-grade storage. The Research Triangle Park cluster in North Carolina is aggregating cryogenic infrastructure for centralized ATMP manufacturing.
Germany
Centralized biobank networks in Berlin and Munich are standardizing procurement specifications across academic-clinical coordination hubs. EU MDR device qualification timelines are extending conformity assessments for Class IIb storage equipment. The Heidelberg-Mannheim medical technology corridor is deploying vapor-phase nitrogen systems for stem cell preservation workflows.
China
NMPA pathways for CAR-T manufacturing are accelerating cryogenic infrastructure deployment in Shanghai and Beijing biotech parks. Dual carbon goals are pressuring energy-intensive mechanical freezer operations toward efficiency upgrades. The Suzhou Industrial Park cluster is attracting foreign equipment vendors for localized production of temperature stability systems.
India
CDSCO's emerging cell therapy framework is creating first-mover openings for cryogenic infrastructure in academic medical centers. BIS certification requirements for imported storage equipment are extending procurement timelines for research institutions. The Hyderabad-Bengaluru pharmaceutical corridor is consolidating biobank capacity for vaccine development programs.
Japan
PMDA quality standards for regenerative medicine products are tightening thermal monitoring requirements for long-term cellular storage. METI subsidies for precision manufacturing are supporting domestic production of temperature control systems. The Kobe biomedical innovation cluster is integrating automated inventory systems with robotic sample handling platforms.
Biobanking Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system providers commanding premium positioning in pharmaceutical procurement while regional fabricators compete on capital efficiency for academic installations. The vendor base organizes around three archetypes: diversified laboratory conglomerates with cryogenic portfolios, dedicated temperature-control engineering houses, and automation-integrated platform developers. M&A activity concentrates on software-enabled monitoring capabilities, while capacity expansion targets vapor-phase nitrogen vessel production for cell therapy applications.
Among diversified laboratory technology providers, Thermo Fisher Scientific and Merck KGaA exemplify the integrated conglomerate archetype with broad life science portfolios. Becton, Dickinson and Company represents the automation-integrated position, while PHC Holdings Corporation occupies a precision-engineering specialization within the temperature-control segment. These three companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Becton, Dickinson and Company |
| PHC Holdings Corporation |
| Hamilton Company |
| Merck KGaA |
| Qiagen |
| Azenta Life Sciences |
| Eppendorf SE |
| Haier Biomedical |
| Others |
Supply Flow & Price Mechanics
Liquid nitrogen consumption contracts flow from Qatar and United States helium concentration through tiered equipment pricing, with pharmaceutical buyers absorbing premium vapor-phase vessel costs while academic institutions negotiate consolidated service bundles through German coordination hubs.
Pricing Analysis
Distributor margins compress the spread between OEM equipment pricing and end-user acquisition cost, with direct-to-pharmaceutical contracts commanding steeper discounts for volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated systems with FDA 21 CFR Part 11 documentation from research-grade units with basic temperature logging. Cost compression in mechanical freezer segments is intensifying because European electricity tariffs strain operational budgets. Academic biorepositories exhibit highest price sensitivity, while cell therapy developers prioritize thermal validation over capital efficiency.
Supply Chain Analysis
EU MDR device qualification gating extends procurement timelines for Class IIb storage equipment, forcing inventory buffers at distribution nodes. Manufacturing concentrates in Germany, Japan, and United States for precision compressor systems and cryogenic vessel fabrication. Raw material dependencies span specialized aluminum alloys for vacuum insulation, rare-earth magnets for compressor motors, and helium for closed-cycle refrigeration. Single-source vulnerability concentrates in Qatar-dominated helium feedstock. Distribution runs through authorized service networks with captive liquid nitrogen supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biobanking equipment functions as a stable compounder anchored by irreversible regulatory ratchets for specimen traceability that perpetuate replacement demand across clinical and research installations.
For Market Incumbents: Deepen vertical integration into predictive maintenance software and liquid nitrogen logistics to lock in recurring revenue streams. Thermo Fisher Scientific's compressor technology ownership provides a template for margin defense against emerging automation-integrated platform developers. Capacity addition in German centralized biobank networks secures anchor tenancy for standardized specification rollouts.
For New Entrants and Emerging Players: Enter via India's CDSCO cell therapy framework before established vendors consolidate academic medical center relationships. The Hyderabad-Bengaluru pharmaceutical corridor offers lowest penetration density among major biotech clusters. A leasing-first go-to-market angle bypasses capital budget constraints at emerging biotech firms.
For Investors and Strategic Acquirers: Consolidation pressure builds where software-enabled monitoring capabilities fragment across legacy hardware vendors. The five-to-ten year viability window favors acquisition targets with validated AI inventory algorithms and EU AI Act attestation pathways. Watch for EMA advanced therapy guidance revisions that mandate retrofits of existing biorepository infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Enabled Automation Integration | Robotic retrieval platforms cut labor cost and misidentification risk in high-throughput German biobank networks. |
| Vapor-Phase Nitrogen Vessel Certification | FDA 21 CFR Part 11 validation opens pharmaceutical procurement channels for cell therapy developers. |
| Service Contract Unbundling | Standalone predictive maintenance subscriptions capture recurring revenue separate from equipment sales cycles. |
| EU MDR Conformity Investment | CE marking for Class IIb storage equipment accelerates product launch timelines in European markets. |
| Helium Supply Diversification | Alternative cryogenic cooling architectures reduce vulnerability to Qatar production concentration. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with biobank operations directors, pharmaceutical procurement managers, GMP quality officers, and cryogenic engineering specialists combined with secondary validation against FDA 510(k) filings, EMA device registration databases, ISO 20387 certification records, and German biobank network procurement disclosures. Triangulation across stakeholder inputs and regulatory documentation ensures cross-verified demand and supply estimates.
Historical trendline analysis of replacement cycles and regulatory compliance deadlines shaped projection mechanics across the analysis window. Segmentation dimensions modeled include product type, end-user archetype, preservation technology, and application workflow. CAGRs derived from equipment shipment tracking and service contract value aggregation. Industry-specific forecast inputs incorporated EMA advanced therapy guidance evolution and EU AI Act implementation timelines for automated inventory systems.
Inputs from regulatory filings and procurement databases were available through the study window; gaps in real-time liquid nitrogen consumption data introduce uncertainty bands around service revenue projections. Forecasts reflect documented assumptions on replacement elasticity and certification timeline standardization. A model refresh is warranted upon material change in EMA chain-of-custody requirements or helium supply disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Amino Acid Analyzer Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Lab Automation in Bioanalysis Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Total Nucleic Acid Extraction Kits Market
Biotechnology Equipment
Automated Cell Culture Equipment Market