
 Biobank Equipment Market | 2026-2036
Biobank Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Biobank Equipment Market Outlook
North American cryogenic equipment manufacturing is pivoting toward automated cold-chain systems for biorepositories. Thermo Fisher Scientific leverages its vertical integration into compressor technology and temperature monitoring software to sustain premium positioning in ultra-low freezers. Becton Dickinson anchors its presence through integrated sample preparation and storage workflows for pharmaceutical clients. Haier Biomedical competes aggressively on manufacturing scale, offering cost-optimized mechanical freezer lines that dominate hospital procurement in price-sensitive segments.
Biobank equipment comprises temperature-controlled storage systems, analytical instruments, and sample management infrastructure engineered to preserve biological specimens at defined thermal setpoints ranging from 4°C ambient cooling to minus 196°C liquid nitrogen vapor-phase storage. These systems serve the primary commercial purpose of maintaining sample viability, genetic integrity, and chain-of-custody documentation across decades-long research horizons. Freezers and cryogenic systems command the largest installed base, though automated technology segments are expanding fastest as biorepositories confront labor scarcity and throughput scaling imperatives. Pharmaceutical companies and research institutions represent the deepest end-user margin pools, driven by cell therapy manufacturing requirements and population-scale genomic cohort programs.
FDA 21 CFR Part 11 electronic records requirements, EU MDR traceability mandates, and ISO 20387 biobanking quality standards collectively shape equipment validation protocols and procurement qualification criteria across regulated markets. The EU AI Act's emerging governance framework for automated sample handling systems will add compliance layers for European biobank operators investing in robotic retrieval platforms. Stakeholders must monitor regulatory divergence between FDA quality system regulations and EMA biobank certification pathways when configuring multi-site equipment deployment strategies.
Market Dynamics
Automated sample handling systems are compressing operational labor requirements while tightening regulatory compliance windows for biorepository operators managing multi-decade cold-chain integrity.
Growth Catalysts
- EU MDR traceability mandates:Biological sample tracking requirements are compelling biobanks to upgrade legacy storage infrastructure with integrated monitoring systems that capture chain-of-custody metadata.
- Cell therapy manufacturing scale-up:Pharmaceutical companies are building dedicated biorepositories to support autologous and allogeneic cell therapy pipelines, driving procurement of vapor-phase liquid nitrogen systems.
- China's national biobanking initiative:Government-funded genomic cohort programs are accelerating freezer and cryogenic equipment deployment across provincial research hospitals.
Market Restraints
- Compressor supply concentration:Ultra-low freezer manufacturing depends on specialized compressor components sourced from a limited supplier base in Germany and Japan, creating input vulnerability.
- ISO 20387 certification timelines:Biobank quality standard validation protocols extend equipment qualification periods, delaying revenue recognition for manufacturers.
- Mechanical freezer energy intensity:Operating costs for minus 80°C mechanical systems constrain adoption in emerging market research institutions facing electricity price volatility.
Strategic Opportunities
- India's biorepository infrastructure gap:Underpenetrated cold-chain capacity in academic medical centers creates first-mover positioning for automated storage system providers.
- AI Act compliance integration:European biobanks investing in robotic retrieval platforms can bundle algorithmic audit trail documentation as a differentiated service layer.
- Service contract unbundling:Predictive maintenance subscriptions using IoT temperature monitoring are opening recurring revenue streams independent of equipment sales cycles.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in liquid nitrogen system design and safety protocol implementation is concentrated among a narrow cohort of trained technicians.
- Legacy freezer fleet interoperability:Biorepositories operating mixed-vendor installed bases face integration complexity when deploying unified sample management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobank Equipment Market |
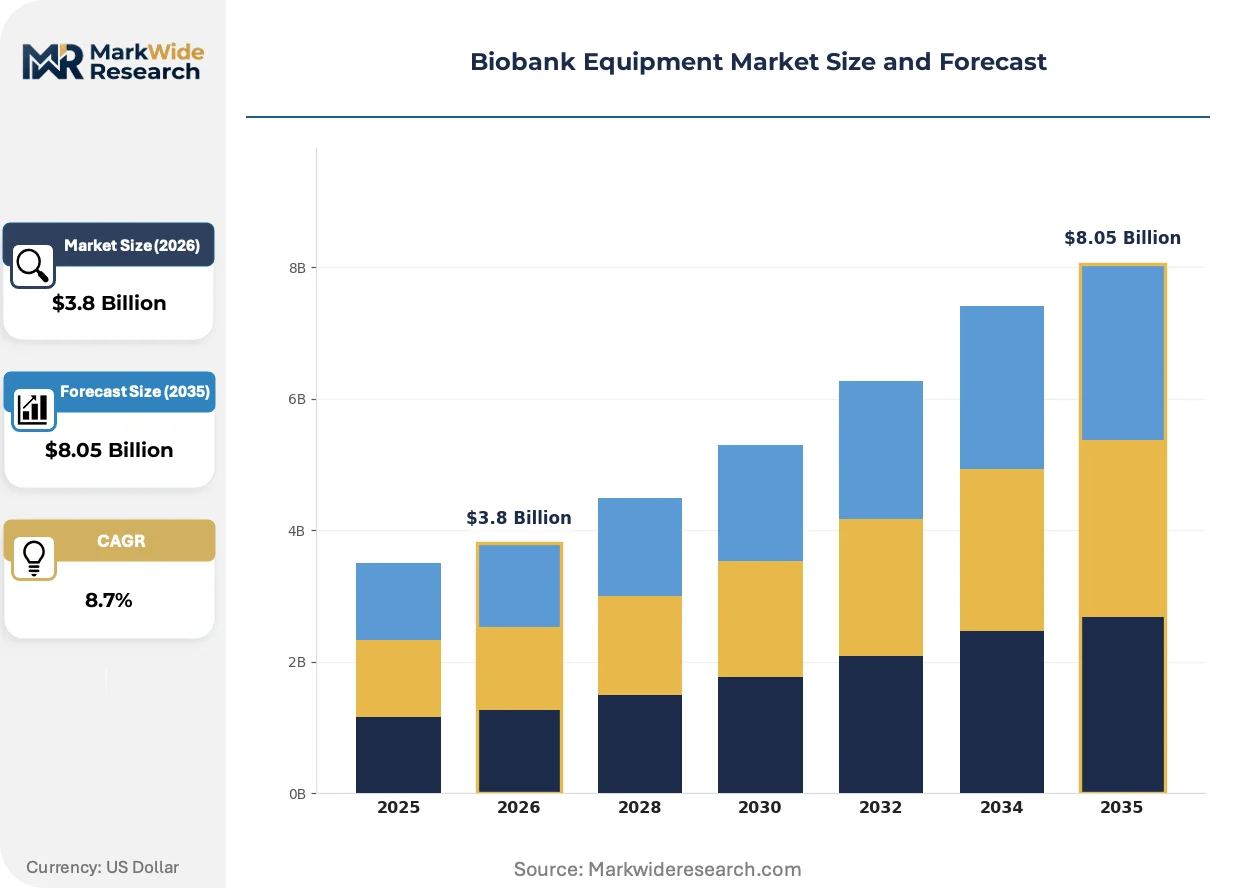
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freezers, Refrigerators, Incubators, Analyzers Technology: Mechanical, Cryogenic, Electrical, Automated End User: Research Institutions, Pharmaceutical Companies, Hospitals, Biorepositories Application: Sample Storage, DNA Analysis, Biospecimen Management, Drug Discovery |
| Companies Covered | Thermo Fisher Scientific, Becton Dickinson, Azenta Life Sciences, PHC Holdings Corporation, Hamilton Company, Merck KGaA, Qiagen, Haier Biomedical, Eppendorf SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobank Equipment Market Strategic Shifts
Robotic sample retrieval and AI-driven predictive maintenance are compressing labor dependency while extending equipment operational lifecycles beyond traditional service intervals.
Vapor-phase liquid nitrogen storage with automated elevator-based retrieval is rewriting biorepository staffing models. Cell therapy manufacturers are adopting these systems at accelerated procurement cycles. The technology is rewriting workforce planning by eliminating manual sample handling in minus 196°C environments and reducing occupational exposure liability.
EU AI Act governance frameworks for automated biological sample handling are mandating algorithmic transparency documentation. Equipment manufacturers must now embed explainable decision logs for robotic retrieval actions. European biobank operators are responding by requiring vendor-provided compliance certification packages before platform procurement.
Pharmaceutical companies are consolidating biorepository equipment procurement under centralized supply chain functions, displacing decentralized hospital purchasing authority. Group purchasing organizations are capturing contract negotiation leverage for multi-site freezer deployments. This concentration is most visible in United States-based pharmaceutical conglomerates integrating biorepository operations with cell therapy manufacturing networks.
Biobank Equipment Market Segmentation
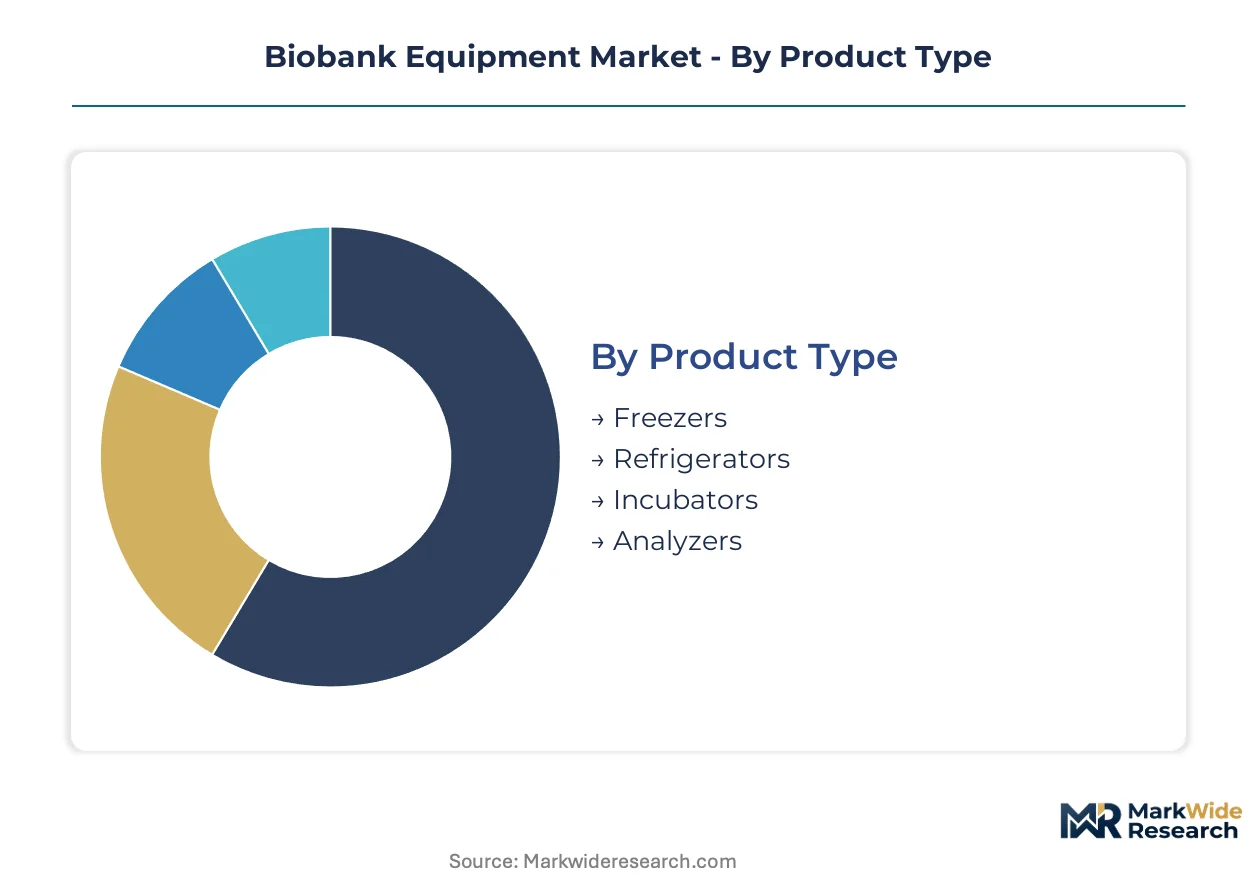
Biobank equipment procurement cycles vary dramatically across product categories and end-use settings, with replacement timelines stretching from 7 years for mechanical freezers to 15-plus years for cryogenic infrastructure. Segmentation reveals where upgrade investments concentrate and which technology transitions are compressing traditional replacement windows.
Product Type:
Equipment replacement cycles diverge sharply across thermal categories, with mechanical systems facing compressed upgrade timelines from energy efficiency mandates while cryogenic assets extend service lives through modular component refurbishment.
- Freezers:Ultra-low mechanical units operating at minus 80°C constitute the largest installed base across biorepositories and pharmaceutical manufacturing sites. Research institutions in Germany and the United States are retiring aging compressor-based fleets ahead of F-Gas Regulation phase-down schedules, triggering procurement of next-generation units with hydrocarbon refrigerants.
- Refrigerators:4°C controlled-temperature units serve high-throughput short-term sample holding in clinical laboratories and hospital pathology departments. Hospital procurement in China's provincial medical centers is accelerating as biobanking infrastructure expands under national genomic cohort programs, with demand concentrating in units above 500-liter capacity.
- Incubators:Controlled atmosphere systems maintain cell culture viability for biobank-derived sample expansion prior to analytical processing.
- Analyzers:Automated nucleic acid extraction and quality assessment instruments integrate directly with storage workflows for sample-in-result-out processing pipelines.
Volume placements concentrate in Freezers; the faster expansion belongs to Analyzers.
Technology:
Capital intensity and operational cost structures segment technology adoption, with automated platforms commanding premium positioning against mature mechanical alternatives.
- Mechanical:Compressor-driven vapor-compression cycles dominate minus 20°C to minus 86°C applications through proven reliability and lower capital outlay. Research institutions in India face adoption constraints from electricity price volatility and compressor maintenance dependency on limited qualified service networks.
- Cryogenic:Liquid nitrogen vapor-phase and liquid-phase systems achieve minus 150°C to minus 196°C setpoints required for long-term cellular material preservation. Pharmaceutical companies building autologous cell therapy manufacturing infrastructure in the United States are procuring vapor-phase systems with automated elevator retrieval at accelerated rates.
- Electrical:Thermoelectric and Stirling engine alternatives address niche applications requiring vibration-free operation or portable deployment.
- Automated:Robotic sample handling and retrieval platforms integrate temperature monitoring, chain-of-custody documentation, and inventory management software. EU MDR traceability mandates are compelling biorepository operators to specify automated systems with embedded audit trail generation for biological sample tracking compliance.
Mechanical systems retain the largest installed footprint; automated platforms are climbing the fastest.
End User:
Procurement authority and qualification requirements segment end-use demand, with pharmaceutical supply chain centralization displacing traditional hospital purchasing autonomy.
- Research Institutions:Academic medical centers and university biorepositories operate mixed-vendor installed bases with extended equipment service intervals constrained by capital budget cycles. ISO 20387 certification timelines are extending qualification periods for new equipment deployments across European national biobanking networks.
- Pharmaceutical Companies:Cell therapy manufacturers and precision medicine developers are consolidating biorepository procurement under centralized supply chain functions. United States-based conglomerates are integrating dedicated storage infrastructure with manufacturing networks to support autologous and allogeneic pipeline scale-up.
- Hospitals:Clinical biobanks within academic medical centers face procurement decentralization challenges as pathology departments retain purchasing authority for diagnostic-grade storage units.
- Biorepositories:Specialized commercial and public-sector sample management facilities operate at largest scale with highest throughput automation requirements.
Pharmaceutical procurement is gaining share fastest; research institutions retain the deepest installed base.
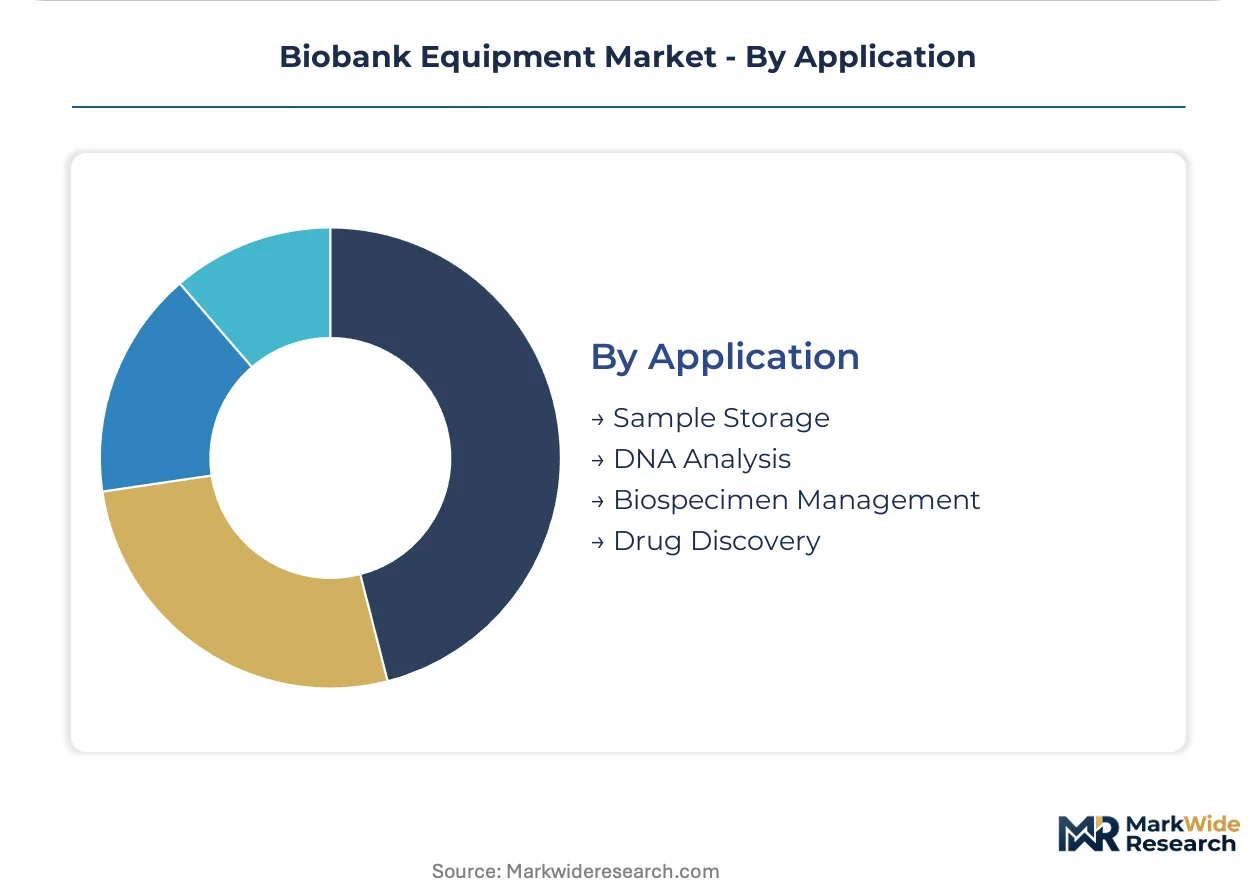
Application:
Workflow integration requirements segment application demand, with sample storage anchoring equipment volume while analytical applications drive technology upgrading.
- Sample Storage:Long-term preservation of biological specimens at defined thermal setpoints constitutes the foundational equipment application. China's national biobanking initiative is accelerating freezer and cryogenic system deployment across provincial research hospitals to support population-scale genomic cohort programs.
- DNA Analysis:Extraction, quantification, and quality control instrumentation processes biobank-derived genetic material for downstream sequencing and genotyping. Pharmaceutical companies are specifying integrated storage-to-analysis workflows that compress sample handling steps and reduce chain-of-custody risk exposure.
- Biospecimen Management:Inventory tracking, retrieval scheduling, and chain-of-custody documentation systems layer software control over physical storage infrastructure.
- Drug Discovery:High-throughput screening and compound profiling applications leverage biobank-derived cellular and molecular materials for target validation and lead optimization.
Sample Storage commands placement volume; DNA Analysis applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized compressor manufacturing in Germany and Japan anchors cryogenic equipment supply chains, while precision medicine investments in the United States and genomic program funding in China drive procurement cycles across the forecast window.
United States
Cell therapy manufacturing scale-up and pharmaceutical biorepository consolidation dominate equipment procurement. FDA 21 CFR Part 11 electronic records requirements compel integrated monitoring system upgrades. The Greater Boston biotech corridor accelerates vapor-phase liquid nitrogen system deployment for autologous pipeline infrastructure.
Germany
F-Gas Regulation phase-down schedules trigger premature retirement of hydrocarbon refrigerant freezer fleets across academic medical centers. EMA biobank certification pathways and ISO 20387 quality standards extend equipment validation timelines. The Rhine-Ruhr industrial cluster concentrates compressor component manufacturing for ultra-low temperature systems.
China
National biobanking initiative funding accelerates freezer procurement across provincial research hospitals under population-scale genomic cohort programs. NMPA medical device registration requirements tighten equipment import qualification. The Yangtze River Delta biotech corridor concentrates automated storage system deployment in Shanghai-Nanjing-Hangzhou metro clusters.
Japan
PMDA quality system regulations and METI industrial standards shape biorepository equipment certification protocols for domestic and export markets. Precision medicine infrastructure investments drive cryogenic system adoption. The Kanto region around Tokyo anchors pharmaceutical company biorepository consolidation and cell therapy manufacturing network integration.
India
Underpenetrated cold-chain capacity in academic medical centers creates procurement acceleration potential as national genomic medicine programs expand. CDSCO medical device regulations and BIS standards govern import qualification for temperature-controlled storage systems. Maharashtra and Karnataka state biotech clusters concentrate early automated storage system pilot deployments.
Biobank Equipment Market Competitive Environment
Global majors compete with regional champions across compressor technology and temperature monitoring software integration, producing a tiered structure where integrated life science conglomerates hold premium positioning against cost-optimized manufacturing specialists. Three archetypes dominate: vertically integrated full-line suppliers controlling upstream compressor production; workflow-integrated platform providers bundling sample preparation with storage infrastructure; and scale-driven mechanical freezer fabricants competing on manufacturing throughput. Capacity expansion in automated retrieval platforms and strategic partnerships for IoT-enabled predictive maintenance services represent the dominant competitive vectors.
Among the integrated conglomerates, Thermo Fisher Scientific occupies a position exemplifying backward integration into compressor technology and captive software development. Becton Dickinson represents the workflow-integrated archetype, anchoring pharmaceutical client relationships through sample-to-analysis platform bundling. Haier Biomedical sits within the manufacturing-scale tier, competing on cost-optimized mechanical freezer production volume for price-sensitive hospital procurement segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Becton Dickinson |
| Azenta Life Sciences |
| PHC Holdings Corporation |
| Hamilton Company |
| Merck KGaA |
| Qiagen |
| Haier Biomedical |
| Eppendorf SE |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical supply chain centralization in the United States and Germany is compressing procurement negotiations into multi-year service-bundled contracts that embed predictive maintenance subscriptions and ISO 20387 validation support. This buyer concentration shifts pricing power toward volume-scale purchasers capable of extracting performance guarantees and extended warranty terms from equipment vendors.
Pricing Analysis
Warranty unbundling and predictive maintenance subscription tiers are separating premium vendor positioning from cost-optimized alternatives. Pricing stratifies across FDA-validated premium systems, CE-marked standard platforms, and economy mechanical freezer lines without integrated monitoring. Cost compression in the economy tier is intensifying because Haier Biomedical and regional Asian manufacturers are expanding hydrocarbon refrigerant production capacity. Hospital procurement committees in price-sensitive emerging markets exhibit highest price sensitivity, while pharmaceutical cell therapy manufacturers demonstrate lowest sensitivity due to compliance-driven specification requirements.
Supply Chain Analysis
Specialized cryogenic engineering talent scarcity in Germany and Japan is constraining compressor component production expansion for ultra-low temperature systems. Manufacturing feeds from German precision machining clusters for hydrocarbon refrigerant compressors and Japanese thermal engineering facilities for Stirling cycle alternatives. Supply chain vulnerability centers on single-source dependency for minus 86°C compressor subassemblies from two dominant suppliers. Distribution runs through life science equipment distributors with GPO contract access in the United States and direct hospital procurement relationships in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory certification timelines and capital intensity are forcing consolidation among sub-scale mechanical freezer fabricants unable to fund automated platform R&D or ISO 20387 validation infrastructure.
For Market Incumbents: Deepen backward integration into compressor technology and captive temperature monitoring software development to defend margin position against modular automated platform entrants. Prioritize predictive maintenance subscription revenue streams that decouple growth from equipment replacement cycles. Pharmaceutical client consolidation into centralized supply chain functions threatens traditional distributor relationships, requiring direct enterprise contracting capabilities. For New Entrants and Emerging Players: The mid-tier price-point gap between Thermo Fisher Scientific premium positioning and Haier Biomedical economy lines offers white-space entry for automated storage platforms with EU MDR pre-certified audit trail functionality. India's underpenetrated academic medical center cold-chain infrastructure presents the most penetrable geography for first-mover automated system deployment. Target service contract unbundling as the primary go-to-market angle, selling IoT-enabled predictive maintenance independently of capital equipment. For Investors and Strategic Acquirers: The window for entry favors automated platform specialists with EU AI Act compliance documentation and established pharmaceutical reference accounts. Long-term viability over the next decade rests on recurring revenue share from software-enabled monitoring services rather than hardware shipment volumes. Watch for FDA 21 CFR Part 11 enforcement actions against biorepositories using legacy manual inventory systems as the inflection signal for accelerated automated platform procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Retrieval Platform Deployment | Eliminates manual handling liability in minus 196°C environments while compressing labor requirements for cell therapy manufacturers. |
| Predictive Maintenance Subscription Launch | Opens recurring revenue streams independent of seven-year freezer replacement cycles using IoT temperature monitoring. |
| EU AI Act Compliance Certification | Mandates explainable decision logs for robotic retrieval actions, creating differentiation for pre-certified vendors. |
| Compressor Technology Backward Integration | Secures supply chain control over specialized minus 86°C refrigeration components concentrated in Germany and Japan. |
| India Biorepository Infrastructure Partnership | Captures first-mover positioning in academic medical centers as national genomic medicine programs expand cold-chain capacity. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this biobank equipment analysis. Primary interviews with biorepository operations directors, pharmaceutical supply chain managers, hospital procurement committees, and cryogenic engineering specialists were combined with FDA 510(k) filings, EU MDR technical documentation, and NMPA registration databases. Bottom-up equipment shipment analysis and top-down precision medicine infrastructure spending estimates were triangulated to validate market sizing.
Data-stream reconciliation across manufacturer production disclosures, GPO contract award notifications, and national biobanking program budget allocations shaped the analytical framework. Segmentation modeling incorporated product thermal category, automation technology tier, end-user procurement authority, and application workflow integration across the projection horizon. CAGRs were derived from equipment replacement cycle compression, regulatory mandate timing, and cell therapy manufacturing capacity expansion trajectories.
Inputs from FDA, EMA, and NMPA regulatory databases were available through the study window; gaps in private biorepository operator capital expenditure plans introduce uncertainty bands around automated platform adoption timing. Forecasts reflect assumptions regarding F-Gas Regulation enforcement consistency and pharmaceutical biorepository consolidation velocity. Material deviation in FDA 21 CFR Part 11 audit enforcement or EU AI Act implementation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Lab Automation in Bioanalysis Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Single-Use Bioprocess Sensor Calibration and Validation Test Systems Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
North America Life Science Tools Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Genetic Analyzer Systems Market