
 Lab Automation in Bioanalysis Market | 2026-2036
Lab Automation in Bioanalysis Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Automation in Bioanalysis Market Outlook
Skilled bioanalytical technicians is rotating toward programming and systems integration roles as manual pipetting and plate handling decline. Tecan Group Ltd leverages its dominance in liquid handling instrumentation to anchor European pharmaceutical accounts. Hamilton Company sustains its position through specialized robotic precision for high-throughput screening environments. Thermo Fisher Scientific competes by extending its channel control across clinical laboratories and academic consortia.
Lab automation in bioanalysis encompasses integrated hardware-software platforms that execute sample preparation, liquid transfer, and analytical detection with throughput exceeding 10,000 samples daily and CV precision below 3%. These systems serve biopharmaceutical quality control, pharmacokinetic studies, and biomarker quantification where reproducibility failures carry regulatory and financial penalties. Liquid handling systems occupy the largest installed base while artificial intelligence segments exhibit the fastest expansion as predictive maintenance and autonomous protocol optimization reduce unplanned downtime. Contract research organizations represent a concentrated margin pool due to their volume-driven procurement and multi-site standardization requirements.
FDA 21 CFR Part 11, EU MDR, and ISO 13485 collectively enforce audit trails, software validation, and design controls that elongate product development cycles but create compliance barriers for new entrants. EPA and OSHA frameworks additionally govern hazardous reagent handling and laboratory ventilation standards that shape workstation enclosure specifications. Stakeholders must monitor evolving AI validation guidance from FDA and EMA as autonomous decision-making in sample routing and flagging advances beyond current predicate device pathways.
Market Dynamics
Pharmaceutical R&D timelines are compressing as automated liquid handling and robotic sample preparation displace manual pipetting workflows, forcing equipment vendors to reconfigure service models around throughput guarantees rather than hardware sales.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signature requirements are mandating audit-trail capabilities in bioanalytical workflows, pulling pharmaceutical quality control departments toward validated automation platforms.
- High-throughput screening:Biopharma discovery groups are deploying integrated robotic systems to execute 10,000+ sample daily throughputs for pharmacokinetic studies and biomarker quantification.
- CRO network densification:Contract research organizations in the United States, Germany, and China are standardizing multi-site automation protocols to capture volume-driven procurement contracts.
Market Restraints
- Capital intensity:Automated liquid handling workstations require seven-figure capital commitments that freeze mid-tier academic laboratories out of procurement cycles.
- Software validation friction:FDA predicate device pathways and EU MDR design controls elongate product development timelines, creating compliance barriers for new equipment entrants.
- Precision component supply:Robotic positioning modules and pipetting heads concentrate manufacturing in specialized German and Swiss supplier networks, exposing lead time vulnerabilities.
Strategic Opportunities
- Artificial intelligence integration:Predictive maintenance algorithms and autonomous protocol optimization are reducing unplanned downtime in biopharma quality control environments.
- Biomarker quantification expansion:Clinical diagnostic laboratories are adopting automated sample preparation for precision medicine applications beyond traditional drug development.
- India biopharma clusters:CDSCO regulatory alignment and PLI scheme incentives are attracting automation vendors to establish localized service infrastructure for emerging CRO networks.
Industry Challenges
- Technician reskilling gaps:Bioanalytical technicians require programming and systems integration competencies as manual plate handling declines, creating workforce transition friction.
- Legacy system interoperability:Pharmaceutical quality control departments face integration complexity when connecting new robotic platforms to established LIMS and chromatography data systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Automation in Bioanalysis Market |
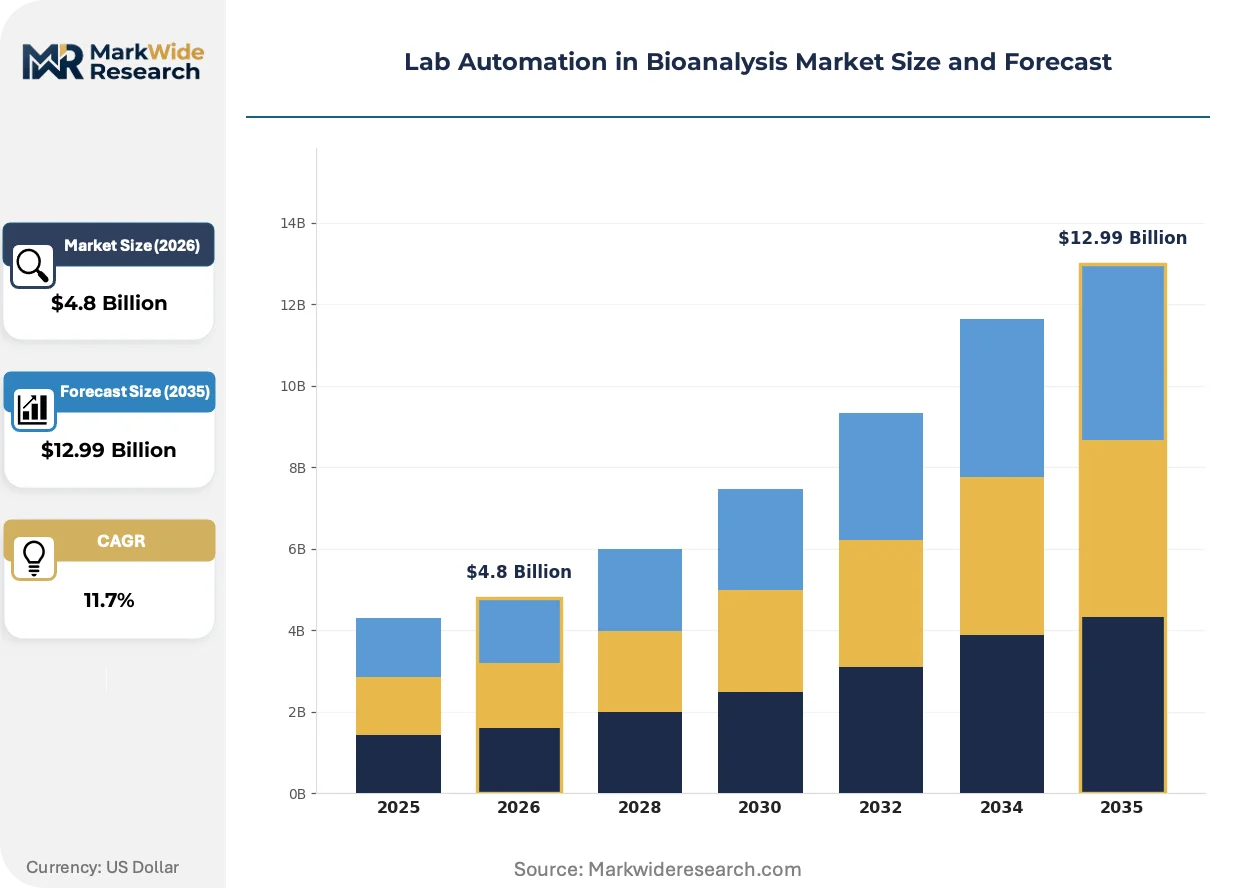
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Handling, Robotic Systems, Automated Workstations, Sample Preparation Technology: Nanotechnology, Microarray, Robotics, Artificial Intelligence End User: Pharmaceuticals, Academic Institutions, Contract Research Organizations, Clinical Laboratories Application: Drug Development, Diagnostics, Quality Control, Genomic Analysis |
| Companies Covered | Agilent Technologies, Becton Dickinson, Thermo Fisher Scientific, Tecan Group Ltd, Hamilton Company, Danaher Corporation, Siemens Healthineers, PerkinElmer, Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Automation in Bioanalysis Market Strategic Shifts
Workflow orchestration software is displacing standalone instrument control, compressing the boundary between liquid handling execution and analytical detection into unified platform architectures.
Artificial intelligence is fragmenting traditional equipment service models. Machine learning algorithms now predict pipetting accuracy degradation and schedule preemptive calibration interventions before CV precision drifts beyond 3% thresholds. Biopharma quality control groups in Massachusetts and Basel are deploying these capabilities to eliminate batch release delays. The technology is fragmenting vendor revenue streams from reactive service contracts toward outcome-based uptime guarantees.
EMA AI validation guidance is reshaping autonomous decision-making protocols. The draft framework extends beyond current predicate device pathways to address sample routing algorithms and automated flagging systems in bioanalytical workflows. European pharmaceutical manufacturers are front-loading compliance documentation for AI-enabled liquid handling platforms ahead of formalized requirements. German CRO networks are establishing internal validation protocols that anticipate regulatory convergence between EMA and FDA positions.
Service unbundling is accelerating among academic consortia and mid-tier pharmaceutical developers. Buyers are separating hardware procurement from validation support and maintenance contracts, sourcing specialized compliance services from third-party consultancies. This pattern concentrates in United States research clusters where NIH funding constraints favor capital-light operational models. Thermo Fisher Scientific and Tecan Group are responding with modular service tiers that decouple installation qualification from ongoing performance verification.
Lab Automation in Bioanalysis Market Segmentation
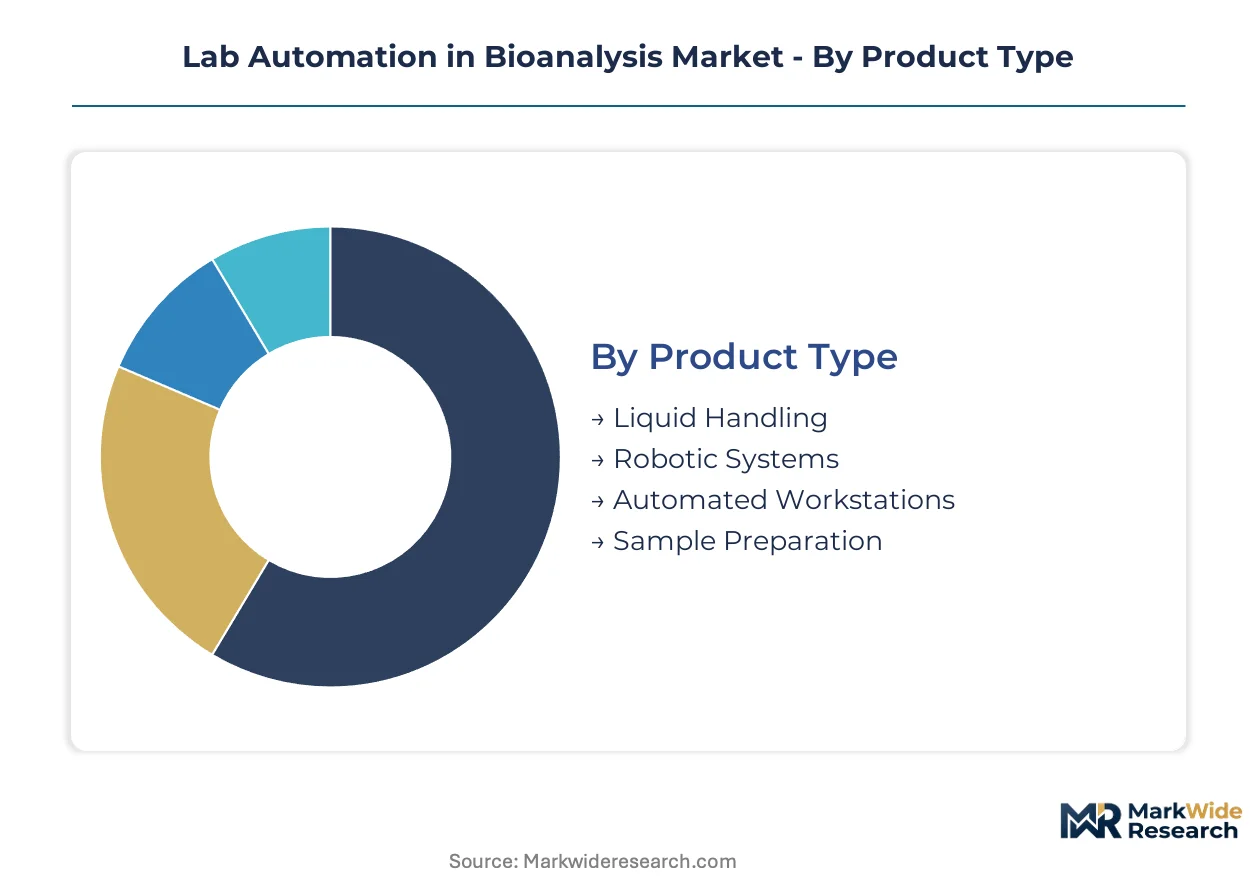
Segmentation in lab automation reveals distinct procurement patterns across product tiers and customer types. Equipment vendors configure channel strategies differently for capital-intensive robotic platforms versus modular liquid handling components. Understanding these divides sharpens targeting for both established suppliers and emerging entrants.
Product Type:
Channel mix varies sharply across hardware categories, with direct sales teams handling integrated workstations while distributors move standardized liquid handling modules.
- Liquid Handling:Precision pipetting modules and multi-channel dispensers form the largest installed base in bioanalytical laboratories. Demand concentrates in United States pharmaceutical quality control departments where FDA 21 CFR Part 11 compliance requirements mandate audit-trail capabilities for electronic records.
- Robotic Systems:Articulated arm platforms and gantry-based sample processors execute plate handling and reagent addition with sub-millimeter repeatability. German CRO networks in Munich and Hamburg are deploying these systems to standardize multi-site protocols for high-throughput pharmacokinetic studies.
- Automated Workstations:Integrated benchtop systems combine liquid handling with incubation and detection in enclosed footprints. Academic consortia favor these units for space-constrained core facilities.
- Sample Preparation:Solid-phase extraction and protein precipitation modules automate upstream processing prior to chromatographic analysis. Clinical diagnostic laboratories in Basel and Boston are adopting these for biomarker quantification workflows.
By volume, Liquid Handling leads. By growth pace, Robotic Systems is ahead.
Technology:
Cost tier stratification separates mature mechanical platforms from premium AI-enabled systems commanding validation premiums.
- Robotics:Servo-driven positioning systems and collaborative arm architectures deliver the mechanical foundation for high-throughput screening environments. Swiss precision component suppliers dominate manufacturing of robotic positioning modules.
- Artificial Intelligence:Machine learning algorithms for predictive maintenance and autonomous protocol optimization are expanding most quickly in biopharma quality control settings. Massachusetts manufacturers are front-loading EMA AI validation documentation ahead of formalized regulatory requirements.
- Microarray:High-density spotting and hybridization automation supports genomic and proteomic analysis workflows. Academic research clusters remain the primary demand concentration.
- Nanotechnology:Nanoliter-scale dispensing and microfluidic integration enable miniaturized assay formats. Specialized applications in precision medicine drive niche procurement.
By installed base, Robotics dominates. By margin expansion, Artificial Intelligence commands the steepest trajectory.
End User:
Customer type determines service bundling preferences, with CROs demanding multi-site standardization and academic buyers seeking capital-light operational models.
- Pharmaceuticals:Biopharma quality control departments and discovery groups represent the highest-value accounts, prioritizing throughput guarantees and regulatory validation support. United States and German manufacturers are compressing drug development timelines through automated liquid handling deployment.
- Contract Research Organizations:Volume-driven procurement and multi-site standardization requirements create concentrated margin pools for vendors offering unified platform architectures. Chinese CRO networks in Shanghai and Suzhou are densifying automation infrastructure.
- Clinical Laboratories:Diagnostic service providers adopt automated sample preparation for precision medicine applications beyond traditional drug development. CDSCO regulatory alignment in India is attracting localized service investment.
- Academic Institutions:NIH funding constraints favor modular procurement separating hardware from validation services. Research clusters source compliance support from third-party consultancies.
By revenue concentration, Pharmaceuticals leads. By procurement velocity, Contract Research Organizations is climbing the fastest.
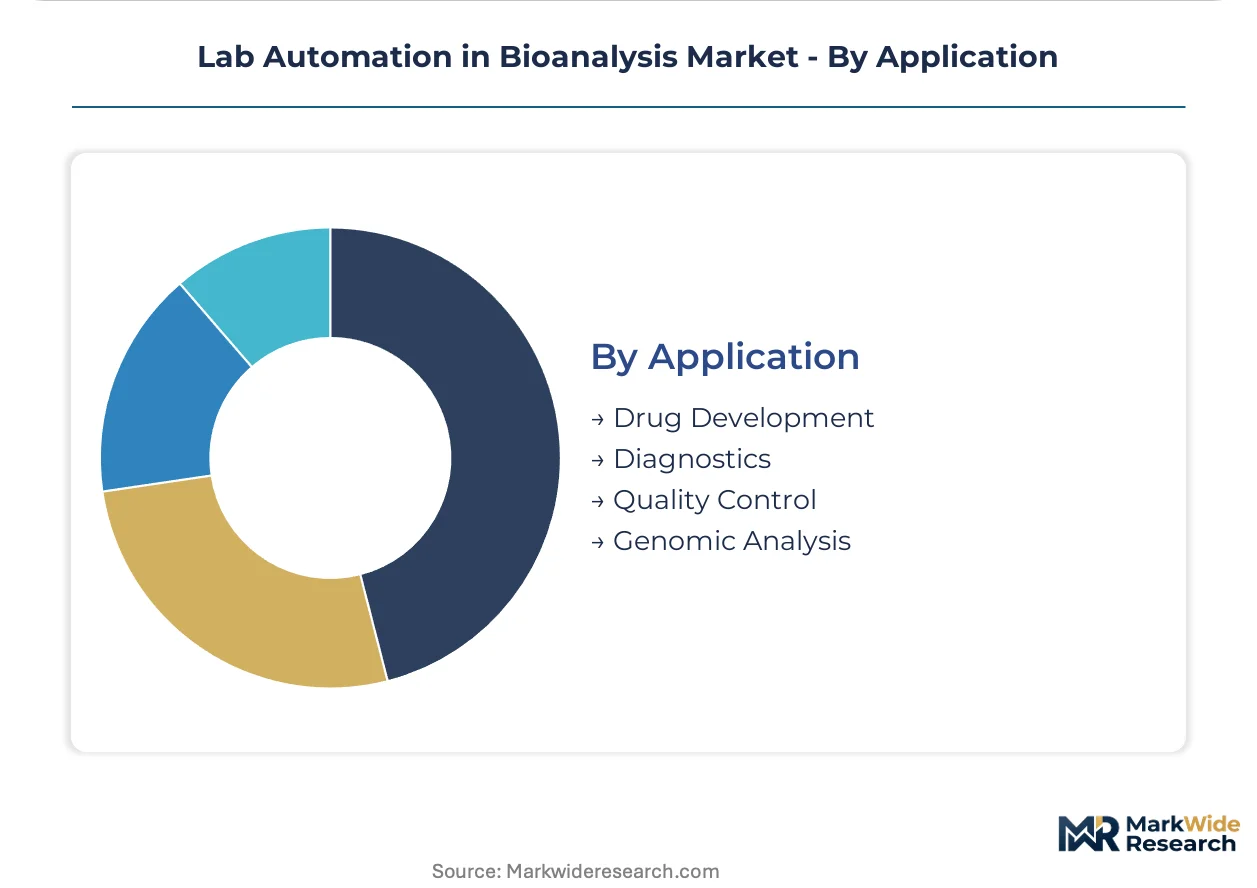
Application:
Maturity gradients separate established quality control workflows from emerging genomic applications requiring novel validation frameworks.
- Drug Development:Pharmacokinetic studies and biomarker quantification in discovery and clinical phases drive the core demand base. FDA 21 CFR Part 11 and EU MDR standards are reshaping equipment validation protocols for electronic records and design controls.
- Quality Control:Batch release testing and stability studies in biopharma manufacturing require CV precision below 3% with full audit trails. Basel and Massachusetts quality control groups are deploying AI-enabled predictive maintenance to eliminate release delays.
- Diagnostics:Clinical biomarker testing and companion diagnostic development are expanding automated sample preparation adoption beyond traditional drug development settings.
- Genomic Analysis:Next-generation sequencing sample prep and nucleic acid quantification represent emerging demand with evolving validation requirements. EMA and FDA AI guidance development is shaping autonomous protocol optimization in this space.
By current spend, Drug Development leads. By regulatory tailwinds, Quality Control is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 compliance requirements anchor demand concentration in the United States, where biopharma quality control departments and CRO networks drive procurement velocity. German precision engineering clusters and Chinese biopharma expansion create complementary growth poles across the analysis window.
United States
Pharmaceutical quality control departments in Massachusetts and North Carolina deploy automated liquid handling to compress batch release timelines. FDA predicate device pathways and 21 CFR Part 11 audit-trail mandates pull validated platforms into GMP environments. Greater Boston biopharma clusters are front-loading AI-enabled predictive maintenance to eliminate unplanned downtime in high-throughput screening operations.
Germany
Baden-Württemberg and Bavaria precision component suppliers dominate robotic positioning module manufacturing for liquid handling systems. EU MDR design controls and EMA draft AI validation guidance are reshaping equipment qualification protocols. Munich and Hamburg CRO networks standardize multi-site automation architectures to capture volume-driven procurement contracts from global pharmaceutical accounts.
China
Shanghai and Suzhou biopharma clusters densify automation infrastructure for domestic drug development and export manufacturing. NMPA regulatory alignment with international standards accelerates validated platform adoption. CDSCO convergence initiatives in neighboring India create spillover demand for Chinese CRO network expansion into South Asian markets.
Switzerland
Basel pharmaceutical quality control groups demand CV precision below 3% for stability studies and biomarker quantification workflows. Swissmedic enforcement of ISO 13485 design controls creates compliance barriers for non-validated equipment entrants. Zurich and Geneva precision engineering suppliers concentrate manufacturing of pipetting heads and servo-driven positioning systems.
India
Hyderabad and Bangalore biopharma clusters attract automation vendors establishing localized service infrastructure. CDSCO regulatory alignment and PLI scheme incentives reduce capital intensity barriers for mid-tier CRO procurement. Maharashtra-based contract research organizations standardize multi-site protocols to compete for global pharmaceutical outsourcing contracts.
Lab Automation in Bioanalysis Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum controlling channel access across pharmaceutical quality control and CRO networks. Mid-scale players concentrate on modular liquid handling components and third-party validation services. Two strategic archetypes dominate: precision-engineering specialists from German and Swiss manufacturing clusters, and diversified life science conglomerates leveraging clinical laboratory channel control. Competitive moves center on service unbundling to capture NIH-constrained academic accounts, and AI validation documentation front-loading ahead of EMA formal requirements.
Among diversified life science conglomerates, Thermo Fisher Scientific occupies a position exemplifying channel control across clinical laboratories and academic consortia. Tecan Group Ltd and Hamilton Company represent the precision-engineering specialist archetype, with the former anchoring European pharmaceutical accounts through liquid handling instrumentation dominance and the latter sustaining positioning through high-throughput screening precision. These three names illustrate the competitive tension between scale-driven platform consolidation and specialized robotic accuracy.
| Leading Market Players |
|---|
| Agilent Technologies |
| Becton Dickinson |
| Thermo Fisher Scientific |
| Tecan Group Ltd |
| Hamilton Company |
| Danaher Corporation |
| Siemens Healthineers |
| PerkinElmer |
| Hoffmann-La Roche |
| Others |
Value Chain & Pricing Dynamics
AI-enabled predictive maintenance modules are displacing traditional reactive service contracts as the primary value anchor, simultaneously shifting supply geography toward Massachusetts and Basel software development clusters while compressing pricing premiums for mechanical-only liquid handling platforms. This substitution dynamic concentrates margin capture among vendors controlling algorithm development talent pools and elongates replacement cycles for standardized pipetting hardware.
Pricing Analysis
Price spreads between German-engineered precision systems and Asian-assembled alternatives widen to three-tier differentiation based on FDA 21 CFR Part 11 validation depth and ISO 13485 certification tier. Academic consortia exhibit highest price sensitivity, deferring seven-figure capital commitments through modular procurement separating hardware from third-party validation services. Pricing pressure stems from NIH funding constraints favoring capital-light operational models, while biopharma quality control departments absorb premiums for throughput guarantees and audit-trail compliance.
Supply Chain Analysis
Inbound logistics costs from Hamburg and Rotterdam port congestion ripple through robotic positioning module lead times, compressing just-in-time delivery windows for CRO network expansion projects. Swiss and German suppliers dominate pipetting head and servo-drive manufacturing, drawing from specialized precision component networks in Baden-Württemberg and Zurich. Single-source vulnerability concentrates in nanoliter-scale dispensing mechanisms, with distribution running through direct sales teams for integrated workstations and distributor channels for standardized liquid handling modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA predicate device pathways and EU MDR design controls constructs formidable defensive moats, as compliance documentation requirements elongate product development timelines beyond the capital horizon of most emerging entrants.
For Market Incumbents: Secure channel control across CRO networks through multi-site standardization protocols that embed switching costs in unified platform architectures. Invest in backward integration into precision component manufacturing to mitigate German and Swiss supplier concentration risks. Front-load EMA AI validation documentation ahead of formalized requirements to extend compliance barriers against software-native challengers. For New Entrants and Emerging Players: Third-party validation services for NIH-constrained academic consortia represent an under-served service layer where incumbents bundle hardware and compliance support at premium rates. Target modular liquid handling component procurement in United States research clusters, positioning through capital-light subscription models that separate instrument access from validation burden. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-engineering specialists with captive AI development capabilities and established pharmaceutical quality control relationships. Long-term viability hinges on autonomous protocol optimization competencies beyond mechanical accuracy. Monitor FDA draft guidance on AI validation as the critical inflection signal for regulatory pathway convergence.| Strategic Initiative | Industry Significance |
|---|---|
| AI Validation Documentation Front-Loading | EMA draft guidance anticipation creates compliance moats before formalized requirements emerge. |
| Multi-Site CRO Protocol Standardization | Volume-driven procurement contracts from Shanghai and Suzhou networks embed platform switching costs. |
| Backward Integration into Precision Components | Captive supply of pipetting heads mitigates Baden-Württemberg supplier concentration vulnerabilities. |
| Service Unbundling for Academic Consortia | Modular validation tiers capture NIH-constrained buyers seeking capital-light operational models. |
| Predictive Maintenance Algorithm Development | Machine learning for pipetting accuracy degradation shifts revenue from reactive contracts to outcome-based uptime guarantees. |
Study Parameters
The analysis maps liquid handling instrumentation, robotic sample preparation systems, and AI-enabled workflow platforms, each validated through bioanalytical laboratory directors, pharmaceutical quality control managers, CRO procurement leads, and regulatory affairs specialists. Primary fieldwork combined with secondary sources including FDA 21 CFR Part 11 guidance documents, EU MDR technical files, ISO 13485 audit records, and NMPA registration databases supports bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and application workflow, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs were derived from installed base expansion rates and replacement cycle compression in biopharma quality control environments, incorporating pharmacokinetic study throughput requirements and biomarker quantification demand trajectories as industry-specific inputs.
Underlying assumptions cover FDA and EMA regulatory convergence timelines, with deviation risk concentrated in AI validation guidance formalization pace and precision component supply chain resilience. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Automated Colony Picking Systems Market
Biotechnology Equipment
Global Life Sciences Tools Market
Biotechnology Equipment
Cell Proliferation Kit Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Bioprocessing Systems Market