
 PCR Master Mix Market | 2026-2036
PCR Master Mix Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Master Mix Market Analytics
Trained molecular diagnostics technicians is unwinding capacity constraints across high-throughput clinical laboratories. Thermo Fisher Scientific leverages its vertical integration in enzyme manufacturing to control raw material quality and cost structures. Qiagen anchors its position through specialized sample-to-insight workflows that bundle reagents with instrumentation. Bio-Rad competes on digital PCR technology leadership, extending its mix portfolio into rare mutation detection applications.
PCR master mix denotes a pre-formulated buffered solution containing thermostable DNA polymerase, deoxynucleotide triphosphates, magnesium chloride, and stabilizers optimized for thermal cycling amplification. Ready-to-use formulations eliminate user pipetting errors and batch-to-batch variability in quantitative and endpoint PCR workflows. Ready-to-use mixes dominate commercial volume due to standardization demands in regulated clinical environments, while custom formulations capture premium margins from pharmaceutical companies running proprietary assay panels. Digital PCR technology represents the fastest-expanding segment as absolute quantification replaces relative threshold methods in cell therapy quality control.
FDA oversight of in vitro diagnostic devices and laboratory-developed tests shapes product labeling, analytical validation requirements, and market access timelines for US suppliers. EMA's In Vitro Diagnostic Regulation and ISO 13485 quality management standards govern CE-marked mix distribution across European clinical laboratories. Stakeholders must monitor how evolving companion diagnostic frameworks in the United States and European Union reshape specification requirements for multiplex and qPCR formulations.
Market Dynamics
Digital PCR technology is fragmenting the quantitative PCR landscape as cell therapy manufacturers demand absolute quantification over relative threshold methods, forcing reformulation of master mix stabilizers and enzyme architectures.
Growth Catalysts
- Laboratory-Developed Test Framework Evolution:FDA guidance updates are accelerating registration pathway clarity for multiplex assay developers in United States clinical laboratories.
- Cell Therapy Quality Control Mandates:CAR-T manufacturers in Germany require digital PCR absolute quantification for vector copy number validation, driving premium formulation consumption.
- Enzyme Manufacturing Backward Integration:Captive thermostable polymerase production is compressing raw material cost volatility for high-volume mix suppliers.
Market Restraints
- Magnesium Chloride Input Volatility:Pharmaceutical-grade MgCl2 supply concentrates among three specialty chemical producers, exposing formulation costs to commodity swings.
- ISO 13485 Certification Bottlenecks:European clinical laboratories face extended audit timelines for CE-marked mix procurement under EMA's In Vitro Diagnostic Regulation.
- Isothermal Amplification Substitution:LAMP and RPA technologies are capturing point-of-care infectious disease testing previously served by qPCR workflows.
Strategic Opportunities
- Companion Diagnostic Convergence:FDA and EMA parallel review pathways for oncology multiplex panels create specification standardization opportunities for assay developers.
- Automated Liquid Handler Integration:Pre-formulated master mixes optimized for Tecan and Hamilton robotics are opening high-throughput clinical laboratory contracts.
- India Research Cluster Expansion:Bangalore and Hyderabad biotech corridors are building molecular diagnostics capacity without entrenched supplier relationships.
Industry Challenges
- Trained Molecular Diagnostics Technician Scarcity:High-throughput clinical laboratories face unwinding capacity constraints as automated workflows outpace workforce development programs.
- Analytical Validation Documentation Burden:FDA pre-submission requirements for laboratory-developed tests extend product launch timelines by 8-14 months for novel multiplex formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR Master Mix Market |
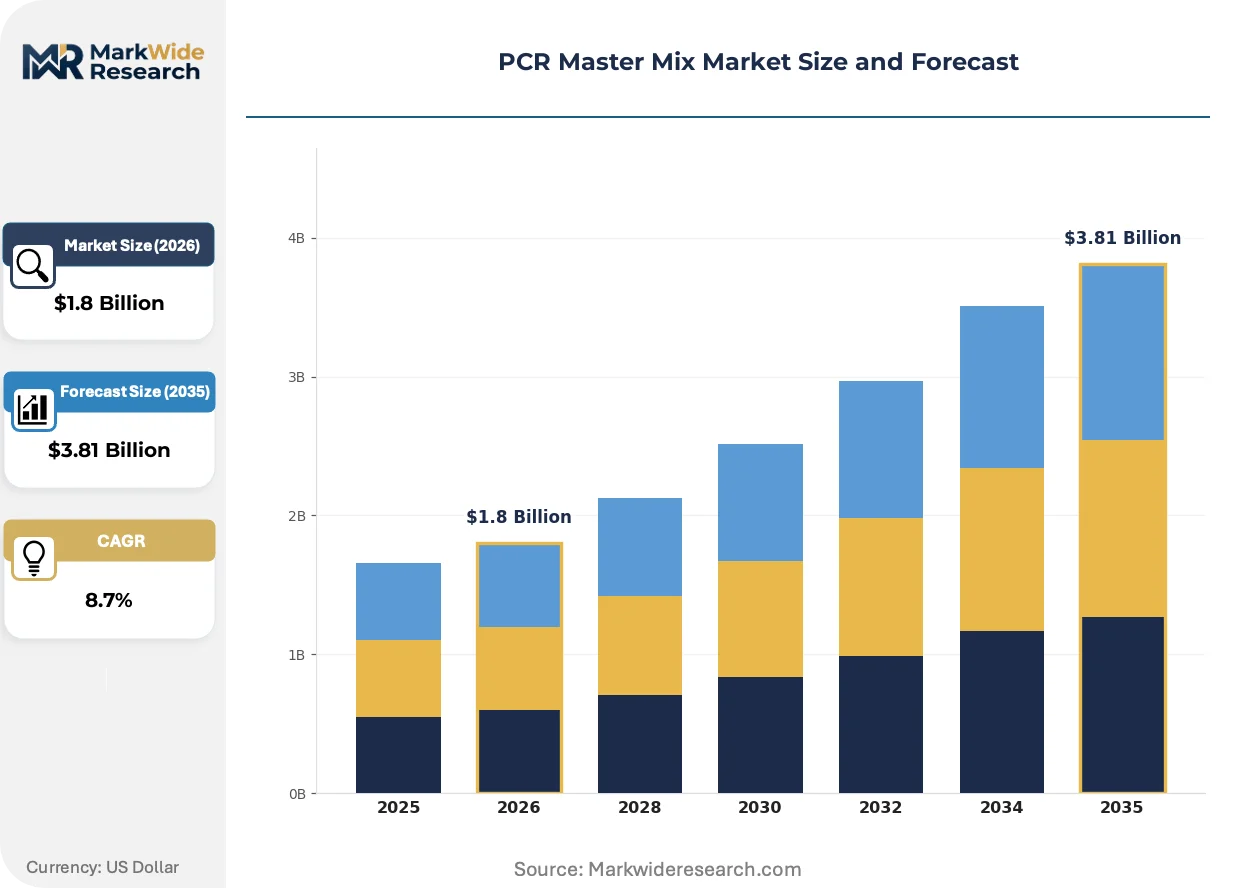
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Use Mixes, Concentrated Mixes, Custom Formulations, 2x Master Mixes End User: Academic Institutions, Pharmaceutical Companies, Clinical Laboratories, Biotechnology Firms Technology: qPCR, Digital PCR, Nested PCR, Multiplex PCR Application: Genetic Research, Disease Diagnostics, Forensic Analysis, Environmental Testing |
| Companies Covered | Qiagen, Bio-Rad, Thermo Fisher Scientific, Merck, New England Biolabs, Promega, Agilent, Takara Bio, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Master Mix Market Evolving Landscape
Reagent formulation architecture is undergoing compression as digital PCR absolute quantification demands displace relative Ct value workflows across cell therapy and liquid biopsy applications.
Lyophilized master mix formats are fragmenting cold-chain logistics requirements for distributed testing networks. Cell therapy quality control laboratories in Massachusetts and North Carolina are adopting ambient-stable enzyme formulations to support decentralized manufacturing site validation. This stabilization chemistry is compressing freight costs and enabling same-day assay deployment to contract manufacturing organizations without controlled-temperature infrastructure.
EMA's In Vitro Diagnostic Regulation is tightening analytical validation documentation for CE-marked mix distribution across European clinical laboratories. Manufacturers must now submit extended stability data and traceability records for thermostable polymerase lots, extending registration timelines by four to six months. German academic medical centers are responding by consolidating procurement around suppliers with established notified body relationships.
Consolidated procurement contracts are compressing supplier fragmentation in United States hospital systems. Integrated delivery networks in Texas and California are unbundling reagent purchasing from instrumentation leases, forcing master mix suppliers to compete on standalone analytical performance rather than bundled pricing. This purchasing model shift is most visible in infectious disease testing volumes, where automated PCR workflow standardization demands interoperable formulation specifications across multiple instrument platforms.
PCR Master Mix Market Segmentation
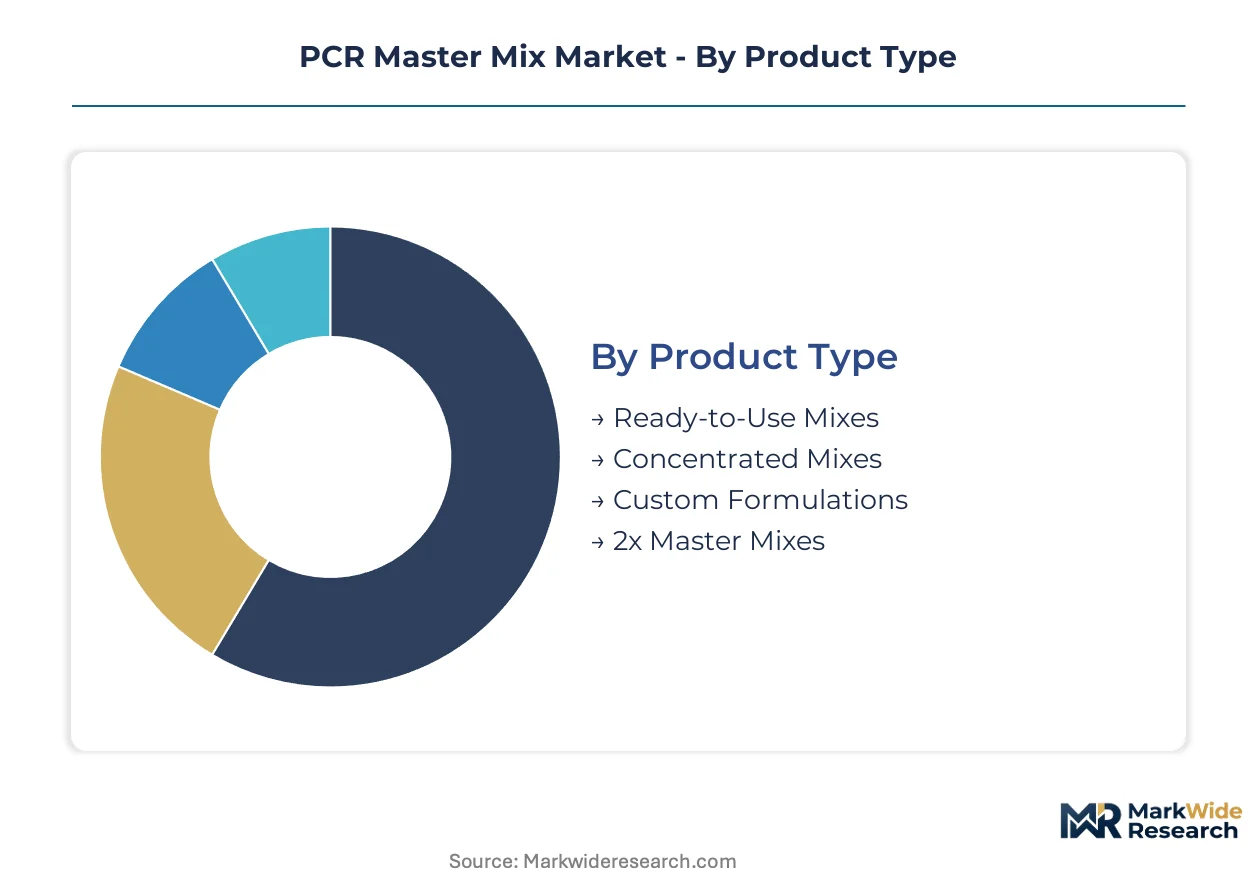
PCR master mix segmentation reflects divergent regulatory burdens across clinical and research environments. Formulation specifications, validation documentation, and quality management requirements fragment procurement patterns across end-use categories.
Product Type:
FDA premarket notification pathways and ISO 13485 certification tiers separate clinical-grade from research-use formulations.
- Ready-to-Use Mixes:Pre-formulated buffered solutions containing thermostable DNA polymerase, dNTPs, and stabilizers eliminate user pipetting errors. United States hospital systems and clinical laboratories specify these for infectious disease testing workflows where batch-to-batch consistency satisfies FDA analytical validation requirements.
- Custom Formulations:Proprietary buffer compositions and enzyme concentrations tailored to pharmaceutical assay panels command premium positioning. CAR-T manufacturers in Germany require vector copy number validation specifications that standard mixes cannot accommodate.
- Concentrated Mixes:Higher enzyme titers and flexible dilution protocols serve academic laboratories with variable throughput demands.
- 2x Master Mixes:Standardized concentration ratios streamline reaction assembly for high-throughput screening operations.
Established volume favors Ready-to-Use Mixes; emerging adoption favors Custom Formulations.
End User:
Procurement authority and quality management maturity shape supplier relationships across customer categories.
- Clinical Laboratories:Automated PCR workflow expansion in United States hospital systems drives standardization demands. Integrated delivery networks in Texas and California unbundle reagent purchasing from instrumentation leases, forcing standalone analytical performance competition.
- Pharmaceutical Companies:Companion diagnostic development and cell therapy quality control mandate digital PCR absolute quantification. Massachusetts and North Carolina manufacturing sites require ambient-stable formulations for decentralized validation.
- Academic Institutions:Research flexibility priorities and grant-funded procurement concentrate demand in Germany's academic medical centers.
- Biotechnology Firms:Early-stage molecular diagnostics developers in Bangalore and Hyderabad corridors build capacity without entrenched supplier relationships.
Procurement consolidation favors Clinical Laboratories; specification complexity favors Pharmaceutical Companies.
Technology:
Quantification methodology determines enzyme architecture and stabilizer chemistry requirements.
- Digital PCR:Absolute quantification replaces relative threshold methods, demanding reformulated master mix stabilizers for cell therapy vector copy number validation. Steepest expansion trajectory among all technology segments.
- qPCR:Relative Ct value workflows dominate infectious disease testing volumes with established regulatory pathways.
- Multiplex PCR:Simultaneous target amplification requires specialized buffer compositions for primer competition management.
- Nested PCR:Two-round amplification protocols retain niche positioning for rare mutation detection sensitivity.
Regulatory familiarity favors qPCR; analytical precision demands favor Digital PCR.
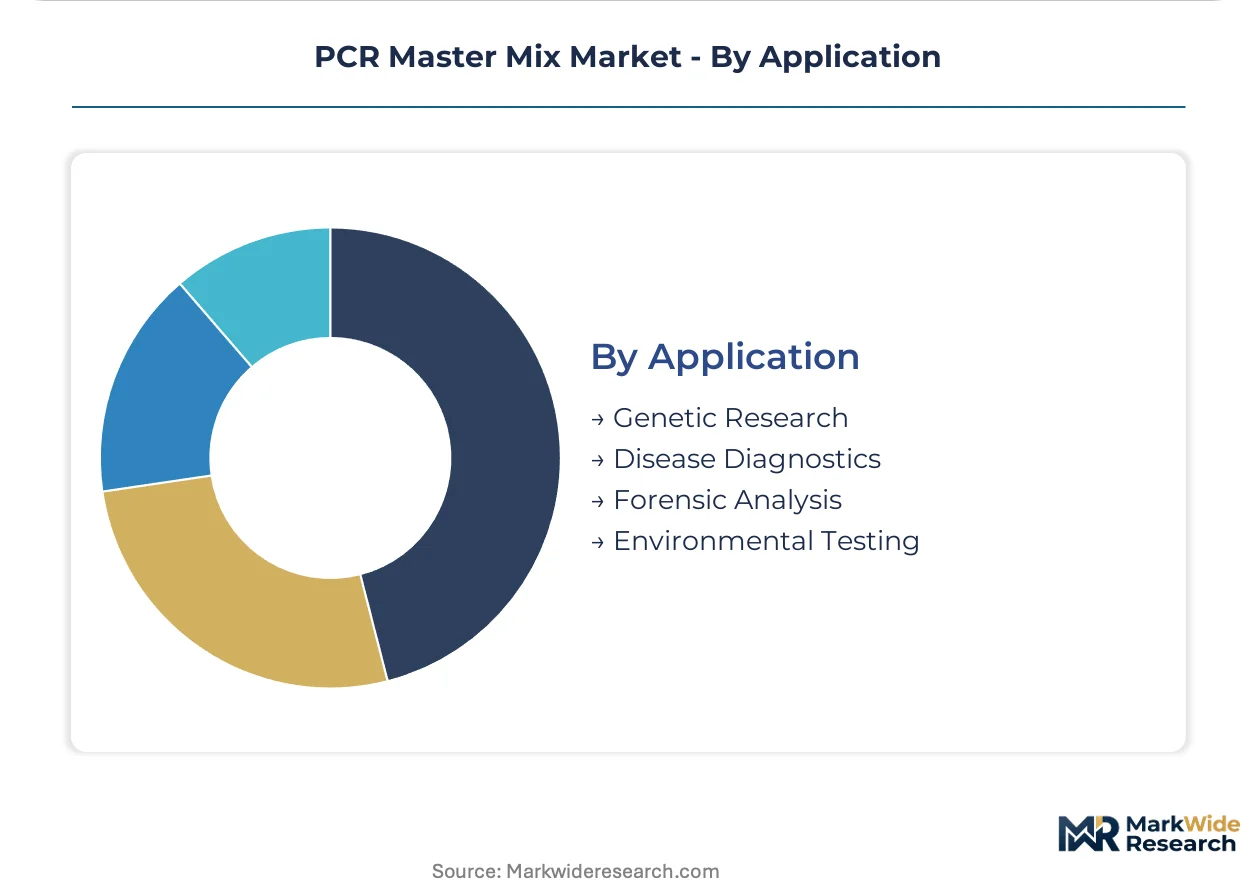
Application:
Sample type and result purpose determine formulation performance specifications.
- Disease Diagnostics:FDA-cleared infectious disease panels and laboratory-developed test frameworks require validated analytical performance. Rising testing volumes in United States clinical laboratories compress turnaround time requirements.
- Genetic Research:Exploratory assay development in academic settings tolerates broader performance variability for experimental flexibility.
- Forensic Analysis:Degraded DNA sample compatibility and chain-of-custody documentation shape procurement specifications.
- Environmental Testing:Field-deployable protocols favor lyophilized formats with ambient stability for distributed sampling networks.
Regulatory stringency favors Disease Diagnostics; methodological flexibility favors Genetic Research.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German clinical laboratories command premium pricing for validated formulations, while Indian research corridors compete on cost-sensitive procurement. This asymmetry fragments supplier margin structures across developed and emerging demand centers.
United States
Hospital system consolidation and automated PCR workflow expansion drive standardization mandates. FDA guidance updates on laboratory-developed tests compress registration timelines for multiplex assay developers. Texas and California integrated delivery networks unbundle reagent purchasing from instrumentation leases.
Germany
Academic medical centers and CAR-T manufacturers anchor European premium formulation consumption. EMA's In Vitro Diagnostic Regulation extends CE-marked mix audit timelines by four to six months. Munich and Heidelberg research clusters consolidate procurement around suppliers with established notified body relationships.
China
Domestic biopharma contract manufacturing expansion and molecular diagnostics infrastructure build-out accelerate import substitution. NMPA medical device registration pathways reshape analytical validation documentation requirements. Shanghai and Suzhou biotech corridors develop captive master mix production capacity.
India
Bangalore and Hyderabad molecular diagnostics startups build assay development capacity without entrenched supplier relationships. CDSCO medical device rules tighten quality management expectations for imported reagents. Research grant funding concentrates procurement flexibility in academic institutions.
Japan
Cell therapy quality control laboratories and precision medicine initiatives sustain digital PCR formulation demand. PMDA consultation frameworks guide companion diagnostic assay validation. Tokyo and Osaka pharmaceutical manufacturing sites require ambient-stable enzyme formulations for decentralized validation protocols.
PCR Master Mix Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the PCR master mix market. The vendor base stratifies into three tiers: multinational life science conglomerates with captive enzyme manufacturing, specialized reagent houses with formulation expertise, and regional distributors serving price-sensitive research markets. Dominant competitive moves include backward integration into thermostable polymerase production and strategic partnerships with automated liquid handler manufacturers.
Among diversified life science conglomerates, Thermo Fisher Scientific exemplifies scale-driven vertical integration, while Qiagen occupies a position bundling reagents with sample-to-insight workflows. Bio-Rad represents the technology leadership archetype through digital PCR specialization. These three anchors illustrate how competitive positioning fragments across cost structure control, workflow integration, and analytical platform leadership.
| Leading Market Players |
|---|
| Qiagen |
| Bio-Rad |
| Thermo Fisher Scientific |
| Merck |
| New England Biolabs |
| Promega |
| Agilent |
| Takara Bio |
| Roche |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with thermostable polymerase suppliers lock in both raw material access and cost visibility for high-volume mix manufacturers serving United States hospital systems. These arrangements insulate formulation costs from magnesium chloride commodity swings while exposing buyers to minimum volume commitments that strain working capital during demand plateaus.
Pricing Analysis
The customization-premium spread between proprietary CAR-T vector validation formulations and standard infectious disease testing mixes exceeds threefold across German academic medical centers. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification grade and analytical validation documentation depth. Cost compression in standard ready-to-use mixes intensifies as integrated delivery networks in Texas and California unbundle reagent purchasing from instrumentation leases. Biotechnology startups in Bangalore and Hyderabad corridors exhibit highest price sensitivity, while Massachusetts cell therapy manufacturers absorb premium positioning for ambient-stable enzyme architectures.
Supply Chain Analysis
Inventory buffers for pharmaceutical-grade magnesium chloride stretch to sixteen weeks across European formulation facilities, reflecting lead-time vulnerability from specialty chemical producers. Thermostable DNA polymerase manufacturing concentrates in the United States, Germany, and Japan, with dNTP synthesis anchored in South Korean and Chinese chemical hubs. Single-source vulnerability runs through three dominant MgCl2 suppliers exposed to energy cost volatility. Distribution runs through authorized distributors serving clinical laboratories alongside direct procurement channels for pharmaceutical quality control operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCR master mix procurement is shifting toward platform-agnostic formulations as automated liquid handler interoperability becomes the decisive purchasing criterion across United States integrated delivery networks.
For Market Incumbents: Compound defensive moats through captive thermostable polymerase production and pre-validated automation protocols that lock in high-throughput clinical laboratory contracts. Isothermal amplification substitution from LAMP and RPA technologies threatens qPCR infectious disease testing volumes. Backward integration into enzyme manufacturing secures margin control against raw material volatility. For New Entrants and Emerging Players: Technical support gaps in digital PCR assay development represent the most penetrable service layer where incumbents under-serve cell therapy quality control laboratories. Target ambient-stable formulation deployment to contract manufacturing organizations lacking cold-chain infrastructure. Build market presence through automated liquid handler integration partnerships before pursuing standalone analytical performance competition. For Investors and Strategic Acquirers: Regional formulation specialists with established notified body relationships and CE-marking expertise command acquisition premiums as EMA's In Vitro Diagnostic Regulation extends audit timelines. Long-term viability hinges on companion diagnostic convergence creating specification standardization opportunities across oncology multiplex panels. Watch FDA pre-submission pathway clarity for laboratory-developed tests as the decisive inflection signal for multiplex assay developer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Liquid Handler Integration | Tecan and Hamilton robotics optimization opens high-throughput clinical laboratory contracts in Texas and California. |
| Lyophilized Format Development | Ambient-stable enzyme architectures compress freight costs for decentralized cell therapy manufacturing validation. |
| Notified Body Relationship Investment | Established CE-marking expertise accelerates EMA In Vitro Diagnostic Regulation compliance for German procurement consolidation. |
| Digital PCR Stabilizer Reformulation | Absolute quantification chemistry captures CAR-T vector copy number validation demand in Massachusetts and North Carolina. |
| India Research Cluster Partnership | Bangalore and Hyderabad corridor access builds assay development relationships without entrenched supplier displacement costs. |
Research Methodology
Initial hypotheses were tested against primary input from molecular diagnostics laboratory directors, pharmaceutical quality control managers, reagent procurement officers at integrated delivery networks, and thermostable polymerase manufacturing engineers, then refined against FDA 510(k) filings, EMA CE-marking databases, ISO 13485 audit records, and automated liquid handler specification sheets. Bottom-up demand modeling from end-user procurement patterns was triangulated with top-down supply-side capacity assessments across enzyme manufacturing facilities.
Variance-decomposition across product type, end user category, quantification technology, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume trajectories weighted by pricing tier penetration. Cell therapy manufacturing expansion rates and laboratory-developed test framework evolution served as primary demand-side forecast inputs alongside isothermal amplification substitution risk parameters.
Forecasts assume regulatory continuity in FDA laboratory-developed test guidance and EMA In Vitro Diagnostic Regulation implementation; material policy shifts would require re-modeling registration pathway timelines and analytical validation documentation burdens. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Gel Column Agglutination Test System Market
Biotechnology Equipment
Global Viral RNA Extraction Kit Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Global Biological Safety Cabinets Market
Biotechnology Equipment
Laboratory Filtration Devices Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Cell Separation Bead Market