
 Upstream Bioprocessing Equipment Market | 2026-2036
Upstream Bioprocessing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Upstream Bioprocessing Equipment Market Analytics
Single-source to multi-source procurement is realigning capital deployment across biopharmaceutical supply chains. Thermo Fisher Scientific leverages its integrated life sciences platform to control upstream hardware and consumable workflows. Danaher Corporation anchors its position through precision measurement and filtration technologies bundled with bioprocessing automation. Sartorius AG specializes in single-use systems that reduce cross-contamination risk in multi-product facilities.
Upstream bioprocessing equipment encompasses vessels, sensors, and fluid-handling systems engineered to cultivate living cells or microorganisms under controlled temperature, pH, and dissolved-oxygen conditions, typically operating at scales from laboratory benchtop to industrial volumes exceeding 20,000 liters. This apparatus serves the foundational stage of biologics manufacturing where therapeutic proteins, viral vectors, or cellular materials propagate before downstream purification. Bioreactors command the largest installed base and replacement cycle revenue, while perfusion technology captures accelerating interest as continuous processing promises higher volumetric productivity than traditional fed-batch modes. Pharmaceutical companies represent the most concentrated buyer segment, though biotechnology firms now drive fastest growth in single-use and modular platform adoption.
The FDA enforces current Good Manufacturing Practice standards that dictate equipment qualification, process validation, and data integrity for commercial biologics production. EMA's Annex 1 revision on sterile manufacturing imposes enhanced containment and closed-system requirements that reshape bioreactor design specifications. China's NMPA accelerates biosimilar and innovative biologic approvals, pressuring domestic and multinational manufacturers to localize upstream capacity. Stakeholders must weigh regulatory divergence against platform standardization when configuring global manufacturing networks.
Market Dynamics
Continuous bioprocessing adoption is compressing batch cycle times and forcing equipment suppliers to redesign bioreactor architectures around perfusion-ready geometries rather than traditional fed-batch footprints.
Growth Catalysts
- EMA Annex 1 Revision:The updated sterile manufacturing guidelines mandate closed-system designs that eliminate open interventions, compelling facility upgrades across European biologics plants.
- Cell and Gene Therapy Manufacturing:Viral vector production for CAR-T therapies requires flexible single-use bioreactor configurations that accommodate low-volume, high-changeover production modes.
- China's NMPA Biosimilar Acceleration:Streamlined approval pathways for follow-on biologics are driving domestic capacity expansion in Shanghai and Suzhou bioclusters.
Market Restraints
- Stainless Steel Resin Pricing Volatility:Electropolished 316L vessel fabrication faces nickel alloy cost swings that distort capital project budgeting for large-scale mammalian cell culture facilities.
- Single-Use Film Supply Concentration:Three specialized polymer suppliers control fluoropolymer and TPE film grades for bioprocess bags, creating geographic chokepoints when regional logistics disrupt.
- Scale-Up Physics Constraints:Oxygen mass transfer limitations in conventional stirred-tank designs impose hard ceilings on cell density achievements beyond 50 million cells per milliliter.
Strategic Opportunities
- India's CDMO Capacity Buildout:Hyderabad and Bengaluru bioclusters lack indigenous upstream equipment fabrication, opening localization partnerships for modular bioreactor platforms.
- Digital Twin Convergence:Integration of computational fluid dynamics with real-time sensor telemetry enables predictive process control that reduces failed batch rates.
- US IRA Manufacturing Tax Credits:Domestic production incentives for active pharmaceutical ingredients extend to bioprocessing hardware, favoring capital deployment toward US-based assembly.
Industry Challenges
- Bioprocess Engineer Talent Scarcity:Perfusion operation and scale-down model development require specialized expertise that outpaces university program output.
- Legacy DCS Integration Friction:Brownfield facilities running 1990s-era distributed control systems face protocol incompatibilities with modern single-use sensor networks.
- Equipment Qualification Timeline Compression:Installation, operational, and performance qualification protocols for GMP bioreactors extend 12-18 months, delaying revenue-generating production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Upstream Bioprocessing Equipment Market |
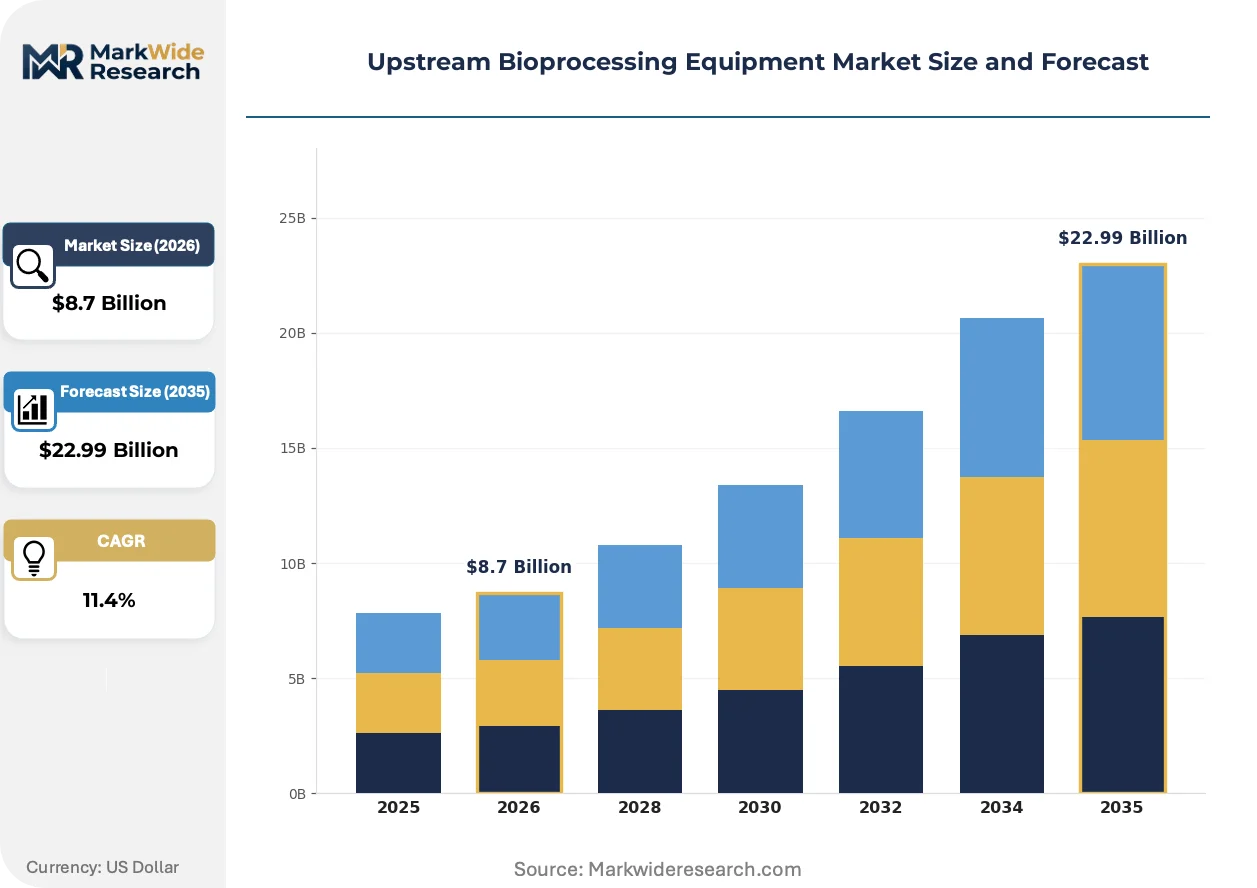
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioreactors, Fermenters, Cell Culture Systems, Disposable Bags Technology: Perfusion, Batch, Continuous, Fed-Batch End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Labs Application: Vaccine Production, Monoclonal Antibodies, Stem Cell Therapy, Gene Therapy |
| Companies Covered | Sartorius AG, Boehringer Ingelheim, Thermo Fisher Scientific, Corning, Eppendorf AG, Merck KGaA, GE Healthcare, Applikon Biotechnology, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Upstream Bioprocessing Equipment Market Evolving Landscape
Modular facility architectures are displacing monolithic cleanroom construction, allowing biopharmaceutical manufacturers to reconfigure production lines within weeks rather than years.
Single-use bioreactor technology is modularizing upstream manufacturing by decoupling vessel, sensor, and control unit procurement. Contract manufacturers now assemble production trains from interchangeable subsystems rather than purchasing integrated stainless steel suites. This modularity is compressing facility construction timelines and enabling multi-product facilities to switch therapeutic modalities within days.
EMA's Annex 1 revision on sterile manufacturing is forcing bioreactor suppliers to engineer fully closed sampling and transfer systems. The regulation eliminates manual interventions that previously introduced contamination risk during cell culture operations. European facilities are responding by retrofitting existing vessels with welded diaphragm valves and pre-sterilized fluid path assemblies.
CDMO procurement teams are consolidating vendor relationships around platform suppliers capable of delivering integrated hardware, consumables, and process analytics. This concentration is marginalizing point-solution providers lacking consumable recurring revenue streams. The shift is most visible in Massachusetts and North Carolina bioclusters where contract manufacturers prioritize supply chain simplification over best-of-breed component sourcing.
Upstream Bioprocessing Equipment Market Segmentation
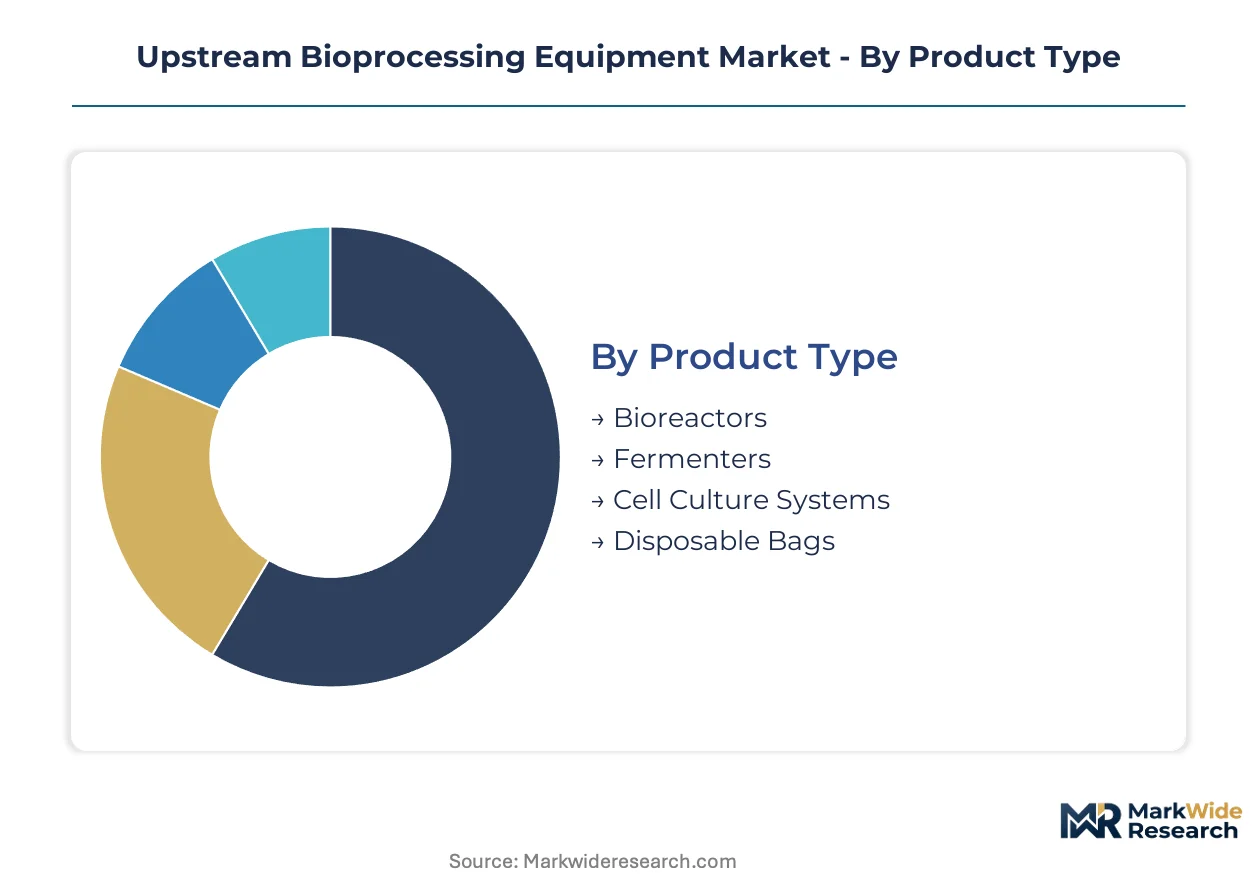
Upstream bioprocessing equipment segments around vessel architecture, operational modality, and therapeutic application. Procurement patterns diverge sharply between stainless steel facilities running blockbuster monoclonal antibodies and flexible single-use installations serving cell and gene therapy pipelines.
Product Type:
Buyers in this category separate by production scale and changeover frequency. Large-volume mammalian cell culture demands stainless steel durability, while multi-product CDMOs prioritize disposability to eliminate cleaning validation.
- Bioreactors:Stirred-tank vessels with agitation and sparging systems dominate commercial manufacturing. Pharmaceutical companies in the United States and Germany anchor replacement demand as legacy stainless steel units reach end-of-life cycles.
- Cell Culture Systems:Integrated platforms combine vessels with environmental controls and media handling. Biotechnology firms in Massachusetts and North Carolina bioclusters drive fastest adoption of modular configurations that compress facility buildout timelines.
- Fermenters:Microbial cultivation vessels engineered for bacterial and yeast propagation. Microbial expression systems for insulin and vaccine bulk production sustain demand across Indian and Chinese biosimilar manufacturers.
- Disposable Bags:Single-use film containers for media storage and harvest collection. Supply concentration among fluoropolymer film suppliers creates procurement risk during regional logistics disruptions.
Bioreactors lead volumes today; cell culture systems are gaining share fastest.
Technology:
Operational modality selection determines capital intensity and batch economics. Continuous processing promises higher volumetric productivity but demands sophisticated process control infrastructure.
- Perfusion:Continuous media exchange maintains cells in exponential growth phase. EMA's Annex 1 closed-system mandates accelerate European retrofit demand for perfusion-ready bioreactor geometries.
- Fed-Batch:Incremental nutrient feeding extends culture duration before harvest. This conventional approach retains installed base dominance across mature monoclonal antibody facilities.
- Continuous:Fully integrated upstream-downstream processing eliminates hold steps. Technical complexity and qualification burden limit current deployment to greenfield installations.
- Batch:Discrete culture cycles with complete harvest between runs. Legacy stainless steel facilities retain this mode where product changeover frequency remains low.
Fed-batch retains the largest installed base; perfusion is climbing the fastest.
End User:
Customer type dictates specification rigor and service intensity. Commercial manufacturers demand GMP-compliant qualification packages that extend procurement cycles.
- Pharmaceutical Companies:Integrated biologics manufacturers with captive production capacity. FDA current Good Manufacturing Practice enforcement drives equipment validation standards across their facility networks.
- Biotechnology Firms:Development-stage companies outsourcing manufacturing or building internal pilot plants. China's NMPA biosimilar acceleration pressures these firms to localize upstream capacity in Shanghai and Suzhou.
- Academic Institutions:University research programs advancing cell culture science. Limited capital budgets favor smaller-scale systems with flexible configuration options.
- Research Labs:Discovery-stage operations screening cell lines and media formulations. Benchtop bioreactor demand concentrates in Boston and San Diego bioclusters.
Pharmaceutical companies dominate current procurement; biotechnology firms show steepest expansion trajectory.
Application:
Therapeutic modality shapes bioreactor scale and containment requirements. Viral vector production imposes distinct design constraints compared to protein expression.
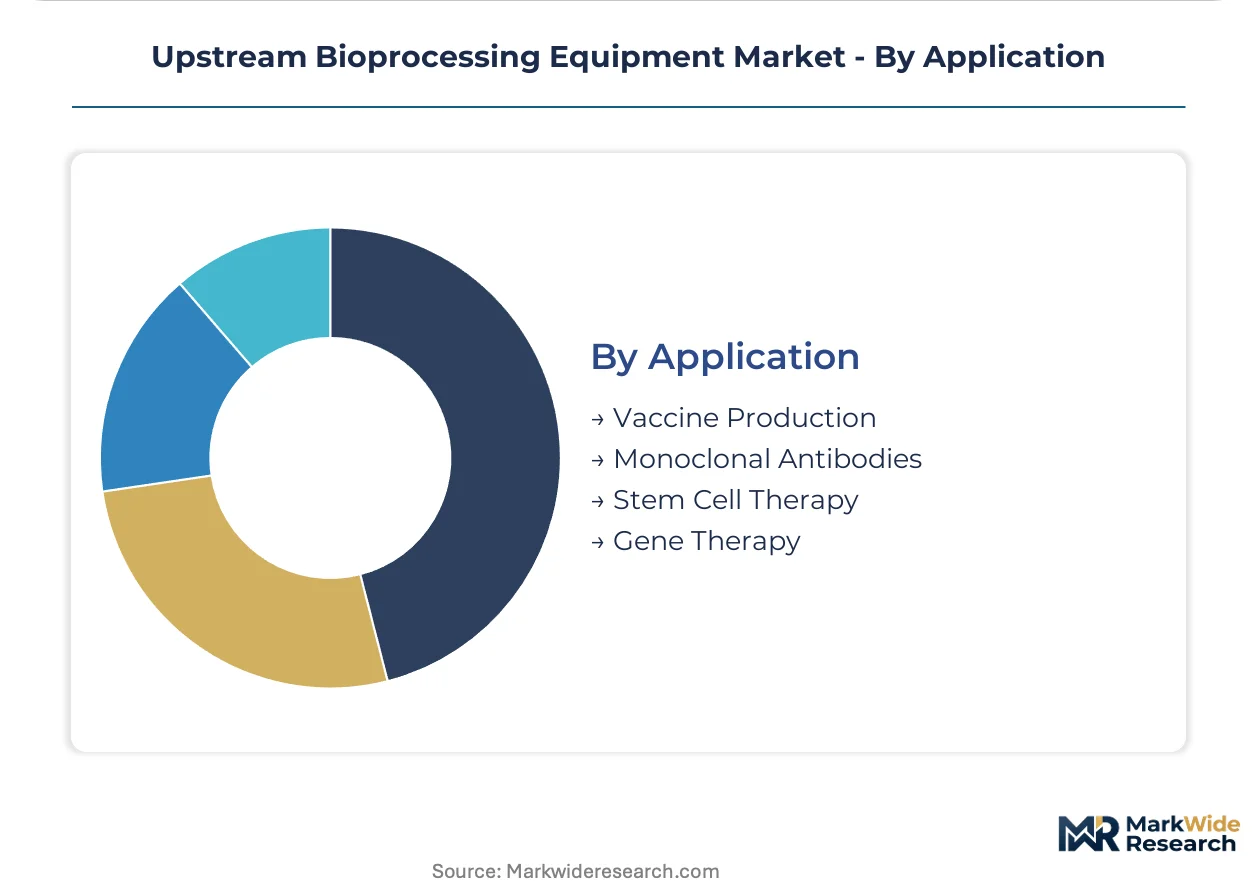
- Monoclonal Antibodies:Large-scale mammalian cell culture producing standardized therapeutic proteins. Fed-batch stainless steel systems retain dominance where production volumes exceed ten thousand liters.
- Gene Therapy:Viral vector manufacturing for AAV and lentiviral delivery systems. Single-use flexibility proves essential given frequent product switches and low-volume requirements.
- Vaccine Production:Both egg-based and cell culture platforms for infectious disease prophylaxis. Pandemic preparedness initiatives sustain strategic capacity reserves across multiple geographies.
- Stem Cell Therapy:Expansion of pluripotent and mesenchymal cell populations. Specialized closed-system bioreactors address sterility requirements for autologous and allogeneic products.
Monoclonal antibodies anchor current revenue; gene therapy is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts and North Carolina bioclusters anchor upstream equipment procurement intensity, with pharmaceutical manufacturers and CDMOs expanding single-use bioreactor capacity to serve cell therapy pipelines.
United States
FDA current Good Manufacturing Practice enforcement drives equipment validation standards across commercial biologics facilities. The Inflation Reduction Act manufacturing tax credits incentivize domestic upstream hardware assembly. Massachusetts bioclusters concentrate CDMO procurement teams consolidating vendor relationships around integrated platform suppliers.
Germany
EMA Annex 1 revision on sterile manufacturing mandates closed-system bioreactor designs eliminating open interventions. Precision measurement and filtration technology suppliers anchor positions through automation bundling. Bavaria and Baden-Württemberg host stainless steel fabrication expertise serving large-scale mammalian cell culture demand.
China
NMPA biosimilar approval acceleration pressures domestic and multinational manufacturers to localize upstream capacity. Dual carbon goals reshape energy-intensive stainless steel vessel production economics. Shanghai and Suzhou bioclusters deepen manufacturing infrastructure for innovative biologics and follow-on proteins.
India
CDSCO regulatory harmonization with ICH guidelines accelerates biologics facility commissioning timelines. Hyderabad and Bengaluru bioclusters lack indigenous upstream equipment fabrication, opening localization partnerships for modular bioreactor platforms. Domestic biosimilar manufacturers sustain fermenter demand for insulin and vaccine bulk production.
Switzerland
Swissmedic stringent GMP inspection protocols elevate equipment qualification requirements for commercial biologics production. Precision engineering traditions support sensor and control system specialization. Basel and Zurich regions concentrate biopharmaceutical headquarters driving captive upstream capacity investment.
Upstream Bioprocessing Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular single-use configurations and digital twin integration. The vendor base stratifies across integrated platform suppliers, point-solution specialists, and contract manufacturing organizations with captive equipment divisions. Diversified life sciences conglomerates and precision instrumentation groups represent dominant archetypes. Competitive dynamics center on strategic partnerships for consumable recurring revenue and geographic expansion into underserved bioclusters.
Among diversified platform suppliers, Thermo Fisher Scientific and Danaher Corporation exemplify integrated hardware-consumable-automation positioning. Sartorius AG occupies a specialist tier representing single-use system concentration. These three anchors illustrate the competitive tension between breadth and depth: conglomerates leverage cross-selling infrastructure while specialists command premium positioning in contamination-sensitive multi-product facilities.
| Leading Market Players |
|---|
| Sartorius AG |
| Boehringer Ingelheim |
| Thermo Fisher Scientific |
| Corning |
| Eppendorf AG |
| Merck KGaA |
| GE Healthcare |
| Applikon Biotechnology |
| Danaher Corporation |
| Others |
Value Network & Pricing Analysis
China's dual carbon goals gate qualified supply and premium-tier pricing access for electropolished 316L vessel fabrication, as energy-intensive stainless steel production faces escalating compliance costs that filter through to bioreactor capital expenditure budgets.
Pricing Analysis
Input-cost pass-through from nickel alloy volatility shapes three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on GMP certification tier and volume scale, with FDA-validated systems commanding substantial premiums over laboratory-grade configurations. Cost compression in standard-tier stirred-tank vessels is intensifying because Chinese biosimilar manufacturers prioritize capital efficiency over feature depth. Academic institutions and early-stage biotechnology firms exhibit highest price sensitivity, while commercial pharmaceutical manufacturers prioritize qualification reliability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for fluoropolymer film grades across Germany, the United States, and Japan. Raw material dependencies center on nickel alloys for vessel fabrication, specialized TPE polymers for single-use bags, and precision sensors for dissolved-oxygen monitoring. Single-source vulnerability concentrates in fluoropolymer resin supply, where regional logistics disruptions propagate procurement delays. Distribution runs through integrated platform suppliers bundling hardware, consumables, and automation rather than point-solution component vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EMA Annex 1 compliance costs in Germany diverge sharply from India's CDSCO harmonization timelines, creating cost-structure differentials for multi-regional facility networks.
For Market Incumbents: Cement platform stickiness through captive consumable recurring revenue and embedded process analytics. Threat from modular single-use specialists demands backward integration into fluoropolymer film production to secure supply continuity. Capacity addition in India's Hyderabad and Bengaluru bioclusters captures CDMO localization demand before indigenous fabrication emerges. For New Entrants and Emerging Players: Academic research labs represent an underserved buyer archetype currently marginalizing point-solution providers lacking flexible benchtop configurations. India's modular bioreactor platform shortage offers the most penetrable geography for partnership-based market entry. A go-to-market angle emphasizing rapid qualification protocols and interchangeable subsystem compatibility bypasses incumbent integration advantages. For Investors and Strategic Acquirers: Roll-up economics work for precision sensor and control system specialists because EMA's closed-system mandates are fragmenting vendor relationships across European facilities. Long-term viability centers on consumable attachment rates rather than hardware replacement cycles. The signal to watch is CDMO procurement team consolidation velocity around integrated platform suppliers in Massachusetts and North Carolina bioclusters.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion-Ready Bioreactor Retrofit | EMA Annex 1 mandates accelerate European facility upgrade cycles for closed-system geometries. |
| Fluoropolymer Film Backward Integration | Captive resin supply insulates margins against nickel alloy and polymer feedstock volatility. |
| Digital Twin Platform Integration | CFD-sensor telemetry convergence reduces failed batch rates for continuous processing adopters. |
| India CDMO Localization Partnership | Hyderabad and Bengaluru bioclusters lack indigenous fabrication, opening modular platform deployment. |
| Single-Use Sensor Network Standardization | Protocol harmonization resolves legacy DCS friction in 1990s-era brownfield facility retrofits. |
Research Methodology
Direct dialogue with bioprocess engineers, CDMO procurement directors, regulatory affairs specialists, and stainless steel fabrication plant managers grounded this analysis in operational reality. Secondary validation drew from FDA warning letter databases, EMA Annex 1 revision comment filings, NMPA biosimilar approval records, and SEC 10-K equipment supplier disclosures. Bottom-up equipment shipment tracking and top-down biologics capacity expansion modeling were triangulated against primary interview findings.
Segment-level value outputs across the analysis window reflect vessel architecture, operational modality, therapeutic application, and regional regulatory cluster dimensions. CAGRs were derived from installed base replacement cycles, greenfield facility commissioning timelines, and technology transition elasticity coefficients. Forecast inputs incorporated perfusion adoption curves, single-use penetration rates by therapeutic modality, and CDMO vendor consolidation velocity indices.
Underlying measurement precision varies by segment; stainless steel bioreactor replacement demand carries tighter precision than emerging perfusion technology forecasts. Projections reflect assumptions around regulatory timeline adherence, supply chain disruption frequency, and cell and gene therapy pipeline advancement. Deviation in China's NMPA biosimilar approval velocity or EMA Annex 1 enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Global Transfection Technologies Market
Biotechnology Equipment
Global Cell Culture Sampling Device Market
Biotechnology Equipment
Botanical Extraction Equipment Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Gel Column Agglutination Test System Market
Biotechnology Equipment
Biotechnology Instrumentation Market
Biotechnology Equipment
Cell Proliferation Kit Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Cryogenic Vial Rack Market