
 Global Lab Automation in Protein Engineering Market | 2026-2036
Global Lab Automation in Protein Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lab Automation in Protein Engineering Market Intelligence
The EU Green Deal's push for sustainable biomanufacturing is expanding the addressable market for energy-efficient automation platforms. Thermo Fisher Scientific leverages its end-to-end instrumentation portfolio to anchor large-scale protein production workflows. Danaher competes through its life sciences conglomerate structure, while Tecan Group specializes in precision liquid handling modules that integrate with third-party robotic ecosystems.
Lab automation in protein engineering encompasses integrated hardware-software systems that execute repetitive sample preparation, screening, and analytical tasks with throughput rates exceeding thousands of variants per day. These platforms rely on robotic arms with sub-millimeter positional accuracy and microplate readers capable of detecting fluorescence, luminescence, and absorbance across 384- and 1536-well formats to accelerate enzyme design and antibody engineering cycles. Liquid handling systems capture the largest installed base due to their ubiquity across every workflow stage, while high-throughput screening technology commands premium pricing because it directly compresses discovery timelines for biopharmaceutical clients. Antibody engineering applications are absorbing disproportionate capital as monoclonal and bispecific programs multiply across contract research organizations and biotech startups.
FDA quality-by-design mandates and EMA's good manufacturing practice standards for biologics both enforce process analytical technology integration, which compels labs to adopt automated data-capture architectures. ISO 13485 and IEC 61010-1 certifications further gate market access for instrument vendors serving diagnostic laboratories and regulated biopharmaceutical manufacturing. Stakeholders must weigh the capital intensity of full-workflow automation against modular point solutions as pipeline portfolios shift between small-molecule biologics and cell-engineering modalities.
Market Dynamics
FDA quality-by-design mandates for biologics manufacturing are forcing protein engineering labs to retrofit legacy workflows with closed-loop automation architectures that integrate process analytical technology. This regulatory compression is restructuring capital allocation across instrument categories and vendor relationships.
Growth Catalysts
- EMA Good Manufacturing Practice Standards:European biopharmaceutical manufacturers must deploy automated data-capture systems to satisfy batch-release documentation requirements, expanding the addressable base for integrated platforms.
- Antibody Engineering Pipelines:Contract research organizations and biotech startups are multiplying monoclonal and bispecific programs, creating sustained pull for high-throughput screening modules.
- Boston-San Diego Infrastructure Density:United States protein engineering clusters concentrate purchasing power and accelerate technology diffusion through proximity-based knowledge spillovers.
Market Restraints
- Precision Optics Supply Concentration:German and Japanese suppliers dominate laser and detector components for microplate readers, exposing buyers to extended lead times and currency volatility.
- ISO 13485 Certification Burden:Diagnostic laboratory instrument vendors face 12-18 month compliance timelines that delay market entry and freeze development roadmaps.
- Manual Pipetting Substitution:Low-complexity academic labs continue using handheld multichannel pipettes for sub-hundred variant workflows, capping penetration in price-sensitive segments.
Strategic Opportunities
- India Biologics Manufacturing Expansion:CDSCO's streamlined biologics approval pathways and production-linked incentive schemes are attracting greenfield automated facility investments.
- Cell Engineering Modality Convergence:CRISPR-edited cell therapy workflows require protein engineering automation adapted for adherent culture formats, opening adjacent hardware categories.
- EU Green Deal Energy Efficiency Mandates:Sustainable biomanufacturing incentives favor automation platforms with reduced consumable waste and lower per-run energy profiles.
Industry Challenges
- Mechatronics Talent Scarcity:Protein engineering labs struggle to hire automation engineers capable of programming robotic arms with sub-millimeter positional accuracy.
- Legacy LIMS Integration Friction:Established laboratory information management systems lack native APIs for modern cloud-based automation control software, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lab Automation in Protein Engineering Market |
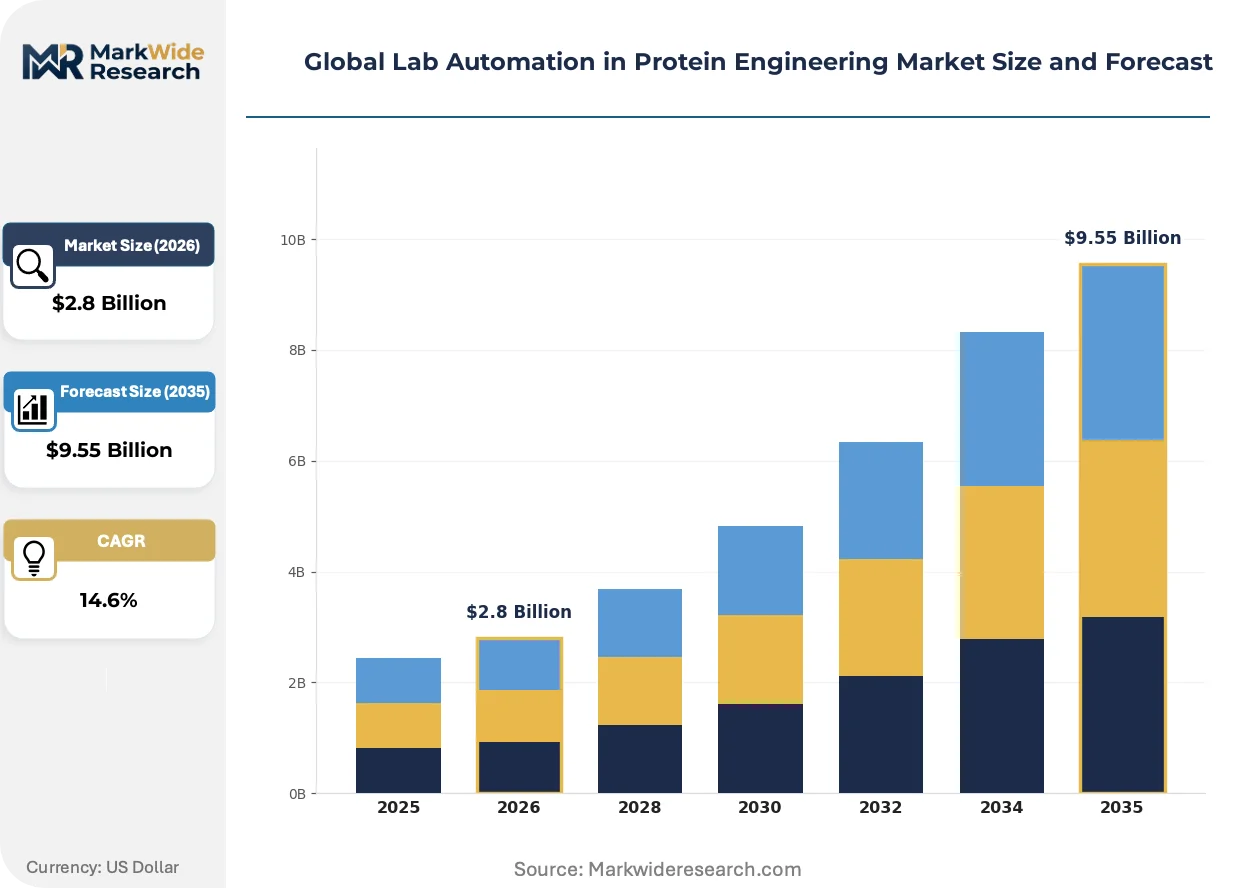
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Handling Systems, Microplate Readers, Automated Pipetting Systems, Robotic Arms, DNA Synthesizers Technology: Mass Spectrometry, High-Throughput Screening, Chromatography, Electrophoresis, Spectrophotometry Application: Enzyme Design, Antibody Engineering, Protein Folding Studies, Peptide Synthesis, Molecular Modeling End User: Biopharmaceutical Firms, Academic Research Institutes, Contract Research Organizations, Biotech Startups, Diagnostic Laboratories |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, PerkinElmer, Danaher, Roche Holding AG, Tecan Group, Hudson Robotics, Synchron Lab Automation, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lab Automation in Protein Engineering Market Strategic Shifts & Innovations
Acoustic liquid handling is displacing traditional pipetting across high-value protein engineering workflows, while regulatory data integrity requirements and buyer consolidation are reshaping how automation platforms are procured and serviced.
Acoustic droplet ejection technology is overtaking contact-based liquid handling in antibody discovery workflows. Biopharmaceutical screening groups are adopting non-contact dispensers to eliminate cross-contamination risks in precious protein libraries. The technology is overtaking legacy pipetting in 1536-well format applications where nanoliter accuracy determines hit identification rates.
EU AI Act risk classification rules are redefining software validation burdens for machine-learning-guided protein design platforms. Automated systems incorporating predictive algorithms now face enhanced documentation and human-oversight requirements. European contract research organizations are responding by segregating AI-enabled screening modules from standard automation workflows to isolate compliance scope.
Consolidated biopharmaceutical procurement functions are unbundling automation service contracts from hardware purchases. Large-cap buyers now negotiate predictive maintenance and reagent supply agreements through separate vendor relationships rather than bundled OEM packages. This pattern is most pronounced in United States coastal clusters where dedicated automation operations teams manage multi-site instrument fleets.
Global Lab Automation in Protein Engineering Market Segmentation
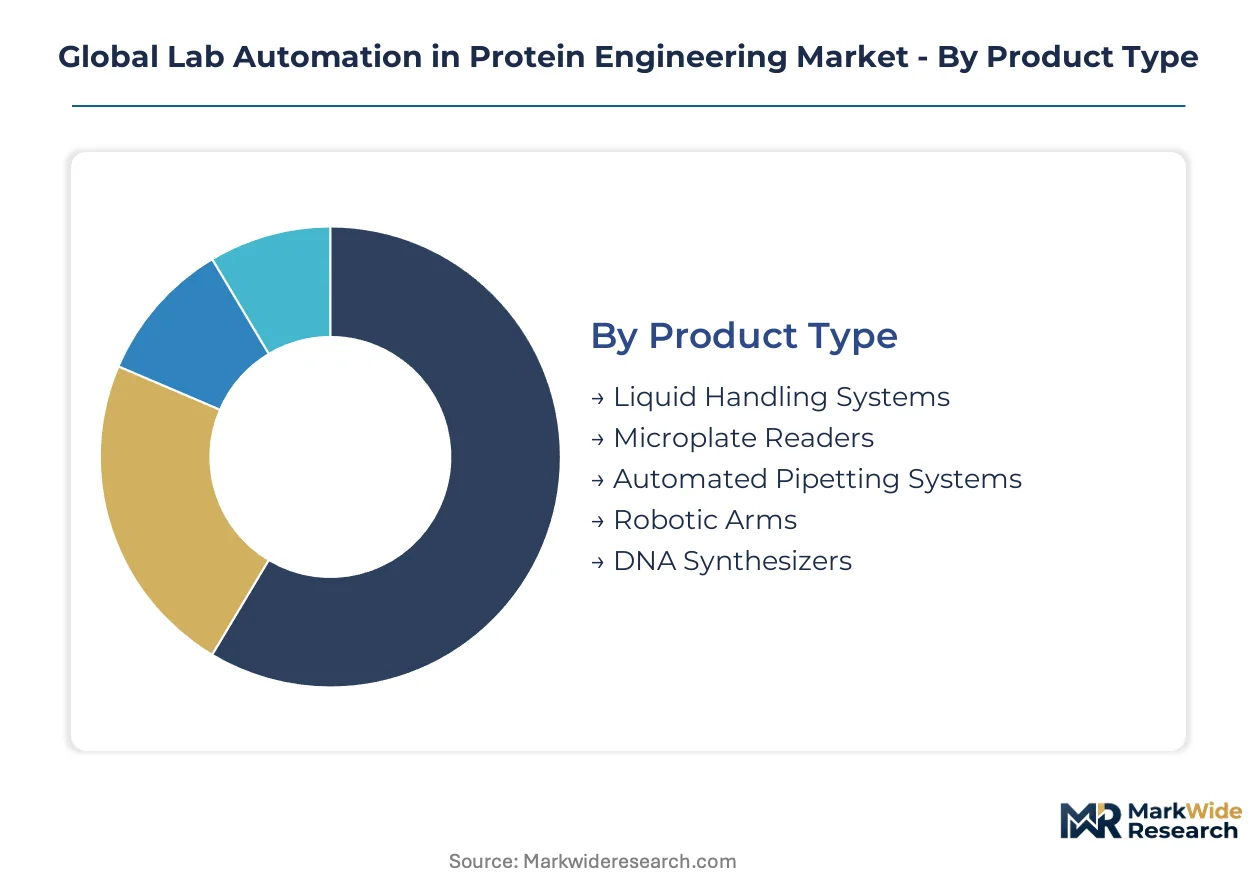
Segmentation in lab automation for protein engineering reveals how purchasing decisions split between workflow-integrated platforms and modular point solutions. Equipment selection tracks directly against pipeline complexity, regulatory exposure, and capital deployment timelines across biopharmaceutical and research settings.
Product Type:
Purchasing committees prioritize interoperability with existing robotic ecosystems and LIMS architectures when evaluating hardware categories.
- Liquid Handling Systems:These platforms execute nanoliter-to-milliliter transfers across 384- and 1536-well formats with sub-microliter precision. Biopharmaceutical firms in the United States deploy these most intensively for antibody library screening where throughput directly compresses discovery timelines. Acoustic droplet ejection variants are displacing contact-based pipetting in high-value workflows.
- Microplate Readers:Detection modules capture fluorescence, luminescence, and absorbance signals across high-density plates. Demand concentrates in Boston and San Diego clusters where contract research organizations run 24-hour screening operations. FDA process analytical technology mandates are forcing upgrades to readers with embedded data-integrity features.
- Automated Pipetting Systems:Mid-tier workstations bridge manual and fully automated workflows for academic labs.
- Robotic Arms:Cartesian and articulated configurations provide sub-millimeter positional accuracy for plate manipulation.
- DNA Synthesizers:Solid-phase oligonucleotide production supports gene library construction for directed evolution campaigns.
Liquid handling systems lead on scale; microplate readers lead on momentum.
Technology:
Technology selection reflects the analytical resolution required for specific protein characterization tasks versus throughput economics.
- Mass Spectrometry:High-resolution protein identification and post-translational modification mapping. Biopharmaceutical quality control labs in Germany and Switzerland deploy these for batch-release documentation under EMA good manufacturing practice standards. Orbitrap and time-of-flight configurations dominate biologics characterization.
- High-Throughput Screening:Parallel assay execution across thousands of protein variants daily. Antibody engineering pipelines at United States biotech startups absorb disproportionate capital here as monoclonal and bispecific programs multiply. Platforms integrate liquid handling, detection, and data capture in closed-loop architectures.
- Chromatography:Separation-based purification and analytical methods for protein quality assessment.
- Electrophoresis:Gel and capillary formats for molecular weight verification and purity analysis.
- Spectrophotometry:UV-Vis quantification of protein concentration and aggregation state.
High-throughput screening commands premium positioning; mass spectrometry anchors regulatory compliance workflows.
Application:
Application segmentation tracks the biological question being addressed rather than the analytical method employed.
- Antibody Engineering:Monoclonal, bispecific, and multispecific therapeutic candidate optimization. Contract research organizations across the United States, United Kingdom, and Switzerland run dedicated automation lines for this application. FDA quality-by-design guidelines for biologics manufacturing mandate automated data capture throughout engineering cycles.
- Enzyme Design:Catalytic efficiency engineering for industrial biocatalysis and therapeutic applications. German and Dutch biomanufacturing clusters under EU Green Deal sustainable production mandates drive demand for energy-efficient automation platforms. Directed evolution workflows require integrated screening and selection modules.
- Protein Folding Studies:Thermodynamic and kinetic characterization of structural stability.
- Peptide Synthesis:Solid-phase and solution-phase production of therapeutic and research peptides.
- Molecular Modeling:Computational structure prediction paired with experimental validation.
Antibody engineering captures the largest capital allocation; enzyme design is expanding most quickly under sustainability mandates.
End User:
End-user segmentation determines pricing tolerance, service contract structure, and compliance documentation requirements.
- Biopharmaceutical Firms:Integrated, validated automation platforms for regulated therapeutic development. Large-cap buyers in the United States negotiate predictive maintenance and reagent supply through separate vendor relationships rather than bundled OEM packages. FDA and EMA compliance documentation drives preference for established instrument vendors with ISO 13485 certification.
- Contract Research Organizations:Flexible, multi-tenant automation infrastructure serving diverse client programs. Academic and biotech startup clients in Boston and San Diego proximity clusters accelerate technology diffusion through shared service models. These organizations absorb the steepest expansion trajectory as antibody pipeline outsourcing intensifies.
- Academic Research Institutes:Modular, price-sensitive configurations for exploratory science.
- Biotech Startups:Leased or shared-access automation to preserve capital for therapeutic development.
- Diagnostic Laboratories:ISO 13485-certified instruments with embedded quality control for clinical assay production.
Biopharmaceutical firms dominate absolute spending; contract research organizations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Protein engineering automation first achieved industrial scale in the United States during the 1990s biotech boom, with subsequent waves of instrumentation investment spreading to European pharmaceutical clusters and, more recently, Asian biomanufacturing hubs.
United States
FDA quality-by-design mandates for biologics manufacturing are accelerating retrofit investments in closed-loop automation architectures. The 21st Century Cures Act streamlined therapeutic development pathways, compressing timelines for antibody engineering programs. Boston and San Diego house the densest concentrations of protein engineering infrastructure, with contract research organizations operating 24-hour automated screening lines for monoclonal and bispecific therapeutic candidates.
Germany
EMA good manufacturing practice standards enforce automated data-capture systems for batch-release documentation, expanding demand for integrated platforms. The country's national pharmaceutical regulator maintains stringent process analytical technology requirements that favor established instrument vendors. The Rhine-Main and Munich clusters concentrate biopharmaceutical manufacturing automation, with particular emphasis on enzyme design workflows for industrial biocatalysis applications.
Switzerland
Swissmedic's alignment with international council for harmonisation standards reduces regulatory friction for exported biologics, attracting automated facility investments. Federal incentives for precision manufacturing support adoption of sub-millimeter accuracy robotic systems. The Basel region anchors European protein engineering automation, hosting major pharmaceutical headquarters that specify instrument standards across global supplier networks.
India
CDSCO streamlined biologics approval pathways and production-linked incentive schemes are attracting greenfield automated facility investments. The central government's biomanufacturing incentives favor energy-efficient automation platforms with reduced consumable waste profiles. Maharashtra and Karnataka are emerging as automated protein production centers, with contract development organizations scaling antibody engineering capacity for export markets.
United Kingdom
Post-Brexit alignment with EMA standards maintains automated data-integrity requirements for biologics manufacturing. The Medicines and Healthcare products Regulatory Agency enforces process analytical technology integration for domestic production. The Cambridge-Oxford-London triangle sustains concentrated automation investment, with academic-industry partnerships accelerating technology diffusion from research institutes to contract research organizations.
Global Lab Automation in Protein Engineering Market Key Industry Players
Premium-margin players sit above commodity-margin players across the certification-complexity spectrum, with ISO 13485-validated systems commanding sustained pricing power against unvalidated alternatives. The vendor base organizes into three tiers: diversified life sciences conglomerates with end-to-end portfolios, specialized liquid handling and detection module producers, and regional system integrators serving price-sensitive academic segments. Two dominant competitive moves are reshaping positioning: unbundling of service contracts from hardware purchases among large-cap biopharmaceutical buyers, and acoustic liquid handling technology displacing legacy contact-based pipetting in high-value screening workflows.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher occupy positions exemplifying the end-to-end instrumentation archetype, anchoring large-scale protein production workflows through comprehensive hardware-software integration. Tecan Group represents the specialized module tier, with precision liquid handling systems that integrate with third-party robotic ecosystems rather than requiring captive platform commitments. These three companies illustrate how competitive positioning splits between workflow-anchored breadth and interoperability-focused depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| PerkinElmer |
| Danaher |
| Roche Holding AG |
| Tecan Group |
| Hudson Robotics |
| Synchron Lab Automation |
| Beckman Coulter |
| Others |
Cost & Logistics Intelligence
Consolidated biopharmaceutical procurement functions in United States coastal clusters negotiate predictive maintenance and reagent supply through separate vendor relationships rather than bundled OEM packages, compressing margins for instrument vendors while elevating service pricing power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified systems for regulated biopharmaceutical manufacturing from modular academic configurations and refurbished secondary-market equipment. Price differentiation rests on certification burden and embedded data-integrity features demanded by FDA process analytical technology mandates. Cost compression in mid-tier liquid handling modules is intensifying because acoustic droplet ejection technology displaces legacy contact-based pipetting. Academic research institutes exhibit highest price sensitivity; large-cap biopharmaceutical firms absorb premium positioning for validated closed-loop architectures.
Supply Chain Analysis
Domestic-content mandates under India's production-linked incentive schemes and the EU Green Deal's sustainable sourcing requirements are reshaping component procurement for automation platforms. German and Japanese suppliers dominate precision laser and detector components for microplate readers, while United States vendors anchor robotic arm production and software architectures. Supply chain risk centers on single-source vulnerability for sub-millimeter positional accuracy encoders sourced from Japanese precision optics manufacturers. Distribution runs through direct OEM sales teams serving biopharmaceutical accounts and specialized life sciences distributors penetrating academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automation platform vendors can exploit geographic arbitrage between India's CDSCO streamlined approval pathways and the United States FDA's quality-by-design compliance costs, capturing margin expansion through lower regulatory friction while maintaining premium pricing in regulated markets.
For Market Incumbents: Hedge against acoustic liquid handling substitution by acquiring non-contact dispenser technology or licensing droplet ejection patents from specialized vendors. Strengthen backward integration into precision motion control components to reduce exposure to German and Japanese supplier concentration. Prioritize ISO 13485 certification maintenance as diagnostic laboratory instrument mandates tighten compliance timelines. For New Entrants and Emerging Players: Enter via India's Maharashtra and Karnataka biomanufacturing corridors where production-linked incentives subsidize greenfield automated facility investments and local procurement rules favor domestic system integrators. Target contract research organizations in Boston and San Diego proximity clusters seeking flexible, multi-tenant automation infrastructure for antibody engineering pipelines. Lead with interoperability-focused liquid handling modules that integrate with established Tecan and Hamilton robotic ecosystems rather than captive platform commitments. For Investors and Strategic Acquirers: Life sciences conglomerates with end-to-end instrumentation portfolios are the most active acquirers in this space, seeking precision liquid handling specialists to fill capability gaps. Long-term viability favors vendors with validated closed-loop architectures capable of satisfying EMA good manufacturing practice standards for batch-release documentation. Watch CDSCO approval velocity and United States coastal cluster CRO expansion rates as inflection indicators for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Liquid Handling Adoption | Non-contact dispensers eliminate cross-contamination risks in precious antibody libraries screened at United States biotech startups. |
| ISO 13485 Certification Investment | Diagnostic laboratory instrument vendors compress 12-18 month compliance timelines to accelerate market entry against unvalidated alternatives. |
| India Manufacturing Footprint Expansion | CDSCO streamlined pathways and production-linked incentives attract greenfield automated protein production facilities in Maharashtra. |
| Predictive Maintenance Unbundling | Large-cap biopharmaceutical buyers in Boston and San Diego negotiate service contracts separately from hardware purchases. |
| EU Green Deal Energy Efficiency Compliance | Sustainable biomanufacturing mandates favor automation platforms with reduced consumable waste and lower per-run energy profiles. |
Research Approach
Direct dialogue with protein engineering lab directors, automation operations managers at contract research organizations, regulatory affairs leads at biopharmaceutical firms, and precision instrumentation procurement specialists grounded qualitative findings. Secondary validation drew from FDA quality-by-design guidance documents, EMA good manufacturing practice standards, ISO 13485 certification records, and SEC filings of diversified life sciences conglomerates. Bottom-up and top-down triangulation cross-checked installed base estimates against capital expenditure disclosures and facility expansion announcements.
Bottom-up modeling aggregated segment-level demand across liquid handling systems, microplate readers, and high-throughput screening platforms by application, end user, and technology type. Top-down analysis calibrated aggregate market trajectory against biopharmaceutical R&D spending patterns and antibody pipeline outsourcing intensity. CAGRs were derived from regression analysis of historical capital deployment and projected regulatory compliance investments across the analysis window. Forecast inputs incorporated FDA process analytical technology mandate implementation timelines and CDSCO biologics approval pathway efficiency metrics.
The model holds under stable regulatory enforcement intensity and sustained biopharmaceutical outsourcing trends; deviation in United States FDA quality-by-design audit frequency or Indian production-linked incentive scheme modifications would shift capital allocation timing and vendor selection patterns. A small set of named triggers warrants ongoing watch: acoustic liquid handling patent litigation outcomes, German precision optics supplier consolidation, and EU AI Act risk classification enforcement against machine-learning-guided protein design platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
North America Life Science Tools Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Biosurgery Equipment Market