
 Tissue Processor Equipment Market | 2026-2036
Tissue Processor Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Processor Equipment Market Outlook
Equipment leasing and pay-per-use service contracts is fragmenting competitive dynamics in tissue processor equipment, lowering capital barriers for mid-sized pathology labs. Leica Biosystems leverages its integrated slide-to-digital workflow portfolio to anchor premium positioning across academic medical centers. Sakura Finetek sustains manufacturing scale advantages in rotary microtomy-adjacent processing systems. Thermo Fisher Scientific competes through its broad life sciences distribution network that extends reagent-to-instrument bundling.
Tissue processor equipment comprises automated and manual systems that fix, dehydrate, clear, and infiltrate tissue specimens with paraffin using controlled temperature cycles between 40°C and 65°C, enabling thin-section histopathological analysis for cancer diagnosis and research. Automated processors now dominate hospital procurement due to throughput demands exceeding 300 cassettes per day, while hybrid processors capture margin pools from labs transitioning from manual methods. Vacuum technology leads in diagnostic throughput applications, whereas computerized systems with barcode tracking represent the fastest-growing segment as laboratories integrate with laboratory information systems.
FDA 510(k) clearance requirements and CAP laboratory accreditation standards shape product development timelines and validation burdens for manufacturers seeking clinical-lab placement. ISO 13485 quality management certification operates as a baseline threshold for export competitiveness into European and Asian markets. Stakeholders must monitor evolving CLIA complexity requirements and digital pathology interoperability standards as these will determine which equipment platforms qualify for integrated diagnostic networks.
Market Dynamics
Hospital consolidation across the United States is compressing procurement timelines and forcing tissue processor vendors to reconfigure service models around centralized laboratory networks rather than standalone pathology departments.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for automated processors with predicate device equivalence are shortening product-to-market cycles for manufacturers targeting diagnostic lab expansion.
- Histopathology workforce shortages:Automated vacuum infiltration systems reduce technician touchpoints by 60-70% per cassette batch, compelling hospital administrators to replace manual methods.
- Paraffin embedding standardization:ISO 13485-certified processors gain preferential placement in European reference laboratories seeking harmonized quality documentation.
Market Restraints
- Capital equipment cyclicality:Rotary microtomy-adjacent processor replacements follow 7-10 year depreciation schedules, creating lumpy revenue recognition for manufacturers.
- Reagent supply concentration:Xylene and formalin procurement bottlenecks from Gulf Coast petrochemical corridors expose processors to input cost volatility.
- Technical interoperability gaps:Proprietary barcode tracking formats from incumbent vendors fragment laboratory information system integration efforts.
Strategic Opportunities
- India diagnostic infrastructure buildout:CDSCO medical device registration reforms and NABH accreditation expansion create first-mover positioning for automated processor vendors in tier-2 city hospital networks.
- Digital pathology convergence:Integration of tissue processing data streams with whole-slide imaging platforms enables predictive maintenance and throughput optimization algorithms.
- Equipment-as-service models:Pay-per-cassette contracts lower capital barriers for mid-sized pathology groups transitioning from manual to automated workflows.
Industry Challenges
- Histotechnologist certification bottlenecks:ASCP-credentialed technician shortages in the United States constrain operational scaling even where capital budgets exist.
- CLIA complexity escalation:Evolving proficiency testing requirements for high-complexity laboratories extend validation timelines for new processor installations by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Processor Equipment Market |
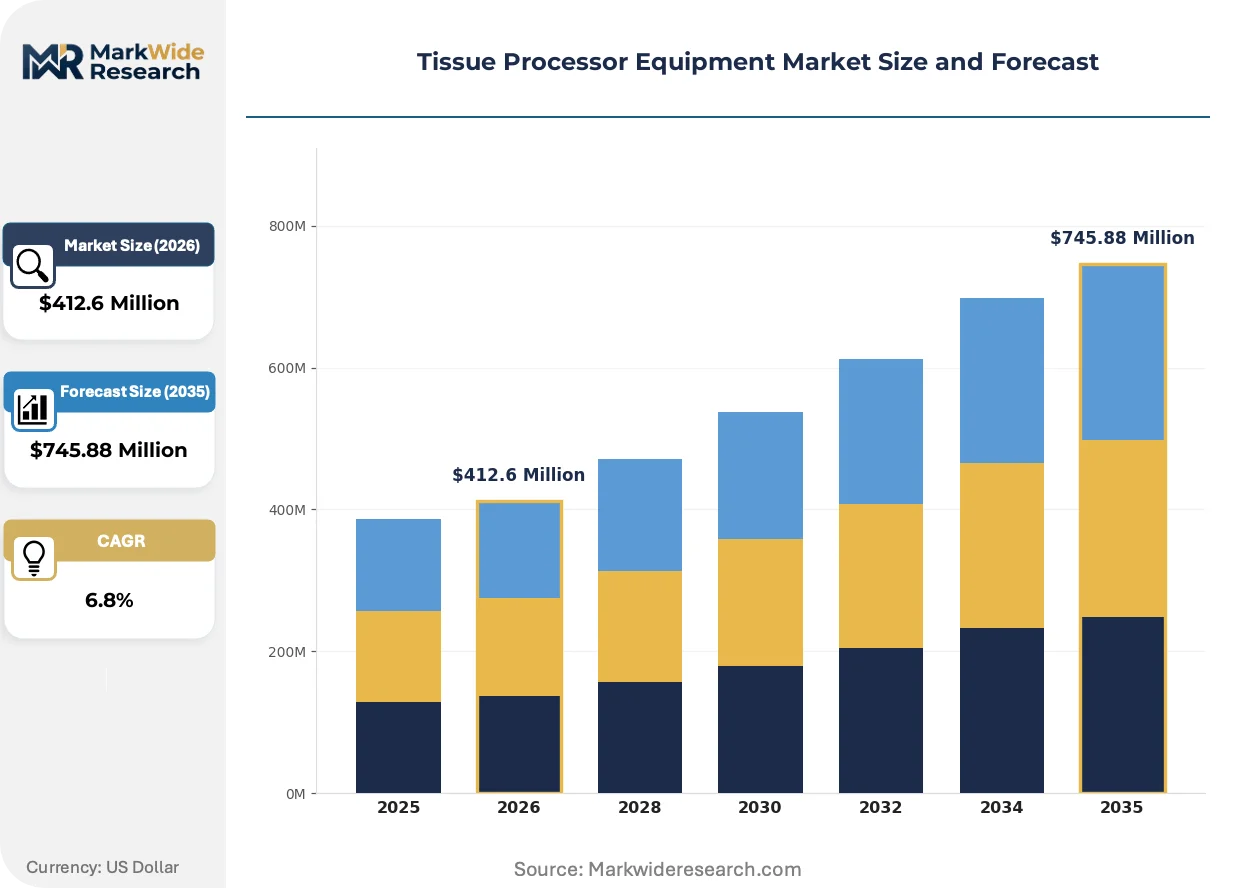
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Processors, Manual Processors, Hybrid Processors, Accessories End User: Hospitals, Diagnostic Labs, Research Institutes, Pathology Labs Technology: Vacuum Technology, Pressure Technology, Conventional Technology, Computerized Systems Application: Histopathology, Cytopathology, Forensic Analysis, Veterinary Diagnosis |
| Companies Covered | Leica Biosystems, Sakura Finetek, Epredia, Thermo Fisher Scientific, MEDITE Medical GmbH, Bio-Optica Milano, Milestone Srl, JOKOH, SLEE medical GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Processor Equipment Market Strategic Shifts
Workflow digitization is compressing the tissue-to-diagnosis continuum, with embedded sensors and cloud-connected processors enabling real-time quality monitoring that manual methods cannot replicate.
Radio-frequency identification tracking is digitizing cassette chain-of-custody documentation. Academic medical centers in Germany and the United States are deploying RFID-integrated processors to eliminate specimen misidentification errors. This technology is digitizing audit trail compliance, reducing CAP inspection preparation labor by automating documentation retrieval.
EU MDR Article 10 technical documentation requirements are mandating clinical evidence portfolios for tissue processor reclassifications. Manufacturers must now submit post-market surveillance data for devices previously grandfathered under MDD certificates. European notified bodies are backlogged 18-24 months, forcing vendors to prioritize MDR-ready submissions for vacuum infiltration systems over rotary models.
Consolidated purchasing organizations are disintermediating traditional distributor relationships. Large United States health systems now negotiate directly with manufacturers for enterprise-wide tissue processor fleets, bypassing regional laboratory supply intermediaries. This pattern concentrates price negotiation leverage among three to five national group purchasing organizations serving integrated delivery networks.
Tissue Processor Equipment Market Segmentation
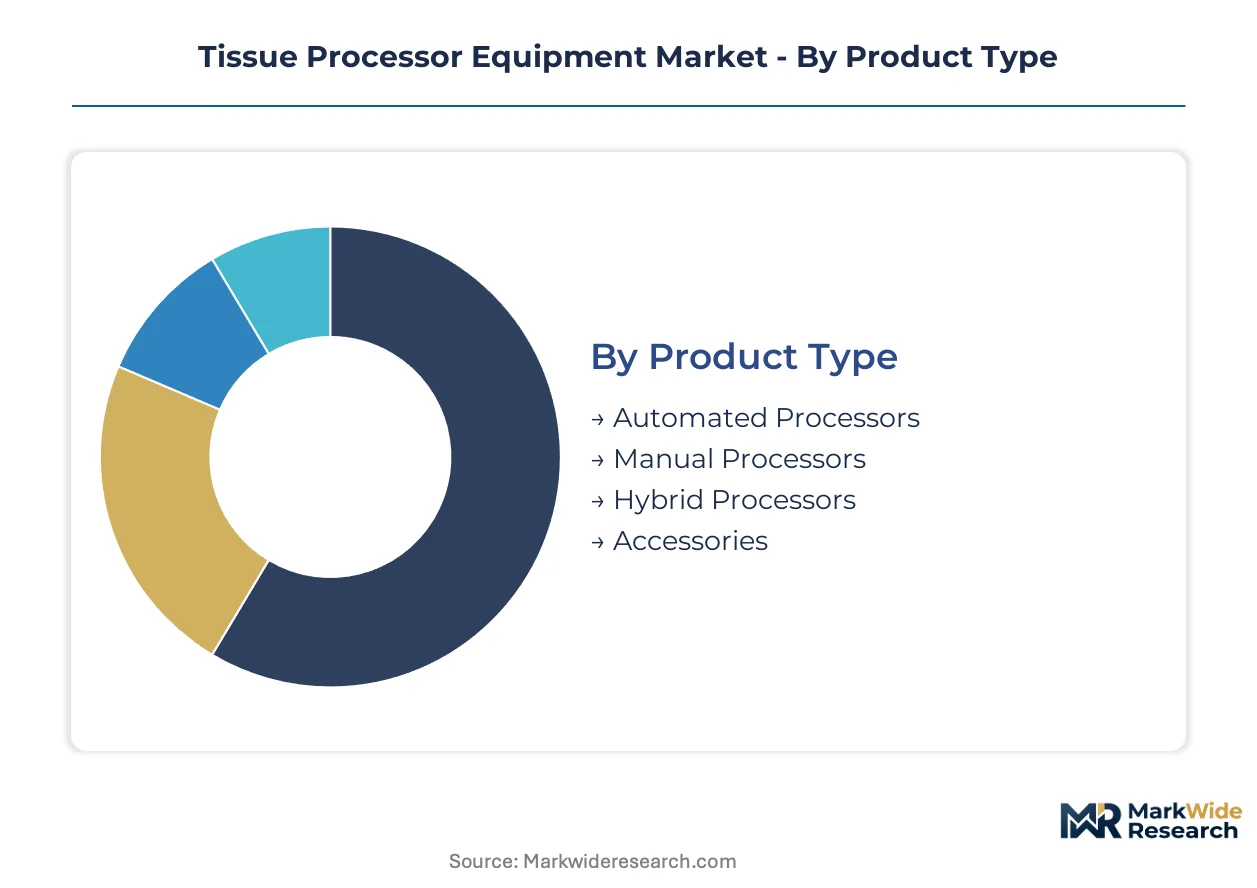
Tissue processor equipment segmentation reveals distinct replacement cadences across product categories. Automated systems cycle through 7-10 year depreciation schedules while consumables and accessories turn annually. Understanding these velocity differentials helps vendors align service contracts and inventory strategies with actual procurement rhythms.
Product Type:
Replacement cycles vary dramatically—accessories turn in months, automated platforms in years, and hybrid systems occupy a transitional middle ground.
- Automated Processors:Closed-system platforms execute fixation through paraffin infiltration with programmable temperature profiles between 40°C and 65°C. Hospital consolidation across the United States is compressing procurement timelines as centralized laboratories demand throughput exceeding 300 cassettes daily.
- Manual Processors:Benchtop units requiring technician oversight for each reagent exchange and temperature transition. Resource-constrained pathology labs in tier-2 Indian cities under CDSCO jurisdiction retain these systems where capital budgets remain restricted.
- Hybrid Processors:Semi-automated configurations allowing selective automation of dehydration or clearing stages while preserving manual control for specimen-sensitive protocols. Research institutes favor these for protocol flexibility during method validation studies.
- Accessories:Cassette baskets, reagent containers, and temperature probes subject to wear and chemical degradation. These generate recurring revenue streams with annual replacement rates.
Automated processors dominate installed base. Hybrid processors are where expansion concentrates.
End User:
Capital intensity and regulatory burden separate institutional buyers, with hospital networks deploying enterprise fleets while independent pathology groups pursue service-based acquisition models.
- Hospitals:Integrated delivery networks negotiate directly with manufacturers for multi-site tissue processor deployments. FDA 510(k) clearance and CAP accreditation requirements shape validation protocols for these high-complexity installations.
- Diagnostic Labs:Commercial reference laboratories processing outsourced histopathology specimens from multiple health systems. These facilities prioritize barcode tracking integration with laboratory information systems to manage chain-of-custody across high specimen volumes.
- Research Institutes:Academic medical centers requiring protocol flexibility for experimental fixation methods and specialized embedding media. Leica Biosystems anchors premium positioning here through integrated slide-to-digital workflow portfolios.
- Pathology Labs:Standalone facilities serving regional physician networks with focused cancer diagnostic services. Equipment-as-service contracts lower capital barriers for these mid-sized groups transitioning from manual methods.
Hospitals command procurement volume. Diagnostic labs are climbing the fastest.
Technology:
Performance tier and digital integration capability now separate technology categories more than fundamental processing chemistry.
- Vacuum Technology:Negative-pressure infiltration systems accelerating reagent penetration into dense tissue specimens. These dominate diagnostic throughput applications where batch consistency and shortened processing cycles justify premium positioning.
- Pressure Technology:Positive-pressure configurations for specialized applications requiring controlled force application during infiltration. Niche deployment in forensic analysis where bone and calcified specimens demand enhanced penetration mechanics.
- Conventional Technology:Gravity-dependent fluid exchange systems without active pressure or vacuum assistance. Declining share except in veterinary diagnosis and emerging market installations where simplicity outweighs speed requirements.
- Computerized Systems:Processor platforms with embedded barcode tracking, RFID integration, and cloud connectivity for real-time quality monitoring. These are gaining share fastest as laboratories pursue digital pathology convergence and predictive maintenance capabilities.
Vacuum technology holds installed base leadership. Computerized systems are where expansion concentrates.
Application:
Specimen type complexity and diagnostic urgency create divergent equipment requirements across clinical and non-clinical use cases.
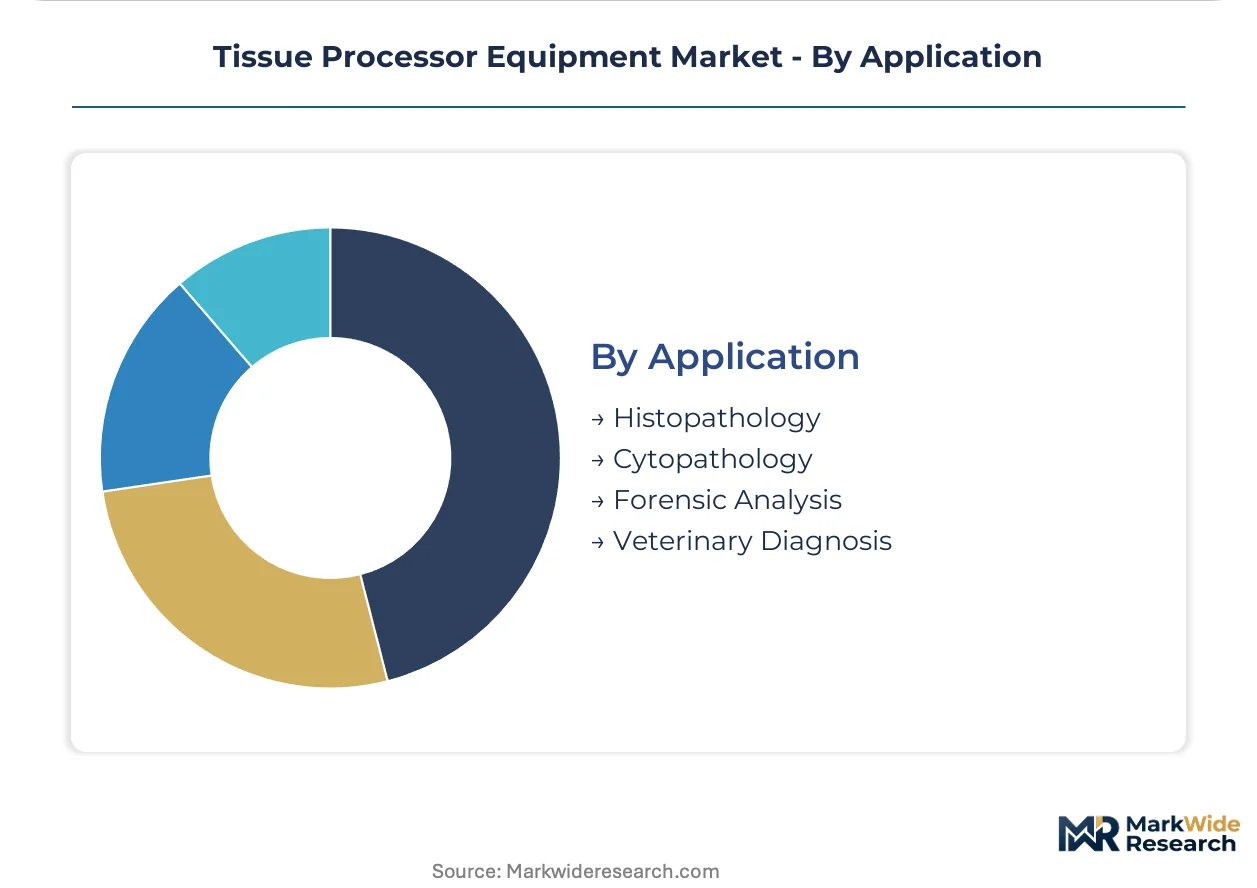
- Histopathology:Cancer diagnosis through thin-section analysis of fixed, dehydrated, cleared, and paraffin-embedded tissue. This application commands the largest equipment deployment due to standardized clinical demand and reimbursement stability.
- Cytopathology:Cell-based specimen processing for Pap smear evaluation and fluid cytology. Distinct workflow requirements including liquid-based preparation systems adjacent to traditional tissue processing infrastructure.
- Forensic Analysis:Post-mortem tissue examination requiring specialized protocols for decomposition-resistant fixation. Medical examiner offices prioritize chain-of-custody documentation and extended processing tolerance for compromised specimens.
- Veterinary Diagnosis:Companion animal and livestock pathology with lower throughput requirements and reduced regulatory validation burden. Manual processors retain meaningful share here due to cost sensitivity and specimen volume variability.
Histopathology anchors installed base. Cytopathology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in tissue processor equipment favor established manufacturing clusters in Germany, Japan, and the United States, while India and Brazil represent net import markets where domestic assembly capabilities remain underdeveloped. Trade flows concentrate in ISO 13485-certified units, with regulatory harmonization gaps creating friction in cross-border equipment validation.
United States
Hospital consolidation across integrated delivery networks is compressing procurement timelines for multi-site tissue processor deployments. FDA 510(k) clearance requirements and CAP laboratory accreditation standards shape validation protocols for high-complexity installations. The Greater Boston and Research Triangle Park clusters anchor academic medical center demand, where Leica Biosystems maintains premium positioning through integrated workflow portfolios.
Germany
EU MDR Article 10 technical documentation mandates are extending product reclassification timelines for vacuum infiltration systems. Notified body backlogs of 18-24 months are forcing manufacturers to prioritize MDR-ready submissions. The Baden-Württemberg industrial corridor concentrates precision engineering capabilities for rotary microtomy-adjacent processing equipment.
India
CDSCO medical device registration reforms and NABH accreditation expansion are accelerating automated processor adoption in tier-2 city hospital networks. PLI scheme incentives for domestic manufacturing remain below threshold for capital equipment localization. The Maharashtra-Gujarat pharmaceutical corridor generates concentrated demand from contract research organizations scaling histopathology infrastructure.
Japan
PMDA quality management requirements and JIS standards certification create elevated barriers for foreign equipment vendors. METI industrial policy prioritizes diagnostic infrastructure resilience through domestic supply chain reinforcement. The Kansai region around Osaka maintains specialized manufacturing capabilities for precision temperature control systems used in paraffin embedding workflows.
Brazil
ANVISA medical device registration pathways for automated processors remain protracted, extending market entry timelines for international manufacturers. Import dependency for advanced histopathology equipment persists due to limited domestic precision instrumentation capabilities. The São Paulo state health system drives procurement volume through centralized laboratory network consolidation.
Tissue Processor Equipment Market Competitive Environment
On the supply side, the industry is consolidating around integrated diagnostic workflow providers with full-stack histopathology portfolios. Three strategic archetypes dominate: precision engineering specialists with rotary microtomy heritage, life sciences conglomerates leveraging reagent-to-instrument bundling, and regional fabricators serving cost-constrained pathology labs. Competitive moves concentrate on M&A for digital pathology integration and service model reconfiguration toward equipment-as-service contracts.
Among precision engineering specialists, Leica Biosystems and Sakura Finetek exemplify contrasting scale positions within automated tissue processing. Leica Biosystems anchors premium-tier positioning through integrated slide-to-digital workflow portfolios across academic medical centers. Sakura Finetek occupies a manufacturing-scale archetype with rotary microtomy-adjacent processing system capabilities. Thermo Fisher Scientific represents the life sciences conglomerate model, competing through broad distribution networks that extend reagent-to-instrument bundling.
| Leading Market Players |
|---|
| Leica Biosystems |
| Sakura Finetek |
| Epredia |
| Thermo Fisher Scientific |
| MEDITE Medical GmbH |
| Bio-Optica Milano |
| Milestone Srl |
| JOKOH |
| SLEE medical GmbH |
| Others |
Value Chain & Pricing Dynamics
The Baden-Württemberg precision engineering corridor anchors European manufacturing capacity for rotary microtomy-adjacent processing systems, concentrating supply-side leverage among German and Japanese vendors. This geographic concentration amplifies pricing power for ISO 13485-certified platforms while compressing margins for manual processor segments facing reagent cost volatility from Gulf Coast petrochemical corridors.
Pricing Analysis
Hospital procurement committees anchor a three-tier pricing structure across premium, standard, and economy levels in tissue processor equipment. Price differentiation separates FDA 510(k)-cleared automated vacuum systems from CE-marked standard units and non-certified economy models for veterinary use. Pricing pressure stems from consolidated purchasing organizations negotiating enterprise-wide fleet contracts that disintermediate regional distributors. Mid-sized pathology labs exhibit highest price sensitivity, while academic medical centers prioritize workflow integration over unit cost.
Supply Chain Analysis
Contract manufacturing for precision temperature control assemblies concentrates in the Kansai region around Osaka and the Baden-Württemberg industrial corridor. Component sourcing draws from Germany for rotary microtomy mechanisms, Japan for thermal regulation systems, and the United States for embedded sensor modules. Single-source vulnerability persists in xylene and formalin reagent supply from Gulf Coast petrochemical clusters. Distribution runs through life sciences conglomerates bundling reagent-to-instrument portfolios alongside specialized histopathology distributors serving standalone pathology labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified histotechnologist scarcity constrains operational scaling even where hospital capital budgets permit automated processor deployment, creating a bottleneck that favors vendors with embedded training and service capabilities.
For Market Incumbents: Harden defensive positioning through backward integration into reagent supply chains and captive service technician certification programs. Consolidated purchasing organizations threaten margin compression through direct manufacturer negotiations, making ISO 13485 quality documentation and CAP accreditation support non-negotiable retention tools. Capacity addition in India's Maharashtra-Gujarat pharmaceutical corridor addresses emerging demand from contract research organizations scaling histopathology infrastructure. For New Entrants and Emerging Players: Build out equipment-as-service contract capabilities targeting mid-sized pathology labs in tier-2 Indian cities under CDSCO jurisdiction. Pathology labs transitioning from manual methods represent the most penetrable segment, with pay-per-cassette models lowering capital barriers. A go-to-market angle emphasizing barcode tracking integration with laboratory information systems differentiates against incumbent proprietary formats. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors computerized systems vendors with embedded RFID and cloud connectivity capabilities over conventional gravity-dependent platform manufacturers. Long-term viability hinges on digital pathology convergence, where processing data streams integrate with whole-slide imaging platforms. The signal to watch is FDA 510(k) clearance velocity for predictive maintenance algorithms, indicating which equipment platforms qualify for integrated diagnostic networks.| Strategic Initiative | Industry Significance |
|---|---|
| MDR-Ready Submission Prioritization | EU MDR Article 10 technical documentation mandates extend notified body timelines, favoring early filers for vacuum infiltration systems. |
| RFID-Integrated Processor Deployment | Academic medical centers in Germany and the United States eliminate specimen misidentification errors through cassette chain-of-custody digitization. |
| Equipment-as-Service Contract Expansion | Pay-per-cassette models lower capital barriers for mid-sized pathology groups transitioning from manual to automated workflows. |
| CDSCO Registration Acceleration | NABH accreditation expansion in tier-2 Indian city hospital networks creates first-mover positioning for automated processor vendors. |
| Digital Pathology Platform Integration | Cloud-connected processors enable predictive maintenance algorithms that optimize throughput across centralized laboratory networks. |
Study Parameters
A standing panel of histopathology laboratory directors, biomedical equipment procurement managers, CAP accreditation specialists, and GPO contracts administrators provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, CAP laboratory accreditation records, CDSCO medical device registration filings, and EU MDR notified body submission trackers. Bottom-up installation base modeling triangulated with top-down market sizing derived from reagent consumption patterns and depreciation cycle analysis.
Scenario bracketing around hospital consolidation velocity and digital pathology adoption curves shaped projection boundaries across the analysis window. Segmentation modeling incorporated product type automation level, end-user capital intensity, technology integration tier, and application specimen complexity. CAGRs were derived from weighted average replacement cycle timing and penetration rate assumptions. Forecast inputs included CLIA complexity escalation timelines and RFID adoption curves in academic medical centers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by life sciences conglomerates pursuing reagent-to-instrument bundling or precision engineering specialists accelerating MDR submissions would shift outcomes. Reagent supply disruptions from Gulf Coast petrochemical corridors or sudden CLIA proficiency testing requirement changes represent primary revision risks. Quarterly review of FDA 510(k) clearance velocity and notified body backlog duration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Global Cell Culture Sampling Device Market
Biotechnology Equipment
Global Life Sciences Tools Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Cell Disruption Market
Biotechnology Equipment
Biobank Equipment Market
Biotechnology Equipment
Asia-Pacific Transfection Reagent and Equipment Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Automated Cell Culture Systems Market