
 Biodetectors and Accessories Market | 2026-2036
Biodetectors and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Biodetectors and Accessories Market Intelligence
The integration of software-as-a-service (SaaS) for data analytics is recalibrating the value proposition from a one-time hardware sale to a recurring revenue model. Thermo Fisher Scientific leverages its extensive portfolio to offer integrated hardware and software solutions. Siemens Healthineers differentiates through its focus on clinical diagnostics automation. Meanwhile, bioMérieux sustains its market position through specialization in microbiology and infectious disease detection.
Biodetectors are analytical devices that combine a biological recognition element, such as an antibody or nucleic acid, with a physical transducer to identify specific biological agents. Their primary function is the rapid and sensitive identification of pathogens, toxins, or biomarkers for clinical and security purposes. While fixed detectors maintain a large installed base in laboratories, the portable detectors segment shows significant uptake for field-based applications. Mass spectrometry technology commands a premium, especially for high-throughput clinical diagnostics and research.
Market access is governed by stringent regulatory frameworks, including the FDA's premarket approval process in the United States and CE marking under the MDR in Europe. In China, the NMPA sets specific standards for medical devices, influencing local product development and import requirements. Stakeholders must navigate the evolving landscape of data privacy regulations, such as GDPR, which impacts the design of connected biodetection systems.
Market Dynamics
The market's development is shaped by the dual pressures of intense demand for rapid, field-deployable detection from clinical and security end-users, and the escalating compliance burden imposed by evolving medical device and data privacy regulations across key markets.
Growth Catalysts
- Government Biodefense Investment:Increased national funding for public health preparedness and pathogen surveillance programs in the United States and European Union member states stimulates procurement of advanced biodetection systems.
- Point-of-Care Diagnostics:The expansion of clinical testing into decentralized settings, such as clinics and physician offices, requires a greater volume of portable and easy-to-use biodetectors for infectious disease management.
- Technology Miniaturization:Advances in shrinking PCR and mass spectrometry components enable the creation of more powerful, field-portable instruments, broadening their applicability beyond traditional laboratories.
Market Restraints
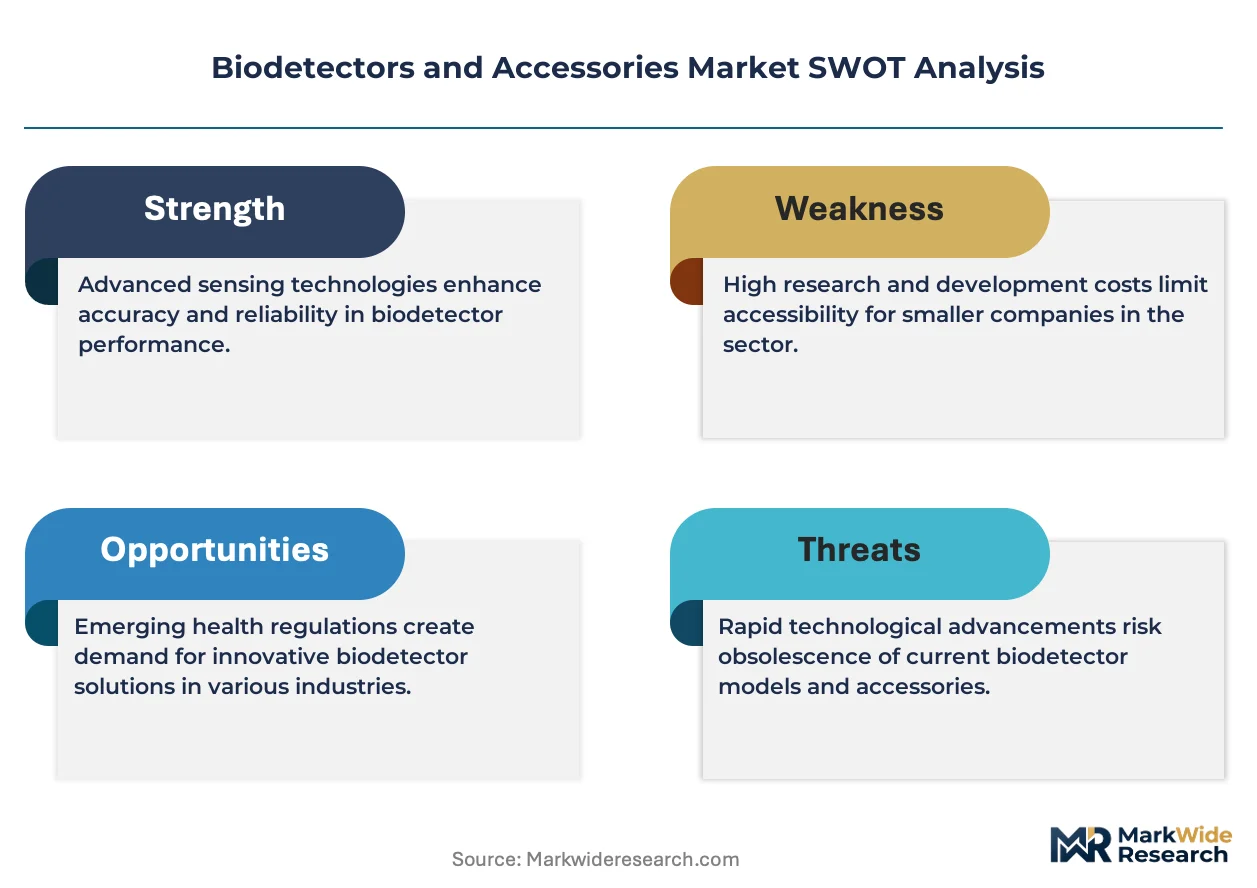
- High Instrument Cost:The significant capital investment required for high-end systems, particularly those using mass spectrometry, restricts their adoption in academic research and healthcare facilities with limited budgets.
- Regulatory Hurdles:Lengthy and complex approval pathways, including the FDA's premarket approval process and CE marking under the EU's MDR, delay product launches and increase development costs.
- Performance Trade-offs:Portable detectors often face a fundamental compromise between sensitivity, specificity, and analysis speed, which can limit their reliability for applications requiring high-confidence results.
Strategic Opportunities
- Agricultural and Food Safety:Integrating biodetection technologies into agricultural supply chains offers a significant opportunity for the early identification of plant pathogens and foodborne contaminants.
- Predictive Analytics Integration:Combining biodetection data with AI-powered software platforms enables the development of subscription services that can forecast disease outbreaks, creating new value streams. *Geographic Expansion: Addressing unmet needs for low-cost, robust infectious disease diagnostics in Southeast Asian and Latin American countries presents a major growth vector for manufacturers.
Industry Challenges
- Skilled Personnel Shortage:A deficit of technicians trained to operate and maintain high-complexity biodetection instruments creates an operational bottleneck for clinical and research laboratories.
- Data Security Compliance:Ensuring that connected biodetection systems comply with stringent data privacy regulations, such as GDPR in Europe and HIPAA in the US, is a complex technical and legal challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodetectors and Accessories Market |
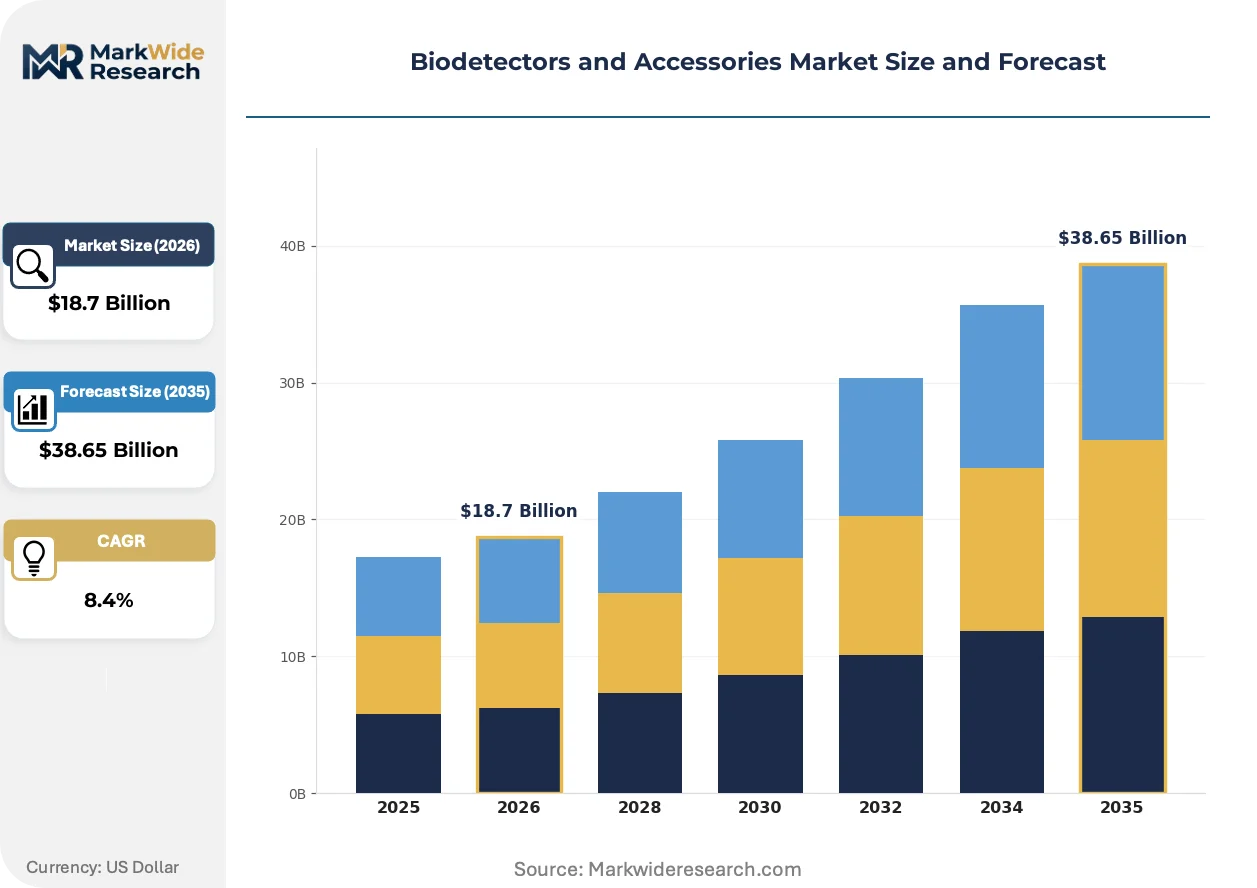
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Accessories, Software Technology: Optical, Electrochemical, Mass Spectrometry, Surface Plasmon Resonance End User: Laboratories, Hospitals, Environmental Agencies, Research Institutions Application: Food Safety, Environmental Monitoring, Clinical Diagnostics, Biosecurity |
| Companies Covered | Thermo Fisher Scientific, Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Becton Dickinson and Company, bioMérieux, Danaher Corporation, PerkinElmer, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodetectors and Accessories Market Strategic Shifts & Innovations
A fundamental shift towards connected, data-centric detection ecosystems is redefining the biodetector market. This transition emphasizes real-time data analytics and system interoperability over the performance of standalone hardware, influencing both product design and business models.
CRISPR-Based Diagnostics
CRISPR-based diagnostics provide a programmable and highly specific method for nucleic acid detection. Clinical laboratories are adopting these platforms for their rapid development cycle when responding to novel pathogens. As a result, the flexibility of CRISPR-based assays is overtaking the fixed-target nature of traditional antibody-based rapid tests for specific molecular diagnostic applications.
Regulatory Stringency
The European Union's Medical Device Regulation (MDR) mandates more rigorous clinical evidence and post-market surveillance for all devices. This regulation increases the time and cost associated with achieving CE marking for market access. Consequently, manufacturers of in-vitro diagnostic (IVD) devices are most affected, forcing them to re-evaluate product portfolios for compliance.
Business Model Evolution
Subscription-based models for analytical software and consumable reagents are becoming more prevalent in the market. This model displaces the traditional one-time capital expenditure for hardware, offering customers lower upfront costs and vendors a recurring revenue stream. The trend is most pronounced in the North American clinical research sector, where budget flexibility is a key purchasing driver.
Biodetectors and Accessories Market Segmentation
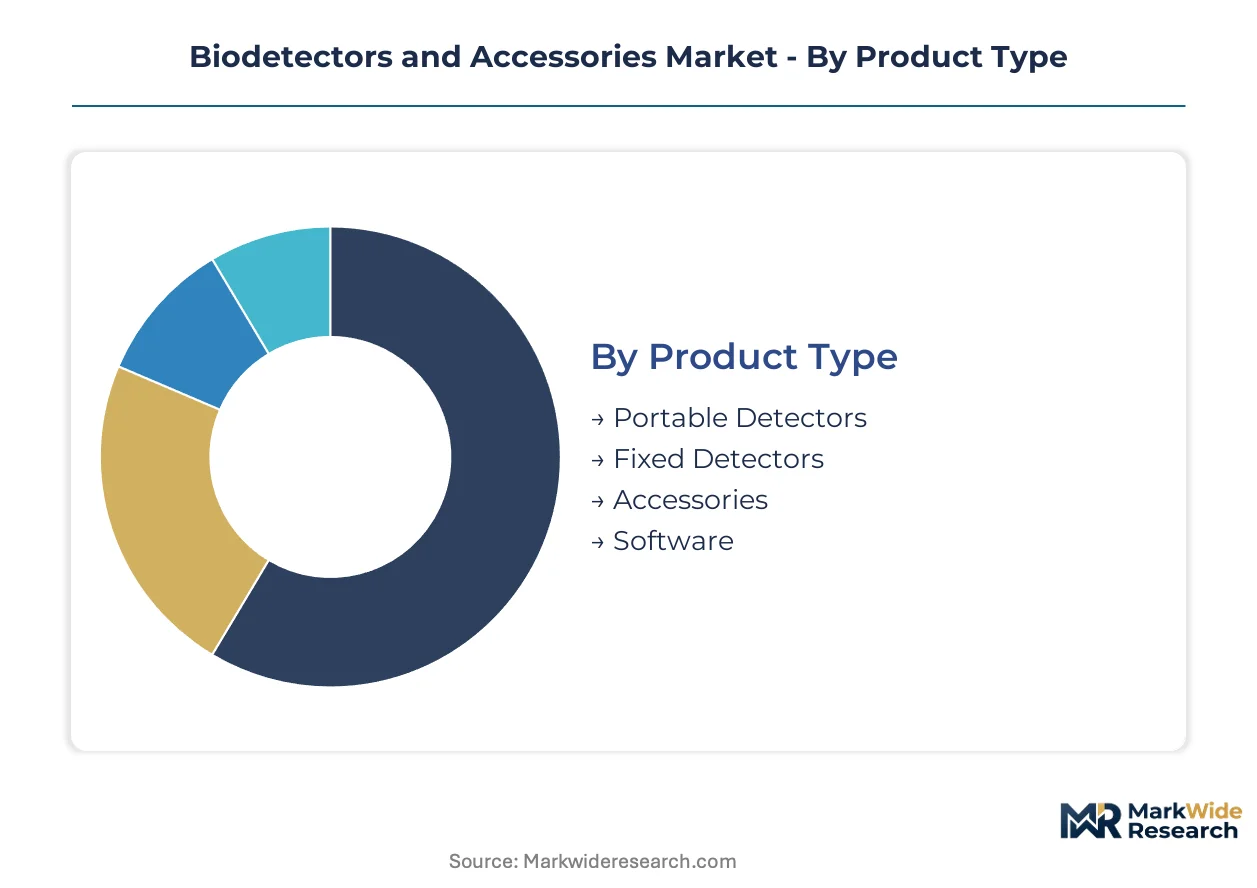
The biodetectors and accessories market exhibits diverse segmentation, reflecting the varied requirements of clinical, security, and environmental applications. Understanding these distinct segments is crucial for manufacturers to tailor product development and market entry strategies effectively.
Product Type:
The product type segmentation highlights the balance between highly specialized, customized biodetection solutions and standardized, off-the-shelf offerings.
- Portable Detectors:These are compact, often battery-powered devices designed for on-site and rapid analysis in non-laboratory settings. Field-based applications, such as point-of-care diagnostics and rapid environmental monitoring, drive procurement due to their inherent mobility requirements.
- Fixed Detectors:Large, laboratory-based instruments provide high throughput, advanced analytical capabilities, and superior sensitivity for complex analyses. Clinical diagnostic laboratories and large research institutions maintain a substantial installed base for routine and specialized testing, supported by established infrastructure.
- Accessories:This segment includes essential consumables, reagents, and calibration kits that ensure the continuous and accurate operation of biodetection systems.
- Software:Data analytics platforms, instrument control interfaces, and bioinformatics tools enhance system functionality, streamline data interpretation, and enable integration into broader health IT systems.
Most installed capacity flows through Fixed Detectors. Expansion is steepest in Portable Detectors.
Technology:
Technology differentiation often correlates with instrument cost and analytical performance, influencing adoption across various budget constraints.
- Mass Spectrometry:This technology provides highly accurate molecular identification and quantification based on the mass-to-charge ratios of ions. High-throughput clinical diagnostics and advanced research applications command premium investment due to its unparalleled specificity and comprehensive analytical power.
- Optical:Optical technologies utilize light-based detection methods, including fluorescence, chemiluminescence, and colorimetry, for biomarker identification. Laboratories frequently adopt optical systems for their versatility and established protocols in molecular and immunoassay-based testing.
- Electrochemical:This method measures electrical signals generated by biological reactions, offering compact and cost-effective detection solutions for point-of-care and field applications.
- Surface Plasmon Resonance:A label-free technology, Surface Plasmon Resonance detects molecular interactions in real-time, proving valuable for drug discovery, binding kinetics studies, and biosensor development.
Optical technologies maintain a broad application base. Mass Spectrometry continues to drive high-value market segments.
End User:
End-user segments reflect distinct operational environments and specific analytical requirements, driving diverse product specifications.
- Hospitals:These institutions require rapid and accurate diagnostic tools for patient care, infection control, and infectious disease management. Point-of-care solutions and automated clinical analyzers are critical for timely treatment decisions and efficient patient throughput.
- Laboratories:This segment encompasses central clinical laboratories, public health laboratories, and academic research facilities performing a wide array of tests. High-throughput fixed detectors and specialized assay platforms are essential for complex analyses and handling large sample volumes.
- Research Institutions:These entities focus on novel biomarker discovery, pathogen characterization, and method development, often requiring advanced, flexible, and customizable biodetection systems.
- Environmental Agencies:These organizations utilize biodetectors for water quality monitoring, air pathogen surveillance, and the detection of biological contaminants in various environmental matrices.
Hospitals and Laboratories represent the largest volume of biodetector deployments. Research Institutions are consistently adopting emerging technologies.
Application:
The application landscape is shaped by varying regulatory stringencies and the critical nature of detection outcomes across different sectors.
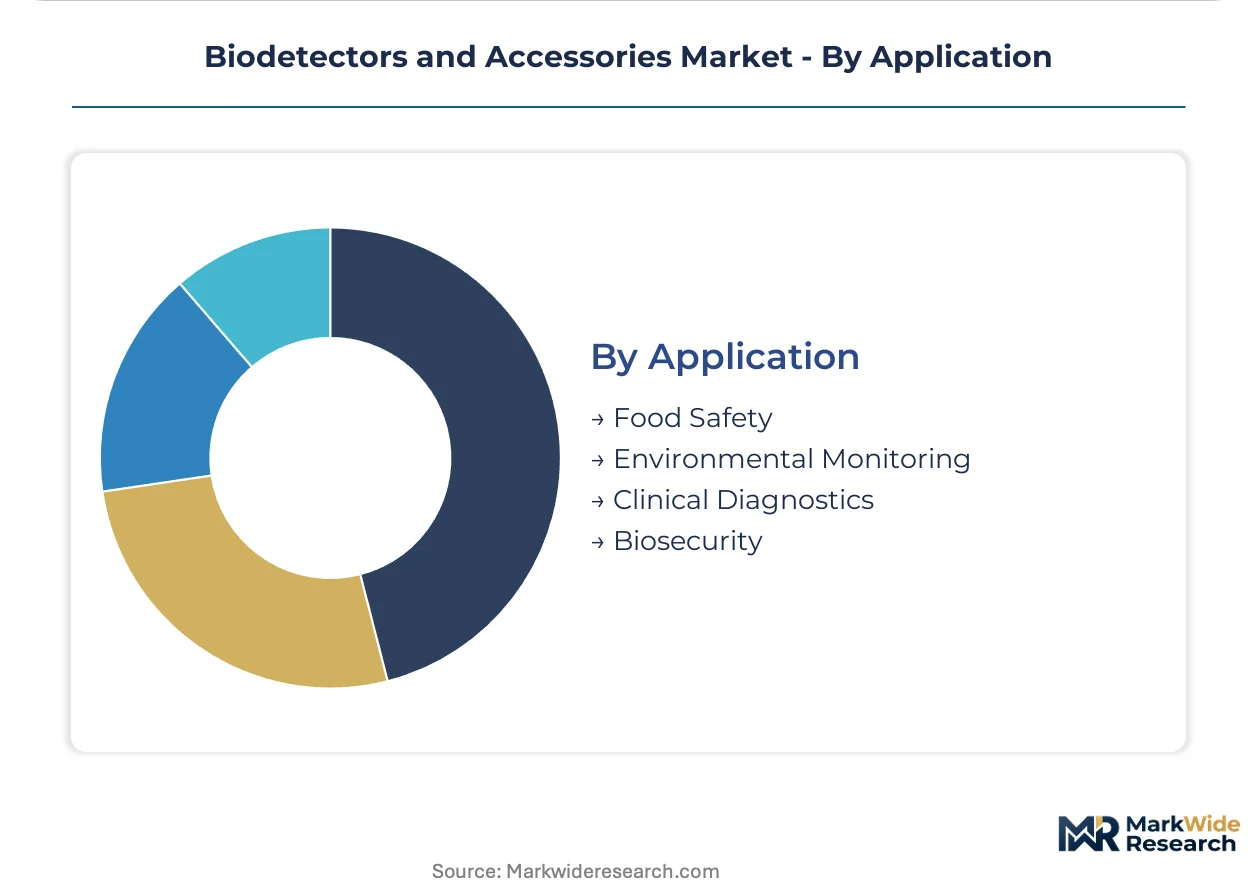
- Clinical Diagnostics:This application involves the identification of pathogens, biomarkers, and genetic markers for disease diagnosis, prognosis, and therapeutic monitoring. Strict regulatory frameworks, such as the FDA's premarket approval process and the EU's MDR, govern product development and market access in this critical area.
- Biosecurity:Biosecurity applications focus on the rapid detection of biological threats, including bioterrorism agents and emerging infectious diseases, for national security and public health protection. Government biodefense investments in the United States and European Union member states stimulate procurement of advanced surveillance systems.
- Food Safety:This segment involves detecting foodborne pathogens, allergens, and contaminants to ensure public health, prevent outbreaks, and comply with international food regulations.
- Environmental Monitoring:Biodetectors in this application identify microbial pollutants, toxins, and invasive species in water, soil, and air, supporting public health and ecological protection efforts.
Clinical Diagnostics drives substantial market value. Biosecurity applications are expanding most quickly due to heightened public health preparedness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The biodetectors and accessories market experiences varied demand across key global regions. While the United States drives significant investment in biodefense, China exhibits robust expansion for research institutions and clinical diagnostics. Diverse regulatory environments and healthcare infrastructure shape regional market trajectories.
United States
Government biodefense investments and point-of-care diagnostics expansion drive demand for biodetection systems. The FDA's premarket approval process rigorously governs market access for medical devices. Major biotechnology clusters in Boston and San Francisco lead in novel biomarker discovery and advanced instrument development.
Germany
Clinical diagnostics automation and advanced research applications underpin strong market demand. The European Union's MDR mandates stringent performance and safety requirements for devices, influencing product design. Munich and Berlin host significant research institutions and medical technology firms, fostering innovation in biodetection.
China
Demand for advanced biosecurity solutions and clinical diagnostics from research institutions is concentrating. The NMPA sets specific standards for medical devices, impacting local product development and import requirements. Shanghai and Beijing serve as key hubs for biomedical research and the deployment of advanced biodetection technologies.
Japan
Advanced research in novel biomarker discovery and high-throughput clinical diagnostics fuel the market. The PMDA regulates medical devices, ensuring product quality and safety for market entry. Tokyo and Kyoto host leading academic and research facilities, driving the adoption of cutting-edge biodetection systems.
France
Specialization in microbiology and infectious disease detection sustains market activity. CE marking under the EU's MDR is a critical requirement for market access. Lyon, home to bioMérieux, remains a prominent center for infectious disease diagnostics and related biodetection technologies.
Biodetectors and Accessories Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied strategic priorities. The market structure includes established diagnostics giants, specialized technology providers, and emerging software-centric innovators. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants.
Established diagnostics firms like Thermo Fisher Scientific exemplify integrated hardware and software solutions, leveraging extensive portfolios. Siemens Healthineers occupies a strong position through its focus on clinical diagnostics automation. Meanwhile, bioMérieux anchors a specialized niche, concentrating on microbiology and infectious disease detection.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Becton Dickinson and Company |
| bioMérieux |
| Danaher Corporation |
| PerkinElmer |
| Hologic |
Cost & Logistics Intelligence
Vertical integration into key component manufacturing anchors the supply position for several biodetector manufacturers, directly influencing their pricing power and market stability. This strategy mitigates external supply shocks.
Pricing Analysis
Capacity additions in China are reshaping price floors for basic biodetection accessories, influencing global market pricing. The dominant pricing structure across the market is a hybrid model, combining subscription-based software services with transactional hardware sales. Price differentiation stems from technology sophistication and regulatory compliance, particularly CE marking under the EU MDR. Pricing softness reflects intense competition in the portable detector segment. Hospitals exhibit the highest price sensitivity for routine diagnostics, while research institutions prioritize performance over cost.
Supply Chain Analysis
Domestic-content mandates, particularly from the NMPA in China, are reshaping sourcing strategies for biodetector components. Supply concentration for advanced optical sensors and specialized reagents rests in Germany, Japan, and the United States. Key raw material dependencies include rare earth elements for certain transducers and complex biochemicals for recognition elements. A structural supply chain risk is single-source vulnerability for highly specialized mass spectrometry components. Distribution runs through a mix of direct sales forces and specialized medical device distributors globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biodetector market presents a geographic-arbitrage opportunity, driven by significant labor cost differentials between European and Southeast Asian manufacturing hubs. This allows for optimized production and market access strategies.
For Market Incumbents: Cement market leadership by investing in advanced software analytics platforms that integrate seamlessly with existing hardware portfolios. This move counters the threat from specialized software-centric innovators and reinforces customer loyalty. Investing in certification for new portable detector models under the EU MDR provides a competitive lever against less compliant entrants, securing broader European market access.
For New Entrants and Emerging Players: CRISPR-based diagnostics offer a technology-first wedge into molecular detection, circumventing established antibody-based platforms. New entrants should target underserved clinical diagnostics applications in Southeast Asian countries, leveraging lower-cost, robust portable detectors. A direct-to-clinic sales model, supported by remote technical assistance, can accelerate market penetration in these regions.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized technology providers because the biodetector market exhibits fragmentation across specialized niches. Investors should target companies with proprietary optical or electrochemical detection technologies and robust software integration capabilities. The long-term viability hinges on consolidating niche players to create comprehensive diagnostic platforms. A signal to watch is the increasing M&A activity involving AI-powered diagnostic software firms.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch SaaS Data Analytics Platform | This initiative shifts revenue models from hardware sales to recurring subscription services for hospitals and laboratories. |
| Form AI Integration Partnerships | Collaborating with AI developers enhances predictive analytics capabilities for disease outbreak forecasting, expanding value propositions. |
| Prioritize EU MDR CE Marking | Achieving CE marking under the strict EU MDR ensures market access and product credibility across European Union member states. |
| Expand into Southeast Asian Markets | Addressing unmet diagnostic needs in Southeast Asia opens new growth vectors for portable and cost-effective biodetector solutions. |
| Acquire CRISPR-Based Diagnostic Firm | This acquisition integrates highly specific and programmable nucleic acid detection into existing product portfolios for rapid pathogen identification. |
Research Approach
Bottom-up clinical diagnostics modeling reconciled against top-down biodetection hardware tracking forms the analytical core for this study. The methodology integrates primary interviews with R&D directors, hospital procurement managers, regulatory affairs specialists, and public health officials. Secondary validation draws from FDA filings, NMPA guidelines, and academic research publications. This approach ensures robust triangulation of market size and growth projections.
An input-output matrix framing quantifies the market across the analysis window, considering technology, product type, end-user, and application dimensions. Forecasts incorporate specific inputs like government biodefense spending and point-of-care diagnostics expansion. Compound annual growth rates are derived from historical trends, expert projections, and anticipated technological advancements in miniaturization.
The model holds under current regulatory frameworks and anticipated technological development trajectories; deviation in global pandemic preparedness funding or significant shifts in medical device regulations would shift market dynamics. Forecasts reflect assumptions regarding economic stability and healthcare investment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Single-Use Bioprocess Sensor Calibration and Validation Test Systems Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Latin America Protein Purification and Isolation Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Bioprocessing Analytics Equipment Market