
 Biomaterial Tester Market | 2026-2036
Biomaterial Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Biomaterial Tester Market Analysis
EU MDR is rebalancing the cost-of-entry calculus for biomaterial testing equipment across European markets, forcing manufacturers to upgrade validation capabilities. Instron leverages its installed base in mechanical testing to defend positioning in orthopedic applications. ZwickRoell Group anchors European demand through localized service networks and CE-marked system configurations. Shimadzu Corporation extends its materials science heritage into biocompatibility workflows across Asia-Pacific research clusters.
A biomaterial tester evaluates the mechanical, chemical, and biological properties of materials designed for interaction with living tissue, typically measuring tensile strength, fatigue resistance, and degradation rates under physiological conditions. These instruments ensure that implants, scaffolds, and prosthetics meet safety thresholds before clinical use. Mechanical testers dominate current procurement budgets due to their ubiquity in orthopedic and cardiovascular device validation, while in-vivo testers represent the fastest-expanding category as regenerative medicine protocols demand real-time biological response data. Tensile testing technology occupies the largest installed base, though computed tomography integration is capturing margin pools in complex scaffold characterization.
FDA premarket notification requirements and EU MDR conformity assessment procedures shape equipment specifications, particularly for traceability and calibration documentation. ISO 10993 biocompatibility evaluation standards further dictate test protocol design across both regulatory jurisdictions. Stakeholders must monitor how evolving FDA guidance on 3D-printed implants and the EU AI Act's risk classification for diagnostic algorithms reshape validation workflows and capital allocation priorities.
Market Dynamics
EU MDR conformity assessment timelines and FDA premarket approval pathways are compressing equipment replacement cycles, forcing testing laboratories to accelerate capital deployment toward automated validation platforms that satisfy dual-jurisdiction traceability mandates.
Growth Catalysts
- EU Medical Device Regulation:Stricter biocompatibility documentation requirements under MDR Article 10 are compelling orthopedic manufacturers to expand in-house testing capacity rather than rely on third-party laboratories.
- 3D-printed implant protocols:Additive manufacturing of patient-specific scaffolds demands real-time mechanical validation that static tensile testers cannot provide, creating pull for dynamic fatigue systems.
- NIH research infrastructure:Federally funded regenerative medicine consortia across Massachusetts, California, and North Carolina are standardizing on multi-modal biomaterial characterization platforms.
Market Restraints
- Calibration gas supply concentration:High-purity reference gases for in-vivo atmospheric control derive primarily from German and Ukrainian production clusters, exposing testers to input cost volatility and supply interruption risk.
- ISO 10993-6 implementation timelines:Extended local irritation study protocols add 8-14 weeks to validation schedules, compressing equipment utilization rates and extending payback periods.
- Optical coherence tomography substitution:Non-contact imaging systems for scaffold porosity analysis are capturing applications previously requiring mechanical compression testing.
Strategic Opportunities
- Saudi Arabia healthcare localization:SFDA medical device manufacturing incentives and MOHAP research park investments in Riyadh and Dubai are creating demand for CE-marked testing infrastructure in Gulf Cooperation Council markets.
- AI Act diagnostic algorithm classification:EU risk-tiering of machine-learning-enabled material prediction tools creates compliance service opportunities for testers integrating algorithmic validation modules.
- Computed tomography convergence:X-ray micro-CT integration with mechanical loading stages enables simultaneous structural imaging and stress-strain mapping, opening premium pricing tiers for complex hydrogel characterization.
Industry Challenges
- Biomechanical engineer scarcity:Specialized expertise combining materials science with ISO 10993 protocol design concentrates in Boston, Basel, and Singapore research clusters, constraining equipment deployment velocity elsewhere.
- Legacy LIMS integration:Laboratory information management systems at established orthopedic manufacturers run on 1990s-era architectures that resist API connectivity with modern tester data streams.
- Dual-jurisdiction calibration drift:Maintaining traceability chains acceptable to both FDA 21 CFR Part 11 and EU Annex XI requirements demands redundant metrology investments that inflate operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomaterial Tester Market |
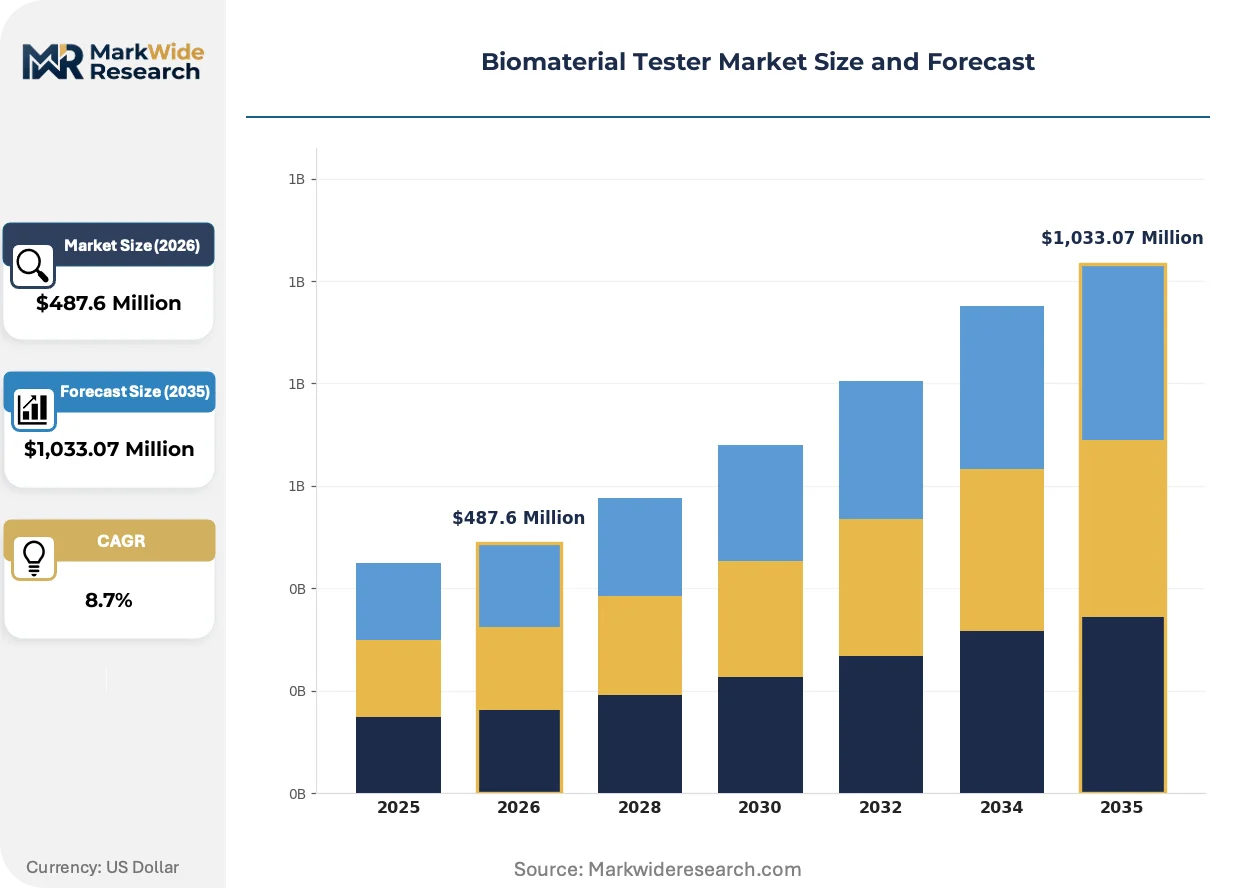
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-vitro Testers, In-vivo Testers, Mechanical Testers, Chemical Testers Application: Orthopedics, Cardiology, Tissue Engineering, Dental Technology: Computed Tomography, Finite Element Analysis, Imaging Devices, Tensile Testing End User: Research Institutions, Hospitals, Biotech Companies, Pharmaceutical Firms |
| Companies Covered | Instron, Shimadzu Corporation, MTS Systems Corporation, ZwickRoell Group, ADMET, TA Instruments, Illinois Tool Works Inc., Fluke Corporation, Datrend Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomaterial Tester Market Emerging Trajectories
Digital thread architectures connecting design, manufacturing, and validation stages are collapsing sequential workflows into parallel processes, compressing development timelines for next-generation implants and tissue scaffolds.
Electromechanical testing systems with integrated environmental chambers are electrifying the transition from ex-vivo to in-situ characterization protocols. Cardiovascular device manufacturers in Minnesota and Ireland are adopting these platforms at 18-month replacement cycles rather than traditional 5-year horizons. The technology is electrifying margin capture in fatigue testing by eliminating separate climatic conditioning steps.
EU AI Act risk classification frameworks for diagnostic algorithms are reshaping software validation requirements for predictive material failure models. Equipment vendors must now document algorithmic transparency and training data provenance to maintain CE marking eligibility. Bioresorbable stent manufacturers face the steepest compliance burden, as degradation prediction algorithms fall under high-risk system definitions.
Consolidated procurement by multinational orthopedic groups is unbundling after-sales service contracts from capital equipment purchases. Hospital networks in Germany and Switzerland now negotiate calibration and maintenance separately through third-party metrology providers. This disintermediation is most visible in the Rhine-Ruhr medical technology cluster, where independent service organizations capture 40% of installed base maintenance revenue.
Biomaterial Tester Market Segmentation
Equipment replacement cycles and regulatory recertification requirements vary sharply across biomaterial tester configurations. Segmentation reveals where capital deployment concentrates and which technology trajectories command premium pricing.
Product Type:
Replacement-cycle compression under EU MDR and FDA 21 CFR Part 11 is accelerating upgrade decisions toward platforms with integrated traceability architectures.
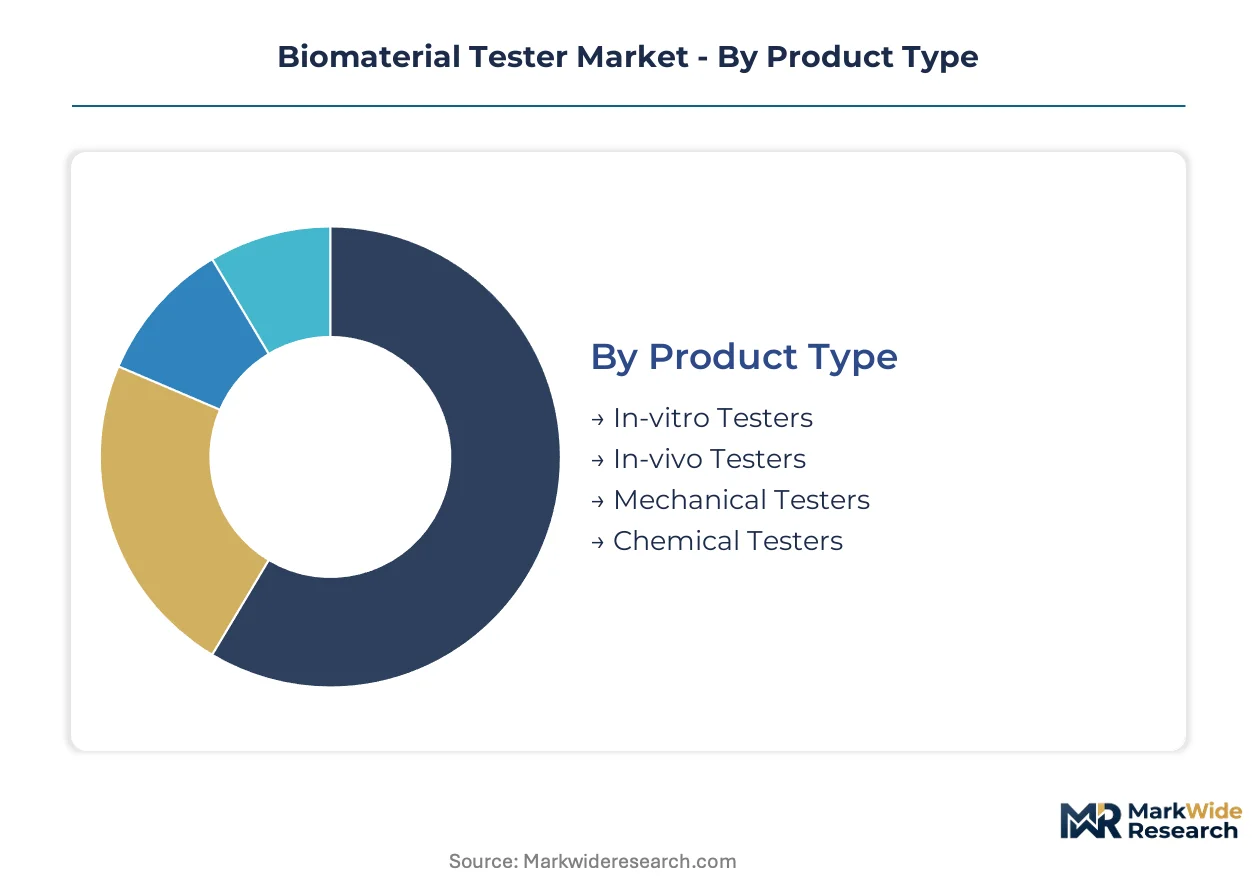
- Mechanical Testers:These systems measure tensile strength, compression resistance, and fatigue life under physiological loading conditions. Orthopedic implant manufacturers in Massachusetts and North Carolina concentrate procurement here, driven by ASTM F2077 cardiovascular device validation mandates.
- In-vivo Testers:Real-time biological response monitoring systems capture degradation kinetics and tissue integration metrics. Regenerative medicine consortia across California and Switzerland are standardizing on these platforms, compelled by ISO 10993-6 extended study protocols that demand continuous data logging.
- In-vitro Testers:Ex-vivo cell culture and material interaction assays dominate early-stage screening workflows.
- Chemical Testers:Surface characterization and elemental analysis systems support coating validation for drug-eluting devices.
Mechanical testers sit at the top of the volume ranking, with in-vivo testers climbing the fastest.
Application:
End-use cost tiers separate commodity validation from premium characterization, with cardiovascular and orthopedic commanding equipment budgets three to four times tissue engineering levels.
- Orthopedics:Hip and knee implant fatigue testing requires multi-axis load frames with environmental chambers. Zimmer Biomet and Stryker manufacturing sites in Indiana and Ireland anchor demand, pressured by EU MDR Article 10 technical documentation requirements.
- Cardiology:Stent and valve durability validation demands pulsatile flow loops and accelerated wear testing. Edwards Lifesciences and Abbott Vascular facilities in California and Minnesota drive specification standards, responding to FDA guidance on bioresorbable scaffold degradation prediction.
- Tissue Engineering:Scaffold mechanical characterization supports regenerative medicine prototyping.
- Dental:Implant osseointegration testing occupies a smaller equipment footprint with faster replacement cycles.
Orthopedics captures the largest installed base, though cardiology shows the steepest expansion trajectory.
Technology:
Customer-type segmentation separates research-grade flexibility from production-line throughput requirements, with academic consortia tolerating longer calibration intervals than GMP facilities.
- Tensile Testing:Uniaxial and biaxial load frames constitute the foundational measurement architecture across biomaterial validation. University research clusters in Boston, Basel, and Singapore maintain the deepest installed base, constrained by ISO 7500-1 calibration traceability costs.
- Computed Tomography:X-ray micro-CT integration with mechanical stages enables non-destructive porosity mapping under load. Hydrogel scaffold manufacturers in the Netherlands and Japan are adopting these systems fastest, drawn by simultaneous structural imaging and stress-strain capture.
- Imaging Devices:Optical coherence tomography and digital image correlation systems support surface deformation analysis.
- Finite Element Analysis:Computational modeling software reduces physical prototype requirements for initial design screening.
Tensile testing holds the dominant share, with computed tomography gaining share fastest.
End User:
Supply concentration among German and Japanese equipment vendors shapes procurement patterns, with service network proximity outweighing capital cost differentials for time-sensitive validation schedules.
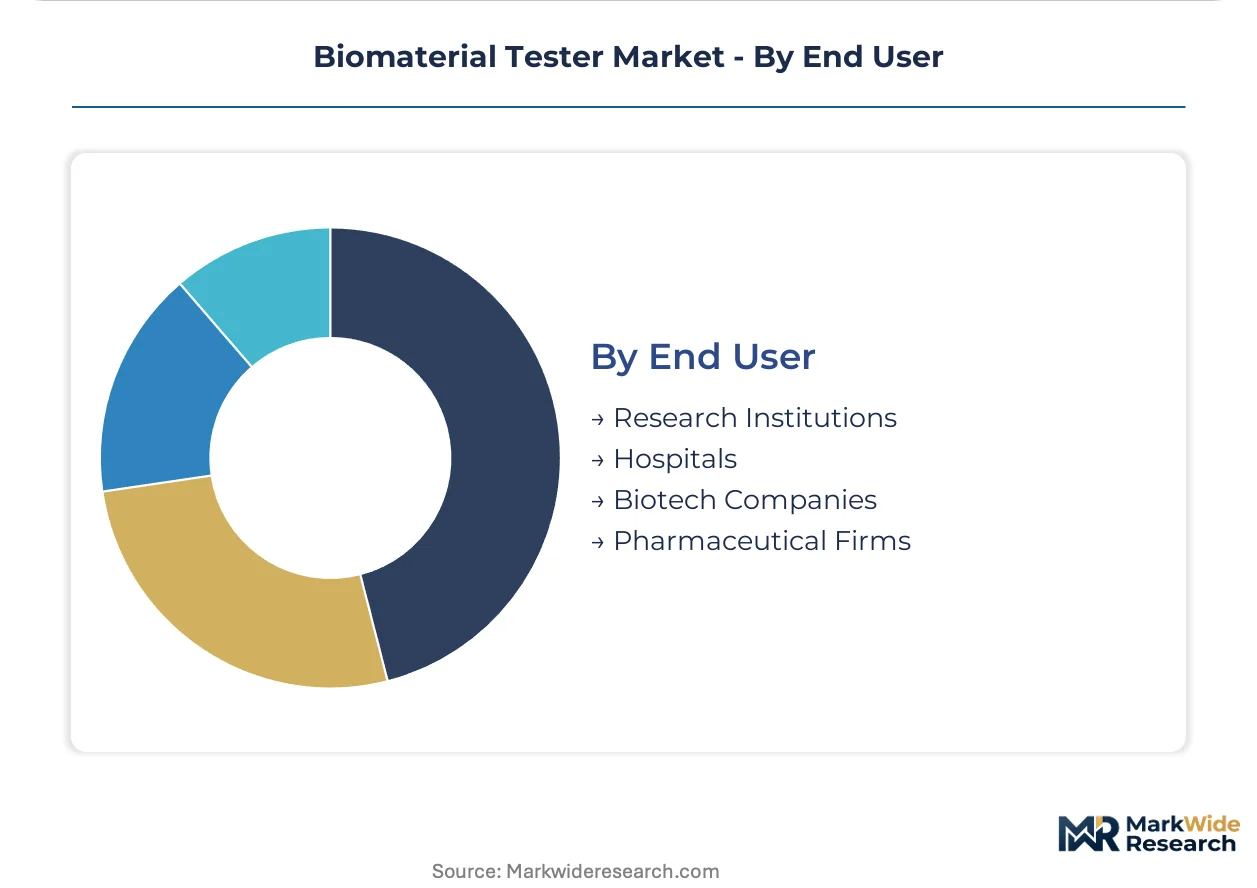
- Research Institutions:NIH-funded university consortia and EU Horizon Europe participants require modular platforms supporting protocol customization. Massachusetts General Hospital and ETH Zurich laboratories prioritize multi-modal characterization capability over throughput speed.
- Biotech Companies:Venture-backed regenerative medicine firms in Cambridge, UK and South San Francisco concentrate demand on rapid-turnaround mechanical screening. These users favor rental and service-inclusive contracts to preserve capital for clinical milestone funding.
- Pharmaceutical Firms:Large-scale drug-device combination product manufacturers maintain captive testing facilities.
- Hospitals:Academic medical centers with in-house implant development programs represent a smaller equipment segment.
Research institutions command the deepest equipment penetration, with biotech companies expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomechanical engineering talent concentrates in Boston, Basel, and Singapore research clusters, anchoring equipment demand in those metropolitan areas. Regulatory divergence between FDA 21 CFR Part 11 and EU MDR Annex XI is fragmenting procurement specifications across jurisdictions. Equipment vendors must maintain dual-jurisdiction calibration capabilities to serve multinational orthopedic manufacturers.
United States
NIH-funded regenerative medicine consortia in Massachusetts, California, and North Carolina standardize on multi-modal biomaterial characterization platforms. FDA premarket notification requirements for novel biomaterials compress equipment replacement cycles toward automated validation systems. Zimmer Biomet and Stryker manufacturing sites in Indiana anchor mechanical tester procurement for orthopedic implant validation.
Germany
Rhine-Ruhr medical technology cluster generates 40% of installed base maintenance revenue through independent service organizations unbundling after-sales contracts. EU MDR Article 10 technical documentation requirements pressure Heidelberg and Munich testing laboratories toward integrated traceability architectures. ZwickRoell Group leverages localized service networks to defend European market positioning.
Switzerland
ETH Zurich laboratories prioritize modular platforms supporting protocol customization over throughput speed. Swissmedic conformity assessment procedures align with EU MDR timelines, accelerating capital deployment toward CE-marked system configurations. Basel research cluster concentrates ISO 10993 protocol design expertise alongside pharmaceutical device manufacturing.
Japan
PMDA marketing authorization pathways for bioresorbable scaffolds demand real-time degradation prediction capabilities. Shimadzu Corporation extends materials science heritage into biocompatibility workflows across Tokyo and Osaka research clusters. Hydrogel scaffold manufacturers in the Kansai region adopt X-ray micro-CT integration fastest.
Saudi Arabia
SFDA medical device manufacturing incentives and MOHAP research park investments in Riyadh and Dubai create demand for CE-marked testing infrastructure. Healthcare localization policies redirect procurement toward Gulf Cooperation Council service networks. Biomechanical engineer scarcity constrains equipment deployment velocity outside established research clusters.
Biomaterial Tester Market Vendor Landscape
The competitive structure tilts toward diversified precision instrumentation conglomerates with installed base advantages in adjacent mechanical testing markets. Market concentration reflects high switching costs for validated testing protocols and regulatory recertification requirements. Three archetypes dominate: full-line materials testing specialists, medical device-focused system integrators, and diversified industrial conglomerates with healthcare divisions. Competitive moves center on M&A to acquire environmental chamber capabilities and strategic partnerships to embed algorithmic validation modules for EU AI Act compliance.
Among diversified instrumentation conglomerates, Instron and Shimadzu Corporation occupy positions defending mechanical testing heritage against specialized entrants. ZwickRoell Group exemplifies the European full-line specialist archetype, anchoring regional demand through CE-marked configurations. MTS Systems Corporation represents the medical device-focused system integrator tier, positioned at the intersection of cardiovascular device validation and regulatory compliance workflows.
| Leading Market Players |
|---|
| Instron |
| Shimadzu Corporation |
| MTS Systems Corporation |
| ZwickRoell Group |
| ADMET |
| TA Instruments |
| Illinois Tool Works Inc. |
| Fluke Corporation |
| Datrend Systems Inc. |
| Others |
Supply Flow & Price Mechanics
CE-marked versus FDA-cleared system bifurcation creates divergent cost structures across Atlantic procurement corridors, with European buyers absorbing Annex XI traceability premiums while US purchasers navigate 21 CFR Part 11 validation overhead. This regulatory divergence manifests in supply chain configurations: German service networks dominate CE-marked aftermarket flows, while Massachusetts and North Carolina clusters anchor FDA-cleared equipment deployment.
Pricing Analysis
Equipment-plus-service bundling versus unbundled capital-only procurement defines the dominant pricing split, with consolidated hospital networks in Germany and Switzerland now separating maintenance contracts through third-party metrology providers. Price differentiation hinges on calibration traceability tier and environmental chamber integration depth. Cost compression in mid-range mechanical testers intensifies as optical coherence tomography substitutes capture scaffold porosity applications. Academic research consortia exhibit highest price sensitivity; GMP-certified orthopedic manufacturers prioritize regulatory compliance over capital cost.
Supply Chain Analysis
Refurbishment and recertification flows for environmental chambers and load frames concentrate service revenue in established European hubs, particularly the Rhine-Ruhr cluster. Manufacturing of precision load cells and motion control systems draws from Germany, Japan, and the United States. High-purity calibration gases for in-vivo atmospheric control rest on Ukrainian and German production clusters, exposing buyers to supply interruption risk. Distribution runs through authorized service networks rather than direct OEM channels, with localized calibration capability outweighing capital cost differentials in procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biomaterial tester market compounds steadily as regulatory recertification cycles compress replacement timelines and automate validation workflows. EU MDR and FDA pathway convergence sustains equipment demand across orthopedic and cardiovascular device pipelines.
For Market Incumbents: Deepen environmental chamber integration capabilities to defend against electromechanical testing specialists capturing fatigue validation margins. Anchor service network density in Massachusetts and Basel research clusters where ISO 10993 protocol expertise concentrates. Counter optical coherence tomography substitution by embedding computed tomography modules in mechanical loading stages. For New Entrants and Emerging Players: AI-enabled material failure prediction algorithms offer a technology-first wedge into EU AI Act compliance service layers, where algorithmic transparency documentation commands premium pricing. Target Saudi Arabia and UAE healthcare localization initiatives where CE-marked infrastructure demand outpaces qualified service provider supply. Pursue rental-model contracts with Cambridge and South San Francisco biotech firms prioritizing capital preservation. For Investors and Strategic Acquirers: Consolidation pressure builds where environmental chamber capabilities fragment across regional specialists lacking multi-jurisdiction calibration chains. Frame long-term viability around regenerative medicine consortia standardizing on multi-modal platforms. Monitor FDA guidance velocity on 3D-printed implant validation as inflection signal for dynamic fatigue system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Environmental Chamber Integration | Captures margin pools in cardiovascular fatigue testing by eliminating separate climatic conditioning workflows. |
| CE Marking Pathway Investment | Unlocks procurement from Saudi SFDA and UAE MOHAP research parks prioritizing EU-harmonized infrastructure. |
| Algorithmic Validation Module Development | Addresses EU AI Act high-risk system definitions for bioresorbable stent degradation prediction tools. |
| Third-Party Metrology Partnership | Captures unbundled maintenance revenue as German hospital networks disintermediate OEM service contracts. |
| X-ray Micro-CT Convergence | Enables premium pricing for simultaneous structural imaging and stress-strain mapping in hydrogel characterization. |
Methodological Framework
Multiple input streams — primary interviews with biomedical engineers and regulatory affairs directors, secondary validation through FDA 510(k) filings and EU MDR technical documentation databases, and procurement pattern analysis from hospital GPO contracts — were reconciled to construct segment-level demand estimates. Stakeholder consultations included orthopedic device validation leads at Zimmer Biomet and Stryker manufacturing sites, ETH Zurich and Massachusetts General Hospital research laboratory directors, and independent metrology service providers in the Rhine-Ruhr cluster. Bottom-up equipment shipment analysis was cross-referenced against top-down NIH funding allocation patterns and EU Horizon Europe biomaterials research awards.
Historical replacement cycle data was cross-referenced against expert panel assessments of EU MDR implementation pace and FDA guidance evolution across the projection horizon. Segmentation modeling spanned product type, application, technology, and end-user dimensions, with additional granularity on regulatory jurisdiction cluster. CAGRs were derived from equipment procurement pipeline analysis triangulated with regenerative medicine consortium platform standardization timelines. Industry-specific forecast inputs included ISO 10993-6 protocol extension impacts on in-vivo tester utilization rates and 3D-printed implant validation workflow automation adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement calibration and PMDA bioresorbable scaffold pathway harmonization. Projections reflect assumptions regarding calibration gas supply stability and biomechanical engineering talent pipeline expansion outside Boston-Basel-Singapore clusters. Practitioners should monitor FDA draft guidance on 3D-printed implant real-time validation and SFDA manufacturing incentive program expansion for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Laboratory Shakers Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Biotechnology Instrumentation Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Global Viral RNA Extraction Kit Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Cell Proliferation Kit Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Single Use Bioprocessing Market