
 Biologic Imaging Reagents Market | 2026-2036
Biologic Imaging Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Biologic Imaging Reagents Market Analysis
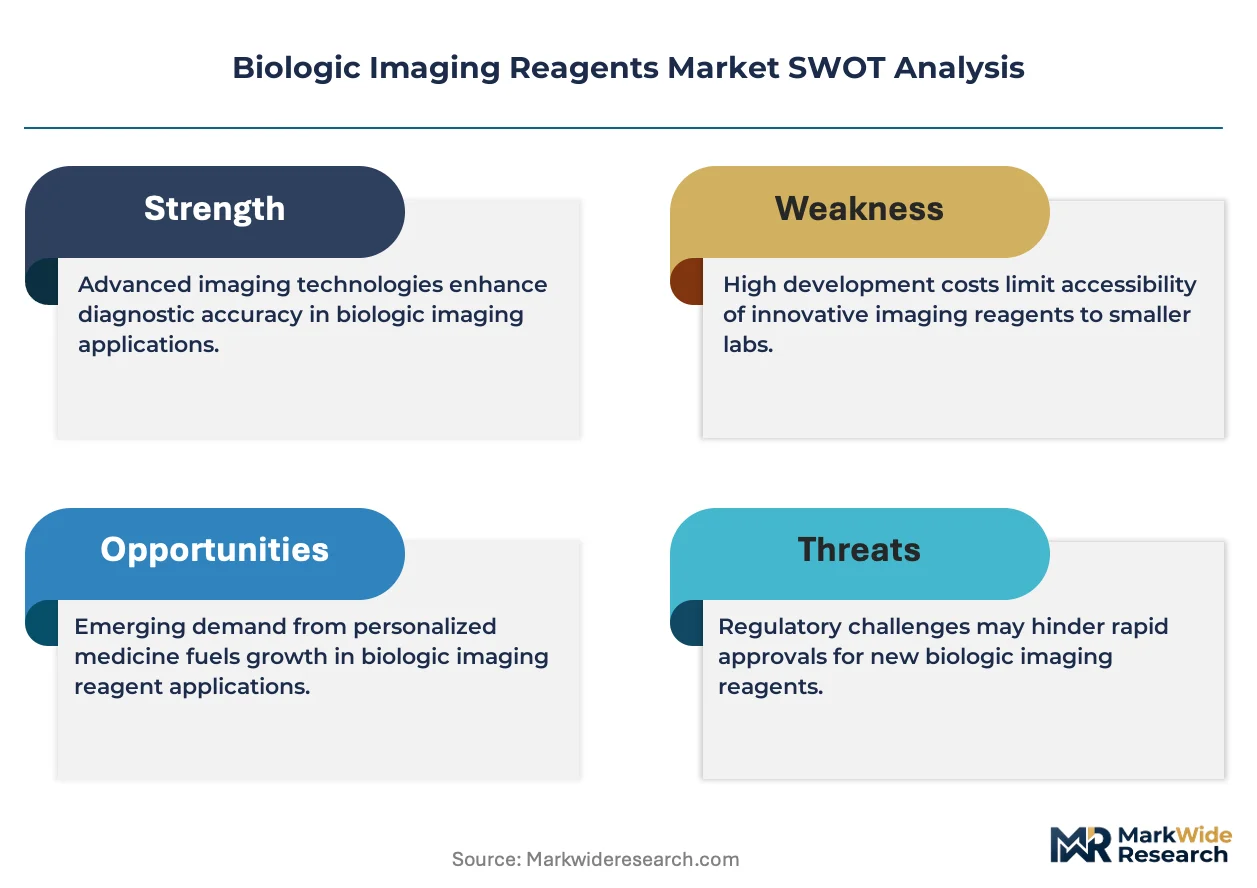
Specialized radiochemistry talent is bifurcating the competitive landscape, separating organizations with in-house isotope production capabilities from those dependent on external supply chains. Bayer AG leverages its integrated radiopharmaceutical manufacturing network to secure supply continuity for PET and SPECT tracers. Thermo Fisher Scientific anchors its position through extensive distribution infrastructure serving research laboratories and diagnostic centers across multiple geographies. GE HealthCare competes by dominating the MRI contrast agent segment with gadolinium-based formulations optimized for high-field scanners.
Biologic imaging reagents comprise molecular probes, contrast media, and radiolabeled compounds engineered to bind specific cellular or molecular targets, with specifications including binding affinity constants in the nanomolar range and purity thresholds exceeding 95% for clinical-grade materials. These reagents enable visualization of biological processes in living organisms, supporting disease diagnosis, therapeutic monitoring, and drug candidate evaluation. Fluorescent dyes occupy established positions in preclinical and in vitro settings where optical imaging platforms predominate, while radioactive tracers represent the fastest-expanding category as theranostic applications merge diagnostic precision with targeted radionuclide therapy. MRI contrast agents sustain premium pricing structures due to the capital intensity of magnetic resonance infrastructure and the specialized synthesis requirements for gadolinium chelation chemistry.
The FDA governs diagnostic reagent approval through the Center for Drug Evaluation and Research and the Center for Devices and Radiological Health, with the European Medicines Agency enforcing centralized marketing authorization for radiopharmaceuticals under the EU's pharmaceutical legislation. REACH compliance for chemical substances and ISO 13485 quality management standards further constrain market access for non-compliant suppliers. Stakeholders must monitor evolving regulatory frameworks for radiopharmaceutical manufacturing, as tightening isotope sourcing requirements and Good Manufacturing Practice inspections reshape competitive barriers and capital deployment priorities.
Market Dynamics
Short-lived isotope supply chains are concentrating production among reactor operators with proprietary molybdenum-99 recovery technology, forcing imaging centers to secure multi-year offtake agreements or face tracer shortages during scheduled maintenance cycles.
Growth Catalysts
- Theranostic convergence:Paired diagnostic and therapeutic radiopharmaceuticals are expanding oncology service lines at academic medical centers, with lutetium-177 based protocols driving PET scanner utilization rates.
- IRAs Medicare reimbursement incentives:The Inflation Reduction Act's advanced imaging payment adjustments are accelerating PET-CT procurement in community hospital settings across underserved counties.
- Fluorine-18 cyclotron miniaturization:Compact on-site production systems are eliminating cold-chain logistics for FDG tracers, enabling same-day synthesis at regional diagnostic networks.
Market Restraints
- High-purity water scarcity:Ultrapure water specifications exceeding 18.2 MΩ·cm resistivity are constraining Good Manufacturing Practice facility expansion in drought-prone manufacturing zones.
- Reactor concentration in aging infrastructure:Over 60% of global technetium-99m supply depends on five government-operated research reactors, with two scheduled for decommissioning within the analysis window.
- Gadolinium retention liability:NSF risk classifications for linear chelate formulations are compressing MRI contrast agent pricing power and elevating product liability insurance premiums.
Strategic Opportunities
- Alpha-emitter theranostics:Actinium-225 and lead-212 based pipelines are creating first-mover advantages in metastatic prostate cancer imaging, with production partnerships securing isotope access ahead of commercialization.
- India's CDSCO fast-track pathway:Streamlined radiopharmaceutical approval timelines are attracting contract manufacturing investments for export-oriented tracer production.
- AI-integrated quantification:Machine learning algorithms for standardized uptake value harmonization are enabling multi-site clinical trial enrollment, expanding addressable patient populations for novel tracer validation.
Industry Challenges
- Radiochemist talent pipeline collapse:Only seven US academic programs graduate sufficient PhD-level talent to replace retiring synthesis specialists, forcing employers to poach from competitor facilities.
- Legacy cyclotron incompatibility:Proton beam energy limitations at 16 MeV systems prevent gallium-68 production, stranding capital investments as generator-based alternatives lose reimbursement parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biologic Imaging Reagents Market |
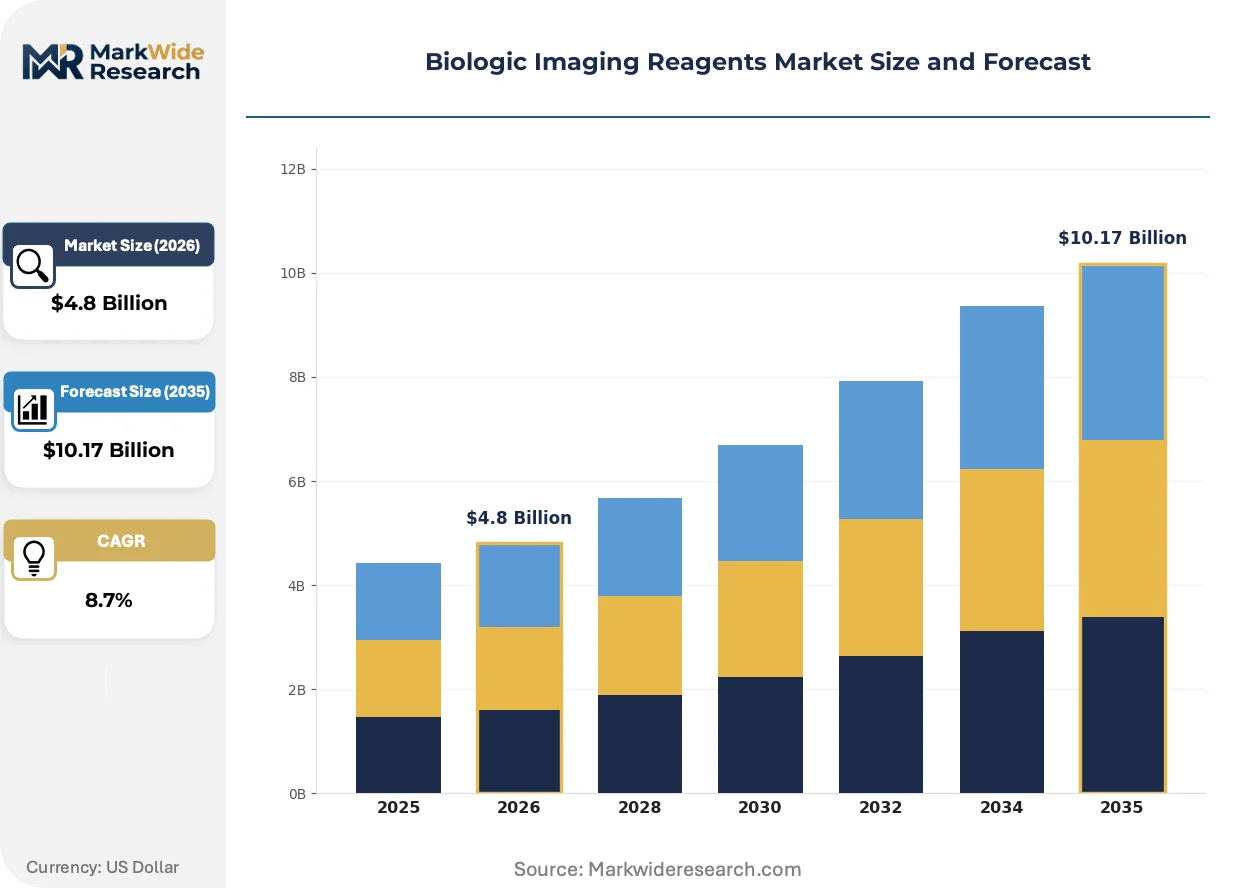
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent Dyes, MRI Contrast Agents, Radioactive Tracers, Bioluminescent Probes Technology: Optical Imaging, Nuclear Imaging, Ultrasound Imaging, Magnetic Resonance Imaging Application: In Vivo Imaging, In Vitro Diagnostics, Preclinical Studies, Drug Development End User: Research Laboratories, Pharmaceutical Companies, Diagnostic Centers, Academic Institutions |
| Companies Covered | Bayer AG, Thermo Fisher Scientific Inc, GE HealthCare, Bracco, Guerbet, PerkinElmer Inc, Siemens Healthineers, Luminex Corporation, Lantheus Holdings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biologic Imaging Reagents Market Emerging Trajectories
Artificial intelligence is compressing radiotracer development timelines by predicting protein binding kinetics before wet-lab synthesis, while decentralized manufacturing models challenge centralized reactor economics.
Copper-64 radiochemistry is bifurcating the PET tracer landscape between cyclotron-dependent and generator-accessible production pathways. Regional cancer centers without on-site isotope infrastructure are adopting zinc-68/copper-64 generators for same-day antibody imaging. This bifurcation is compressing the addressable market for fluorine-18 FDG in neuro-oncology applications where longer half-lives enable delayed imaging protocols.
EMA's centralized marketing authorization for radiopharmaceuticals under pharmaceutical legislation is harmonizing batch release standards across member states. Manufacturers previously navigating 27 national competent authorities now face unified Good Manufacturing Practice inspections and centralized quality documentation. Small and mid-sized radiochemistry firms are consolidating quality assurance functions or exiting the market rather than absorbing compliance overhead.
Academic medical centers are unbundling contrast agent procurement from equipment service contracts, reversing decade-long bundled purchasing arrangements. Procurement teams now negotiate tracer pricing separately from MRI and PET scanner maintenance agreements, introducing competitive bidding for gadolinium and iron oxide formulations. This unbundling is most pronounced in the United States, where hospital system consolidation has centralized purchasing authority at the IDN level.
Biologic Imaging Reagents Market Segmentation
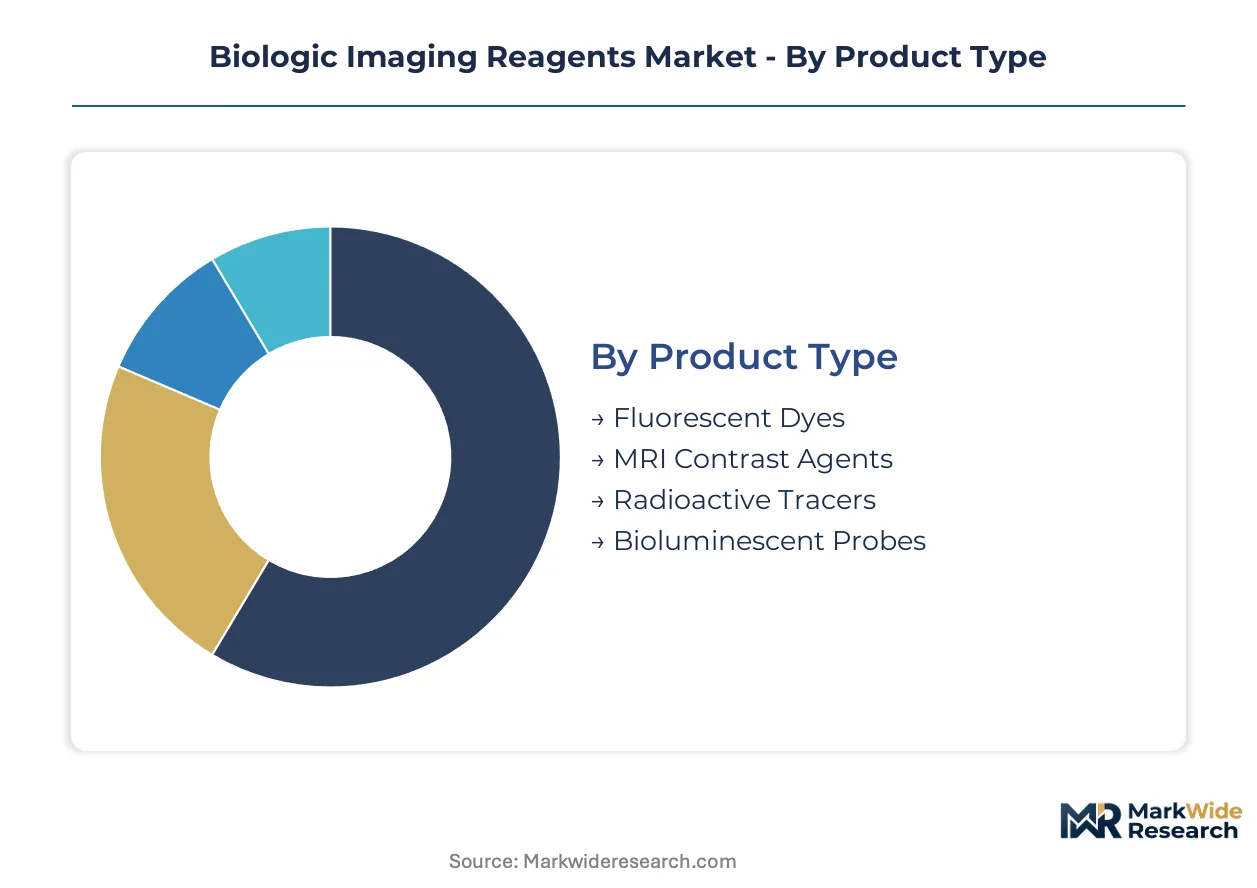
Biologic imaging reagents serve divergent technical requirements across preclinical research, clinical diagnostics, and therapeutic monitoring. Segmentation reveals how supply chains, regulatory pathways, and procurement patterns fragment across product chemistries and imaging modalities.
Product Type:
Domestic production dominates MRI contrast agents and fluorescent dyes, while radioactive tracers depend on cross-border isotope supply chains concentrated among five government-operated research reactors.
- Radioactive Tracers:Radiolabeled compounds with half-lives ranging from minutes to days enable PET and SPECT visualization of metabolic processes. Demand concentrates at academic medical centers in the United States and Germany as theranostic protocols expand oncology service lines. Supply vulnerability from aging reactor infrastructure constrains procurement security.
- MRI Contrast Agents:Gadolinium-based and iron oxide formulations enhance tissue differentiation in magnetic resonance systems. German and Japanese diagnostic centers drive premium-grade procurement as high-field scanner penetration deepens. Gadolinium retention liability compresses pricing power for linear chelate variants.
- Fluorescent Dyes:Organic fluorophores and quantum dots serve preclinical optical imaging with emission spectra tunable across visible and near-infrared ranges.
- Bioluminescent Probes:Luciferase substrates and engineered reporter systems enable longitudinal tracking in small-animal models without external excitation sources.
MRI contrast agents hold the largest share; momentum sits with radioactive tracers.
Technology:
Capital intensity creates a three-tier cost structure: optical systems at entry-level investment, MRI at premium infrastructure, and nuclear imaging at the highest capital and regulatory burden.
- Nuclear Imaging:PET and SPECT modalities detect gamma-ray emissions from administered radiopharmaceuticals, requiring cyclotron or generator infrastructure and specialized radiochemistry personnel. United States community hospitals accelerate PET-CT procurement under IRA reimbursement incentives. Isotope supply concentration creates procurement risk for centers without multi-year offtake agreements.
- Magnetic Resonance Imaging:Magnetic field gradients and radiofrequency pulses generate high-resolution anatomical and functional data without ionizing radiation. Japanese and German healthcare systems sustain premium pricing for gadolinium-enhanced protocols. Scanner utilization rates drive reagent consumption patterns at hospital system scale.
- Optical Imaging:Fluorescence and bioluminescence systems dominate preclinical research with lower capital barriers and faster image acquisition.
- Ultrasound Imaging:Microbubble contrast agents enhance echogenicity for vascular and perfusion assessment in cardiology and hepatology applications.
Magnetic resonance imaging commands the dominant installed base; nuclear imaging gains share fastest as theranostic adoption accelerates.
Application:
Volume concentrates in clinical diagnostics, while value per procedure peaks in drug development where tracer validation supports billion-dollar therapeutic decisions.
- Drug Development:Pharmacokinetic imaging guides candidate selection and biomarker validation across oncology, neurology, and immunology pipelines. United States pharmaceutical R&D hubs in Boston and San Francisco drive demand for novel radiochemistry and longitudinal imaging protocols. Regulatory submission requirements for companion diagnostics elevate specification thresholds.
- In Vivo Imaging:Whole-organism visualization tracks disease progression and treatment response in clinical and preclinical settings. German academic medical centers expand theranostic service lines with lutetium-177 based protocols. Reimbursement parity variations across national systems shape procurement patterns.
- In Vitro Diagnostics:Cell-based and tissue-based assays utilize fluorescent and luminescent reagents for high-throughput screening.
- Preclinical Studies:Small-animal imaging platforms enable mechanistic research and early safety assessment before human translation.
In vivo imaging holds the largest share; drug development commands the steepest expansion trajectory.
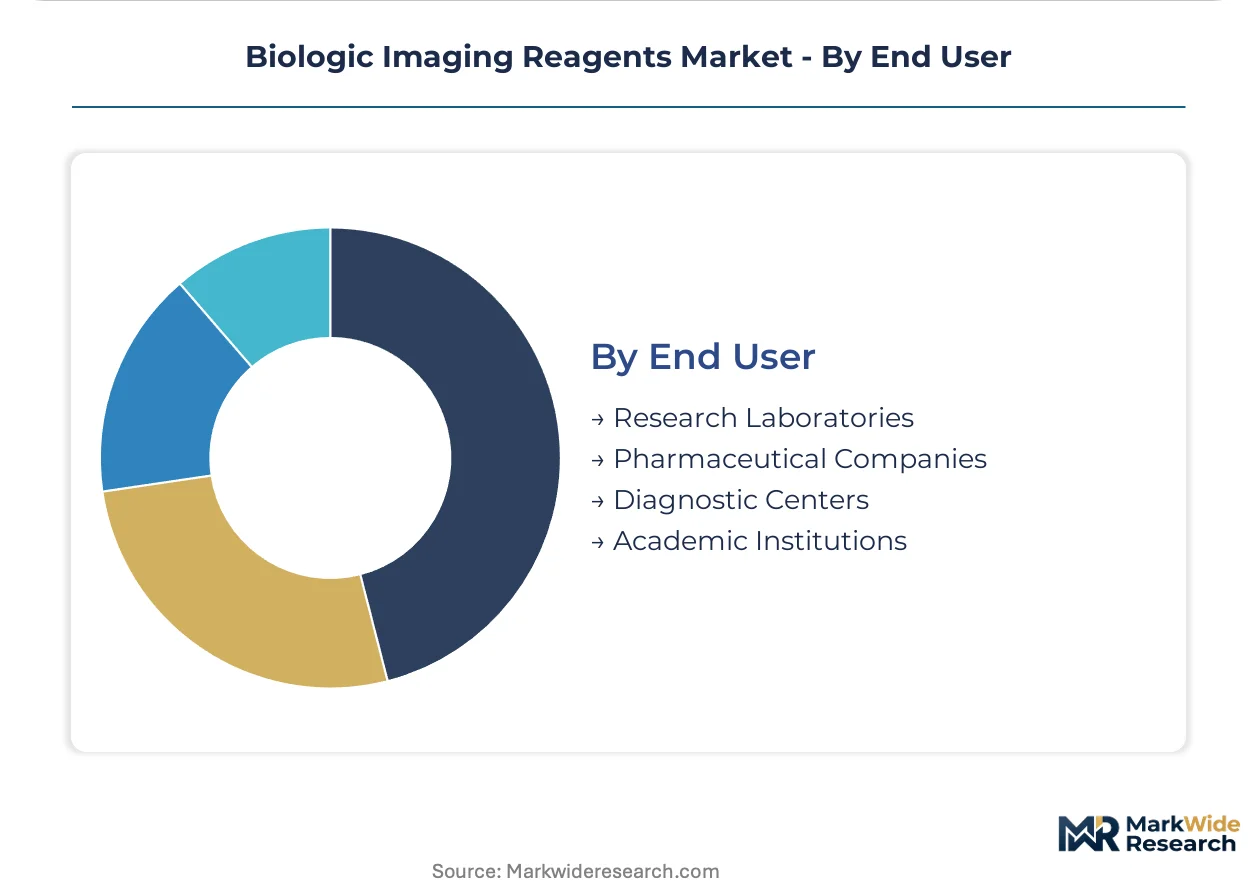
End User:
Procurement authority is centralizing as hospital system consolidation and pharmaceutical vertical integration reshape vendor relationships.
- Pharmaceutical Companies:Internal radiochemistry capabilities and external CDMO partnerships support therapeutic pipeline imaging requirements. United States and Swiss firms invest in alpha-emitter theranostic production partnerships ahead of commercialization. Talent scarcity forces competitive recruitment of PhD-level synthesis specialists.
- Diagnostic Centers:Independent imaging facilities and hospital-affiliated radiology departments consume contrast agents and tracers at procedure volume scale. Community hospital networks in underserved United States counties accelerate PET-CT deployment under IRA payment adjustments. Unbundling of reagent procurement from equipment service contracts introduces price competition.
- Research Laboratories:Academic and government facilities drive fluorescent dye and bioluminescent probe consumption for mechanistic biology.
- Academic Institutions:Medical schools and teaching hospitals integrate imaging reagents across clinical service, research, and training missions.
Diagnostic centers hold the largest share; pharmaceutical companies are expanding procurement fastest as theranostic pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for clinical-grade radiopharmaceuticals concentrates in Germany and the United States, where reimbursement premiums for theranostic protocols exceed margins available in price-controlled national systems by substantial multiples. Japanese and Swiss healthcare systems sustain premium-grade procurement through specialized high-field scanner networks. Indian manufacturing hubs exploit regulatory arbitrage for export-oriented tracer production.
United States
Academic medical centers in Boston and Houston expand lutetium-177 theranostic service lines as Medicare reimbursement adjustments under the Inflation Reduction Act accelerate PET-CT deployment in underserved counties. The FDA's Center for Drug Evaluation and Research streamlines diagnostic agent approval pathways. Philadelphia and San Francisco pharmaceutical R&D clusters drive demand for novel radiochemistry supporting billion-dollar therapeutic decisions.
Germany
Diagnostic centers in Munich and Heidelberg sustain premium pricing for gadolinium-enhanced MRI protocols as high-field scanner penetration deepens in university hospital networks. The EMA enforces centralized marketing authorization for radiopharmaceuticals under pharmaceutical legislation. The Mannheim-Heidelberg cancer cluster anchors theranostic research partnerships between university hospitals and radiopharmaceutical manufacturers.
Japan
Tokyo and Osaka metropolitan healthcare systems maintain premium procurement for MRI contrast agents optimized for 3-tesla and 7-tesla magnetic resonance infrastructure. METI supports domestic isotope production capabilities through targeted industrial policy. The Kobe biomedical innovation cluster integrates radiochemistry research with pharmaceutical development pipelines.
India
Contract manufacturing organizations in Hyderabad and Ahmedabad attract radiopharmaceutical production investments through CDSCO fast-track approval pathways for export-oriented tracer synthesis. The country's national pharmaceutical regulator harmonizes batch release standards with EMA and FDA requirements. Gujarat's pharmaceutical manufacturing corridor expands Good Manufacturing Practice facility capacity for European and North American export markets.
Switzerland
Basel and Zurich pharmaceutical headquarters drive demand for companion diagnostic imaging reagents supporting therapeutic pipeline decisions. Swissmedic enforces stringent quality management standards for clinical-grade radiopharmaceutical manufacturing. The Basel biotech cluster concentrates radiochemistry talent and isotope production partnerships for alpha-emitter theranostic development.
Biologic Imaging Reagents Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated radiopharmaceutical manufacturers commanding supply continuity premiums while distribution-focused competitors compete on procurement efficiency and geographic reach. The market structure fragments across three tiers: multinational conglomerates with captive isotope infrastructure, specialized radiochemistry firms with therapeutic partnerships, and regional distributors serving diagnostic center networks. Dominant competitive moves include production partnership formation for alpha-emitter access and quality assurance function consolidation to absorb EMA compliance overhead.
Within the integrated manufacturing tier, Bayer AG and GE HealthCare exemplify archetypes combining radiopharmaceutical synthesis with diagnostic equipment ecosystems. Thermo Fisher Scientific occupies a position bridging research laboratory supply and clinical diagnostic distribution across multiple geographies. These three anchors represent distinct strategic postures: captive isotope production, equipment-reagent bundling, and channel scale respectively.
| Leading Market Players |
|---|
| Bayer AG |
| Thermo Fisher Scientific Inc |
| GE HealthCare |
| Bracco |
| Guerbet |
| PerkinElmer Inc |
| Siemens Healthineers |
| Luminex Corporation |
| Lantheus Holdings Inc |
| Others |
Supply Flow & Price Mechanics
Copper-64 generator systems displacing cyclotron-dependent fluorine-18 production are redrawing supply geography toward regional diagnostic networks while compressing pricing premiums for same-day synthesis capabilities. This substitution simultaneously fragments procurement authority across community hospital systems and erodes the volume-based discounts that academic medical centers once commanded.
Pricing Analysis
The customization-premium spread between patient-matched theranostic protocols and standard FDG imaging runs three to fivefold in United States reimbursement schedules. Three-tier pricing structure across premium, standard, and economy levels tracks binding affinity specifications and isotope half-life requirements. Cost compression in standard-grade gadolinium formulations is intensifying because unbundled procurement from equipment service contracts exposes linear chelate variants to competitive bidding. Hospital procurement committees at integrated delivery networks exhibit highest price sensitivity, while pharmaceutical R&D divisions tolerate premium positioning for companion diagnostic validation.
Supply Chain Analysis
Inventory buffers for technetium-99m extend to six weeks at major United States distributors, though generator shelf-life constraints prevent meaningful stockpiling beyond this threshold. Isotope supply concentrates in Belgium, Netherlands, and South Africa where five aging research reactors process molybdenum-99 recovery. Raw material dependencies encompass highly enriched uranium targets, ultrapure water exceeding 18.2 MΩ·cm resistivity, and specialized gadolinium chelation precursors. Single-source vulnerability from scheduled reactor maintenance cycles forces imaging centers into multi-year offtake agreements. Distribution runs through radiopharmaceutical-specialized logistics networks with cold-chain requirements for generator transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating at the integrated delivery network level as hospital system consolidation centralizes radiopharmaceutical procurement decisions across multi-state footprints.
For Market Incumbents: Secure multi-year isotope offtake agreements ahead of reactor decommissioning schedules to lock in supply continuity premiums. Invest in captive gallium-68 and copper-64 generator production capabilities to defend against cyclotron miniaturization displacing centralized tracer synthesis. The threat of AI-integrated quantification standardizing uptake value measurements is eroding proprietary algorithm advantages. For New Entrants and Emerging Players: Differentiate on alpha-emitter theranostic production partnerships targeting metastatic prostate cancer imaging protocols. White-space opportunities concentrate in India's CDSCO fast-track pathway for export-oriented tracer manufacturing and in decentralized fluorine-18 cyclotron placement at underserved United States community hospitals. A contract development and manufacturing organization positioning with EMA-harmonized quality systems offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: The market sits at a theranostic convergence phase that favors radiochemistry specialists with isotope access partnerships over equipment-reagent bundlers. Long-term viability over the next decade hinges on alpha-emitter pipeline positioning and talent retention in PhD-level synthesis roles. Acquisition targets should display captive isotope infrastructure or exclusive generator distribution rights. The signal to watch is Medicare reimbursement parity adjustments for generator-based versus cyclotron-produced tracers.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Decommissioning Risk Mitigation | Securing alternative molybdenum-99 supply channels prevents tracer shortages at United States imaging centers. |
| Alpha-Emitter Production Partnership | Actinium-225 access agreements create first-mover positioning in metastatic prostate cancer theranostics. |
| CDSCO Fast-Track Manufacturing Investment | Hyderabad and Ahmedabad facilities exploit regulatory arbitrage for European and North American export markets. |
| AI-Integrated Quantification Development | Machine learning algorithms for standardized uptake value harmonization enable multi-site clinical trial enrollment. |
| Radiochemist Talent Pipeline Securement | Exclusive recruitment from the seven United States PhD programs replaces retiring synthesis specialists. |
Methodological Framework
A spread of perspectives from radiopharmaceutical manufacturing executives, hospital procurement directors, regulatory affairs specialists, and academic radiochemistry faculty converged on the working assumptions underlying this analysis. Primary interviews with cyclotron operators and generator distributors were cross-referenced against secondary validation from FDA 510(k) filings, EMA centralized marketing authorization submissions, CMS Medicare reimbursement databases, and ISO 13485 audit records. Bottom-up procedure volume estimates and top-down radiopharmaceutical production capacity assessments were triangulated to constrain forecast variance.
Segmentation dimensions modeled include product chemistry class, imaging modality capital intensity tier, application purpose across diagnostic versus therapeutic monitoring, and end-user procurement authority structure. CAGRs were derived from elasticity-adjusted procedure volume projections and pricing trajectory assumptions across the projection horizon. Industry-specific forecast inputs encompassed PET-CT scanner deployment rates under IRA reimbursement incentives and lutetium-177 protocol adoption curves at academic medical centers.
Forecasts assume regulatory continuity in FDA diagnostic agent approval pathways and EMA centralized marketing authorization procedures; material policy shifts would require re-modeling. Specific risks that could revise trajectory include accelerated reactor decommissioning, gadolinium retention liability reclassification, and radiochemist training program closures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market