
 Global Laboratory Centrifuge Market | 2026-2036
Global Laboratory Centrifuge Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Centrifuge Market Foresight
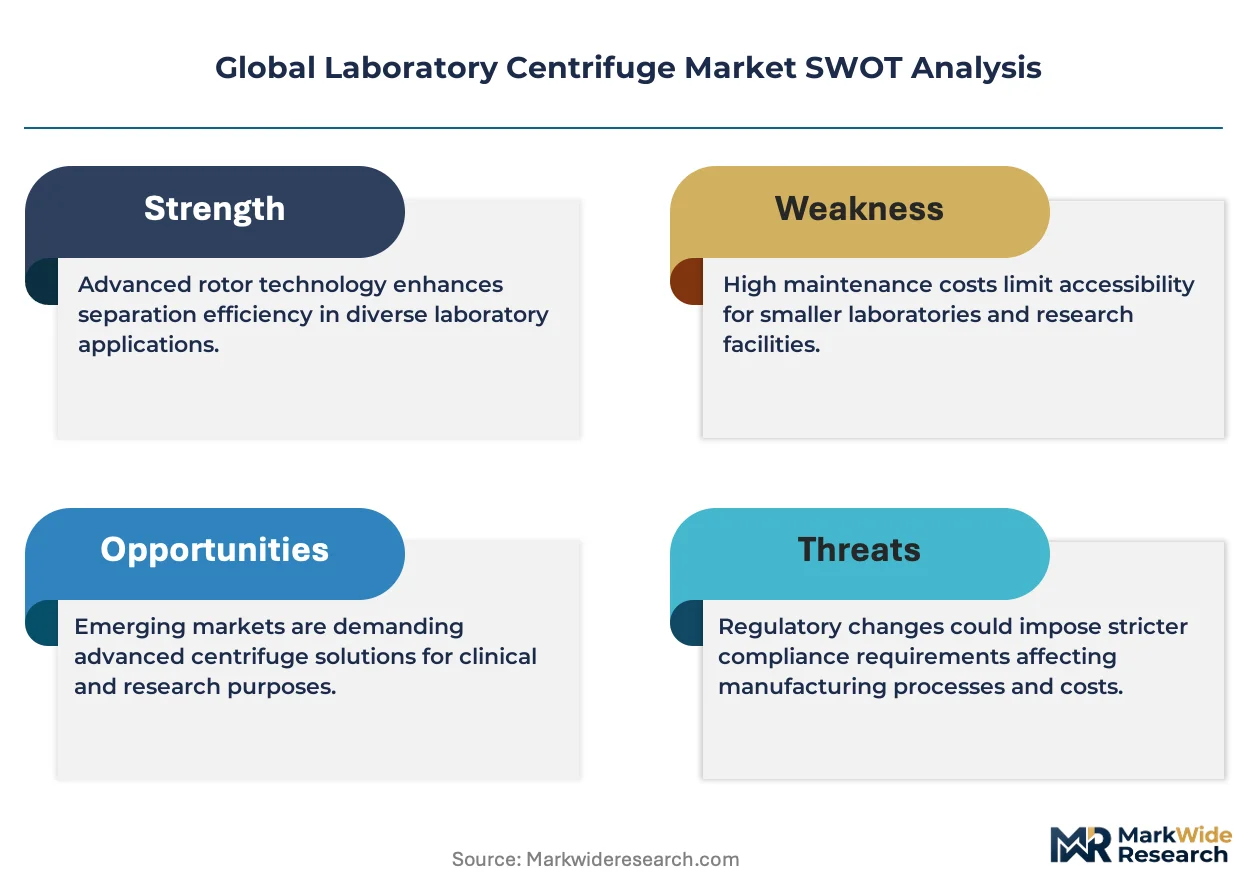
European precision engineering clusters is recalibrating supply chains for high-performance rotor assemblies. Thermo Fisher Scientific leverages vertical integration across analytical instrumentation to sustain pricing power in ultracentrifuge segments. Danaher Corporation anchors its position through diagnostic workflow integration, while Eppendorf SE differentiates via specialization in microcentrifuge platforms for molecular biology workflows.
A laboratory centrifuge is a motor-driven device that generates centrifugal force measured in relative centrifugal force (RCF) or revolutions per minute (RPM) to separate components of heterogeneous mixtures based on density differentials. Its primary purpose spans cell pelleting, virus purification, blood component fractionation, and nanoparticle isolation across research and clinical settings. Benchtop centrifuges occupy the highest volume tier due to universal laboratory deployment, while ultracentrifuges command premium positioning through extreme RCF thresholds exceeding 100,000 x g for subcellular fractionation. Refrigerated units are gaining structural importance as temperature-sensitive sample protocols expand in genetic research and biopharmaceutical quality control.
The FDA enforces Good Laboratory Practice standards that mandate centrifuge calibration documentation for preclinical drug safety studies, directly shaping procurement specifications in contract research organizations. The EU Medical Device Regulation and ISO 13485 quality management framework constrain market access for non-compliant manufacturers while elevating service revenue attachment rates. Stakeholders must monitor rotor material innovations, particularly carbon fiber composites, and evolving biosafety containment requirements as cell and gene therapy manufacturing scales beyond research volumes.
Market Dynamics
Carbon fiber rotor assemblies are compressing equipment weight thresholds while EU MDR documentation mandates reshape vendor qualification protocols across diagnostic supply chains.
Growth Catalysts
- Cell therapy manufacturing scale-up:Commercial-grade viral vector production requires ultracentrifuge capacity expansion in contract manufacturing organizations. GMP-compliant refrigerated units command priority placement in facility buildouts.
- EU MDR performance documentation:Tightened conformity assessment procedures for laboratory equipment elevate service revenue attachment rates. Manufacturers with established technical files capture procurement preference in European diagnostic networks.
- Carbon fiber composite rotors:Material substitution from aluminum alloys enables higher RPM thresholds with reduced thermal expansion. Precision engineering clusters in Germany and Switzerland supply these components to analytical instrument builders.
Market Restraints
- Specialized alloy supply concentration:Titanium and high-grade aluminum for rotor forging concentrate among German and Japanese metallurgical suppliers. Disruption risks propagate through tier-two component vendors.
- Ultracentrifuge technical floor:Subcellular fractionation protocols demand RCF thresholds exceeding 100,000 x g with vacuum containment. These specifications restrict viable supplier pools to established precision manufacturers.
- FDA GLP calibration mandates:Preclinical drug safety studies require documented centrifuge performance verification. Contract research organizations face compliance cost burdens that compress capital equipment budgets.
Strategic Opportunities
- India biopharma infrastructure buildout:CDSCO-aligned manufacturing facilities require analytical instrumentation for biosimilar quality control. Domestic production incentives under PLI schemes attract centrifuge assembly localization.
- Point-of-care blood processing:Decentralized clinical settings deploy compact refrigerated units for rapid component separation. Emergency medicine and rural health networks drive format innovation below traditional benchtop footprints.
- ISO 13485 certification acceleration:Quality management framework adoption opens access to regulated clinical markets. Manufacturers achieving this standard capture diagnostic workflow integration opportunities.
Industry Challenges
- Rotor balancing technician scarcity:Precision dynamic balancing for high-speed assemblies requires specialized metrology skills. Training pipelines lag equipment complexity advancement in manufacturing hubs.
- Legacy system integration friction:Modern centrifuge data outputs must interface with established laboratory information management systems. Middleware development extends deployment timelines in research institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Centrifuge Market |
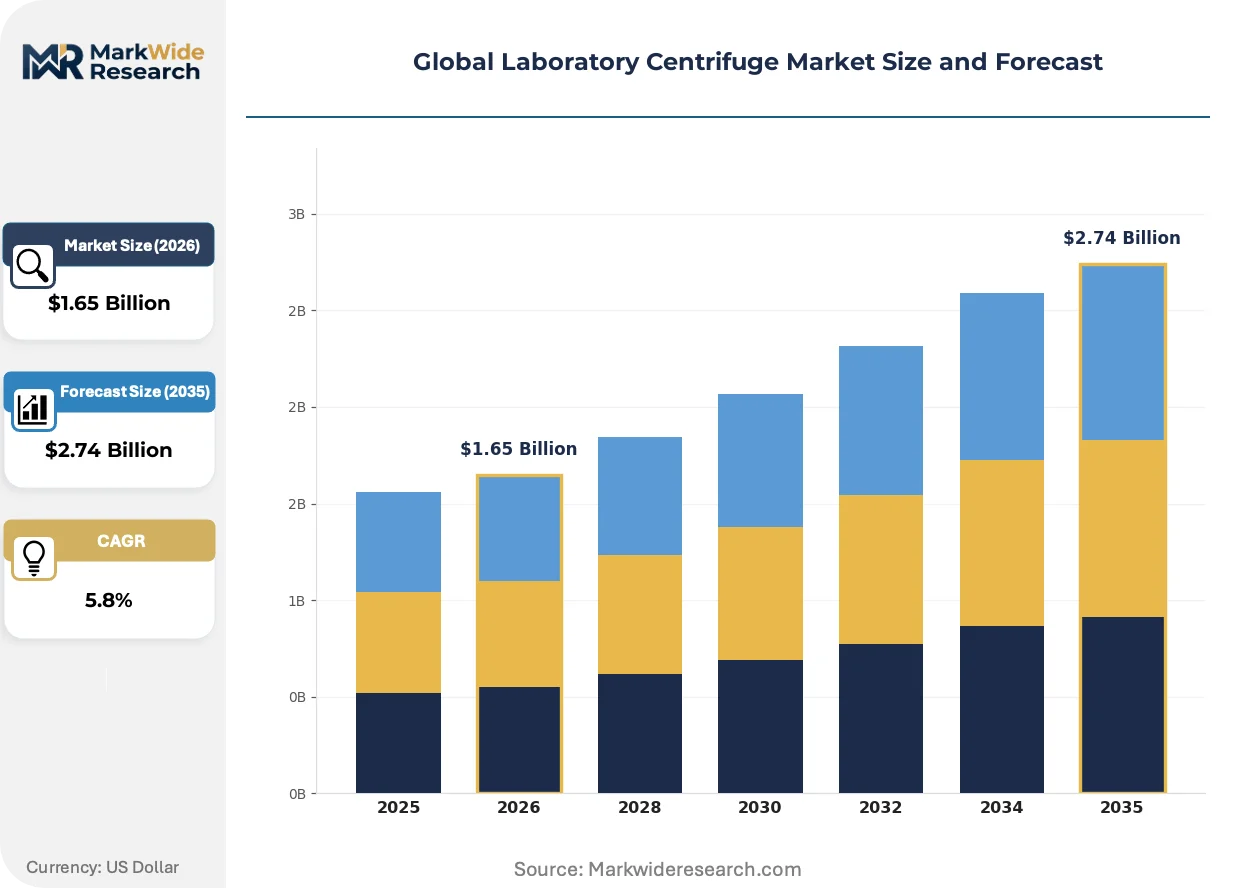
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.74 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Floor Standing, Microcentrifuge, Ultracentrifuge, Refrigerated Technology: Fixed Angle Rotor, Swing Bucket Rotor, Continuous Flow, Vacuum, High Speed Application: Pharmaceutical Testing, Food Safety Analysis, Genetic Research, Environmental Testing, Forensic Analysis End User: Academic Research Labs, Biotechnology Firms, Diagnostic Centers, Government Laboratories |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Eppendorf SE, Andreas Hettich GmbH, Sartorius AG, Sigma Laborzentrifugen GmbH, HERMLE Labortechnik GmbH, KUBOTA Corporation, QIAGEN N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Centrifuge Market Shifts & Advancements
Connected instrumentation protocols and advanced materials science are reconfiguring equipment specifications while regulatory documentation requirements intensify across major jurisdictions.
Carbon fiber composite rotor technology is decentralizing manufacturing location requirements for high-performance centrifuge assemblies. Cell therapy producers in Singapore and South Korea adopt these lighter rotors to reduce facility structural load constraints. The shift enables modular cleanroom deployments that previously required reinforced flooring for aluminum rotor systems.
REACH substance restrictions on perfluorinated compounds are compelling seal and gasket material substitutions in refrigerated centrifuge designs. Manufacturers reformulate vacuum chamber components to maintain thermal performance without restricted fluoropolymers. European diagnostic equipment vendors face compressed reformulation timelines ahead of authorization sunset dates.
Service contract unbundling is fragmenting traditional equipment procurement relationships. Academic research institutions in the United States negotiate à la carte maintenance arrangements separate from capital purchases. This pattern compresses manufacturer recurring revenue predictability while expanding third-party calibration provider market entry.
Global Laboratory Centrifuge Market Segmentation
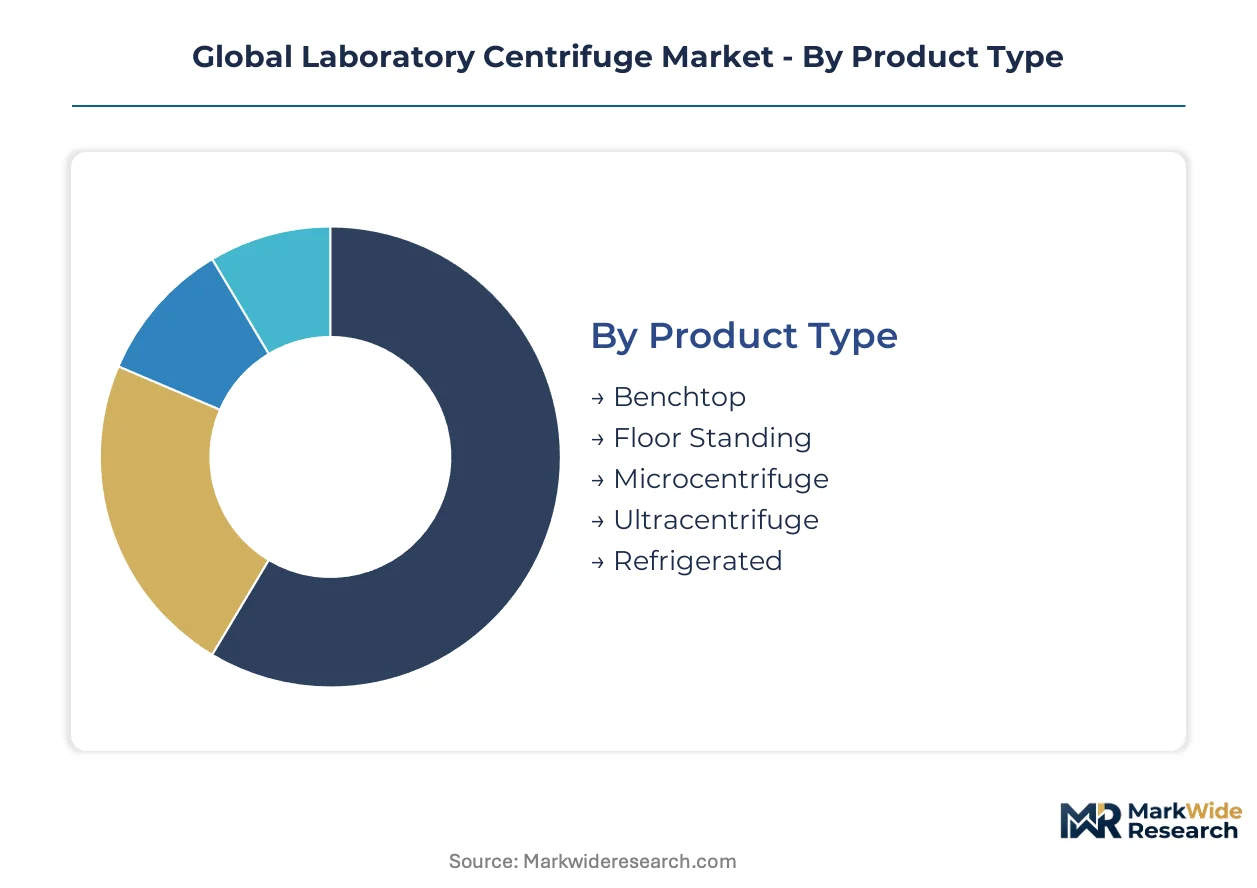
Centrifuge procurement decisions pivot on rotor specifications, thermal control requirements, and protocol complexity. Each segmentation axis reveals distinct vendor qualification criteria and service revenue attachment patterns across research and clinical workflows.
Product Type:
Rotor speed thresholds and thermal management capabilities define equipment classification and facility infrastructure requirements.
- Benchtop:Compact units delivering moderate RCF up to 25,000 x g dominate universal laboratory deployment. Diagnostic networks in Germany and academic institutions in the United States prioritize these for routine blood processing and cell pelleting protocols.
- Floor Standing:High-capacity systems accommodate larger sample volumes with enhanced stability at elevated speeds. Biotechnology firms expanding viral vector manufacturing in Singapore and South Korea specify these for GMP-compliant production suites.
- Microcentrifuge:Specialized for microtube processing in molecular biology workflows. Eppendorf SE anchors this segment through precision speed control and compact footprints.
- Ultracentrifuge:Extreme RCF exceeding 100,000 x g enables subcellular fractionation and nanoparticle isolation. Vacuum containment and refrigeration integration restrict viable suppliers to precision engineering specialists.
- Refrigerated:Active cooling maintains sample integrity during extended runs. Temperature-sensitive genetic research protocols and biopharmaceutical quality control drive specification priority.
Benchtop leads on scale; refrigerated leads on momentum.
Technology:
Rotor geometry and containment architecture determine separation efficiency, sample recovery rates, and biosafety compliance.
- Fixed Angle Rotor:Rigid tube holders generate rapid pelleting with minimal wall contact. Pharmaceutical testing laboratories in Switzerland and diagnostic centers in Japan favor these for high-throughput screening protocols.
- Swing Bucket Rotor:Horizontal tube orientation during centrifugation produces flat pellet surfaces and cleaner supernatant recovery. Density gradient separations in cell therapy manufacturing require this configuration.
- Continuous Flow:Enables uninterrupted processing of large liquid volumes without batch interruption. Industrial-scale viral vector purification in contract manufacturing organizations deploys these systems.
- Vacuum:Reduced air friction permits higher rotational speeds with diminished thermal generation. Ultracentrifuge specifications mandate vacuum containment for subcellular applications.
- High Speed:RCF thresholds between 20,000 and 100,000 x g bridge routine and ultracentrifuge domains. Carbon fiber rotor materials from German precision clusters enable weight reduction at these specifications.
Fixed angle leads on volume; swing bucket leads on bioprocessing adoption.
Application:
Protocol stringency and regulatory oversight intensity vary sharply across end-use contexts.
- Pharmaceutical Testing:FDA GLP documentation mandates and EMA stability study requirements enforce calibration traceability. Contract research organizations face compressed capital budgets from compliance cost burdens.
- Food Safety Analysis:Pathogen detection and contaminant isolation protocols demand reliable pelleting performance. Government laboratories in France and Italy specify mid-speed refrigerated units for mycotoxin and bacterial screening.
- Genetic Research:DNA/RNA extraction and plasmid preparation require precise speed control and temperature maintenance. Academic research labs in the United States and Germany drive microcentrifuge specifications.
- Environmental Testing:Sediment analysis and pollutant concentration from water and soil samples. Standard benchtop configurations satisfy most protocol requirements.
- Forensic Analysis:Blood component separation and trace evidence processing demand chain-of-custody documentation. ISO 17025 accreditation shapes procurement specifications.
Pharmaceutical testing leads on specification intensity; genetic research leads on unit volume.
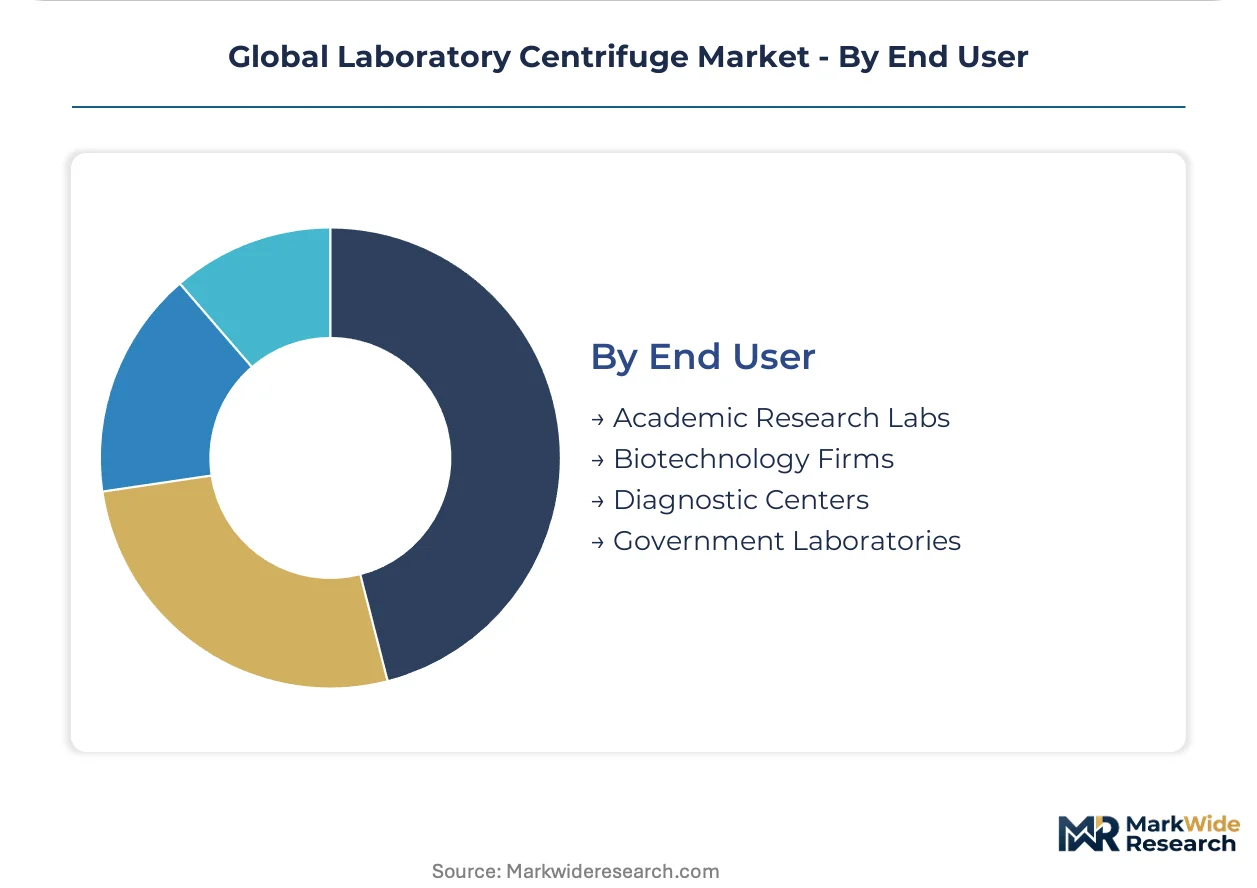
End User:
Capital allocation flexibility and service contract preferences diverge across institutional categories.
- Academic Research Labs:Grant-dependent funding cycles favor mid-tier benchtop and microcentrifuge procurement. Service contract unbundling trends in the United States compress manufacturer recurring revenue predictability.
- Biotechnology Firms:Cell therapy manufacturing scale-up drives ultracentrifuge and refrigerated unit investment. GMP compliance requirements elevate vendor qualification thresholds.
- Diagnostic Centers:High-throughput routine processing prioritizes reliability and rapid maintenance response. EU MDR performance documentation reshapes European procurement protocols.
- Government Laboratories:Public procurement regulations and multi-year budget cycles extend equipment replacement timelines. Standardization across facility networks favors established supplier relationships.
Biotechnology firms lead on premium unit acquisition; diagnostic centers lead on installed base scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing centrifuge manufacturing capacity toward jurisdictions with streamlined conformity pathways. German precision engineering clusters retain premium rotor assembly dominance while Asian biopharma infrastructure investments accelerate localized procurement.
United States
FDA GLP calibration mandates drive specification intensity in contract research organizations. Preclinical drug safety studies require documented centrifuge performance verification, elevating vendor qualification thresholds. The Greater Boston biotech corridor concentrates demand for GMP-compliant refrigerated units.
Germany
EU MDR performance documentation requirements reshape diagnostic network procurement protocols. Tightened conformity assessment procedures elevate service revenue attachment rates. Precision engineering clusters in Baden-Württemberg supply carbon fiber rotor systems to analytical instrument builders.
China
NMPA medical device registration reforms accelerate domestic centrifuge manufacturer certification timelines. Biosimilar quality control expansion drives analytical instrumentation demand. Yangtze River Delta biopharma zones prioritize localized supply chain development.
India
CDSCO-aligned manufacturing facilities require centrifuge capacity for biosimilar production quality control. PLI scheme incentives attract analytical instrumentation assembly localization. Maharashtra pharmaceutical clusters drive mid-speed refrigerated unit procurement.
Japan
PMDA quality management enforcement maintains stringent vendor qualification for clinical diagnostic equipment. Subcellular fractionation research protocols sustain ultracentrifuge specification priority. Kansai region precision manufacturers supply high-grade titanium rotor forgings.
Global Laboratory Centrifuge Market Competitive Landscape
German producers anchor one tier; US specialists hold premium analytical instrumentation positions. The vendor base stratifies across precision engineering specialists, diversified life science conglomerates, and regional equipment fabricators. Three archetypes dominate: rotor technology specialists, workflow-integrated platform providers, and cost-optimized volume manufacturers. Competitive moves concentrate on M&A for diagnostic workflow integration and carbon fiber composite rotor material substitution.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify platform breadth strategies. Eppendorf SE occupies a specialized position in microcentrifuge platforms for molecular biology workflows. These three entities represent contrasting archetypes: vertical integration across analytical instrumentation, diagnostic workflow anchoring, and sub-segment specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Eppendorf SE |
| Andreas Hettich GmbH |
| Sartorius AG |
| Sigma Laborzentrifugen GmbH |
| HERMLE Labortechnik GmbH |
| KUBOTA Corporation |
| QIAGEN N.V. |
| Others |
Supply & Pricing Matrix
Contract research organizations and diagnostic networks in Germany concentrate procurement volumes for high-performance centrifuge systems, anchoring a pricing model that stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. EU MDR compliance costs and rotor material specifications compress margins for non-specialized vendors while elevating pricing power for precision engineering clusters with established technical files.
Pricing Analysis
Distributor margins for analytical instrumentation typically range from 15 to 25 percent, with direct-to-OEM contracts commanding deeper discounts for volume commitments. Pricing stratifies across premium, standard, and economy tiers, with FDA GLP certification and ISO 13485 quality management framework serving as primary differentiation drivers. Cost compression in the mid-speed benchtop segment is intensifying because domestic manufacturers in China and India expand assembly capacity under production-linked incentive schemes. Academic research labs exhibit the highest price sensitivity due to grant-dependent funding cycles, while biotechnology firms acquiring GMP-compliant ultracentrifuges demonstrate the least sensitivity given protocol stringency requirements.
Supply Chain Analysis
Carbon fiber composite and high-grade titanium rotor forgings rest on metallurgical suppliers concentrated in Germany, Japan, and Switzerland. Precision engineering clusters in Baden-Württemberg and the Kansai region supply critical rotor assemblies, while aluminum alloy stock feeds from Chinese and Russian primary metal producers. Single-source vulnerability around vacuum chamber seal materials compounds risk profiles as REACH substance restrictions sunset perfluorinated compound authorizations. Distribution runs through authorized analytical instrumentation distributors with regional service depots, supplemented by direct manufacturer relationships for large diagnostic network accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play between EU MDR compliance burdens in Europe and PLI scheme subsidies in India, where domestic assembly localization reduces landed cost structures for biosimilar quality control equipment.
For Market Incumbents: Deepen backward integration into carbon fiber rotor production to defend margin positions against emerging Asian component suppliers. Expand service contract bundling in European diagnostic networks to capture recurring revenue streams elevated by EU MDR performance documentation mandates. Prioritize certification investment for ISO 13485 quality management framework to maintain procurement preference in regulated clinical markets.
For New Entrants and Emerging Players: Launch via third-party calibration service partnerships to circumvent capital-intensive manufacturing barriers in ultracentrifuge segments. Target India's CDSCO-aligned manufacturing facilities for mid-speed refrigerated units, the most penetrable geography given PLI scheme traction and biosimilar infrastructure buildout. Pursue a white-label OEM supply angle to German precision engineering clusters seeking cost-optimized rotor assembly alternatives.
For Investors and Strategic Acquirers: Diversified life science conglomerates are the most active acquirer in this space, seeking diagnostic workflow integration capabilities. Long-term viability centers on rotor material substitution patents and GMP-compliant service network density rather than unit volume scale. Watch carbon fiber composite adoption rates in Asian cell therapy manufacturing facilities as the inflection indicator for technology displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Rotor Patent Acquisition | Secures material substitution moats against aluminum forging incumbents in German precision clusters. |
| ISO 13485 Certification Acceleration | Opens diagnostic workflow integration opportunities in EU MDR-regulated European networks. |
| India PLI Scheme Localization | Reduces landed costs for CDSCO-aligned biosimilar quality control equipment procurement. |
| Service Contract Rebundling | Restores recurring revenue predictability compressed by academic institution unbundling trends. |
| Vacuum Chamber Seal Reformulation | Addresses REACH sunset dates for perfluorinated compounds in refrigerated centrifuge designs. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with centrifuge procurement managers at contract research organizations, biomedical engineers at biotechnology firms, and GPO contracts managers at diagnostic networks. Secondary validation draws from FDA 510(k) filings, EMA medical device registrations, NMPA certification databases, and ISO 13485 audit records. Bottom-up equipment shipment estimates triangulate against top-down analytical instrumentation market assessments.
Rate-of-change decomposition separates volume expansion from price realization across the projection horizon. Segmentation dimensions modeled include rotor speed tier, thermal management configuration, application protocol stringency, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and biopharma facility buildout pipelines. Forecast inputs incorporate cell therapy manufacturing capacity announcements and EU MDR technical file submission timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rotor material supply disruption or accelerated REACH substance restriction enforcement. Forecasts reflect documented assumptions regarding biopharma capital expenditure continuity and diagnostic network consolidation patterns. A small set of named triggers warrants ongoing watch: carbon fiber composite adoption inflection, CDSCO manufacturing facility commissioning rates, and EU MDR notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Bioprocess Analyzers and Technology Market
Biotechnology Equipment
Single-Use Bioprocess Sensor Calibration and Validation Test Systems Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Biotechnology Instrumentation Market
Biotechnology Equipment
Bioprocessing Analytics Equipment Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Global Cryostat Microbiome Equipment Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Biosurgery Equipment Market