
 Global Life Science Reagents Market | 2026-2036
Global Life Science Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Life Science Reagents Market Intelligence
Chinese contract manufacturers is recalibrating bulk enzyme output to serve Western biopharma clients. Thermo Fisher Scientific leverages its end-to-end workflow portfolio to dominate clinical research channels. Danaher Corporation anchors its position through intensive filtration and chromatography expertise. Merck KGaA differentiates via its rare chemical building-block catalog across European academic networks.
Life science reagents comprise purified biochemical substances, including monoclonal antibodies, recombinant enzymes, fluorescent probes, and formulated buffers, manufactured under ISO 13485 and GMP conditions with defined activity units, endotoxin limits, and lot-to-lot consistency thresholds; these materials enable detection, quantification, and manipulation of biological targets in research and diagnostic settings. Antibodies and enzymes command the largest revenue pools due to their irreplaceability in immunoassay and PCR workflows, while probes and stains are gaining traction in multiplex imaging applications. Genomics and proteomics applications are absorbing the fastest-growing share of specialized reagent spend as single-cell and spatial transcriptomics methods proliferate.
The FDA enforces current Good Manufacturing Practice for in vitro diagnostic reagents under 21 CFR Part 820, while the EMA's In Vitro Diagnostic Regulation mandates performance documentation and traceability across the European supply chain. ISO 13485 certification has become a baseline market-access filter rather than a competitive differentiator for reagent suppliers. Stakeholders must monitor how the EU AI Act and evolving FDA guidance on algorithm-assisted diagnostics reshape validation requirements for reagents paired with automated interpretation platforms.
Market Dynamics
Antibody and enzyme supply chains are consolidating around multi-site GMP manufacturing hubs as biopharma clients demand single-source qualification for complex biologics workflows. This concentration dynamic is reshaping vendor selection criteria and capital allocation patterns across the value chain.
Growth Catalysts
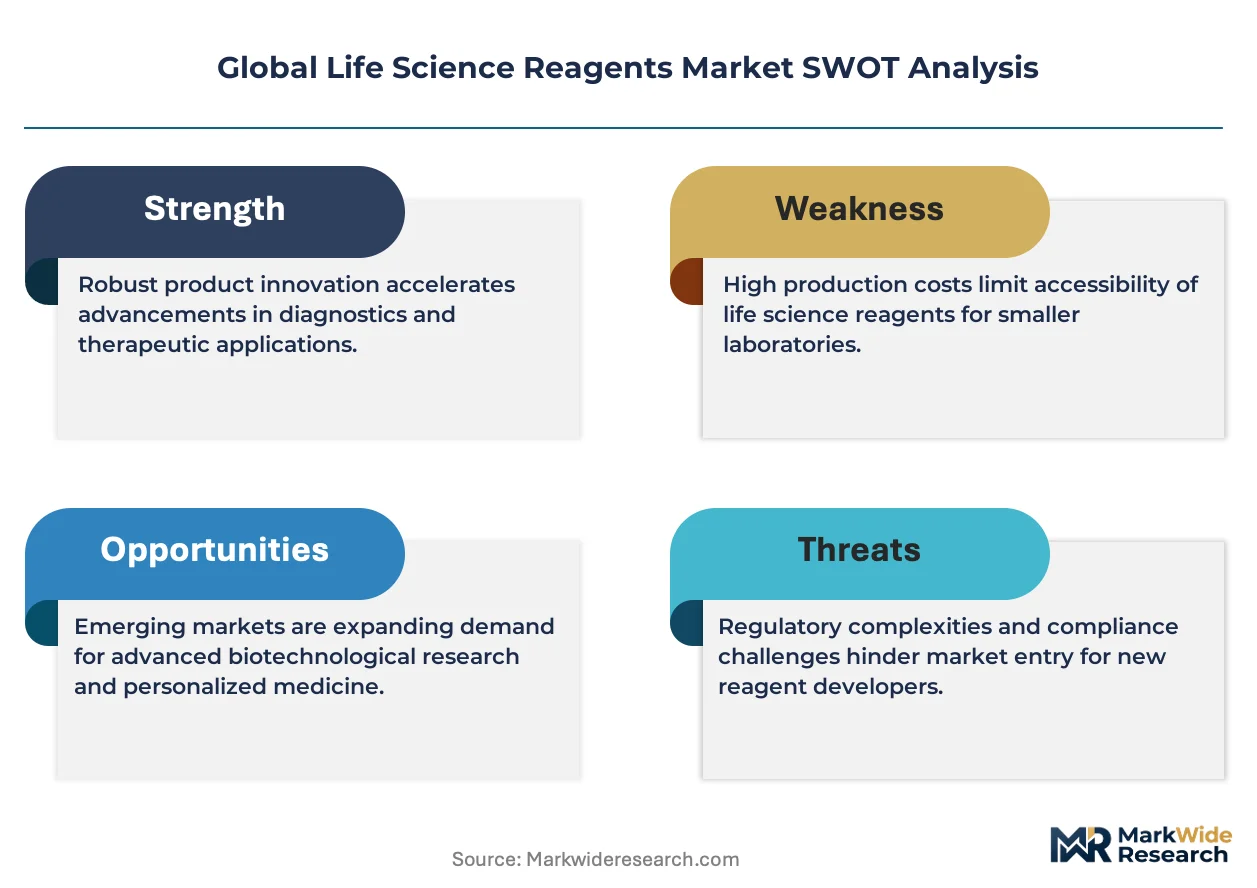
- FDA 21 CFR Part 820 enforcement:Diagnostic manufacturers are upgrading reagent purification protocols to meet tightened quality standards, expanding the addressable market for certified-grade materials.
- Single-cell transcriptomics:Academic and clinical research laboratories are scaling specialized reagent consumption for spatial and multi-omics applications.
- China-Germany-US production triangle:Contract manufacturers across these three markets are absorbing new capacity for monoclonal antibody and recombinant enzyme output.
Market Restraints
- Chromatography resin cost volatility:Protein A and ion-exchange media price swings compress margin structures for antibody purification workflows.
- ISO 13485 certification backlog:Audit queue delays at notified bodies extend time-to-market for new diagnostic reagent suppliers.
- Recombinant protein expression limitations:Yield ceilings in mammalian cell culture constrain bulk enzyme output scaling.
Strategic Opportunities
- EU AI Act compliance services:Reagent vendors can bundle validation documentation for algorithm-assisted diagnostic platforms.
- India CDSCO pathway expansion:Local manufacturing incentives and streamlined IVD registration create entry points for Western suppliers.
- Lyophilized format convergence:Cold-chain-independent reagent formulations unlock distribution into ambient-temperature logistics networks.
Industry Challenges
- GMP facility qualification timelines:Construction and validation of multi-product manufacturing suites demand 24-36 month capital cycles.
- Endotoxin testing capacity:LAL assay bottlenecks at contract testing organizations delay lot release for parenteral-grade reagents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Life Science Reagents Market |
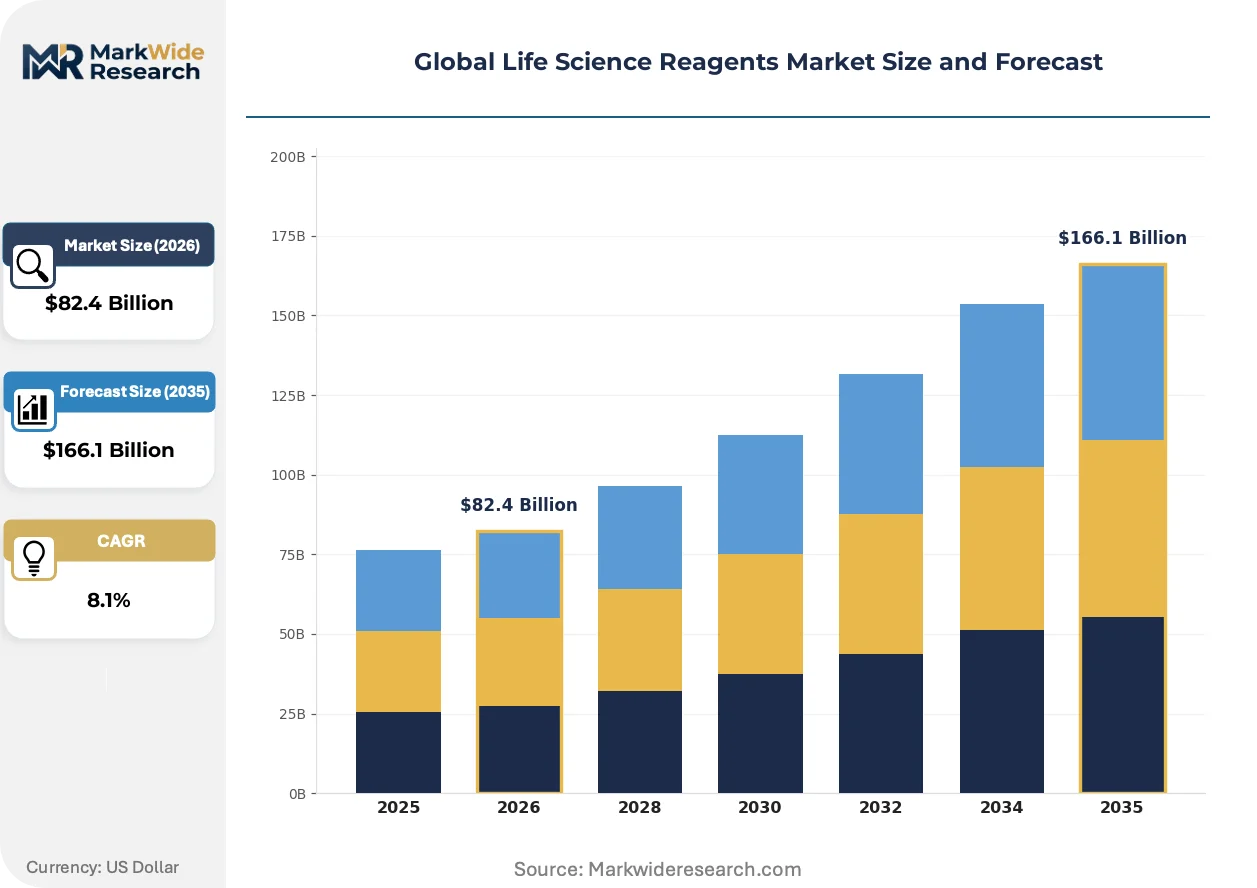
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $166.1 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Enzymes, Probes, Kits, Buffers, Stains Application: Genomics, Proteomics, Cell Biology, Drug Discovery, Diagnostics, Molecular Cloning End User: Research Institutes, Biotechnology Firms, Pharmaceutical Companies, Academic Laboratories, Contract Research Organizations Deployment Model: In-lab Use, Outsourced Services, Automated Platforms, Point-of-Care Testing |
| Companies Covered | Danaher Corporation, Agilent Technologies, Thermo Fisher Scientific, PerkinElmer, Waters Corporation, Merck KGaA, Bio-Rad Laboratories, Becton Dickinson, Roche Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Life Science Reagents Market Strategic Shifts & Innovations
Synthetic biology toolkits and automated formulation platforms are compressing development cycles for customized reagent specifications. These capabilities are enabling demand-responsive production models that challenge traditional catalog-based supply structures.
Lyophilized bead-based reagent formats are overtaking traditional liquid formulations in point-of-care and field-deployed diagnostic applications. Emergency medicine and veterinary testing segments are adopting these ambient-stable configurations fastest. This transition is overtaking established cold-chain infrastructure investments and reshaping regional distribution economics.
EMA's In Vitro Diagnostic Regulation is mandating performance documentation and supply chain traceability across European markets. Manufacturers must maintain post-market surveillance systems and unique device identification for reagent components. Clinical laboratories in Germany, France, and the Netherlands are consolidating supplier lists to reduce compliance overhead.
Biopharma procurement teams are consolidating antibody and enzyme sourcing around qualified contract manufacturers with end-to-end workflow capabilities. Long-term supply agreements with technical service attachments are displacing spot purchasing through distribution intermediaries. This pattern is most pronounced among mid-cap biotechnology companies in the United States and Switzerland.
Global Life Science Reagents Market Segmentation
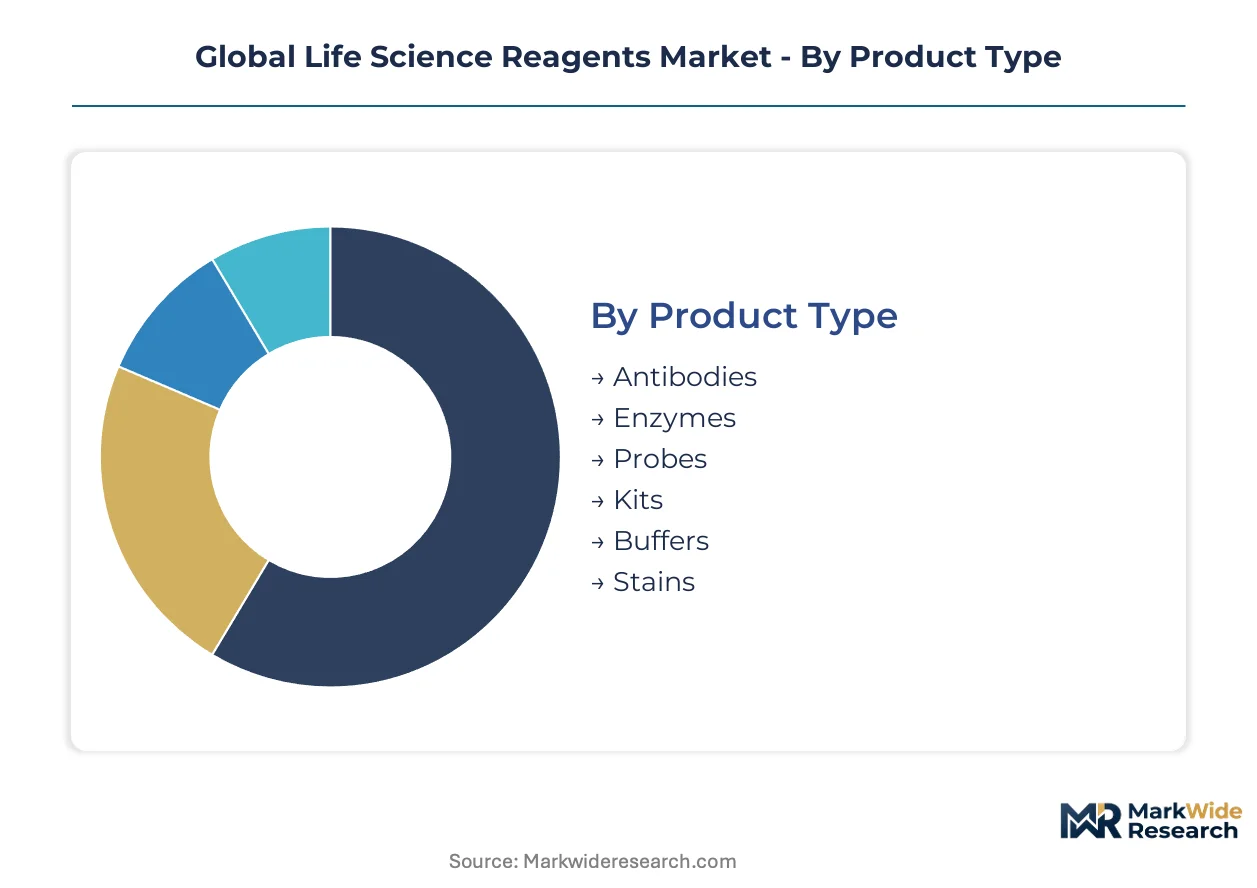
Life science reagents exhibit extreme specification diversity, with purification grades, activity tolerances, and endotoxin thresholds varying by application. Procurement teams segment suppliers across multiple axes simultaneously to match workflow requirements with certification levels and volume economics.
Product Type:
Standardization dominates high-volume enzyme and buffer categories, while antibodies and custom probes command project-specific manufacturing runs with extended lead times.
- Antibodies:Monoclonal and polyclonal immunoglobulins manufactured under GMP conditions with defined binding affinity, cross-reactivity profiles, and endotoxin specifications below 0.1 EU/mL. Demand concentrates in United States and Switzerland biopharma hubs where FDA 21 CFR Part 820 compliance is mandatory for diagnostic workflows. Supply tightness in Protein A chromatography resin constrains batch release timelines.
- Enzymes:Recombinant proteins including DNA polymerases, restriction endonucleases, and reverse transcriptases produced in bacterial or mammalian expression systems with specific activity guarantees. China-Germany manufacturing corridors absorb the bulk of new capacity expansion as Western clients seek dual-source qualification for PCR and sequencing workflows.
- Probes:Fluorescent and chemiluminescent detection molecules with defined excitation/emission spectra and photostability ratings.
- Kits:Pre-formulated reagent assemblies with validated protocols and quality-controlled component ratios.
- Buffers:pH-stabilized aqueous solutions with defined ionic strength and preservative systems.
- Stains:Chromogenic and fluorogenic visualization compounds for microscopy and flow cytometry applications.
Most installed capacity flows through enzymes and antibodies. Expansion is steepest in probes as spatial transcriptomics methods proliferate.
Application:
Cost tier stratification separates commodity research-grade materials from premium diagnostic-certified reagents with full traceability documentation.
- Genomics:Nucleic acid extraction, amplification, and sequencing reagents requiring RNase-free certification and lot-to-lot consistency for variant calling accuracy. Academic laboratories in Germany and the Netherlands are scaling specialized reagent procurement for single-cell and spatial transcriptomics platforms.
- Proteomics:Mass spectrometry sample preparation reagents, protein digestion enzymes, and quantification standards with defined peptide recovery rates.
- Cell Biology:Cell culture media supplements, transfection reagents, and viability assays for adherent and suspension cell systems.
- Drug Discovery:High-throughput screening reagents and assay development materials with Z-factor validation data.
- Diagnostics:IVD-certified reagents with EMA performance documentation and post-market surveillance systems mandated under EU regulation.
- Molecular Cloning:Restriction enzymes, ligases, and competent cells for plasmid construction workflows.
Diagnostic applications command the highest certification premiums. Genomics applications are gaining share fastest as clinical sequencing expands.
End User:
Volume concentration varies dramatically, with pharmaceutical companies negotiating multi-year supply agreements while academic laboratories purchase through distribution intermediaries.
- Research Institutes:Government-funded facilities with open-access publication requirements and preference for catalog-standard reagents with batch documentation.
- Biotechnology Firms:Venture-backed companies prioritizing speed-to-data over cost optimization, often sourcing through qualified contract manufacturers with technical service attachments.
- Pharmaceutical Companies:Large-cap organizations with dedicated procurement teams, vendor audit programs, and single-source qualification requirements for GMP-grade materials. United States and Swiss operations are consolidating antibody and enzyme sourcing around end-to-end workflow suppliers.
- Academic Laboratories:University-based research groups with grant-dependent budgets and fragmented purchasing authority.
- Contract Research Organizations:Service providers requiring flexible reagent access across multiple client protocols and regulatory jurisdictions.
Pharmaceutical companies absorb the largest revenue share. Biotechnology firms are expanding procurement fastest as mid-cap pipelines mature.
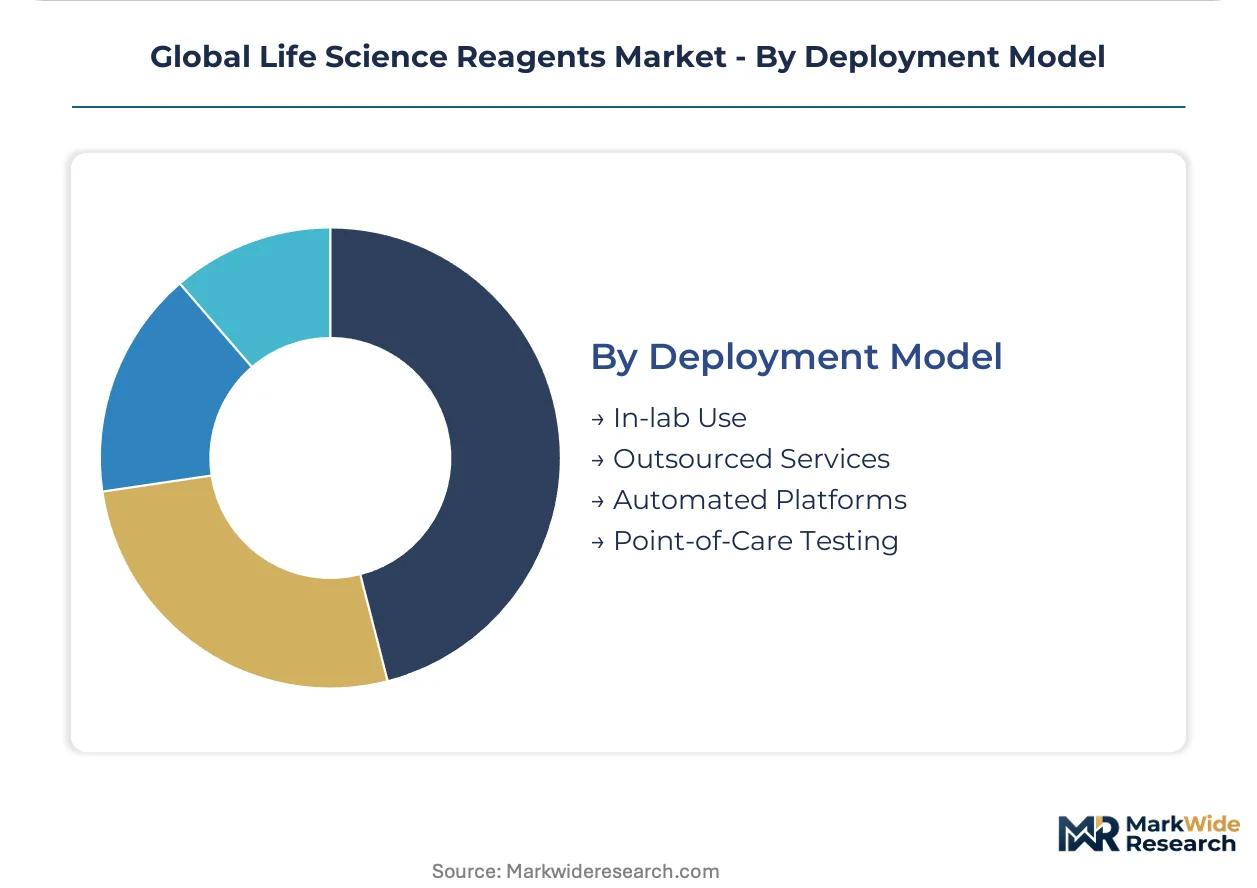
Deployment Model:
Maturity gradients separate established in-lab consumption from emerging automated and point-of-care configurations with distinct formulation requirements.
- In-lab Use:Traditional benchtop reagent handling with researcher-prepared dilutions and manual quality verification steps.
- Outsourced Services:Contract manufacturing and testing arrangements where reagent preparation and validation are delegated to specialized providers.
- Automated Platforms:Liquid-handling integrated systems requiring barcoded reagent cartridges with machine-readable lot data and defined viscosity specifications for pipetting accuracy.
- Point-of-Care Testing:Lyophilized bead-based formats with ambient stability and minimal operator training requirements, adopted fastest in emergency medicine and veterinary segments.
Most reagent volume still flows through in-lab use. Point-of-care configurations are climbing the fastest as cold-chain-independent distribution networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting GMP-grade reagent production toward jurisdictions with streamlined certification pathways and lower facility qualification costs. Manufacturers are relocating bulk enzyme and antibody capacity to exploit these compliance-cost differentials while maintaining FDA and EMA market access through dual-site qualification strategies.
United States
Biopharma procurement teams in Massachusetts and California are consolidating antibody sourcing around end-to-end workflow suppliers with single-site GMP qualification. FDA 21 CFR Part 820 enforcement is tightening endotoxin specifications for diagnostic-grade materials. The Greater Boston cluster absorbs the largest share of specialized reagent spend for single-cell transcriptomics platforms.
Germany
Academic laboratories in Heidelberg and Munich are scaling specialized reagent procurement for spatial transcriptomics and proteomics applications. EMA's In Vitro Diagnostic Regulation mandates performance documentation and supply chain traceability across European markets. The Rhine-Main biotech corridor concentrates contract manufacturing capacity for recombinant enzymes serving Western European diagnostic manufacturers.
China
Contract manufacturers in Suzhou and Shanghai are recalibrating bulk enzyme output to serve Western biopharma clients seeking dual-source qualification. NMPA alignment with international GMP standards is accelerating facility certification timelines for export-oriented producers. The Yangtze River Delta biopharma cluster is absorbing the majority of new monoclonal antibody production capacity expansion.
Switzerland
Mid-cap biotechnology companies in Basel and Zurich are negotiating long-term supply agreements with technical service attachments for GMP-grade antibody sourcing. Swissmedic maintains stringent lot-release protocols that exceed baseline ISO 13485 requirements. The Basel pharmaceutical hub concentrates demand for high-purity reagents in biologics development workflows.
India
Domestic diagnostic manufacturers in Hyderabad and Bengaluru are expanding procurement of research-grade reagents for assay development. CDSCO's streamlined IVD registration pathway is attracting Western suppliers seeking market entry through local manufacturing partnerships. The Genome Valley biotech cluster is emerging as a contract testing hub for endotoxin validation services.
Global Life Science Reagents Market Key Industry Players
United States producers anchor one tier with end-to-end workflow portfolios; German and Swiss specialists hold differentiated positions in filtration and rare chemical building blocks. Market structure tilts toward consolidation as biopharma clients demand single-source qualification for complex workflows. Three archetypes dominate: diversified conglomerates with integrated purification expertise, mid-scale specialists with chromatography depth, and regional contract manufacturers with GMP flexibility. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure multi-year supply agreements.
Among diversified conglomerates, Danaher Corporation and Thermo Fisher Scientific exemplify the integrated workflow archetype with extensive filtration and clinical research channel presence. Merck KGaA occupies a distinct position within the European specialist tier, anchored by its rare chemical building-block catalog across academic networks. These three entities represent the competitive spectrum from scale-driven consolidation to technical differentiation.
| Leading Market Players |
|---|
| Danaher Corporation |
| Agilent Technologies |
| Thermo Fisher Scientific |
| PerkinElmer |
| Waters Corporation |
| Merck KGaA |
| Bio-Rad Laboratories |
| Becton Dickinson |
| Roche Diagnostics |
| Others |
Cost & Logistics Intelligence
Biopharma procurement consolidation around single-source GMP qualification is forcing contract manufacturers to absorb upfront certification costs and extend payment terms, compressing working capital cycles and reshaping how suppliers price long-term antibody and enzyme agreements.
Pricing Analysis
Direct-to-biopharma contract pricing bypasses traditional distribution markups that historically captured 15-25% in research-grade channels. Three-tier pricing structure across GMP-certified, ISO-grade, and research-use materials reflects endotoxin thresholds and lot-release documentation depth. Cost compression in diagnostic-grade enzymes is intensifying because Protein A resin price volatility feeds directly into purification economics. Academic laboratories exhibit highest price sensitivity, while pharmaceutical companies prioritize supply security over unit cost optimization.
Supply Chain Analysis
Skilled bioprocessing technician shortages in Suzhou and Shanghai are constraining batch release velocity for export-oriented antibody manufacturers. Supply concentrates in China, Germany, and the United States, with each corridor specializing in distinct expression systems and purification scales. Chromatography resin and mammalian cell culture media constitute critical input dependencies. Single-source vulnerability in Protein A resin supply creates systemic risk for antibody purification workflows. Distribution runs through qualified contract manufacturers with end-to-end workflow capabilities rather than fragmented catalog distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between China's streamlined NMPA facility certification and the EMA's rigorous post-market surveillance requirements, with cost differentials exceeding 30% in GMP construction and validation timelines.
For Market Incumbents: Anticipate margin erosion from Chinese contract manufacturers recalibrating bulk enzyme output for Western biopharma clients by deepening captive supply of chromatography resin and securing dual-site GMP qualification across the China-Germany-US triangle. Lock in multi-year antibody supply agreements with technical service attachments before procurement consolidation accelerates. For New Entrants and Emerging Players: Synthetic biology toolkits offer a technology-first wedge into customized reagent specifications where automated formulation platforms compress development cycles for spatial transcriptomics probe demand. Target India's CDSCO pathway expansion through local manufacturing partnerships for IVD-grade materials. Pursue lyophilized format convergence for cold-chain-independent distribution into emergency medicine and veterinary segments. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists possessing chromatography depth and GMP flexibility in the China-Germany-US production triangle. Five-to-ten year viability hinges on EU AI Act compliance service bundling for algorithm-assisted diagnostic platforms. Monitor endotoxin testing capacity expansion at contract testing organizations as the inflection signal for parenteral-grade reagent lot release velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Site GMP Qualification | China-Germany-US manufacturing corridors absorb biopharma single-source consolidation demands. |
| Lyophilized Format Development | Ambient-stable reagents unlock distribution into cold-chain-limited point-of-care networks. |
| Chromatography Resin Backward Integration | Protein A and ion-exchange media captive supply mitigates margin volatility from price swings. |
| EU AI Act Compliance Bundling | Validation documentation for algorithm-assisted platforms differentiates diagnostic reagent vendors. |
| India CDSCO Manufacturing Partnership | Streamlined IVD registration creates entry points for Western suppliers seeking market expansion. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biopharma procurement directors, GMP facility managers, diagnostic regulatory affairs leads, and academic laboratory principal investigators with secondary validation against FDA 21 CFR Part 820 guidance documents, EMA In Vitro Diagnostic Regulation performance standards, NMPA GMP alignment protocols, and ISO 13485 certification body audit disclosures. Bottom-up reagent consumption modeling and top-down market sizing triangulated volume estimates.
Segment-weighting across product type, application, end user, and deployment model dimensions structured the analytical framework across the analysis window. CAGRs derived from trend extrapolation of genomics and proteomics reagent spend, spatial transcriptomics platform adoption curves, and biopharma antibody procurement contract values. Forecast inputs incorporated GMP facility qualification timeline distributions and chromatography resin price index trajectories.
The model holds under stable regulatory enforcement intensity and continued biopharma R&D expenditure; deviation in FDA or EMA quality standard tightening, or sustained Protein A resin supply disruption, would shift capacity expansion and pricing assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Small-Scale Bioreactors Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Global Cryostat Microbiome Equipment Market
Biotechnology Equipment
Biologic Imaging Reagents Market