
 Moving Bed Bioreactor Market | 2026-2036
Moving Bed Bioreactor Market Size, Share, and Industry Trends Forecast 2026-2036
Moving Bed Bioreactor Market Analysis
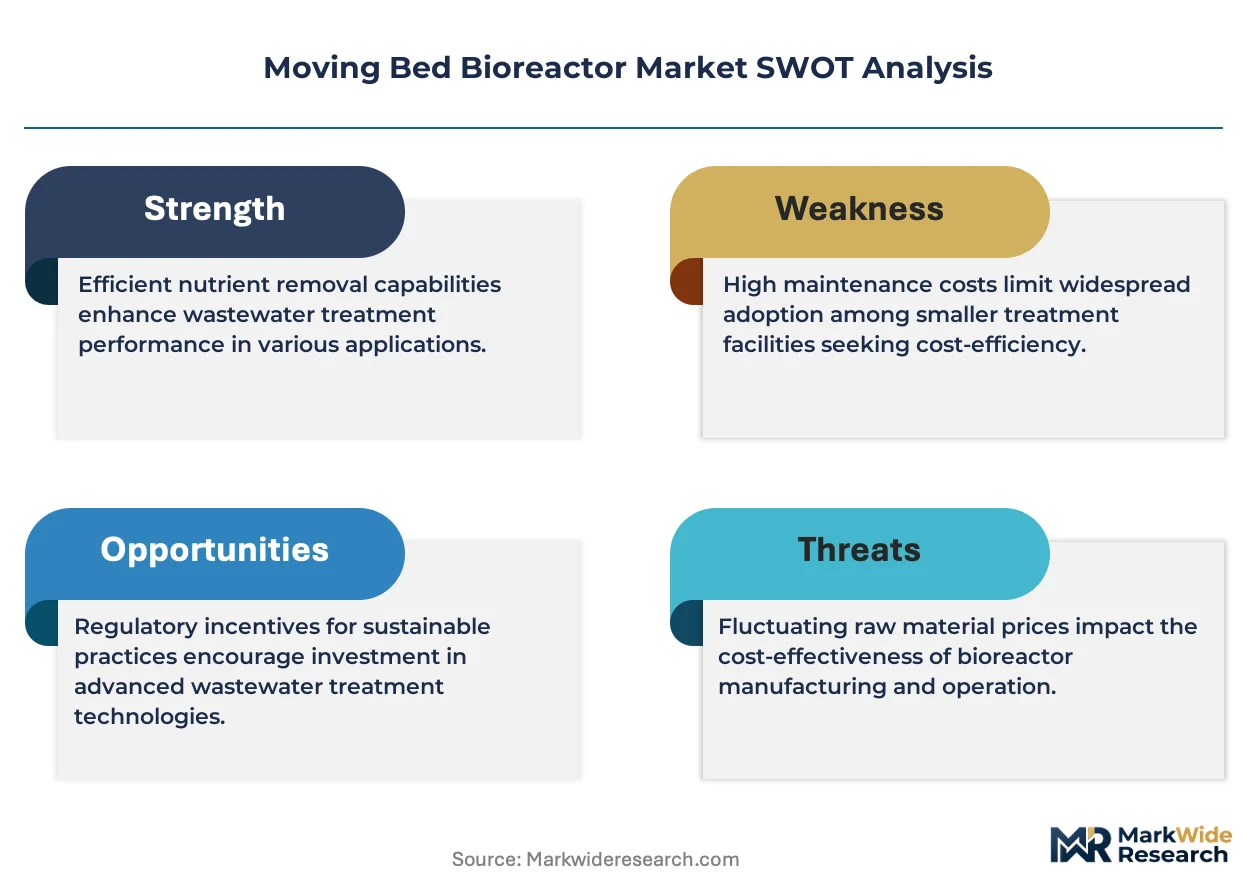
The capability gap between integrated system providers and component suppliers is rotating competitive advantage toward full-lifecycle vendors. Veolia leverages its global service infrastructure to lock in long-term operating contracts across European municipal utilities. Xylem sustains technology leadership through proprietary aeration control algorithms that cut energy draw in aerobic digestion trains. Evoqua Water Technologies LLC anchors its position in North American industrial end users with modular skids designed for food processing effluent.
A moving bed bioreactor employs suspended plastic biofilm carriers within aeration tanks, typically achieving mixed liquor suspended solids concentrations of 4,000–12,000 mg/L while operating at hydraulic retention times under six hours. The system's primary purpose is high-rate biological nutrient removal from municipal and industrial wastewater streams without clarifier footprint expansion. Fluidized bed configurations command premium pricing in compact urban retrofits where land scarcity drives vertical tank designs, while hybrid systems that couple aerobic and anaerobic digestion stages represent the fastest-growing technology category as industrial users pursue net-zero Scope 1 targets. Municipal end users still occupy the largest volume pool, though food processing applications are shifting toward anaerobic digestion technology to capture biogas for captive energy recovery.
EPA effluent limitation guidelines under the Clean Water Act shape product design requirements for US discharge permits, while ECHA REACH compliance governs biofilm carrier polymer composition across European installations. China's MEE enforces Class 1A discharge standards that directly mandate MBR upgrades for existing activated sludge plants. Stakeholders must monitor how tightening phosphorus limits in multiple jurisdictions will force carrier media redesigns and anaerobic sidestream configurations.
Market Dynamics
Carrier media densification and anaerobic sidestream integration are compressing hydraulic retention times below four hours while expanding nutrient removal capacity in retrofit-constrained sites.
Growth Catalysts
- China's MEE Class 1A discharge standards:Existing activated sludge plants in the Yangtze River Basin must upgrade to MBR configurations, triggering equipment replacement cycles across municipal utilities.
- Food processing biogas capture:Anaerobic digestion retrofits at dairy and meat processing facilities convert organic loading into captive energy, offsetting Scope 1 emissions under corporate net-zero commitments.
- Vietnam's Red River Delta industrial zones:Textile manufacturers face biological oxygen demand limits that conventional activated sludge cannot meet, forcing high-rate biofilm technology adoption.
Market Restraints
- Polyethylene biofilm carrier cost volatility:Virgin polymer prices fluctuate with petrochemical feedstock indices, compressing margins for skid fabricators locked into fixed municipal contract pricing.
- Proprietary aeration control IP concentration:Algorithm-integrated blower systems remain concentrated among integrated system providers, limiting component supplier upgrade paths.
- Hybrid system integration complexity:Coupling aerobic and anaerobic stages demands specialized process engineering talent scarce outside Western Europe and East Asia.
Strategic Opportunities
- Indonesia's Citarum River basin:Garment clusters around Bandung lack centralized treatment infrastructure, creating greenfield demand for compact vertical tank configurations.
- Phosphorus recovery sidestreams:Struvite precipitation coupled with anaerobic MBBR stages transforms nutrient liability into fertilizer revenue streams for utilities.
- Digital twin integration:Real-time biofilm thickness monitoring via machine vision converges with predictive aeration control to cut energy draw.
Industry Challenges
- Process modeling skill scarcity:Computational fluid dynamics expertise for carrier fluidization optimization remains concentrated among senior engineers approaching retirement in German and Japanese engineering consultancies.
- Legacy clarifier infrastructure lock-in:Municipal utilities with recently upgraded secondary settling tanks resist full MBR conversion, forcing hybrid retrofit designs that complicate warranty liability.
- Carrier media standardization delays:Competing proprietary geometries from system providers prevent interchangeability, stranding inventory when utilities switch vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moving Bed Bioreactor Market |
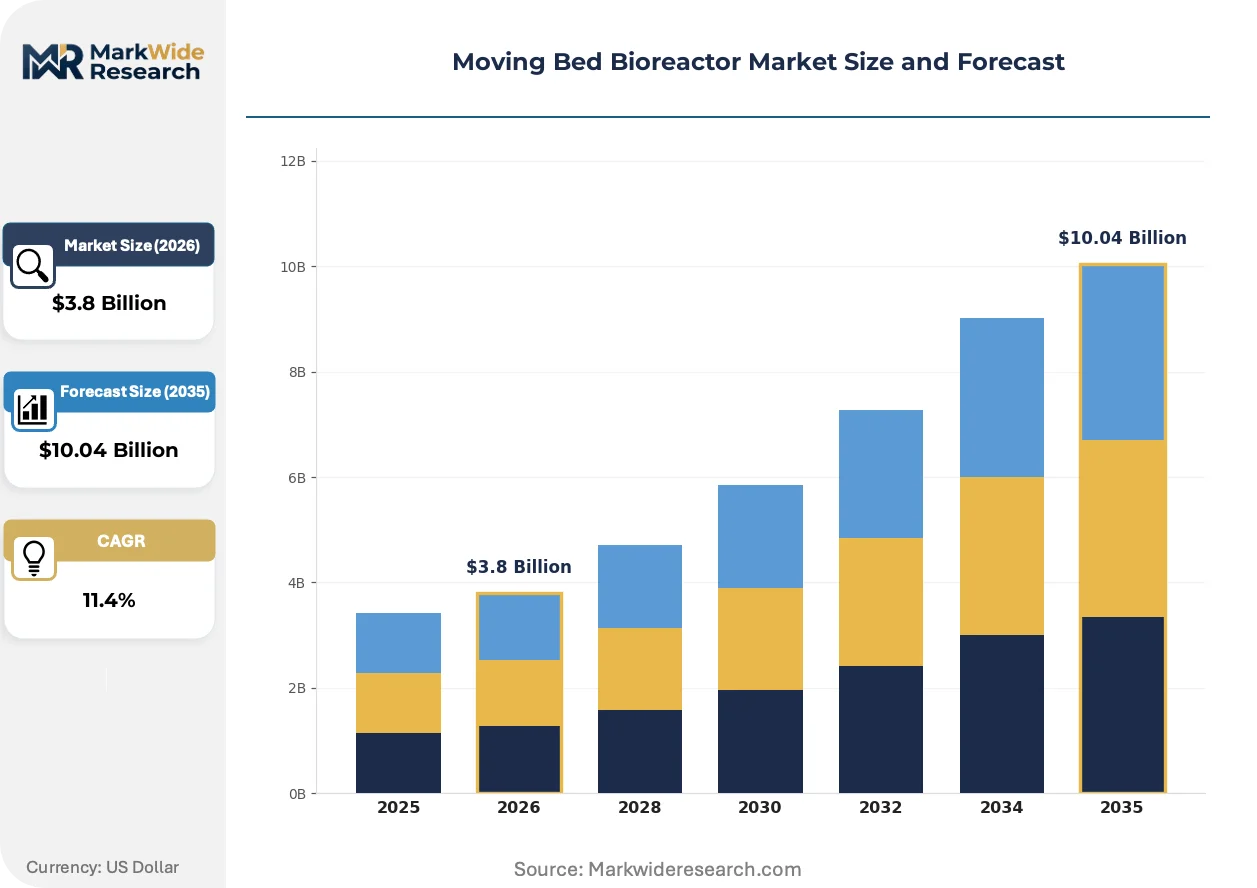
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Bed, Fluidized Bed, Sequencing Batch, Moving Bed Application: Wastewater Treatment, Biogas Production, Poultry Waste Management, Soil Remediation End User: Agriculture, Municipalities, Food Processing, Industrial Technology: Aerobic Digestion, Anaerobic Digestion, Hybrid Systems, Microbial Fuel Cells |
| Companies Covered | Biowater Technology AS, Genesis Water Technologies, Veolia, Headworks International, Aquapoint Inc., Aquatech International LLC, Ovivo, Xylem, Evoqua Water Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moving Bed Bioreactor Market Emerging Trajectories
Biological nutrient removal is compressing toward single-reactor configurations while digital control layers embed predictive capability directly into aeration infrastructure. These shifts reward vendors who integrate hardware, software, and lifecycle service rather than pure equipment supply.
Advanced composite carriers with controlled surface roughness are decomposing the historical trade-off between biofilm attachment strength and oxygen transfer efficiency. Food processors in the Netherlands and Denmark are deploying these materials at pilot scale to handle high-strength whey streams without dilution. The technology is decomposing clarifier footprint requirements in brownfield dairy plants where expansion land is unavailable.
EPA effluent limitation guidelines under the Clean Water Act are tightening nitrogen and phosphorus limits for municipal dischargers in Chesapeake Bay and Gulf of Mexico watersheds. These rules force activated sludge plants toward biofilm augmentation or full MBR conversion to achieve seasonal nutrient caps. Small-to-midsize utilities in Pennsylvania and Maryland are bundling upgrade financing with long-term operating contracts to transfer performance risk.
Buyer preference is consolidating around performance-guaranteed service agreements that unbundle capital expenditure from operating outcomes. Industrial end users in Southeast Asian textile clusters now procure cubic meters of treated effluent rather than reactor hardware, shifting vendor revenue toward opex-linked contracts. This model is most visible in Vietnam's Bac Ninh province where foreign-owned manufacturers demand ISO 14001-aligned discharge documentation for supply chain audits.
Moving Bed Bioreactor Market Segmentation
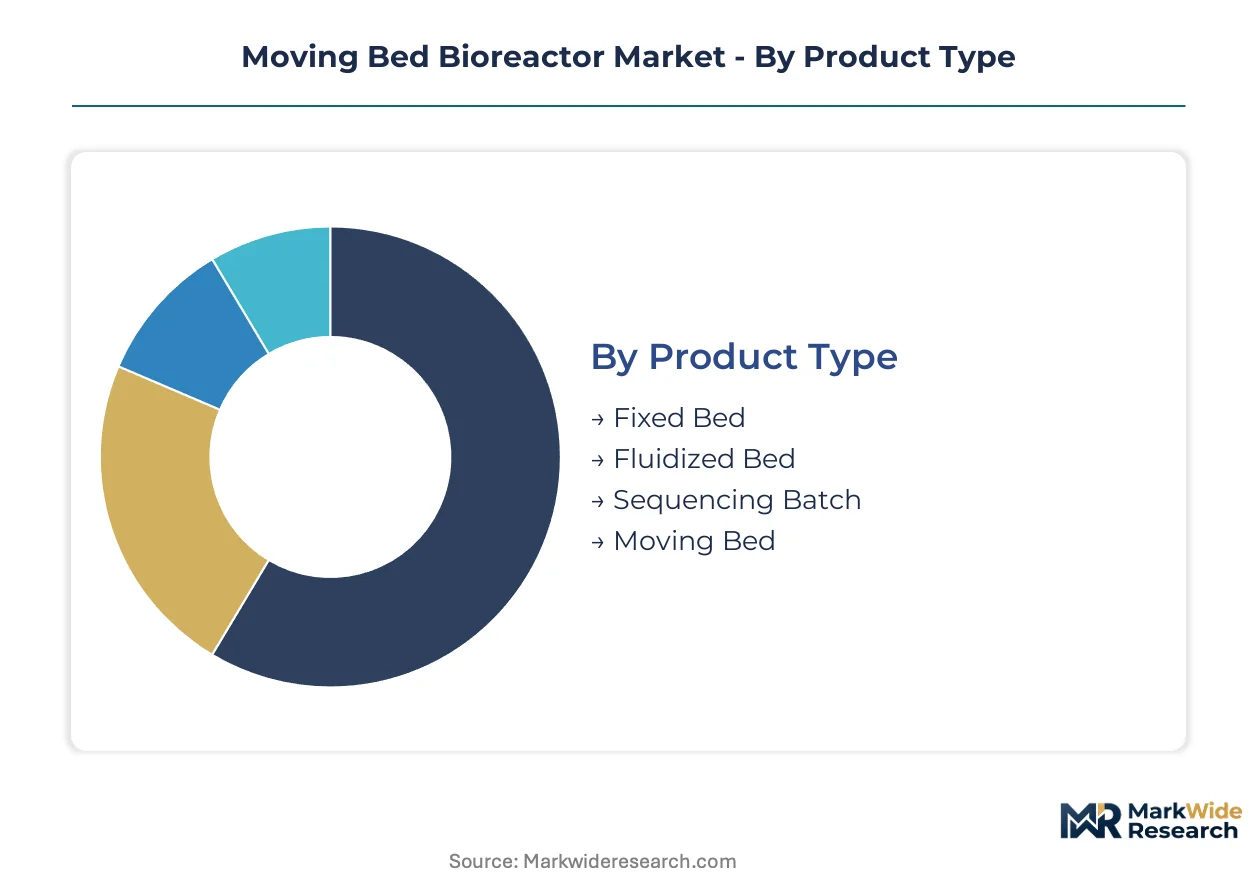
Segmentation in the moving bed bioreactor market reveals how technology selection maps to effluent constraints, energy recovery goals, and retrofit feasibility. Buyers prioritize hydraulic retention time reduction, nutrient removal rates, and land footprint compression when matching reactor configurations to site conditions.
Product Type:
Substitution pressure runs strongest against fixed bed configurations as fluidized and hybrid designs compress retention times below four hours without clarifier expansion.
- Fixed Bed:Biofilm grows on stationary media within submerged packed columns, achieving moderate organic loading rates. Demand concentrates in legacy industrial sites across Germany and Japan where existing infrastructure resists full replacement, constrained by oxygen transfer limitations that favor retrofit over greenfield deployment.
- Fluidized Bed:High-velocity upflow suspends granular media at expanded bed volumes, delivering intensified mass transfer. Premium pricing commands compact urban retrofits in Vietnam's Red River Delta and Indonesia's Citarum basin where land scarcity drives vertical tank designs and textile manufacturers face biological oxygen demand limits.
- Sequencing Batch:Cyclic fill-react-settle-decant operation within single vessels suits small-scale municipal utilities with intermittent flow patterns.
- Moving Bed:Suspended plastic carriers achieve 4,000–12,000 mg/L mixed liquor suspended solids with retention times under six hours.
Moving bed anchors the volume base while fluidized bed gains share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive municipal installations from industrial deployments where energy recovery offsets equipment expenditure.
- Wastewater Treatment:Biological nutrient removal from municipal and industrial streams dominates installed base. China's MEE Class 1A discharge standards force Yangtze River Basin activated sludge plants toward MBR upgrades, triggering replacement cycles across municipal utilities locked into performance-guaranteed operating contracts.
- Biogas Production:Anaerobic digestion stages convert organic loading to methane for captive energy recovery. Dairy and meat processing facilities in the Netherlands and Denmark deploy these systems at scale to offset Scope 1 emissions under corporate net-zero commitments, with high-strength whey streams driving advanced composite carrier adoption.
- Poultry Waste Management:High-ammonia streams from concentrated animal feeding operations demand specialized nitrification capacity.
- Soil Remediation:Ex-situ bioreactor treatment of contaminated excavated soils serves brownfield redevelopment projects.
Wastewater treatment absorbs the majority of capital deployment while biogas production climbs fastest as food processors pursue emission reduction targets.
End User:
Customer type determines procurement modality, with municipalities favoring bundled financing and industrial users shifting toward cubic-meter-based effluent contracting.
- Agriculture:Concentrated animal feeding operations and crop processing facilities manage nutrient-laden runoff. Demand clusters in poultry-dense regions of the US Southeast where EPA Chesapeake Bay watershed nitrogen limits force lagoon upgrades toward biofilm-augmented systems.
- Municipalities:Urban utilities face effluent limitation guidelines under the US Clean Water Act and EU Urban Waste Water Treatment Directive. Small-to-midsize utilities in Pennsylvania and Maryland bundle upgrade financing with long-term operating contracts to transfer performance risk under tightening seasonal nutrient caps.
- Food Processing:Dairy, meat, and beverage producers prioritize anaerobic digestion for biogas capture.
- Industrial:Textile, chemical, and pharmaceutical manufacturers face site-specific discharge permits.
Municipalities anchor the volume base while food processing gains share at the steepest rate.
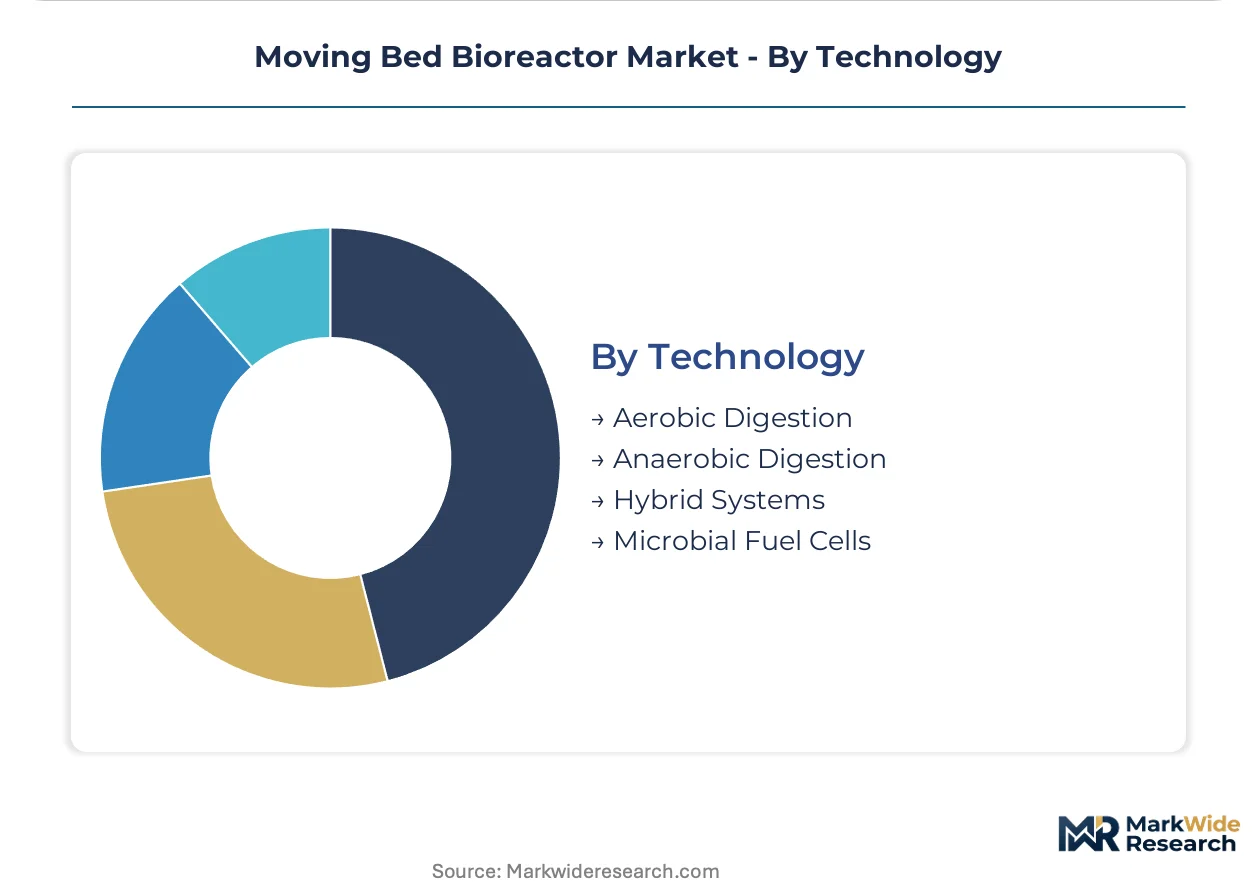
Technology:
Supply concentration among algorithm-integrated blower system providers limits component supplier upgrade paths and rewards full-lifecycle vendors.
- Aerobic Digestion:Oxygen-dependent mineralization of organic matter dominates conventional installations. Xylem's proprietary aeration control algorithms cut energy draw in municipal trains across European utilities, locking in long-term service relationships through performance-guaranteed outcomes.
- Anaerobic Digestion:Oxygen-free conversion of organics to biogas suits high-strength industrial streams. China's dual carbon goals and updated MEE discharge rules accelerate adoption at meat processing facilities seeking captive energy recovery and carbon intensity reduction.
- Hybrid Systems:Coupled aerobic-anaerobic stages represent the fastest-expanding technology category.
- Microbial Fuel Cells:Direct electricity generation from organic oxidation remains at pilot scale.
Aerobic digestion anchors the volume base while hybrid systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment pricing power concentrates in German engineering consultancies and Japanese system integrators, while Vietnamese textile clusters and Indonesian garment hubs absorb margin compression through volume procurement.
China
Yangtze River Basin municipal utilities drive replacement cycles for activated sludge infrastructure. The MEE enforces Class 1A discharge standards that mandate MBR upgrades at existing plants. Meat processing facilities in Sichuan-Chongqing pursue anaerobic digestion retrofits to capture biogas under dual carbon compliance timelines.
United States
Chesapeake Bay and Gulf of Mexico watershed utilities face seasonal nutrient caps that biofilm augmentation addresses. EPA effluent limitation guidelines under the Clean Water Act tighten nitrogen and phosphorus thresholds. Small-to-midsize utilities in Pennsylvania bundle upgrade financing with operating contracts to transfer performance risk.
Germany
Legacy industrial sites retain fixed bed configurations where existing infrastructure resists full replacement. ECHA REACH compliance governs biofilm carrier polymer composition across installations. Engineering consultancies in Baden-Württemberg concentrate computational fluid dynamics expertise for carrier fluidization optimization.
Vietnam
Textile manufacturers in Bac Ninh province face biological oxygen demand limits that conventional activated sludge cannot satisfy. Foreign-owned manufacturers demand ISO 14001-aligned discharge documentation for supply chain audits. Red River Delta industrial zones absorb compact vertical tank designs where land scarcity drives configuration selection.
Netherlands
Food processors deploy advanced composite carriers at pilot scale to handle high-strength whey streams without dilution. Dairy and meat processing facilities convert organic loading to captive energy under corporate net-zero commitments. Advanced carrier materials decompose clarifier footprint requirements in brownfield plants where expansion land is unavailable.
Moving Bed Bioreactor Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with algorithm-integrated blower systems concentrated among integrated providers while component suppliers face compressed upgrade paths. The vendor base organizes around three strategic archetypes: full-lifecycle service vendors locking in municipal utilities through performance-guaranteed contracts, technology specialists commanding premium pricing via proprietary control systems, and regional fabricators competing on skid delivery speed. Dominant competitive moves include long-term operating contract bundling to transfer performance risk and vertical tank configuration specialization for land-constrained retrofits.
Among integrated service providers, Veolia anchors the full-lifecycle archetype through global infrastructure deployment. Xylem occupies the technology-specialist position with proprietary aeration control algorithms. Evoqua Water Technologies LLC represents the North American industrial focus through modular skid design orientation.
| Leading Market Players |
|---|
| Biowater Technology AS |
| Genesis Water Technologies |
| Veolia |
| Headworks International |
| Aquapoint Inc. |
| Aquatech International LLC |
| Ovivo |
| Xylem |
| Evoqua Water Technologies LLC |
| Others |
Supply Flow & Price Mechanics
Carrier media manufacturing scale in Germany and Japan anchors price floors for fluidized bed configurations, with multi-reactor municipal contracts compressing margins for skid fabricators locked into fixed pricing while premium vertical tank designs command configured-to-order premiums in Vietnam's land-constrained industrial zones.
Pricing Analysis
Configured-to-order pricing for compact vertical tank designs runs 40-60 percent above standard horizontal configurations, with differentiation driven by ISO 14001-aligned documentation bundles for supply chain audits and site-specific CFD modeling for carrier fluidization optimization. Price erosion runs through standard moving bed skids as polyethylene virgin polymer costs fluctuate with petrochemical feedstock indices. Municipal utilities in Pennsylvania and Maryland exhibit lowest price sensitivity due to bundled operating contracts that transfer performance risk, while Indonesian garment clusters around Bandung show highest sensitivity and procure on cubic-meter effluent basis.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for biofilm carrier polymers sourced from German chemical producers, with container availability constraints extending lead times for engineered media. Manufacturing concentrates in Germany, Japan, and China, drawing from high-density polyethylene resin, controlled-surface-roughness composite substrates, and algorithm-integrated blower systems. Single-source vulnerability sits with proprietary aeration control IP concentrated among integrated system providers. Distribution runs through EPC contractors and municipal procurement consortia rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term operating contracts with performance-guaranteed outcomes expand faster than hardware sales as Vietnamese textile manufacturers and Dutch food processors shift toward cubic-meter-based effluent procurement, creating durable recurring revenue layers that outpace equipment replacement cycles.
For Market Incumbents: Fortify algorithm-integrated service infrastructure to lock in municipal utilities against emerging digital-twin specialists, while deepening captive supply of advanced composite carrier materials to offset polyethylene price volatility. Priority investment targets CFD modeling talent pools in Baden-Württemberg engineering consultancies facing generational retirement.
For New Entrants and Emerging Players: Aftermarket biofilm carrier replacement and digital twin integration services present under-served layers where incumbents focus on front-end equipment sales. Indonesia's Citarum River basin garment clusters offer most penetrable geography with greenfield demand for compact vertical tanks. Go-to-market through performance-guaranteed cubic-meter contracting rather than capital equipment sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-lifecycle service vendors with installed base lock-in over pure equipment suppliers facing margin compression. Five-to-ten year viability hinges on anaerobic digestion integration capability and hybrid system process engineering talent. Watch phosphorus recovery sidestream commercialization rates as inflection signal for nutrient-capture technology premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Guaranteed Operating Contracts | Transfers effluent compliance risk from Yangtze River Basin utilities to vendor balance sheets. |
| Backward Integration into Carrier Media Manufacturing | Captures polymer cost margin and insulates against ECHA REACH compliance volatility. |
| Hybrid System Process Engineering Talent Acquisition | Secures scarce CFD expertise for aerobic-anaerobic stage coupling in retrofit-constrained sites. |
| Digital Twin Platform Development | Embeds predictive aeration control via machine vision for biofilm thickness monitoring. |
| Phosphorus Recovery Sidestream Commercialization | Transforms nutrient liability into fertilizer revenue streams for municipal utilities. |
Methodological Framework
A standing panel of municipal utility operations directors, food processing plant engineers, EPC contractor procurement leads, and aftermarket service heads provided ongoing calibration across the study period, supplemented by secondary validation against EPA effluent limitation guidelines, China's MEE discharge standards, EU Urban Waste Water Treatment Directive implementations, and customs data for biofilm carrier polymer trade flows. Bottom-up equipment shipment tallies triangulated against top-down municipal capital expenditure disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon, with segmentation modeling spanning reactor configuration type, application end-use, technology stage, and customer procurement modality. CAGRs derived from logistic growth curve fitting to historical installation data, incorporating MEE Class 1A compliance timelines and corporate net-zero commitment schedules as industry-specific demand drivers.
Forecasts assume regulatory continuity in EPA Chesapeake Bay watershed rules, EU Urban Waste Water Treatment Directive enforcement, and China's MEE discharge standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Laboratory Filtration Devices Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Global Biological Safety Cabinets Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
North America Life Science Tools Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Lab Automation in Bioanalysis Market