
 IVF Workstation Market | 2026-2036
IVF Workstation Market Size, Share, and Industry Trends Forecast 2026-2036
IVF Workstation Market Foresight
Polycarbonate is restructuring enclosure economics across IVF workstation manufacturing as manufacturers replace heavier glass-and-steel housings with lighter, thermally stable polymer assemblies. CooperSurgical leverages its integrated consumables portfolio to bundle workstations with media and cultureware, locking in multi-year clinic contracts. Esco Lifesciences anchors Asia-Pacific supply chains through vertically controlled manufacturing campuses in Singapore and China. Hamilton Thorne differentiates through embedded time-lapse imaging modules that reduce manual embryo handling.
An IVF workstation is a controlled-environment laboratory platform that maintains stable temperature, pH, and gas composition for gamete and embryo manipulation, typically operating within 37°C ± 0.2°C and 6% CO₂ atmospheric conditions to mimic physiological conditions. These systems integrate micromanipulators, heated stages, and HEPA-filtered airflow to protect sample viability during procedures such as intracytoplasmic sperm injection and embryo biopsy. Embryo culture systems command the largest installed base due to their universal requirement across all IVF cycles, while automated workstations represent the fastest-expanding technology segment as labor costs rise and reproducibility standards tighten. Fertility clinics absorb the majority of capital expenditure, though cryobanks are emerging as a concentrated secondary buyer as commercial egg and sperm banking scales.
The FDA's 510(k) clearance pathway and the EU MDR's Class IIa device classification jointly determine market access timelines and clinical evidence requirements for workstation manufacturers selling into the United States and European Union. ISO 14644 cleanroom standards and WHO laboratory guidelines further shape product specifications for air quality and contamination control in embryology suites. Stakeholders must monitor how the EU AI Act's risk-based framework will classify automated embryo assessment algorithms embedded in next-generation workstations.
Market Dynamics
The IVF workstation market is restructuring around polycarbonate enclosure substitution and automated embryo assessment integration, as manufacturers and fertility clinics jointly pursue thermal stability gains and labor cost reduction.
Growth Catalysts
- EU MDR Class IIa Device Pathway:The European Union's Medical Device Regulation is accelerating certification consolidation among workstation manufacturers, filtering out marginal suppliers and concentrating procurement among certified vendors in Germany and France.
- Time-Lapse Imaging Convergence:Embedded imaging modules are reducing manual embryo handling cycles, enabling fertility clinics in the United States to process higher case volumes per embryologist.
- India Domestic Fertility Network Buildout:Regional capacity expansion across Mumbai, Delhi, and Bangalore is generating concentrated demand for embryo culture systems and cryopreservation workstations.
Market Restraints
- Polycarbonate Feedstock Volatility:Petrochemical input cost swings are compressing margin stability for enclosure manufacturers dependent on polymer supply chains centered in East Asia.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation's expanded technical documentation requirements are extending time-to-market for workstation variants by 12-24 months.
- Glass-Steel Housing Substitution Ceiling:Premium fertility clinics in Switzerland and the United Kingdom maintain preference for legacy enclosure materials, limiting polymer penetration in high-end segments.
Strategic Opportunities
- China NMPA Streamlined Review:The National Medical Products Administration's priority review channel for assisted reproductive technologies is opening accelerated market access for automated workstation platforms.
- Cryobank Commercial Banking Scale:Commercial egg and sperm banking operations in the United States are emerging as concentrated secondary buyers with standardized high-volume procurement protocols.
- ISO 14644-WHO Guideline Alignment:Convergence between cleanroom standards and WHO laboratory guidelines is creating certification bundling opportunities for workstation manufacturers serving multi-jurisdictional clinic chains.
Industry Challenges
- Embryologist Specialization Scarcity:The technical workforce capable of operating micromanipulator-integrated workstations is concentrated in Western Europe and North America, constraining deployment velocity in emerging markets.
- 510(k)-MDR Parallel Certification Complexity:Dual-track FDA and European Union regulatory submissions are fragmenting product development resources and delaying variant launches.
- Legacy Stage Integration Friction:Heated stage retrofits into existing embryology suites require HVAC and electrical infrastructure modifications that extend installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IVF Workstation Market |
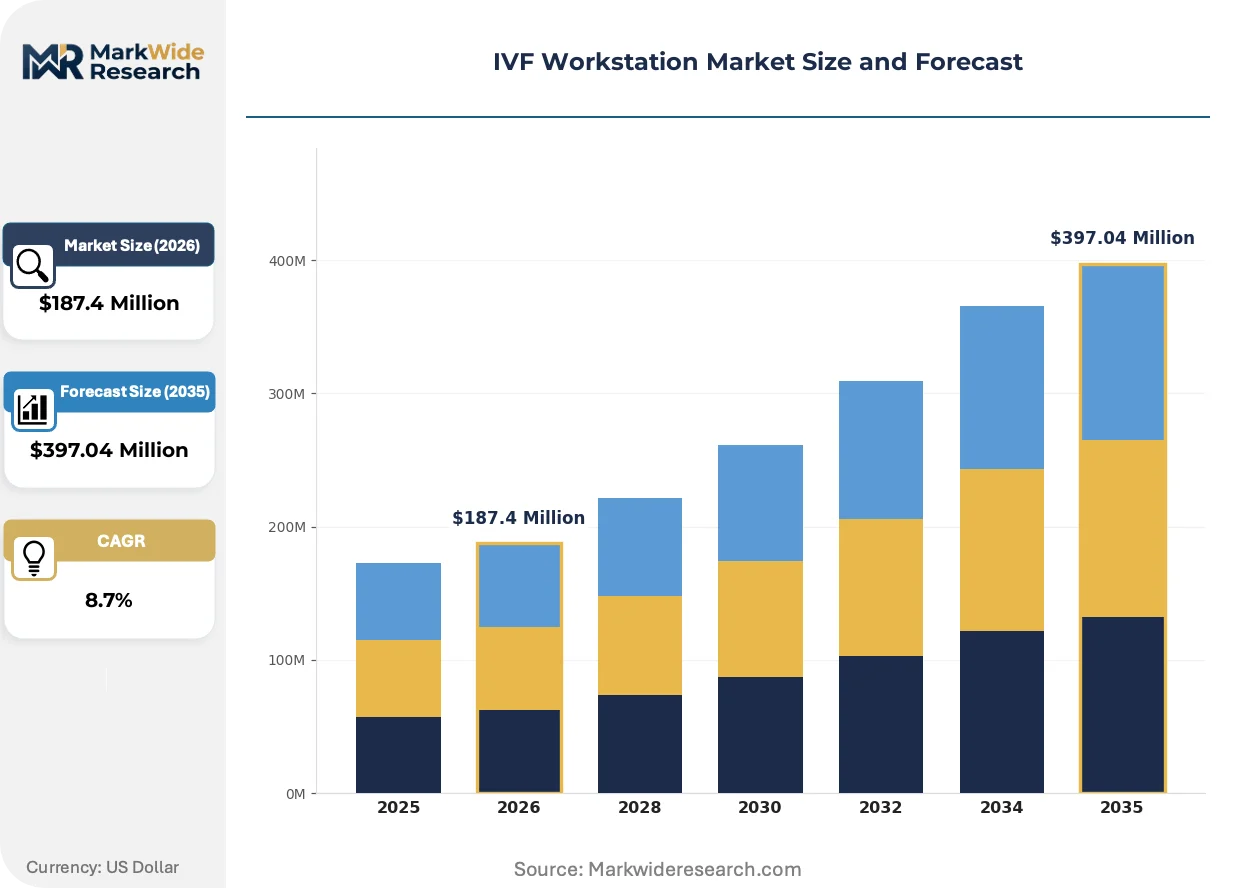
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
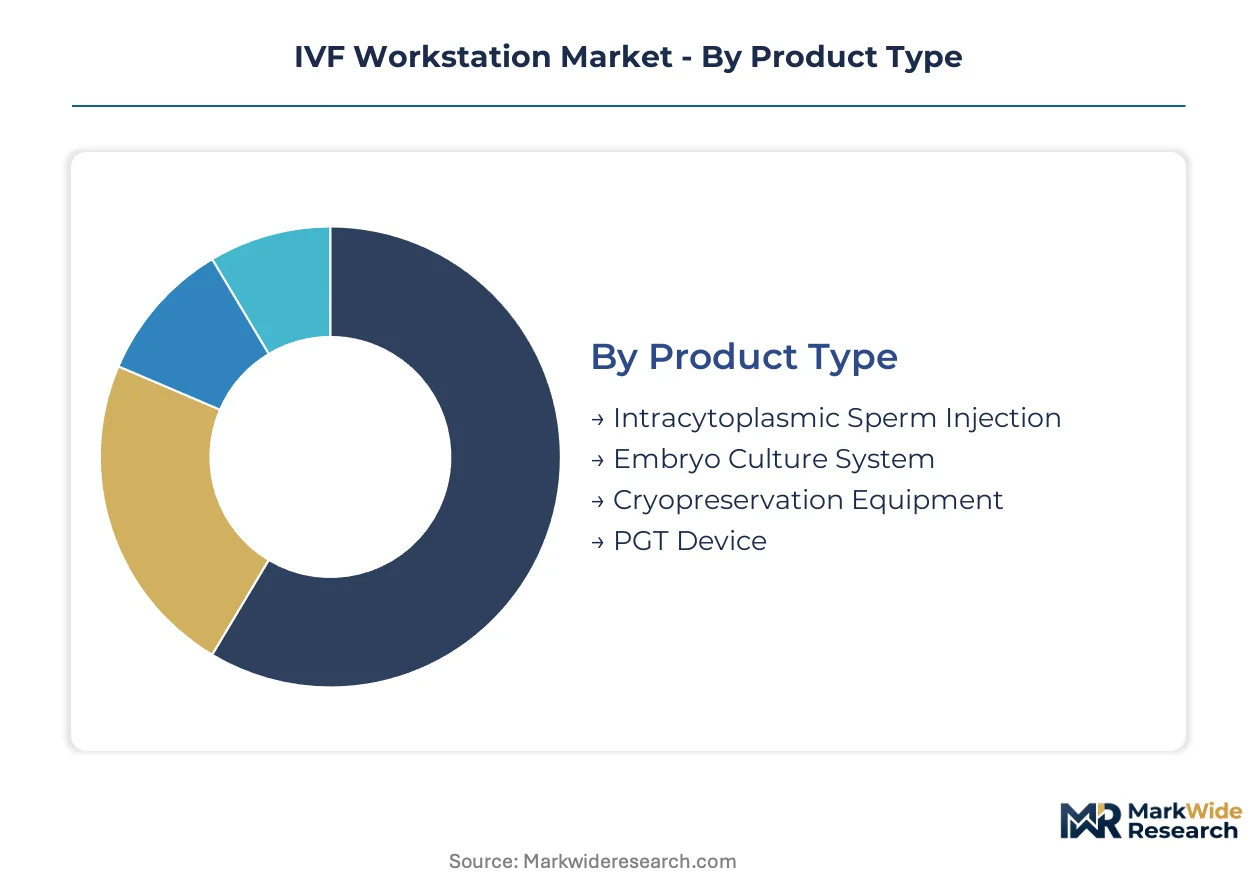
| Segmentation | Product Type: Intracytoplasmic Sperm Injection, Embryo Culture System, Cryopreservation Equipment, PGT Device End User: Fertility Clinics, Research Institutes, Hospitals, Cryobanks Technology: Electrophysiology, Time-Lapse Imaging, Laser Systems, Automated Workstations Application: Infertility Treatment, Genetic Testing, Sperm Bank Management, Research Studies |
| Companies Covered | CooperSurgical, Esco Lifesciences, Hamilton Thorne, IVFtech, Hunter Scientific, LAMSYSTEMS, Leica Microsystems, MTG Medical Technology, Silver Arrow Medicare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IVF Workstation Market Shifts & Advancements
Automation architectures and regulatory classification frameworks are simultaneously redefining workstation design priorities and procurement criteria across fertility clinic networks.
Polycarbonate enclosure assemblies are replacing glass-and-steel housings in next-generation workstation designs. Fertility clinic operators in Germany and the United States are specifying polymer-based platforms for new laboratory construction. This material transition is modularizing supply chain configurations, enabling regional injection molding capacity to substitute for precision glass fabrication.
The EU AI Act's risk-based classification framework is reshaping automated embryo assessment deployment. Algorithms embedded in time-lapse imaging modules now face heightened clinical evidence requirements before CE marking. Workstation manufacturers serving the European Union are restructuring software validation protocols to accommodate this regulatory expansion.
Service unbundling is disrupting traditional capital equipment procurement. Fertility clinic groups in the United Kingdom and Australia are separating hardware acquisition from maintenance and consumables contracts. This purchasing pattern compression is forcing workstation vendors to compete on discrete value components rather than bundled lifecycle pricing.
IVF Workstation Market Segmentation
IVF workstation procurement patterns diverge sharply across clinical settings and technological tiers. Fertility clinic operators prioritize thermal stability and contamination control specifications that vary by procedure volume and regulatory jurisdiction.
Product Type:
Supply concentration in polycarbonate enclosure manufacturing favors platforms with standardized polymer housings over legacy glass-and-steel assemblies.
- Embryo Culture System:Maintains 37°C ± 0.2°C and 6% CO₂ atmospheric conditions through heated stages and HEPA-filtered airflow. Demand concentrates in Germany and the United States where fertility clinics are expanding in-house embryology laboratories to reduce outsourcing costs. The universal requirement across all IVF cycles sustains the largest installed base.
- Intracytoplasmic Sperm Injection:Integrates micromanipulators with inverted microscopes for precise gamete handling. Adoption is climbing fastest in India and China as domestic fertility networks build regional capacity in Mumbai, Delhi, and Bangalore.
- Cryopreservation Equipment:Enables vitrification and storage of oocytes and embryos at cryogenic temperatures.
- PGT Device:Supports embryo biopsy for preimplantation genetic testing with integrated laser systems.
Today's leader: Embryo Culture System. Tomorrow's challenger: Intracytoplasmic Sperm Injection.
End User:
Cost tier stratification separates high-volume capital purchasers from research-oriented buyers with intermittent procurement cycles.
- Fertility Clinics:Absorb the majority of capital expenditure through multi-year equipment refresh cycles. Procurement in the United States and Western Europe favors bundled contracts combining workstations with media and cultureware consumables.
- Cryobanks:Commercial egg and sperm banking operations in the United States are emerging as concentrated secondary buyers with standardized high-volume procurement protocols.
- Research Institutes:Require flexible configurations for experimental protocols with lower utilization rates.
- Hospitals:Integrate workstations into broader reproductive medicine departments with shared infrastructure.
The dominant volume position belongs to Fertility Clinics. Cryobanks are gaining share fastest as commercial banking scales.
Technology:
Application requirements dictate technology selection, with automated platforms displacing manual workstations in high-throughput environments.
- Automated Workstations:Reduce manual embryo handling through robotic micromanipulation and integrated quality monitoring. Labor cost pressures in the United States are accelerating deployment as clinics process higher case volumes per embryologist.
- Time-Lapse Imaging:Captures continuous embryo development without removal from controlled incubation. The EU AI Act's risk-based classification is reshaping deployment as embedded assessment algorithms face heightened clinical evidence requirements.
- Laser Systems:Enable precise zona pellucida drilling and embryo biopsy for genetic testing applications.
- Electrophysiology:Supports research-oriented gamete characterization and membrane potential studies.
Current procurement favors Time-Lapse Imaging. Automated Workstations show the steepest expansion trajectory as reproducibility standards tighten.
Application:
Customer type and procedure reimbursement patterns segment demand across clinical and research domains.
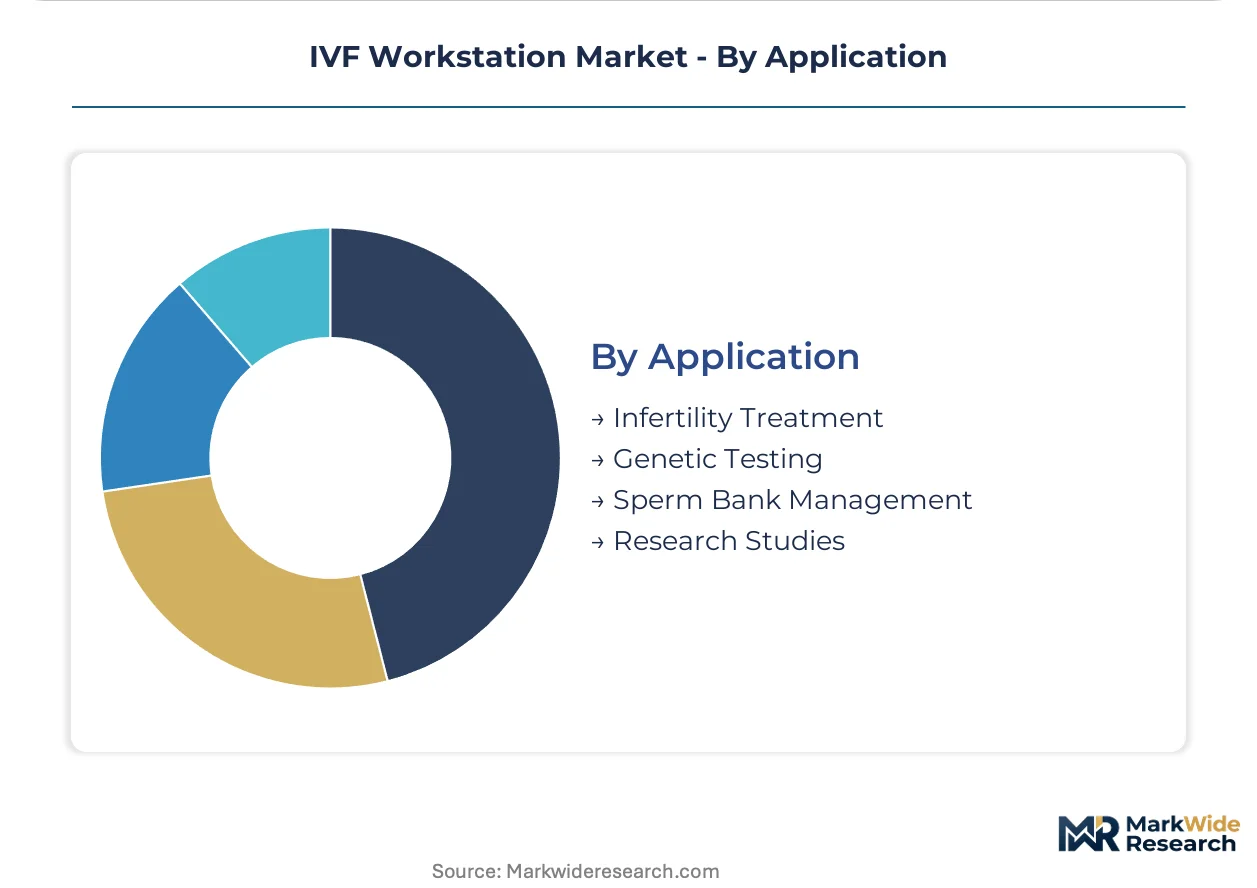
- Infertility Treatment:Encompasses standard IVF and ICSI cycles with the highest procedure volume globally. Regulatory pathways through FDA 510(k) and EU MDR Class IIa determine market access timelines for workstation manufacturers.
- Genetic Testing:Embryo biopsy and PGT workflows require laser-integrated platforms with enhanced micromanipulation stability.
- Sperm Bank Management:Concentrated demand from commercial cryobanking operations with standardized processing protocols.
- Research Studies:Academic and pharmaceutical research programs with specialized configuration requirements and extended procurement cycles.
Infertility Treatment commands current volume leadership. Genetic Testing is expanding most quickly as PGT reimbursement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing clusters anchor IVF workstation supply chains, while regulatory divergence between FDA and EU MDR pathways fragments certification strategies across Atlantic markets.
United States
Fertility clinics in California and Texas are expanding in-house embryology laboratories to reduce outsourcing costs. FDA's 510(k) clearance pathway determines market access timelines for workstation manufacturers. CooperSurgical leverages its integrated consumables portfolio to bundle workstations with media and cultureware, locking in multi-year clinic contracts across the Sun Belt.
Germany
Precision enclosure manufacturing concentrates in Baden-Württemberg and Bavaria, supplying polycarbonate housing assemblies to European workstation builders. EU MDR Class IIa device classification raises certification barriers, filtering out marginal suppliers. Stuttgart's medical technology corridor hosts specialized cleanroom component fabricators serving fertility clinic networks in France and the Netherlands.
China
Domestic fertility networks in Shanghai, Beijing, and Guangzhou are building regional embryology capacity. NMPA's priority review channel for assisted reproductive technologies opens accelerated market access for automated workstation platforms. Esco Lifesciences anchors Asia-Pacific supply chains through vertically controlled manufacturing campuses in Singapore and China.
India
Regional capacity expansion across Mumbai, Delhi, and Bangalore generates concentrated demand for embryo culture systems and cryopreservation workstations. CDSCO medical device regulations shape import substitution strategies for domestic manufacturers. Hyderabad's life sciences corridor attracts workstation distributors targeting Tier-2 fertility clinic buildouts.
United Kingdom
Premium fertility clinics in London and Manchester maintain preference for legacy glass-and-steel enclosure materials, limiting polymer penetration in high-end segments. MHRA post-Brexit regulatory alignment with EU MDR extends certification timelines. Service unbundling disrupts traditional capital equipment procurement as clinic groups separate hardware acquisition from maintenance contracts.
IVF Workstation Market Competitive Landscape
Global majors compete with regional champions across regulatory certification and consumables bundling strategies. The vendor base stratifies into three tiers: integrated life sciences conglomerates with full consumables portfolios, specialized embryology equipment manufacturers with imaging-integrated platforms, and regional assembly houses serving price-sensitive markets. Dominant competitive moves include strategic partnerships with fertility clinic networks and geographic expansion through distributor relationships in emerging Asian markets.
Among integrated life sciences conglomerates, CooperSurgical exemplifies the consumables-anchored archetype through its bundled contract structures. Esco Lifesciences occupies a position within the Asia-Pacific supply chain control tier, leveraging vertically integrated manufacturing campuses. Hamilton Thorne represents the imaging-integrated specialization vector, embedding time-lapse modules that reduce manual embryo handling cycles.
| Leading Market Players |
|---|
| CooperSurgical |
| Esco Lifesciences |
| Hamilton Thorne |
| IVFtech |
| Hunter Scientific |
| LAMSYSTEMS |
| Leica Microsystems |
| MTG Medical Technology |
| Silver Arrow Medicare |
| Others |
Supply & Pricing Matrix
Polycarbonate resin feedstock costs cascade through three workstation pricing tiers, with petrochemical volatility in East Asian supply hubs compressing margins for enclosure manufacturers serving mid-market fertility clinics in India and China.
Pricing Analysis
Input-cost pass-through from polymer suppliers to workstation assemblers operates on quarterly contract adjustments, leaving limited pricing power for manufacturers without backward integration into injection molding. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked Class IIa certified platforms from CDSCO-registered variants and unbundled hardware-only configurations. Pricing pressure stems from fertility clinic procurement committees in the United Kingdom unbundling service contracts from capital equipment. Cryobanks show lowest price sensitivity due to standardized high-volume protocols, while Tier-2 clinic buildouts in India represent the most price-constrained buyer segment.
Supply Chain Analysis
EU MDR Class IIa qualification requirements gate component supply, with polycarbonate enclosure fabrication concentrated in Germany, Singapore, and China's Yangtze River Delta. Critical inputs include optical-grade polycarbonate resin, HEPA filtration media, and precision micromanipulator stages. Single-source vulnerability sits with German cleanroom component fabricators serving CE-marking pathways. Distribution runs through authorized medical device distributors with regulatory compliance capabilities, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into sustainable competitive advantage, with the EU AI Act's risk-based framework for automated embryo assessment algorithms driving demand for validated software-integrated platforms.
For Market Incumbents: Cement multi-year consumables bundling to lock in fertility clinic refresh cycles against emerging Asian competitors with unbundled pricing. Deepen backward integration into polycarbonate injection molding to insulate margin structures from petrochemical volatility. Prioritize MDR recertification investment ahead of AI Act algorithm validation requirements.
For New Entrants and Emerging Players: Begin with cryobank commercial banking operations in the United States, where standardized high-volume procurement protocols reduce embryologist specialization barriers. Target NMPA priority review channel positioning for automated workstation platforms in China's domestic fertility network buildout. Deploy distributor partnerships with regulatory compliance capabilities rather than direct sales infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for imaging-integrated workstation specialists because time-lapse module differentiation is concentrating procurement among vendors with embedded AI assessment capabilities. Five-to-ten year viability hinges on software validation moats rather than hardware manufacturing scale. Watch for EU AI Act enforcement actions against non-compliant embryo assessment algorithms as inflection indicator for certification-premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Recertification | Filters marginal suppliers and concentrates procurement among certified German and French vendors. |
| Time-Lapse Imaging Module Integration | Reduces manual embryo handling cycles for US fertility clinics processing higher case volumes. |
| Consumables Bundling Contracts | Locks in multi-year clinic relationships through integrated media and cultureware portfolios. |
| NMPA Priority Review Channel Entry | Accelerates market access for automated platforms in China's domestic fertility network expansion. |
| Cryobank Commercial Banking Partnership | Captures concentrated secondary demand from standardized high-volume procurement protocols. |
Research Methodology
Coverage spans the United States, Germany, China, India, and the United Kingdom, with primary inputs from each market cluster. The research combines structured interviews with embryology laboratory directors, biomedical equipment procurement managers, GPO contracts specialists, and regulatory affairs leads at workstation manufacturers with secondary validation against FDA 510(k) filings, EU MDR technical documentation, NMPA registration databases, and hospital capital expenditure records. Bottom-up demand modeling triangulates against top-down supply-side capacity assessments.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, end-user category, technology tier, and application workflow. CAGRs derive from fitted growth curves calibrated to regulatory milestone timelines and fertility clinic capital expenditure cycles. Industry-specific inputs incorporate embryologist workforce density by region and reimbursement expansion trajectories for PGT procedures.
Several conditions sit outside the modeled scope, including abrupt changes in EU AI Act enforcement interpretation, polycarbonate feedstock supply disruptions from geopolitical events, and fertility clinic consolidation patterns that alter procurement decision-making structures. Forecasts reflect assumptions about regulatory pathway stability and continued NMPA streamlining for assisted reproductive technologies. A model refresh is warranted upon material change in EU MDR certification timelines or NMPA priority review channel suspension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
Cell Disruption Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
PCR Consumables Market
Biotechnology Equipment
Cell Proliferation Kit Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Bioprocess Analyzers and Technology Market
Biotechnology Equipment
Global Transfection Technologies Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Cryopreservation Equipment Market