
 Plant Phenotyping Equipment Market | 2026-2036
Plant Phenotyping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Phenotyping Equipment Market Analytics
Subscription-based phenotyping analytics is recalibrating how equipment vendors monetize hardware deployments. LemnaTec GmbH leverages its modular platform architecture to anchor recurring revenue streams alongside instrument sales. Heinz Walz GmbH sustains technology leadership through deep specialization in chlorophyll fluorescence systems. Phenospex competes by extending portable 3D canopy scanning into field environments where laboratory-bound rivals lack reach.
Plant phenotyping equipment comprises integrated sensor arrays, imaging modules, and environmental control systems designed to capture quantitative morphological, physiological, and biochemical plant traits under controlled or field conditions; hyperspectral imaging systems operating across 400-1000 nm wavebands enable non-destructive assessment of leaf chlorophyll content and water stress indicators. Automated platforms dominate capital deployment among agricultural research institutes due to throughput advantages in multi-environment trial networks. Trait analysis applications absorb the largest share of analytical software licensing as seed companies prioritize genomic selection pipelines. RGB camera modules retain cost advantages in yield estimation workflows where spectral resolution offers marginal return.
The EU Green Deal and associated Farm to Fork strategy shape equipment specifications through mandated sustainability reporting on crop genetic improvement timelines. Germany's KBA and France's ANSM do not regulate this sector directly; instead, EFSA guidelines on novel food varieties and REACH compliance for sensor materials constrain product design choices. Stakeholders must monitor how emerging EU AI Act classifications affect automated image analysis algorithms embedded in phenotyping platforms. The convergence of regulatory pressure on breeding acceleration and machine-vision standardization will determine which vendors capture platform-level contracts.
Market Dynamics
Subscription-based phenotyping analytics is recalibrating how equipment vendors monetize hardware deployments, with recurring revenue streams displacing pure instrument sales as the dominant commercial model.
Growth Catalysts
- EU Green Deal biodiversity targets:Mandated acceleration of crop development cycles pressures breeders to deploy high-throughput phenotyping infrastructure.
- Hyperspectral imaging systems:Non-destructive assessment capabilities across 400-1000 nm wavebands enable water stress monitoring and chlorophyll quantification at scale.
- German and Dutch agricultural research institutes:Publicly funded precision agriculture programs in these countries anchor regional infrastructure deployment.
Market Restraints
- Sensor material compliance costs:REACH restrictions on specialized optical components and rare-earth magnet specifications inflate procurement expenses.
- Technical standardization gaps:Absence of unified protocols for automated image analysis algorithms complicates cross-platform data interoperability.
- Capital intensity barriers:Automated platform deployments require substantial upfront investment, limiting access for smaller breeding operations.
Strategic Opportunities
- Portable 3D canopy scanning:Field-deployable systems extend phenotyping reach beyond laboratory-bound competitors into unpenetrated agricultural zones.
- EU AI Act classification clarity:Emerging regulatory frameworks for automated image analysis create first-mover advantages for compliant platform vendors.
- Trait analysis software licensing:Seed companies prioritizing genomic selection pipelines present underexploited revenue channels for analytical modules.
Industry Challenges
- Machine-vision standardization delays:Fragmented algorithm certification pathways slow automated trait extraction deployment timelines.
- Integration complexity with legacy breeding databases:Established genomic information management systems resist seamless phenotypic data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Phenotyping Equipment Market |
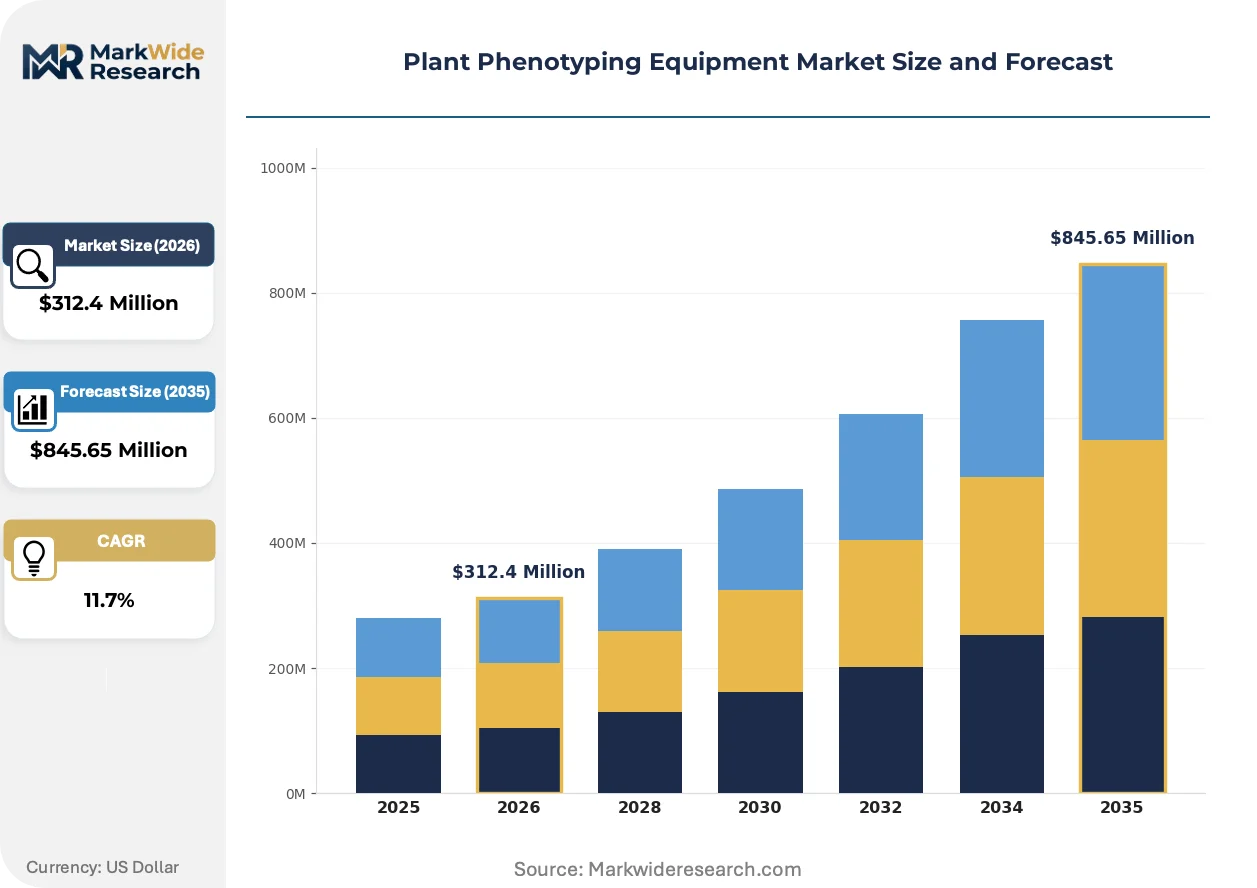
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Sensor Networks, Automated Platforms, Mobile Equipment Technology: Hyperspectral Imaging, Laser Scanning, Acoustic Sensors, RGB Cameras End User: Agricultural Research, Academic Institutions, Agricultural Corporations, Public Agencies Application: Trait Analysis, Yield Estimation, Disease Detection, Stress Assessment |
| Companies Covered | LemnaTec GmbH, Heinz Walz GmbH, Phenospex, KeyGene, BASF SE, Photon Systems Instruments, Delta-T Devices, Qubit Systems, Rothamsted Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Phenotyping Equipment Market Evolving Landscape
Equipment architecture is pivoting from standalone instruments toward modular, sensor-agnostic platforms capable of field reconfiguration. Three developments are compressing competitive timelines.
Hyperspectral imaging is consolidating its position as the dominant non-destructive sensing modality for physiological trait capture. Agricultural research institutes in Germany and the Netherlands are deploying these systems at accelerating rates within multi-environment trial networks. The technology is consolidating vendor market power around integrated hardware-software stacks that lock in recurring analytics subscriptions.
REACH compliance for sensor materials is reshaping component sourcing strategies across European equipment manufacturers. EFSA guidelines on novel food varieties create parallel documentation burdens for phenotyping data used in variety registration. Seed companies operating genomic selection pipelines face the steepest adaptation costs as they reconcile phenotypic datasets with emerging chemical safety dossier requirements.
Service unbundling is fragmenting traditional equipment procurement patterns. Research institutes now separate hardware acquisition from analytics licensing and maintenance obligations, compressing vendor margins on initial instrument sales. This behavioral shift is most pronounced in Western Europe where publicly funded programs enable multi-year subscription commitments independent of capital budget cycles.
Plant Phenotyping Equipment Market Segmentation
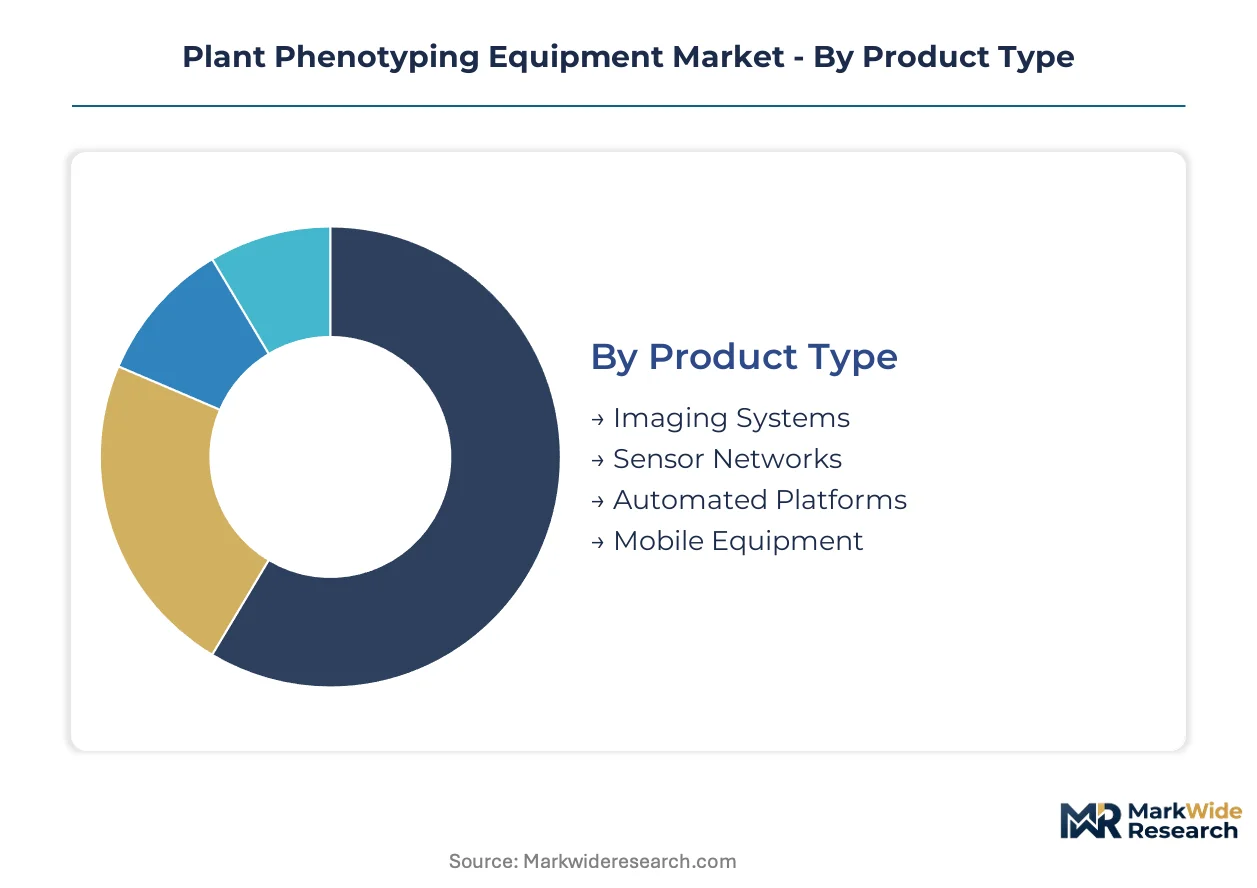
Equipment segmentation in plant phenotyping reflects divergent capital deployment strategies across research and commercial breeding operations. Procurement patterns cluster around throughput requirements, field mobility needs, and integration depth with genomic selection pipelines.
Product Type:
Supply concentration tilts toward integrated platform vendors capable of bundling hardware with recurring analytics subscriptions.
- Imaging Systems:Hyperspectral and multispectral camera arrays operating across 400-1000 nm wavebands capture leaf chlorophyll content and water stress indicators. German and Dutch agricultural research institutes deploy these most intensively within multi-environment trial networks pressured by EU Green Deal acceleration timelines.
- Automated Platforms:Conveyor-based systems with environmental control chambers enable high-throughput trait extraction under standardized conditions. Seed companies prioritize these for genomic selection pipelines where throughput directly compresses variety development cycles.
- Sensor Networks:Distributed IoT architectures for continuous field monitoring.
- Mobile Equipment:Portable units extending phenotyping into uncontrolled agricultural environments.
Automated platforms absorb the bulk of installed capacity; mobile equipment is expanding most quickly.
Technology:
Cost tier differentiation separates premium spectral systems from commodity imaging hardware serving yield estimation workflows.
- Hyperspectral Imaging:Non-destructive physiological assessment across narrow wavebands enables chlorophyll quantification and early stress detection. REACH compliance costs for specialized optical components constrain vendor margins while consolidating market power around integrated hardware-software stacks.
- RGB Cameras:Standard visible-spectrum imaging modules retain cost advantages where spectral resolution offers marginal return. Academic institutions with constrained capital budgets favor these for basic morphological trait extraction.
- Laser Scanning:LiDAR-based 3D canopy reconstruction for structural phenotyping.
- Acoustic Sensors:Vibration-based biomass estimation and root system characterization.
Hyperspectral imaging commands the premium tier; RGB cameras dominate volume shipments.
End User:
Customer type determines procurement modality, with public research institutes favoring capital purchases and seed companies migrating toward subscription analytics.
- Agricultural Research:Publicly funded institutes in Germany and the Netherlands anchor regional infrastructure deployment through multi-year precision agriculture programs. These institutions drive standardization demands for cross-platform data interoperability.
- Agricultural Corporations:Commercial breeding operations integrate phenotyping data directly into variety registration dossiers. EFSA guidelines on novel food varieties create documentation burdens that favor vendors with established regulatory compliance pathways.
- Academic Institutions:University laboratories with fragmented funding cycles.
- Public Agencies:Government extension services supporting regional agricultural monitoring.
Agricultural research absorbs the bulk of installed capacity; agricultural corporations are climbing the fastest.
Application:
Application maturity varies sharply, with trait analysis software licensing already consolidated while disease detection algorithms await EU AI Act classification clarity.
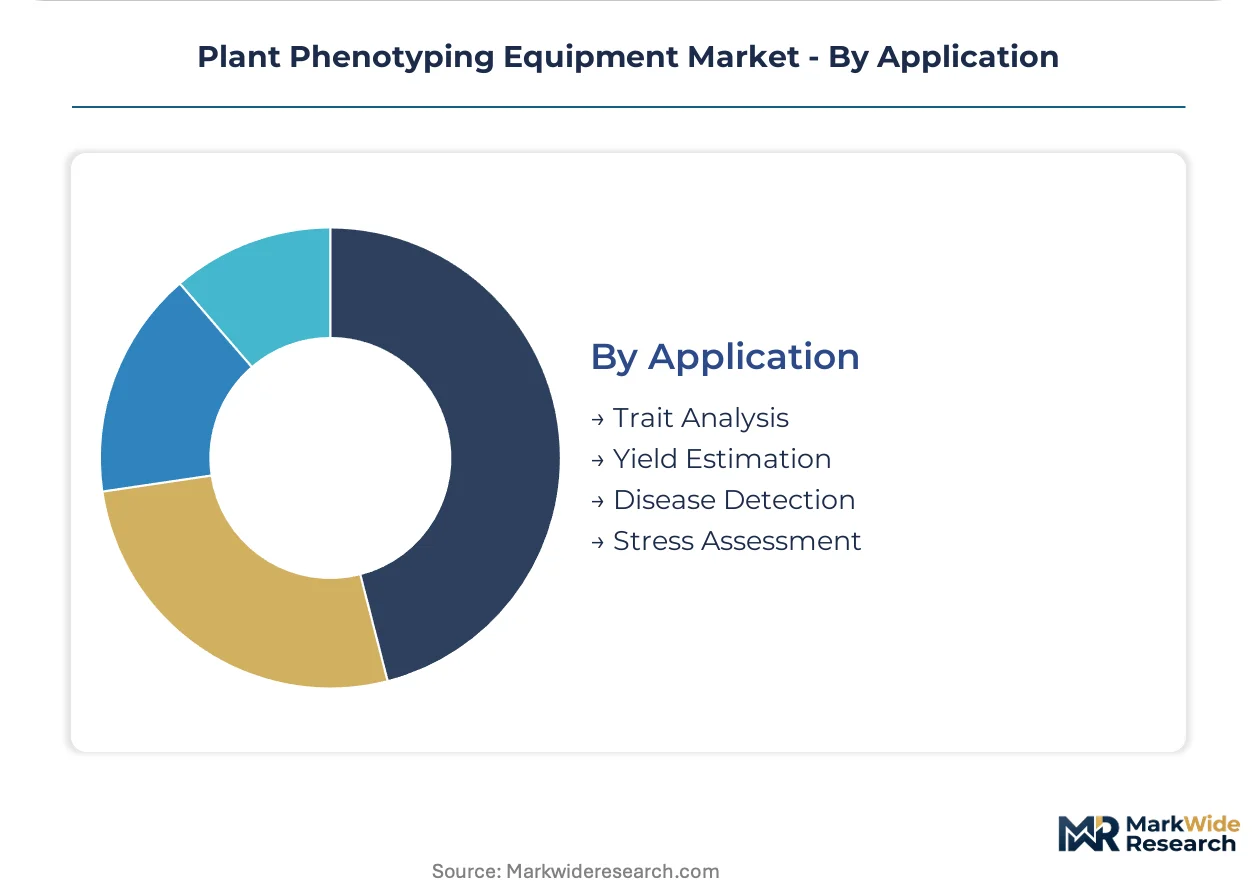
- Trait Analysis:Quantitative morphological and physiological characterization feeding genomic selection pipelines. Seed companies prioritize this application for its direct impact on breeding cycle compression mandated by EU biodiversity targets.
- Yield Estimation:Pre-harvest productivity prediction using canopy spectral indices. RGB camera cost advantages concentrate demand here among smaller breeding operations unable to justify hyperspectral capital expenditure.
- Disease Detection:Automated pathogen identification through spectral signature analysis.
- Stress Assessment:Abiotic factor monitoring for drought, salinity, and temperature response.
Trait analysis anchors current revenue; disease detection shows steepest expansion trajectory pending regulatory clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of plant phenotyping equipment concentrates in Western Europe while consumption spreads across research-intensive agricultural zones. German and Dutch engineering clusters supply integrated platforms to institutes worldwide. Demand fragmentation reflects divergent public funding cycles and breeding industry consolidation patterns.
Germany
Agricultural research institutes in Bavaria and North Rhine-Westphalia deploy high-throughput conveyor systems for multi-environment trials. KBA vehicle standards do not regulate phenotyping equipment directly, though REACH compliance for sensor materials shapes component sourcing strategies. The Jülich Research Centre anchors hyperspectral imaging adoption for drought stress quantification.
Netherlands
Wageningen University & Research drives demand for automated greenhouse phenotyping platforms. The country's national precision agriculture program funds infrastructure deployment through multi-year grants. Eindhoven's photonics cluster supplies specialized optical components to equipment manufacturers serving European breeding networks.
France
ANSM oversight of medical device standards does not extend to agricultural equipment, leaving EFSA novel food guidelines as the primary regulatory frame. INRAE research stations in Île-de-France and Occitanie integrate phenotyping data into variety registration dossiers. The Montpellier ag-tech corridor hosts field-deployable system developers targeting Mediterranean cropping systems.
United Kingdom
Rothamsted Research in Hertfordshire maintains legacy infrastructure while migrating toward modular sensor networks. Defra-funded sustainable agriculture programs compress equipment replacement cycles. The Cambridge-Norwich agri-tech cluster attracts hyperspectral imaging specialists serving wheat breeding programs.
United States
USDA ARS stations in Iowa and California deploy portable canopy scanners for regional variety trials. EPA water quality monitoring requirements indirectly shape field equipment specifications for runoff-conscious deployments. The Midwest corn belt concentrates demand for yield estimation workflows using RGB camera modules.
Plant Phenotyping Equipment Market Competitive Landscape
Capital-heavy platform manufacturers compete with asset-light analytics specialists for recurring revenue streams. The vendor base separates between integrated system architects and component suppliers. Three archetypes dominate: modular platform builders anchoring subscription models, fluorescence instrumentation specialists defending technology niches, and portable field system developers extending reach beyond laboratory boundaries. Competitive moves concentrate on service unbundling to capture analytics licensing and strategic positioning for EU AI Act compliance.
Among German GmbH-structured equipment builders, LemnaTec GmbH and Heinz Walz GmbH exemplify divergent specialization strategies. LemnaTec occupies a position as a modular platform architect enabling recurring revenue through analytics subscriptions. Heinz Walz anchors the fluorescence instrumentation tier with deep technical specialization. Phenospex represents the field-extension archetype, with Dutch-originated portable 3D canopy scanning capabilities.
| Leading Market Players |
|---|
| LemnaTec GmbH |
| Heinz Walz GmbH |
| Phenospex |
| KeyGene |
| BASF SE |
| Photon Systems Instruments |
| Delta-T Devices |
| Qubit Systems |
| Rothamsted Research |
| Others |
Value Network & Pricing Analysis
Hyperspectral imaging module miniaturization is compressing unit economics while redrawing vendor competitive boundaries, as German and Dutch photonics clusters capture value from REACH-compliant component sourcing. Equipment buyers now face trade-offs between capital expenditure flexibility and locked-in analytics subscriptions.
Pricing Analysis
Margin tightening in automated platform tiers reflects REACH compliance costs for specialized optical components and rare-earth magnet specifications. Three-tier pricing structure across premium hyperspectral systems, standard multispectral configurations, and economy RGB modules stratifies the installed base. Academic institutions in Western Europe exhibit highest price sensitivity due to fragmented funding cycles, while seed companies prioritizing genomic selection pipelines accept premium positioning for throughput advantages.
Supply Chain Analysis
Refurbishment flows for imaging sensor arrays and environmental control chambers extend equipment lifecycles, compressing new-unit demand in publicly funded research institutes. Manufacturing concentrates in Germany, the Netherlands, and the United Kingdom, with Eindhoven's photonics cluster supplying specialized optical components. Supply chain risk centers on single-source vulnerability for narrow-waveband detectors. Distribution runs through direct vendor relationships with agricultural research institutes and seed company procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into optical component manufacturing and captive analytics software development is accelerating as vendors seek margin defense against unbundling pressures.
For Market Incumbents: Lock in recurring revenue through multi-year analytics subscriptions anchored to modular platform architectures, while deepening sensor component sourcing from REACH-compliant European suppliers to preempt regulatory disruption. Portable field system developers represent the most threatening entrant archetype. For New Entrants and Emerging Players: Agricultural extension services in Mediterranean cropping zones offer the most penetrable channel partnership avenue, as these agencies lack capital budgets for automated platforms but require field-deployable trait extraction. White-space concentration appears in disease detection algorithms awaiting EU AI Act classification clarity. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to precision agriculture conglomerates seeking phenotyping data pipelines. Long-term viability hinges on regulatory compliance capabilities rather than hardware differentiation alone. The signal to watch is EU AI Act implementation timelines affecting automated image analysis algorithm certification.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Architecture | Enables subscription revenue streams at LemnaTec GmbH and competing vendors. |
| REACH Compliance Investment | Reshapes component sourcing for German manufacturers facing optical material restrictions. |
| Field System Development | Extends phenotyping reach beyond laboratory boundaries into Mediterranean agricultural zones. |
| Analytics Software Licensing | Captures recurring revenue from seed companies operating genomic selection pipelines. |
| EU AI Act Certification | Creates first-mover advantage for automated trait extraction algorithm vendors. |
Research Methodology
Multi-period observation of equipment deployment rates at German and Dutch agricultural research institutes anchored the trend analysis, supplemented by interviews with phenotyping platform engineers, seed company breeding operations directors, agricultural research institute procurement managers, and optical component sourcing specialists. Secondary validation drew from EFSA novel food guideline documentation, EU Green Deal biodiversity target specifications, REACH regulatory filings, and publicly funded precision agriculture program disclosures. Bottom-up triangulation across vendor shipment records and top-down reconciliation with public research budget allocations ensured cross-verification.
Input-output matrix modeling connected hyperspectral imaging adoption rates, genomic selection pipeline integration depth, and regulatory compliance cost burdens to equipment demand projections across the analysis window. Segmentation dimensions included product type, technology tier, end-user category, and application maturity. CAGRs derived from curve-fitting observed adoption velocities against EU-mandated breeding acceleration timelines, with sensor material cost inflation and analytics subscription penetration serving as key forecast inputs.
Caveats apply where EU AI Act classification delays or REACH scope expansions could materially shift the outlook for automated platform vendors. Practitioners should monitor regulatory implementation timelines and public research funding cycle disruptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Lab Automation in Bioanalysis Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Biotechnology Instrumentation Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
Cell Proliferation Kit Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Small-Scale Bioreactors Market
Biotechnology Equipment
Bioprocessing Systems Market