
 Automated Molecular Diagnostics Testing System Market | 2026-2036
Automated Molecular Diagnostics Testing System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Molecular Diagnostics Testing System Market Outlook
Hospital laboratories is collapsing the traditional dominance of reference labs in molecular testing volume. Roche Diagnostics leverages its installed base of cobas platforms to sustain recurring reagent revenue across major health systems. Abbott Laboratories anchors its competitive position through point-of-care molecular systems that bypass centralized lab workflows. Thermo Fisher Scientific competes by extending its clinical NGS portfolio into automated sample-to-answer workflows for oncology panels.
An automated molecular diagnostics testing system integrates nucleic acid extraction, amplification, and detection modules within a single instrument platform, typically processing 96-384 samples per run with less than five percent hands-on time. These systems serve primarily to standardize pathogen identification and genetic variant detection while minimizing operator error and cross-contamination risk. PCR-based automated systems occupy the largest installed base among product categories, though NGS platforms capture the fastest growth as tumor profiling panels expand into community hospital settings. Diagnostic laboratories represent the most concentrated end-user segment by revenue, yet home care is emerging as a structural growth vector as capillary blood collection and microfluidic cartridge designs simplify self-administered infectious disease screening.
The FDA enforces premarket notification and quality system regulation requirements that shape instrument design toward closed, assay-specific platforms rather than open reagent systems. CLIA certification tiers from the Centers for Medicare and Medicaid Services determine which laboratory types may perform high-complexity molecular testing, directly constraining addressable market scope by end-user segment. Stakeholders must monitor how the FDA's evolving oversight of laboratory-developed tests intersects with automated platform standardization to determine whether consolidation favors integrated device manufacturers or independent assay developers.
Market Dynamics
The FDA's laboratory-developed test enforcement is fragmenting the competitive landscape by privileging closed-system instrument manufacturers over open-platform reagent suppliers, compressing margins for independent assay developers while entrenching integrated device makers.
Growth Catalysts
- CLIA high-complexity certification expansion:The Centers for Medicare and Medicaid Services is certifying more hospital laboratories for complex molecular testing, enlarging the addressable end-user base beyond reference laboratories.
- Sepsis panel reimbursement:United States Medicare coverage decisions for rapid bloodstream pathogen identification are pulling automated platform adoption into community hospital emergency departments.
- Microfluidic cartridge miniaturization:Advances in lab-on-chip architectures are collapsing sample volume requirements, enabling capillary blood collection for infectious disease screening outside traditional phlebotomy settings.
Market Restraints
- Reagent rental lock-in:Closed-system architectures from dominant instrument manufacturers create captive supply relationships that inflate lifetime cost of ownership for diagnostic laboratories.
- Polymerase supply concentration:Thermostable DNA polymerase production concentrates among three specialty chemical suppliers, exposing automated system operators to input cost volatility during fermentation capacity constraints.
- Quality system regulation compliance burden:FDA 21 CFR Part 820 requirements extend development timelines for new assay-menu expansions, delaying revenue realization from platform investments.
Strategic Opportunities
- Home care infectious disease screening:Self-administered respiratory panels using finger-stick capillary collection represent underpenetrated demand in United States retail pharmacy channels.
- NGS-polymerase chain reaction convergence:Hybrid platforms combining targeted amplification with next-generation sequencing readouts are opening oncology profiling workflows to mid-volume hospital laboratories.
- Integrated delivery network procurement centralization:Multi-site instrument contracts negotiated by United States health systems are creating volume aggregation opportunities for vendors with scalable service infrastructure.
Industry Challenges
- Cross-training molecular technologists:Automated platforms still require specialized operators for troubleshooting and quality control, and workforce pipelines for clinical laboratory scientists remain constrained.
- Legacy laboratory information system integration:Middleware compatibility gaps between new automated instruments and existing hospital IT architectures extend deployment timelines and inflate implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Molecular Diagnostics Testing System Market |
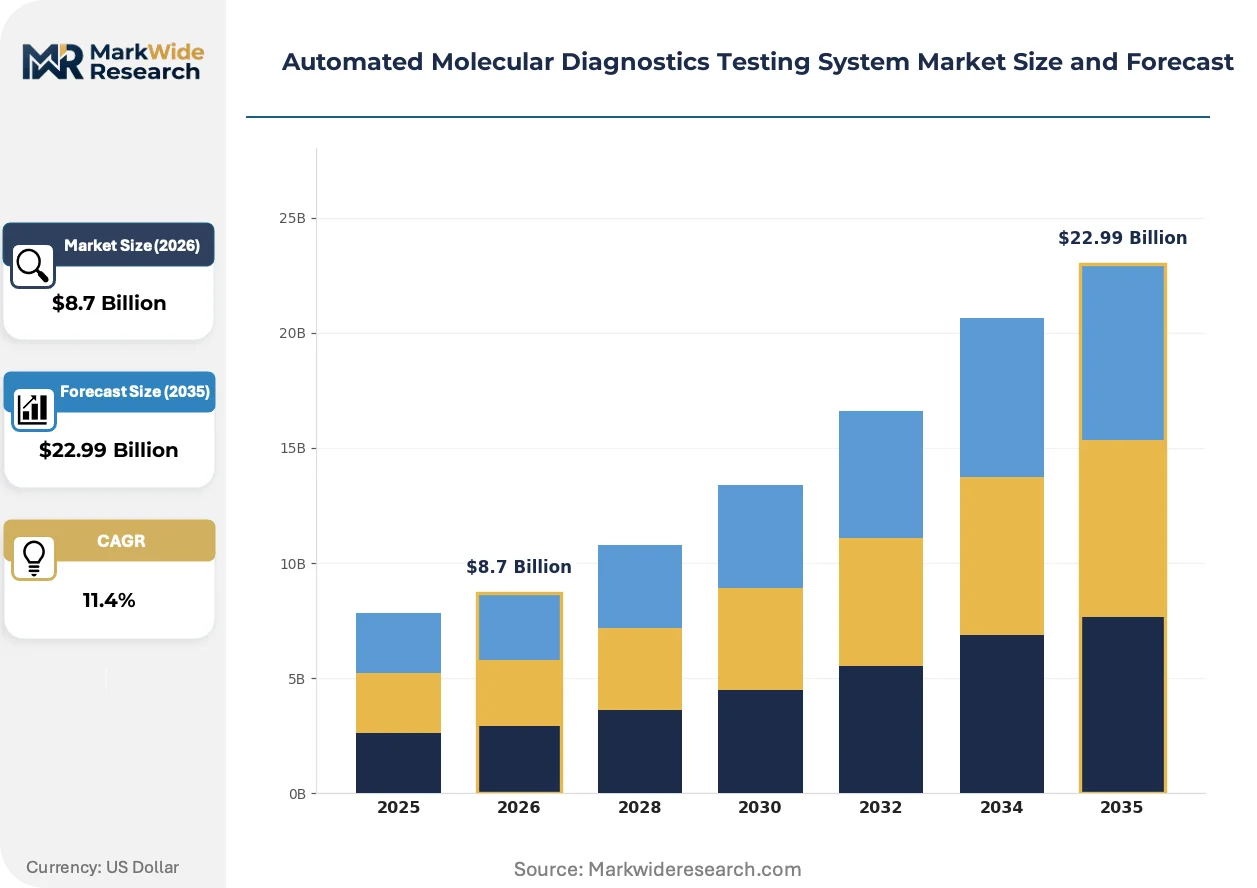
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR, RT-PCR, NGS, Microarray Application: Infectious Diseases, Genetic Testing, Oncology, Pharmacogenomics End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Care Technology: Automated Systems, Point-of-Care, Cloud-Based, Software Solutions |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Becton Dickinson and Company, Siemens Healthineers, QIAGEN, Cepheid, Thermo Fisher Scientific, Danaher Corporation, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Molecular Diagnostics Testing System Market Strategic Shifts
Sample-to-answer automation is collapsing the historical separation between nucleic acid extraction and detection workflows, compressing turnaround times while raising the technical bar for platform engineering.
Digital microfluidics is decomposing the traditional physical separation between liquid handling modules in automated molecular systems. Community hospital laboratories are adopting cartridge-based platforms that integrate extraction, amplification, and detection within single-use consumables. This architecture is decomposing the service revenue model for field engineers by reducing moving parts and preventive maintenance intervals.
European Medical Device Regulation (MDR) is extending conformity assessment requirements to automated molecular diagnostics platforms previously governed by directive-based frameworks. Manufacturers face notified body bottlenecks for clinical evidence review, compressing product launch cadences. In vitro diagnostic device companies are responding by consolidating assay menus onto fewer platform generations to amortize certification costs across larger installed bases.
Integrated delivery networks are consolidating procurement authority for automated molecular systems into centralized supply chain functions, displacing decentralized laboratory director purchasing autonomy. Reference laboratories and hospital systems are ceding vendor selection to health system executives who negotiate enterprise-wide contracts spanning multiple sites. This concentration is most visible in United States metropolitan markets where three-hospital systems dominate inpatient molecular testing volume.
Automated Molecular Diagnostics Testing System Market Segmentation
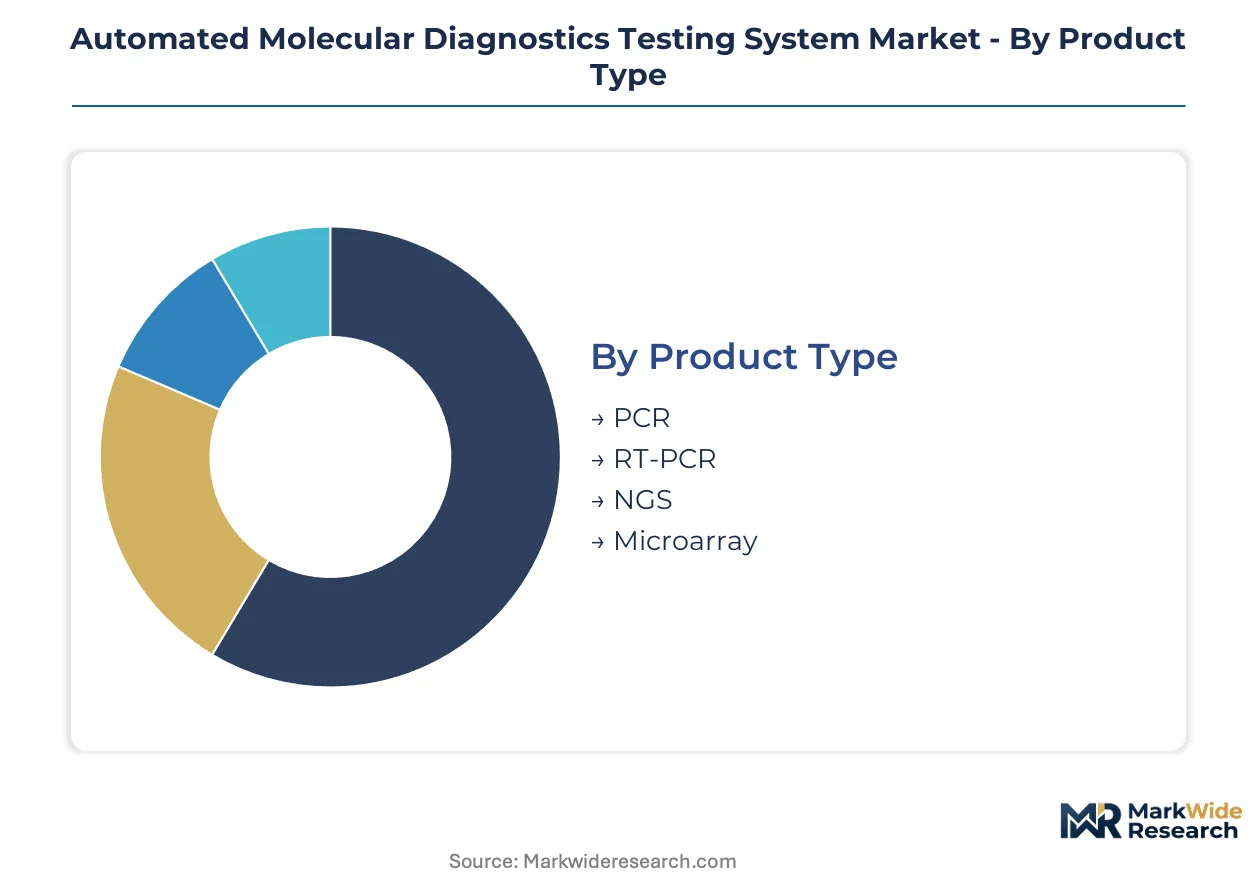
Automated molecular diagnostics systems fragment across four dimensions that determine regulatory pathways, reimbursement eligibility, and procurement authority. Product type governs FDA premarket classification tiers. Application scope shapes CLIA complexity certification requirements. End-user category determines capital deployment models and service infrastructure needs. Technology architecture dictates middleware integration burdens and data governance frameworks.
Product Type:
FDA enforcement of quality system regulations creates divergent compliance burdens across amplification and sequencing platforms, privileging closed-system manufacturers with integrated assay menus over open-platform reagent suppliers.
- PCR:Thermal cycling instrumentation dominates hospital laboratory installed bases through standardized pathogen identification workflows. United States community hospitals concentrate demand here for sepsis and respiratory panels as Medicare reimbursement expands for rapid bloodstream pathogen detection.
- RT-PCR:Reverse transcription modules enable RNA virus quantification within single-instrument architectures. Diagnostic laboratories in integrated delivery networks favor these platforms for influenza and SARS-CoV-2 surveillance contracts that require same-shift turnaround.
- NGS:Next-generation sequencing platforms capture oncology profiling demand as tumor mutation burden testing migrates from reference laboratories into mid-volume hospital settings.
- Microarray:Solid-phase hybridization systems retain niche positioning for pharmacogenomics screening and constitutional genetic variant detection in academic medical centers.
PCR handles the majority of throughput; NGS is climbing the fastest on share as community hospitals adopt tumor profiling workflows.
Application:
Reimbursement policy and CLIA certification tiers partition addressable volume across clinical indications, with infectious disease commanding the largest eligible test menu and oncology requiring the most specialized operator training.
- Infectious Diseases:Bloodstream, respiratory, and gastrointestinal pathogen panels constitute the highest-frequency test category. United States Medicare coverage decisions for rapid sepsis identification are pulling automated platform adoption into emergency departments at community hospitals.
- Oncology:Solid tumor and hematologic malignancy profiling demands sample-to-answer automation to compress formalin-fixed paraffin-embedded processing timelines. Mid-volume hospital laboratories represent the fastest-expanding addressable base as integrated delivery networks consolidate oncology service lines.
- Genetic Testing:Carrier screening and prenatal diagnostics concentrate in reference laboratories with high-complexity CLIA certification for constitutional variant interpretation.
- Pharmacogenomics:Drug-gene interaction testing for warfarin, clopidogrel, and psychiatric medication metabolism remains concentrated in academic medical centers with clinical pharmacy integration.
Infectious diseases commands the largest test volume; oncology is expanding most quickly as community hospital laboratories acquire NGS-polymerase chain reaction hybrid platforms.
End User:
Capital deployment models and procurement authority structures diverge sharply across institutional settings, with integrated delivery networks centralizing vendor selection for hospital laboratories while home care channels remain fragmented.
- Hospitals:Inpatient and emergency department laboratories negotiate enterprise-wide instrument contracts through health system supply chain functions. Three-hospital systems in United States metropolitan markets dominate molecular testing volume and cede purchasing autonomy from individual laboratory directors.
- Diagnostic Laboratories:Reference laboratories and independent clinical laboratories face margin compression from reagent rental lock-in and captive supply relationships with closed-system manufacturers.
- Research Institutions:Academic medical centers and translational research programs require open-platform architectures for laboratory-developed test flexibility, though FDA enforcement is constraining this segment's expansion.
- Home Care:Self-administered infectious disease screening using capillary blood collection and microfluidic cartridges represents underpenetrated demand in United States retail pharmacy channels.
Hospitals handle the majority of throughput; home care is gaining share fastest as microfluidic miniaturization simplifies finger-stick specimen collection.
Technology:
Architecture choices determine middleware compatibility requirements and preventive maintenance intervals, with cloud-based connectivity emerging as a procurement differentiator for integrated delivery networks managing multi-site instrument fleets.
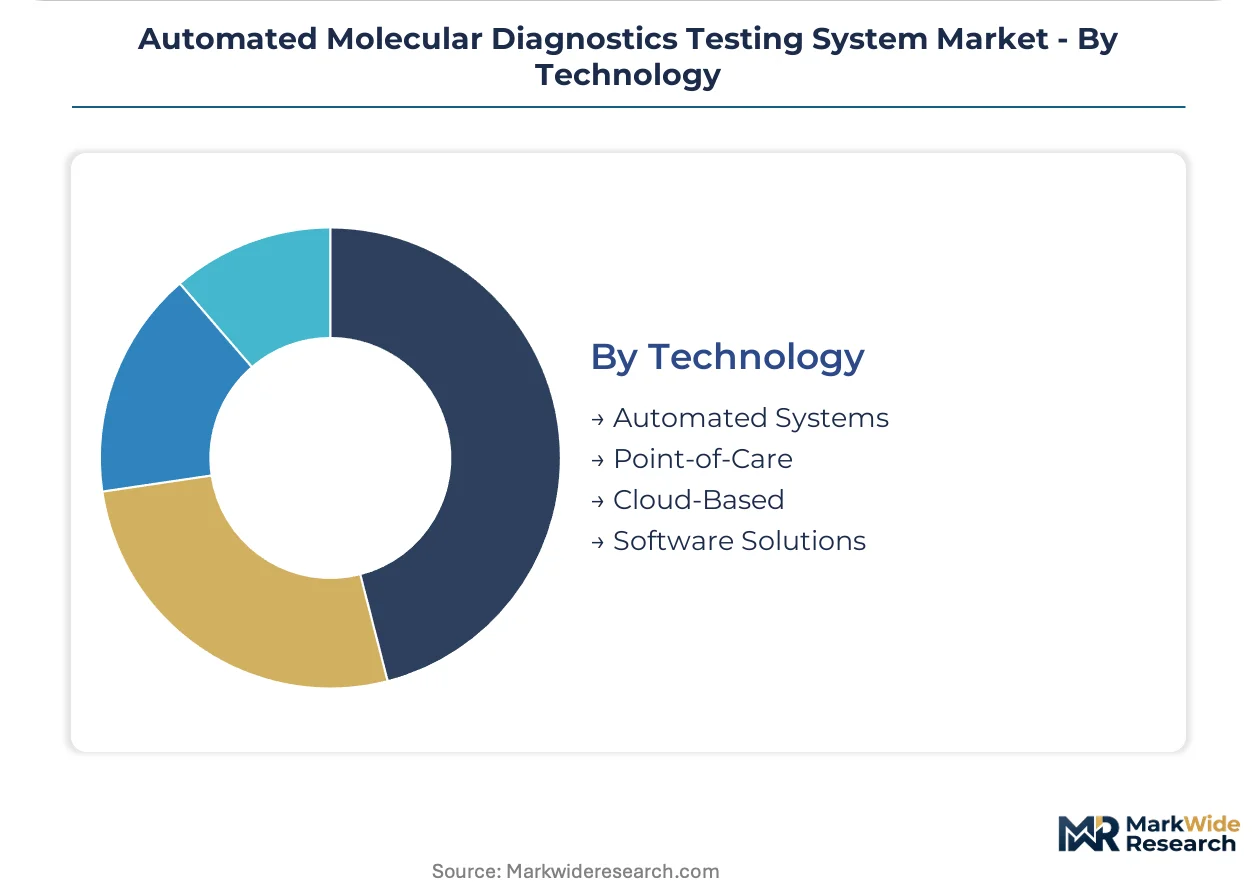
- Automated Systems:Sample-to-answer platforms integrating nucleic acid extraction, amplification, and detection modules within single instruments. These systems reduce hands-on time below five percent and standardize operator workflows across hospital laboratory shifts.
- Point-of-Care:Cartridge-based platforms bypass centralized laboratory infrastructure for emergency department and urgent care deployment. Abbott Laboratories anchors competitive positioning here through CLIA-waived molecular systems.
- Cloud-Based:Remote instrument monitoring, assay version control, and data analytics platforms enable health systems to manage dispersed instrument fleets from centralized informatics functions.
- Software Solutions:Laboratory information system middleware and result interpretation algorithms address legacy IT integration gaps that extend deployment timelines and inflate implementation costs.
Automated systems handle the majority of throughput; cloud-based connectivity is ascending fastest as integrated delivery networks prioritize fleet management capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate procurement authority for automated molecular platforms, while European hospital systems navigate MDR certification bottlenecks and Asian markets expand CLIA-equivalent laboratory accreditation.
United States
Three-hospital systems in metropolitan markets dominate inpatient molecular testing volume and negotiate enterprise-wide instrument contracts spanning multiple sites. FDA enforcement of quality system regulations under 21 CFR Part 820 shapes closed-system platform designs. The Greater Boston cluster anchors academic medical center adoption of NGS-polymerase chain reaction hybrid workflows for oncology profiling.
Germany
University hospital networks drive demand for sample-to-answer automation in infectious disease and pharmacogenomics applications. The European Medical Device Regulation extends conformity assessment requirements, compressing product launch cadences through notified body bottlenecks. The Rhine-Ruhr metropolitan region concentrates reference laboratory capacity for high-complexity constitutional genetic testing.
China
Class III medical device registration under NMPA requirements accelerates domestic manufacturer investment in closed-system molecular platforms. Hospital laboratory consolidation into regional medical centers expands addressable base for automated systems. The Yangtze River Delta cluster hosts the highest density of IVD instrument manufacturing and clinical trial sites for infectious disease panels.
Japan
PMDA premarket approval pathways favor integrated assay-instrument submissions over open-platform reagent systems. Cancer genomic medicine reimbursement expansion pulls NGS automation into mid-volume hospital laboratories. The Kansai region around Osaka anchors pharmaceutical industry demand for companion diagnostic testing infrastructure.
India
CDSCO medical device rules and state-level laboratory licensing create heterogeneous regulatory terrain for automated platform deployment. Corporate hospital chains in metropolitan markets centralize molecular testing procurement. The Maharashtra-Gujarat corridor concentrates diagnostic laboratory networks expanding CLIA-equivalent high-complexity certification for infectious disease and oncology panels.
Automated Molecular Diagnostics Testing System Market Competitive Environment
Player mix skews toward integrated device manufacturers with captive reagent supply chains, creating tiered competitive dynamics between closed-system platform vendors and independent assay developers. The vendor base fragments across PCR-dominant installed base holders, point-of-care specialists, and NGS workflow integrators. Strategic archetypes include platform-locked reament rental providers, sample-to-answer automation specialists, and hybrid amplification-sequencing convergence players. Dominant competitive moves encompass multi-site instrument contract aggregation and assay menu consolidation to amortize regulatory certification costs.
Within the integrated device manufacturer tier, Roche Diagnostics and Abbott Laboratories exemplify divergent automation philosophies, with the former anchoring centralized laboratory workflows and the latter representing point-of-care bypass strategies. Thermo Fisher Scientific occupies a position bridging clinical NGS portfolio extension into automated sample-to-answer architectures. These three entities collectively illustrate how FDA quality system regulation enforcement privileges closed-system designs over open-platform alternatives.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Becton Dickinson and Company |
| Siemens Healthineers |
| QIAGEN |
| Cepheid |
| Thermo Fisher Scientific |
| Danaher Corporation |
| bioMérieux |
| Others |
Value Chain & Pricing Dynamics
Reagent rental contracts with polymerase cost indexation lock United States hospital laboratories into multi-year supply commitments that flatten price volatility while embedding lifetime cost premiums. FDA quality system regulation enforcement compresses open-platform alternatives, entrenching closed-system manufacturers with captive reagent pricing power.
Pricing Analysis
Cost-plus reagent rental agreements indexed to specialty chemical feedstock costs dominate United States procurement, with FDA 21 CFR Part 820 certification tier separating premium closed-system platforms from standard open-architecture alternatives. Price differentiation rests on CLIA high-complexity certification status and integrated assay menu breadth. Cost compression in mid-volume hospital segments is intensifying because integrated delivery networks negotiate enterprise-wide volume discounts. Community hospital emergency departments exhibit highest price sensitivity; academic medical centers with research budgets show lowest.
Supply Chain Analysis
Inbound logistics costs from Port of Shanghai congestion and trans-Pacific container availability constrain thermostable DNA polymerase delivery timelines for United States instrument operators. Manufacturing concentrates in the United States, Germany, and China, with fermentation capacity for specialty enzymes anchored in South Korea and Japan. Raw material dependencies include purified nucleotides, engineered polymerases, and precision-molded microfluidic substrates. Single-source vulnerability in thermostable enzyme supply exposes operators to input cost spikes. Distribution runs through health system supply chain centralization and GPO contract aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of clinical laboratory scientists trained in molecular troubleshooting constrains automated platform deployment velocity across mid-volume hospital settings. This capability gap privileges vendors with embedded field service infrastructure and remote diagnostic connectivity.
For Market Incumbents: Fortify reagent rental lock-in through expanded CLIA-waived assay menus that preempt point-of-care bypass threats from Abbott-style cartridge platforms. Deepen backward integration into thermostable polymerase production to neutralize fermentation capacity bottlenecks from South Korean suppliers. Prioritize cloud-based fleet management capabilities to capture integrated delivery network procurement centralization. For New Entrants and Emerging Players: Differentiate on home care infectious disease screening workflows using finger-stick capillary collection and retail pharmacy distribution partnerships. Target United States retail pharmacy channels for self-administered respiratory panels, the most penetrable white space. Pursue CLIA-waived certification pathways to bypass centralized laboratory infrastructure entirely. For Investors and Strategic Acquirers: Point-of-care molecular specialists with FDA-cleared cartridge platforms and pharmacy channel relationships represent the priority acquisition archetype. Long-term viability hinges on regulatory moat durability against FDA laboratory-developed test enforcement shifts. Watch Medicare sepsis panel reimbursement decisions as volume inflection signal for emergency department platform placement.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Expansion | Enlarges addressable base for hospital laboratories beyond reference lab dependence. |
| Reagent Rental Contract Aggregation | Captures lifetime revenue streams through captive supply relationships with health systems. |
| Microfluidic Cartridge Miniaturization | Enables capillary blood collection for home care infectious disease screening channels. |
| Cloud-Based Fleet Management Platform | Supports multi-site instrument contracts negotiated by integrated delivery network supply chains. |
| NGS-PCR Hybrid Workflow Development | Opens oncology profiling to mid-volume hospital laboratories with compressed turnaround requirements. |
Study Parameters
The analysis maps PCR, RT-PCR, NGS, and microarray platform sub-sectors, each validated through hospital laboratory directors, biomedical engineers, GPO contracts managers, and FDA regulatory affairs specialists. Primary interviews with instrument manufacturers and diagnostic laboratory executives combined with secondary validation from FDA 510(k) filings, CMS Medicare coverage determinations, hospital procurement databases, and CLIA certification records. Bottom-up instrument shipment modeling and top-down health system capital expenditure triangulation anchored volume estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon. The analytical framework modeled product type, application scope, end-user category, and technology architecture dimensions throughout the forecast period. CAGRs derived from installed base expansion rates and reagent consumption per instrument. Forecast inputs included Medicare reimbursement trajectory for sepsis panels and European Medical Device Regulation certification bottlenecks.
Material uncertainties — FDA laboratory-developed test enforcement shifts, polymerase fermentation capacity constraints, integrated delivery network procurement consolidation pace — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and health system capital deployment priorities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Gel Column Agglutination Test System Market
Biotechnology Equipment
Global Biological Microscope Objectives Market
Biotechnology Equipment
Botanical Extraction Equipment Market
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
Global Viral RNA Extraction Kit Market
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Global Biological Safety Cabinets Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Global Laboratory Centrifuge Market
Biotechnology Equipment
Global Biotechnology Reagents Market