
 Global Primary Cell Culture Market | 2026-2036
Global Primary Cell Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Primary Cell Culture Market Foresight
A shortage of GMP-trained cell culture specialists is redrawing competitive boundaries across the industry. Thermo Fisher Scientific sustains its position through backward integration into media formulation and single-use bioreactor systems. Danaher leverages its Life Sciences portfolio to control instrumentation workflows from isolation to scale-up. PromoCell GmbH specializes in human primary cell sourcing, anchoring European academic and pharmaceutical demand with ethically documented donor protocols.
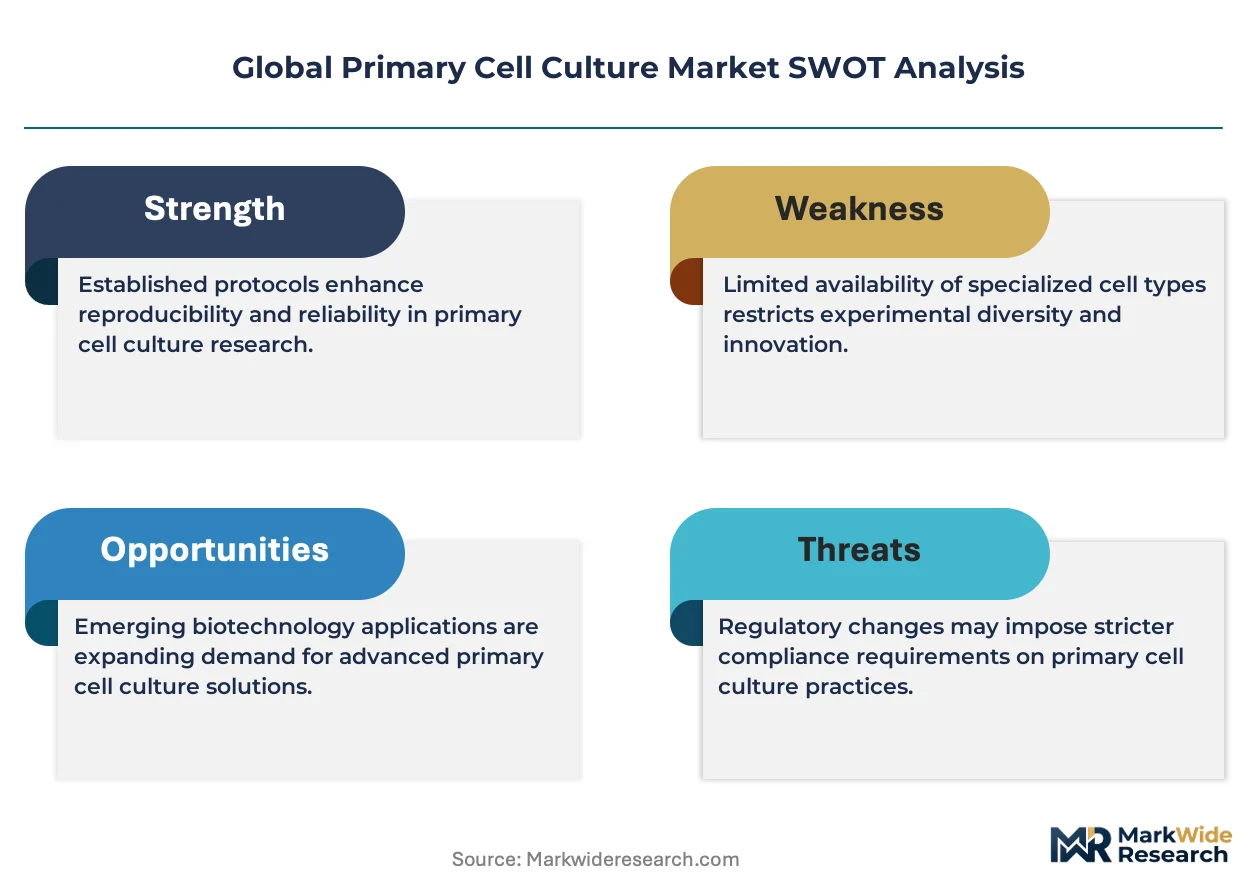
Primary cell culture denotes the cultivation of cells isolated directly from tissue explants or organ samples, maintained in vitro under controlled temperature, pH, and nutrient conditions using basal media supplemented with growth factors and sera. These cultures retain physiological relevance for drug metabolism studies, toxicity profiling, and personalized medicine applications because they preserve donor-specific genetic and epigenetic characteristics lost in immortalized lines. Stem cell and organ-on-chip segments are capturing disproportionate R&D investment as pharmaceutical sponsors prioritize physiologically predictive models over traditional two-dimensional assays. Adherent cell formats still dominate manufacturing-scale revenue, though suspension-adapted primary cultures are gaining share in vaccine and viral vector production where scalability determines program economics.
The FDA enforces current Good Manufacturing Practice standards for cell-based therapies through its Office of Therapeutic Products, while the EMA's Committee for Advanced Therapies evaluates quality and consistency requirements for ATMPs marketed in Europe. ISO 20399 guidelines on ancillary materials further constrain supplier qualification pathways, particularly for serum-free and chemically defined media formulations. Stakeholders must monitor how evolving pharmacopeial standards for cell identity and potency testing reshape validation burdens across contract manufacturing networks.
Market Dynamics
The transition from serum-dependent to chemically defined media formulations is compressing supplier margins while elevating technical barriers for contract manufacturing organizations.
Growth Catalysts
- ATMP commercialization:The EMA's Committee for Advanced Therapies has streamlined marketing authorization pathways for gene-modified cell therapies, accelerating GMP-grade primary cell demand across European manufacturing networks.
- Organ-on-chip validation:FDA qualification programs for microphysiological systems are displacing animal models in preclinical toxicity studies, creating pull-through for primary hepatocyte and cardiomyocyte sourcing.
- China's biologics capacity expansion:NMPA reforms for cell therapy IND approvals have concentrated investment in Shanghai and Suzhou CDMO clusters, driving serum-free media localization requirements.
Market Restraints
- Fetal bovine serum price volatility:Supply interruptions from South American collection networks have destabilized cost structures for legacy adherent culture protocols still dependent on undefined supplements.
- Donor tissue traceability mandates:ISO 20399 documentation requirements for ancillary materials have extended supplier qualification timelines, constraining rapid scale-up for autologous therapy programs.
- Immortalized line substitution:Continuous cell lines from Chinese hamster ovary and human embryonic kidney platforms retain cost advantages for bulk protein production, limiting primary culture penetration in commoditized antibody segments.
Strategic Opportunities
- India's CRO/CDMO emergence:CDSCO streamlined clinical trial regulations and PLI scheme incentives for biopharmaceutical manufacturing are attracting primary cell banking investments in Hyderabad and Bengaluru.
- AI-driven media optimization:Machine learning platforms for predictive nutrient formulation are converging with high-throughput bioreactor screening, enabling rapid chemically defined media development.
- Direct-to-biotech distribution:E-commerce procurement channels for small-volume research-grade cells are bypassing traditional distributor markups for early-stage discovery programs.
Industry Challenges
- GMP cell banking expertise:Master and working cell bank qualification under FDA current Good Tissue Practice rules requires specialized personnel scarce across contract manufacturing networks.
- Single-use system validation:Extractables and leachables testing for polymer contact materials adds 12-18 month certification timelines to primary culture scale-up projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Primary Cell Culture Market |
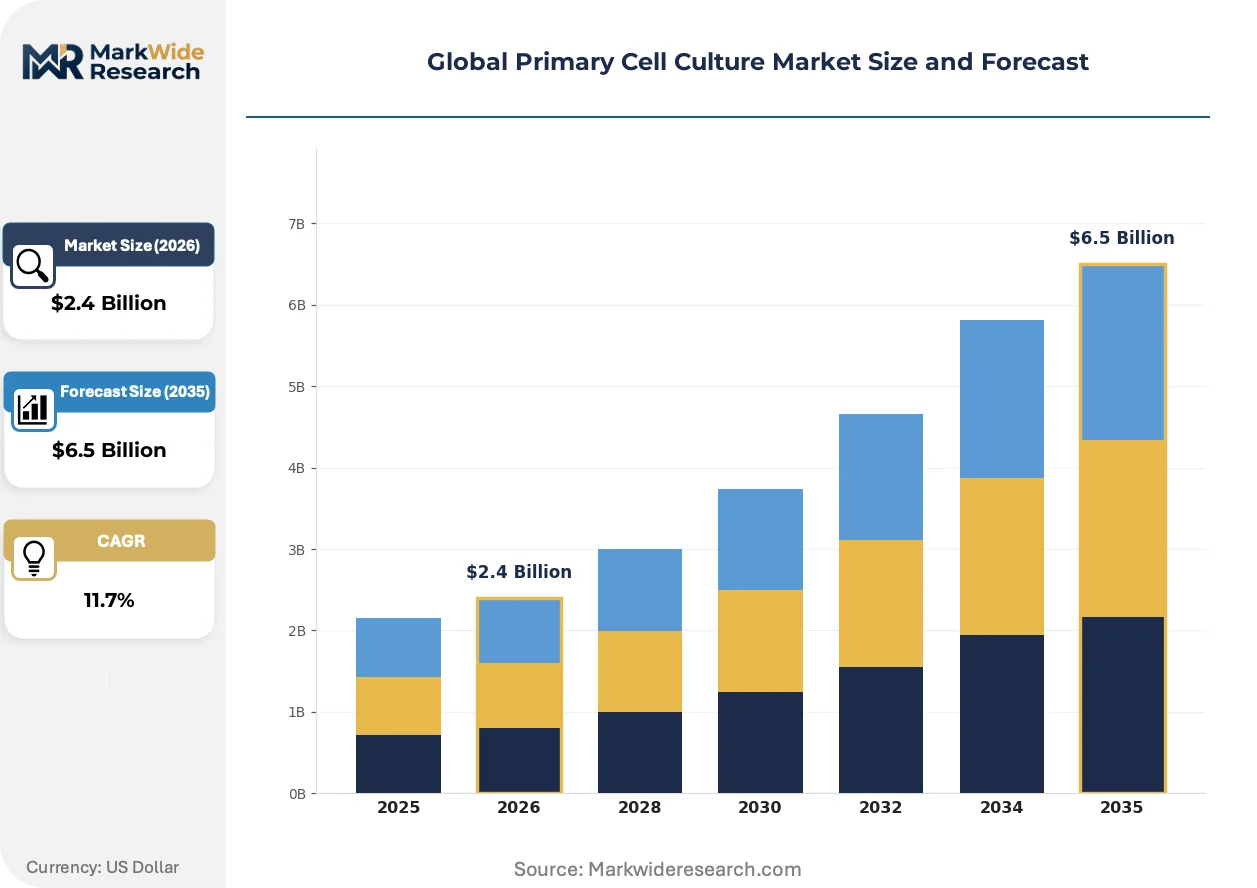
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adherent Cells, Suspension Cells, Stem Cells, Co-Culture Systems, Serum-Free Culture, Customized Media Application: Drug Discovery, Toxicology Testing, Vaccine Production, Regenerative Medicine, Genetic Research, Biopharmaceuticals End User: Pharmaceutical Manufacturers, Academic Research Institutions, Contract Research Organizations, Biotechnology Companies, Clinical Laboratories Technology: 2D Culture, 3D Culture, Microcarrier-Based Culture, Organ-on-Chip, Bioreactor Systems, High-Throughput Screening |
| Companies Covered | STEMCELL Technologies Inc., Danaher, Thermo Fisher Scientific Inc., American Type Culture Collection, Corning Incorporated, Merck KGaA, PromoCell GmbH, Axol Bioscience Ltd., Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Primary Cell Culture Market Shifts & Advancements
Automation and closed-system architecture are reconfiguring facility design standards, while regulatory science initiatives redefine acceptable evidence for cell-based product characterization.
Perfusion bioreactor technology is decomposing the batch-size limitations that have constrained primary cell manufacturing economics. Vaccine producers in Germany and the United States are adopting continuous harvest systems for viral vector production at 200-liter scales. This technology is decomposing the traditional trade-off between culture fidelity and volumetric productivity that favored immortalized platforms.
REACH restrictions on substance of very high concern classifications are pressuring European suppliers to eliminate undefined biological additives from media formulations. The ECHA evaluation of residual processing aids has accelerated adoption of recombinant protein replacements for pituitary extract supplements. Primary stem cell manufacturers in the Netherlands and Switzerland are reformulating expansion media ahead of 2027 authorization deadlines.
CDMO customers are consolidating procurement around qualified supplier networks with dual-source redundancy for critical raw materials. Large pharmaceutical sponsors in the United States now mandate secondary cell sourcing agreements for phase III programs, displacing single-source academic tissue bank relationships. This pattern is most visible in immuno-oncology trials where patient enrollment timelines tolerate no donor material interruptions.
Global Primary Cell Culture Market Segmentation
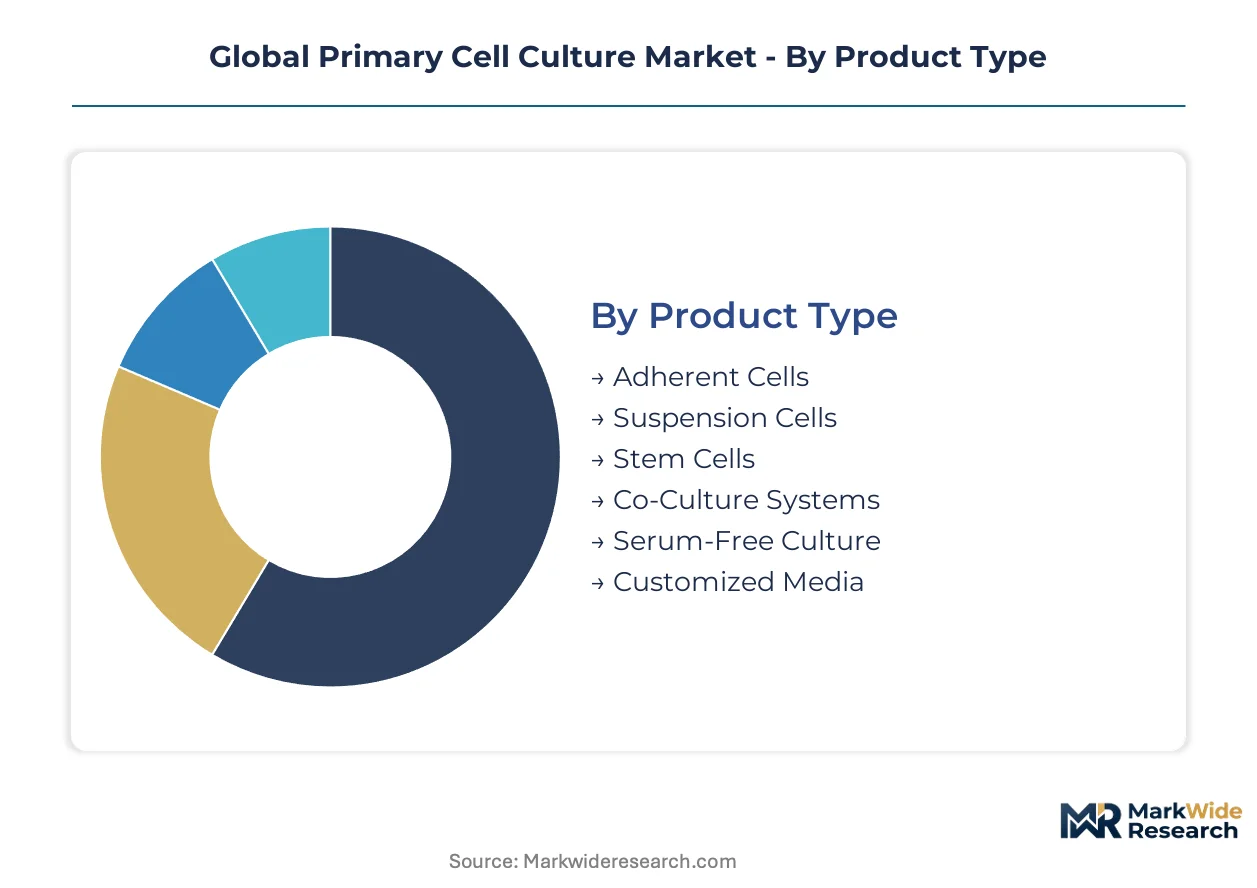
Segmentation in primary cell culture reveals how technical specifications, regulatory requirements, and manufacturing scale reshape procurement patterns across pharmaceutical value chains. Each dimension carries distinct margin profiles and qualification burdens that determine supplier positioning.
Product Type:
Adherent formats dominate domestic consumption in the United States and Germany, while suspension-adapted systems serve export-oriented viral vector manufacturers in China and India.
- Adherent Cells:These cultures require surface attachment via collagen or fibronectin coatings, preserving native morphology for hepatocyte and keratinocyte applications. Demand concentrates in United States toxicology laboratories where FDA submission requirements mandate physiologically predictive metabolism data.
- Stem Cells:Pluripotent and multipotent populations enable patient-specific disease modeling and autologous therapy manufacturing. Procurement in Germany and the Netherlands accelerates under EMA ATMP commercialization timelines, with CDMOs qualifying ethically documented donor protocols.
- Suspension Cells:Adapted primary cultures enable scalable bioreactor expansion for vaccine and gene therapy vectors.
- Co-Culture Systems:Multi-cell type configurations replicate tissue microenvironments for organ-on-chip applications.
- Serum-Free Culture:Chemically defined formulations eliminate lot-to-lot variability for GMP manufacturing.
- Customized Media:Client-specific nutrient blends address rare cell type requirements in academic consortia.
Adherent cells hold the largest share; momentum sits with stem cells.
Application:
Cost tiers separate commodity toxicology screening from premium regenerative medicine manufacturing, with the latter commanding 3-4x media expenditure per liter.
- Regenerative Medicine:Cell therapy manufacturing demands GMP-grade starting materials with full donor traceability under FDA current Good Tissue Practice. Sponsors in Boston and San Francisco corridors require master cell bank documentation for IND-enabling studies.
- Biopharmaceuticals:Monoclonal antibody and recombinant protein production increasingly adopts serum-free primary cultures for critical quality attribute control. Chinese NMPA reforms have concentrated investment in Shanghai CDMO clusters seeking chemically defined media localization.
- Drug Discovery:High-throughput compound screening drives consumption of standardized hepatocyte lots.
- Toxicology Testing:Regulatory submission requirements sustain demand for primary hepatocyte panels.
- Vaccine Production:Viral vector manufacturing favors suspension-adapted primary cultures at 200-liter scales.
- Genetic Research:CRISPR validation studies utilize patient-derived primary cells for off-target analysis.
Biopharmaceuticals command the highest absolute spend; regenerative medicine shows the steepest expansion trajectory.
End User:
Volume concentration distinguishes high-throughput CRO screening programs from low-volume clinical laboratory cell banking operations.
- Pharmaceutical Manufacturers:In-house cell culture capabilities at Merck KGaA and Roche facilities in Germany prioritize backward integration into media formulation to secure supply continuity.
- Contract Research Organizations:Hyderabad and Bengaluru CROs leverage India's CDSCO streamlined trial regulations to offer cost-competitive primary cell screening services.
- Academic Research Institutions:European universities anchor demand for ethically documented human primary cells with full donor consent chains.
- Biotechnology Companies:Venture-backed startups in Cambridge and South San Francisco procure small-volume research-grade cells through direct-to-biotech distribution channels.
- Clinical Laboratories:Hospital-based cell therapy processing requires point-of-care isolation protocols for autologous applications.
Pharmaceutical manufacturers hold the largest share; biotechnology companies are climbing the fastest.
Technology:
Supply concentration in perfusion bioreactor systems has created captive vendor relationships among German viral vector producers.
- 3D Culture:Spheroid and organoid formats replicate tumor microenvironments for immuno-oncology drug development. United States sponsors displace animal models under FDA microphysiological system qualification programs.
- Organ-on-Chip:Microfluidic platforms integrate primary hepatocytes, cardiomyocytes, and endothelial cells for multi-organ toxicity prediction. Dutch and Swiss manufacturers reformulate expansion media ahead of ECHA REACH authorization deadlines.
- 2D Culture:Traditional monolayer formats persist in high-throughput screening for cost-sensitive applications.
- Microcarrier-Based Culture:Bead-supported expansion enables adherent cell scale-up in stirred-tank bioreactors.
- Bioreactor Systems:Perfusion technology decomposes batch-size limitations for continuous viral vector harvest.
- High-Throughput Screening:Automated liquid handling integrates with 384-well primary cell plates for compound profiling.
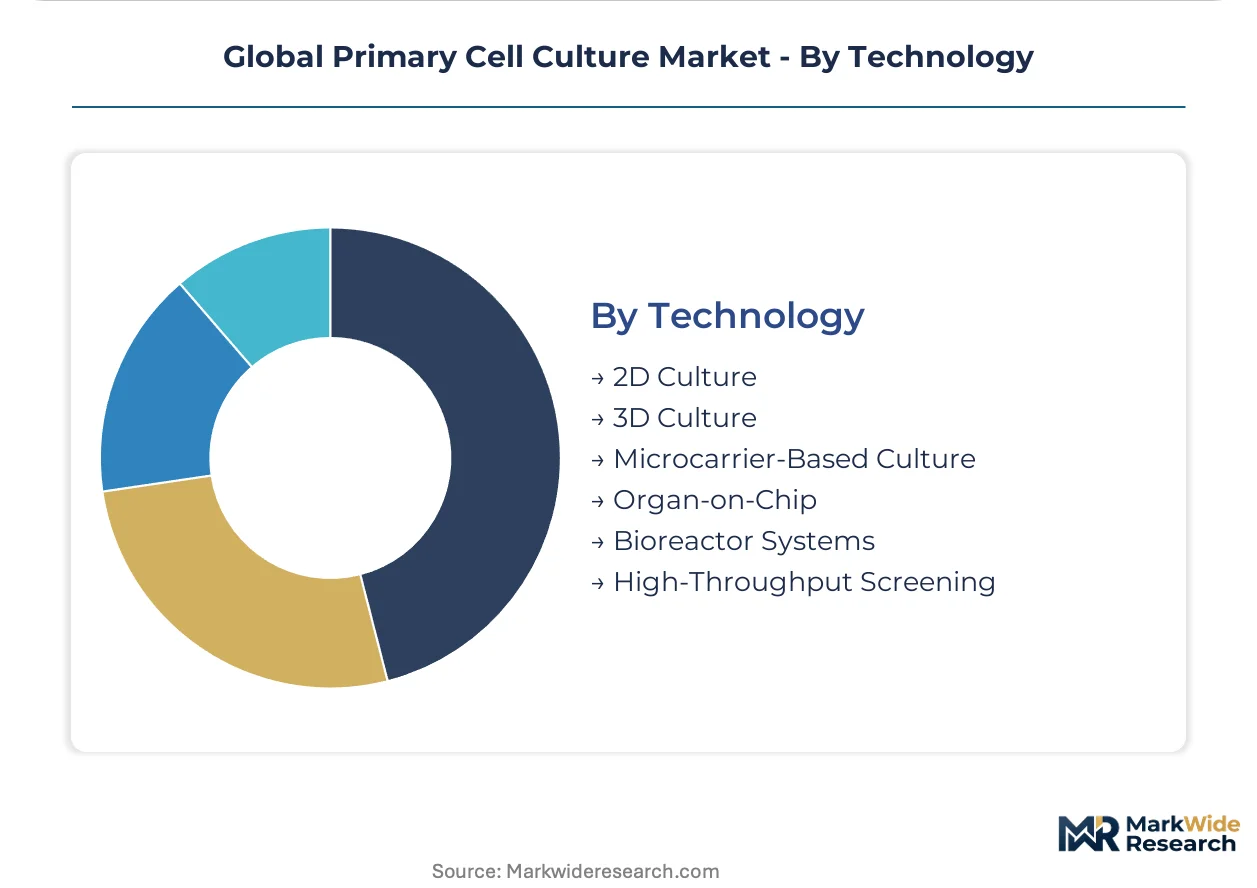
2D culture holds the largest share; organ-on-chip platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of current Good Tissue Practice standards anchors United States demand for GMP-grade primary cells, while EMA and NMPA reforms in Europe and China reshape procurement patterns across their respective manufacturing networks. Country-specific regulatory frameworks and industrial clustering determine where serum-free media localization and cell banking investments concentrate.
United States
Boston and San Francisco biotech corridors drive demand for master cell bank documentation in IND-enabling studies. FDA Office of Therapeutic Products oversight of cell-based therapies compels sponsors to secure full donor traceability. Contract manufacturing clusters in Research Triangle Park and San Diego prioritize backward integration into media formulation.
Germany
Merck KGaA and Roche facilities anchor European biopharmaceutical manufacturing capacity. EMA Committee for Advanced Therapies marketing authorization pathways accelerate GMP-grade primary cell demand across Bavarian and North Rhine-Westphalia production networks. Viral vector producers in Heidelberg and Cologne adopt perfusion bioreactor systems at 200-liter scales.
China
NMPA reforms for cell therapy IND approvals concentrate investment in Shanghai and Suzhou CDMO clusters. Serum-free media localization requirements emerge as domestic biologics capacity expands. Contract development organizations in Zhangjiang Hi-Tech Park reformulate chemically defined nutrient blends for export-oriented viral vector manufacturing.
India
CDSCO streamlined clinical trial regulations attract primary cell banking investments to Hyderabad and Bengaluru. PLI scheme incentives for biopharmaceutical manufacturing lower cost structures for CRO screening services. Academic medical centers in Chennai and Pune establish ethically documented donor protocols for regional pharmaceutical demand.
Switzerland
Swissmedic oversight of ATMP quality requirements shapes primary stem cell manufacturer behavior in Basel and Zurich. REACH authorization deadlines for 2027 accelerate reformulation of expansion media ahead of ECHA evaluations. Dutch and Swiss manufacturers eliminate undefined biological additives from pituitary extract supplements.
Global Primary Cell Culture Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the primary cell culture supply base. The market structure consolidates around diversified life sciences conglomerates with captive media formulation capabilities, while specialized cell sourcing boutiques occupy premium niches requiring ethical documentation. Three archetypes dominate: full-stack platform providers controlling instrumentation-to-media workflows, human primary cell specialists with documented donor chains, and regional CROs leveraging cost-advantaged screening capacity. M&A activity targets single-use bioreactor technology, while strategic partnerships secure dual-source redundancy for critical raw materials.
Among diversified conglomerates, Danaher and Thermo Fisher Scientific occupy positions spanning instrumentation workflows from isolation to scale-up. PromoCell GmbH exemplifies the European specialist archetype, anchoring academic and pharmaceutical demand through ethically documented human primary cell sourcing. These three represent distinct competitive vectors: platform breadth, geographic origin specialization, and donor protocol rigor.
| Leading Market Players |
|---|
| STEMCELL Technologies Inc. |
| Danaher |
| Thermo Fisher Scientific Inc. |
| American Type Culture Collection |
| Corning Incorporated |
| Merck KGaA |
| PromoCell GmbH |
| Axol Bioscience Ltd. |
| Lonza |
| Others |
Supply & Pricing Matrix
ISO 20399 documentation requirements for ancillary materials simultaneously gate supplier qualification timelines and stratify pricing tiers, forcing sponsors to pay premiums for pre-validated serum-free media while compressing margins on legacy fetal bovine serum-dependent protocols.
Pricing Analysis
Price spreads between United States and Chinese CDMO sourcing run 40-60 percent for equivalent GMP-grade hepatocyte lots. Three-tier pricing structure across premium, standard, and economy levels separates master cell bank-qualified donors from research-grade tissue with truncated consent chains. Cost compression in commodity adherent formats is intensifying because Chinese manufacturers localize chemically defined media formulations. Biotechnology startups in Boston and San Francisco corridors show highest price sensitivity, while phase III pharmaceutical sponsors absorb premium tier pricing to secure dual-source redundancy.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have extended lead times for temperature-controlled fetal bovine serum shipments from South American collection networks. Supply concentrates in the United States for master cell banking expertise, Germany for perfusion bioreactor systems, and China for viral vector manufacturing capacity. Raw material dependencies center on recombinant growth factors, synthetic surface coatings, and polymer contact materials for single-use vessels. Single-source vulnerability in ethically documented human donor tissue constrains rapid autologous therapy scale-up. Distribution runs through qualified supplier networks with direct-to-biotech channels penetrating early-stage discovery procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from the 2020-2023 capacity overbuild cycle as ATMP commercialization timelines compress and GMP-grade cell demand reaccelerates through 2025-2026 IND filing windows.
For Market Incumbents: Fortify backward integration into media formulation and single-use bioreactor systems to defend against emerging platform providers offering integrated instrumentation-to-media workflows. Incumbent CDMOs must secure dual-source redundancy for critical donor tissue ahead of FDA current Good Tissue Practice enforcement intensification. Capacity addition in German and Swiss manufacturing corridors anchors European ATMP production networks against Chinese cost competition. For New Entrants and Emerging Players: Lead with AI-driven media optimization services to penetrate the cost-sensitive Indian CRO screening segment where traditional formulation expertise concentrates among established suppliers. White-space targets include direct-to-biotech distribution channels for small-volume research-grade cells and perfusion bioreactor technology licensing to viral vector producers. Geographic expansion into Hyderabad and Bengaluru leverages CDSCO streamlined trial regulations and PLI scheme incentives. For Investors and Strategic Acquirers: EMA ATMP marketing authorization pathway streamlining reshapes the acquisition landscape toward human primary cell specialists with ethically documented donor protocols and pre-qualified master cell banks. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than scale economics alone. Acquisition target archetype: mid-cap European cell sourcing boutiques with ISO 20399-compliant ancillary material supply chains. Signal to watch: FDA qualification program momentum for microphysiological systems displacing animal toxicity models.| Strategic Initiative | Industry Significance |
|---|---|
| Serum-Free Media Localization | Chinese NMPA reforms accelerate chemically defined formulation investments in Shanghai CDMO clusters. |
| Perfusion Bioreactor Adoption | German viral vector producers at 200-liter scales decompose batch-size limitations for continuous harvest economics. |
| AI-Driven Nutrient Optimization | Machine learning platforms converge with high-throughput screening to compress media development cycles. |
| Dual-Source Cell Banking | United States pharmaceutical sponsors mandate secondary sourcing agreements for phase III immuno-oncology trials. |
| Organ-on-Chip Validation | FDA microphysiological system qualification programs displace animal models for hepatocyte toxicity profiling. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Office of Therapeutic Products guidance documents, EMA Committee for Advanced Therapies marketing authorization databases, and ISO 20399 ancillary material standards. Interviews with cell therapy manufacturing executives, GMP quality assurance leads, CDMO procurement managers, and academic principal investigators informed supply chain and pricing dynamics. Secondary validation drew from ClinicalTrials.gov cell therapy protocol registrations, SEC 10-K filings of diversified life sciences conglomerates, and ECHA REACH substance evaluation timelines. Bottom-up triangulation across product type, application, and end-user segments converged with top-down macroeconomic and regulatory scenario testing.
Segmentation dimensions modeled include adherent versus suspension culture formats, regenerative medicine versus biopharmaceutical application tiers, and pharmaceutical manufacturer versus CRO end-user categories. Forecast outputs reflect volume and value trajectories across the projection horizon, with CAGRs derived from historical procurement pattern analysis and forward-looking capacity buildout disclosures. Industry-specific inputs encompass master cell bank qualification timelines, perfusion bioreactor adoption curves, and serum-free media formulation switching costs.
Underlying assumptions cover sustained ATMP commercialization momentum, stable fetal bovine serum supply from South American networks, and gradual REACH authorization compliance ahead of 2027 deadlines, with deviation risk concentrated in regulatory enforcement intensity and donor tissue traceability mandate expansion. Practitioners should keep alternative scenarios live as FDA cell and gene therapy oversight frameworks and EMA ATMP evaluation criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Europe Transfection Technologies Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market