
 Fermentation Equipment Market | 2026-2036
Fermentation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fermentation Equipment Market Analysis
Buyer concentration among biopharmaceutical contract manufacturers is rebalancing toward mid-tier CDMOs building multi-product facilities alongside established large-molecule giants. Sartorius AG leverages its single-use platform dominance to capture flexible manufacturing demand across Asia-Pacific and European installations. GEA Group anchors large-scale stainless-steel bioreactor supply for industrial enzyme and biofuel producers requiring tonnage-scale fermentation capacity. Thermo Fisher Scientific competes through integrated analytical and bioproduction workflows that reduce process development timelines for gene therapy applications.
Fermentation equipment encompasses vessels, sensors, control systems, and downstream processing skids engineered to maintain sterile, aerobic, or anaerobic conditions for microbial or cell-culture propagation, typically operating at pressures up to 3 bar and temperatures controlled within 0.5 degrees Celsius to optimize metabolic yield. Its primary industrial purpose spans pharmaceutical protein production, industrial enzyme manufacture, biofuel generation, and cultured-food processing. Stirred-tank systems occupy the largest installed base due to proven scalability from laboratory to production scale, while fed-batch fermentation technology sustains the dominant revenue share in biologics manufacturing where substrate limitation controls byproduct formation. Continuous fermentation differentiates emerging facilities targeting commodity biochemicals where steady-state operation reduces capital intensity per unit output.
FDA process validation guidance and EMA good manufacturing practice Annex 1 revisions on sterile manufacturing are forcing vessel sterilization-in-place and cleanability redesigns across supplier portfolios. REACH substance restrictions and EU Green Deal industrial emissions frameworks shape material selection for gaskets, coatings, and heat-transfer surfaces in European-sourced equipment. Stakeholders must monitor evolving pharmacopoeial standards for extractables and leachables from single-use polymer films, as regulatory divergence between FDA and EMA testing protocols could fragment qualification requirements and complicate global facility standardization strategies.
Market Dynamics
Single-use bioreactor adoption is compressing facility validation timelines and reconfiguring capital deployment patterns across biopharmaceutical manufacturing networks, forcing stainless-steel incumbents to defend installed base through hybrid platform offerings.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:Mandates for closed-system processing are accelerating replacement cycles for open-vessel fermentation trains across European biologics facilities.
- Cell-culture capacity expansion:Contract manufacturers are scaling mammalian production platforms to meet monoclonal antibody demand, driving vessel orders across 50L to 2,000L scales.
- Precision-engineering clusters:Concentrated supplier capability around Basel and Hamburg is reducing lead times for modular skid-mounted systems serving global biopharma buyers.
Market Restraints
- Specialized alloy supply concentration:Premium 316L stainless-steel sourcing for large-scale vessels depends on concentrated European and Asian mill capacity, exposing buyers to input cost volatility.
- Single-use polymer film qualification:Divergent FDA and EMA extractables testing protocols are fragmenting global standardization strategies and inflating validation documentation burdens.
- Skilled bioprocess engineering scarcity:Talent gaps in process analytical technology integration and sterile operations are extending commissioning timelines for advanced fermentation facilities.
Strategic Opportunities
- Continuous fermentation for commodity biochemicals:Steady-state operation models are reducing capital intensity per unit output for biofuel and industrial enzyme producers seeking tonnage-scale capacity.
- EU Green Deal industrial emissions frameworks:REACH substance restrictions on gaskets and coatings are creating first-mover advantage for suppliers with validated sustainable material portfolios.
- Cultured-food processing scale-up:Precision fermentation for alternative proteins represents underpenetrated demand requiring novel vessel geometries and sterility protocols distinct from pharmaceutical applications.
Industry Challenges
- Process analytical technology integration complexity:Embedding real-time monitoring sensors into legacy stainless-steel vessels requires extensive retrofit engineering and revalidation.
- Cleanability verification for multi-product facilities:Demonstrating residue elimination between campaigns demands enhanced sterilization-in-place protocol development and documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermentation Equipment Market |
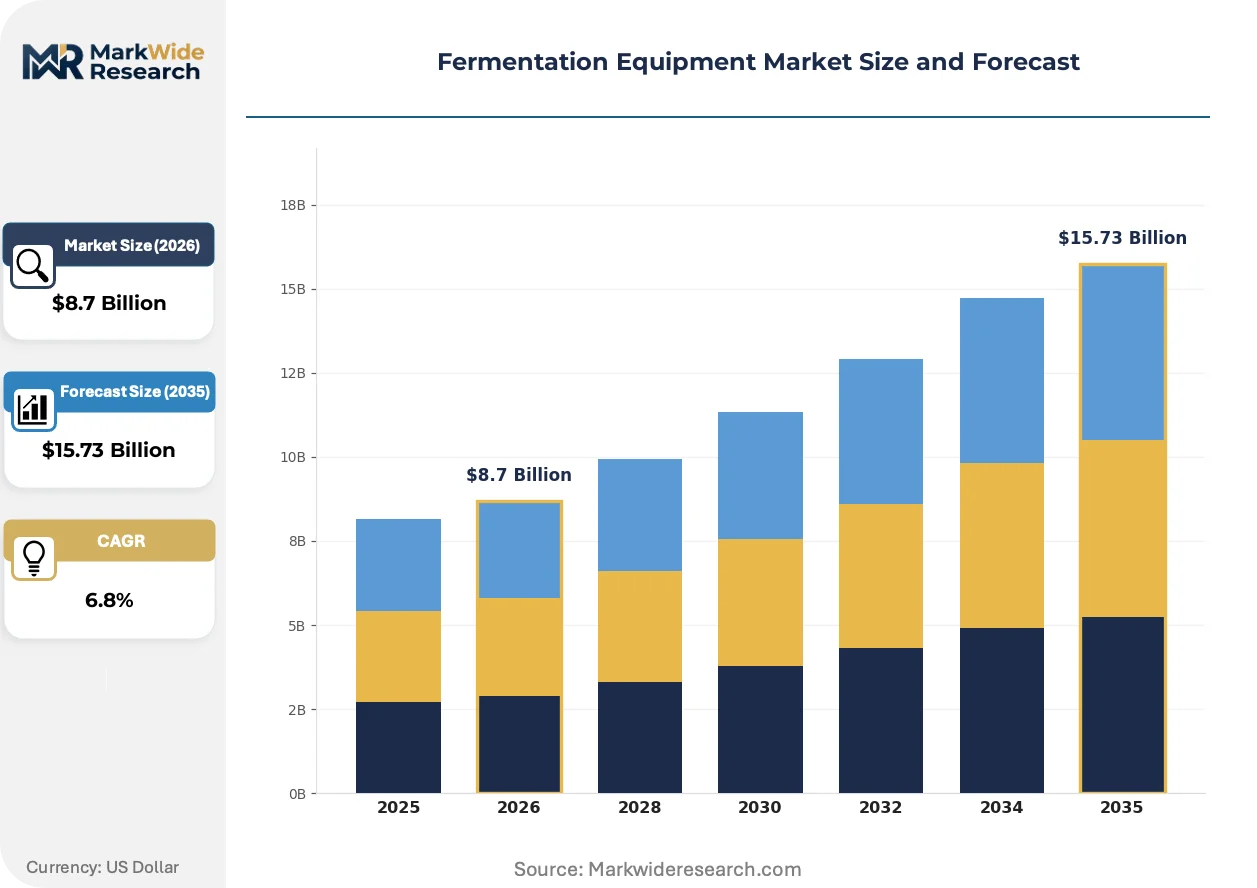
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stirred Tank, Bubble Column, Airlift, Packed Bed End User: Pharmaceuticals, Food & Beverage, Biofuels, Wastewater Treatment Technology: Batch Fermentation, Continuous Fermentation, Fed-Batch Fermentation, Solid-State Fermentation Size: Small Scale, Medium Scale, Large Scale, Pilot Scale |
| Companies Covered | DIOSNA Dierks & Söhne GmbH, Bioengineering AG, SYSBIOTECH GmbH, GEA Group, Thermo Fisher Scientific, Pierre Guerin SA, Sartorius AG, Heinrich Frings GmbH & Co. KG, Eppendorf North America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermentation Equipment Market Emerging Trajectories
Digital twin deployment and advanced process control architectures are compressing development timelines and enabling predictive maintenance models that shift operational expenditure structures across fermentation facilities.
Single-use mixing technologies are rewriting scale-up economics for clinical-stage biologics by eliminating cleaning validation requirements and enabling rapid product changeover. Mid-tier CDMOs building multi-product facilities are adopting these platforms fastest, collapsing traditional 18-month facility qualification timelines to under six months and forcing stainless-steel suppliers to develop hybrid offerings that preserve their large-scale installed base.
REACH substance restrictions and EU Green Deal industrial emissions frameworks are mandating material substitutions for gaskets, seals, and heat-transfer surfaces in European-sourced equipment. Suppliers are reformulating elastomer compounds and ceramic coatings to maintain performance under thermal cycling while satisfying regulatory substance restrictions, with German precision-engineering clusters leading qualification documentation for global export.
Equipment-as-a-service contracting is displacing traditional capital purchase models among emerging biotech developers with constrained balance sheets. CDMOs and specialist lessors are capturing recurring revenue streams through performance-guaranteed uptime arrangements, with Asia-Pacific gene therapy startups representing the most visible adoption geography for this procurement innovation.
Fermentation Equipment Market Segmentation
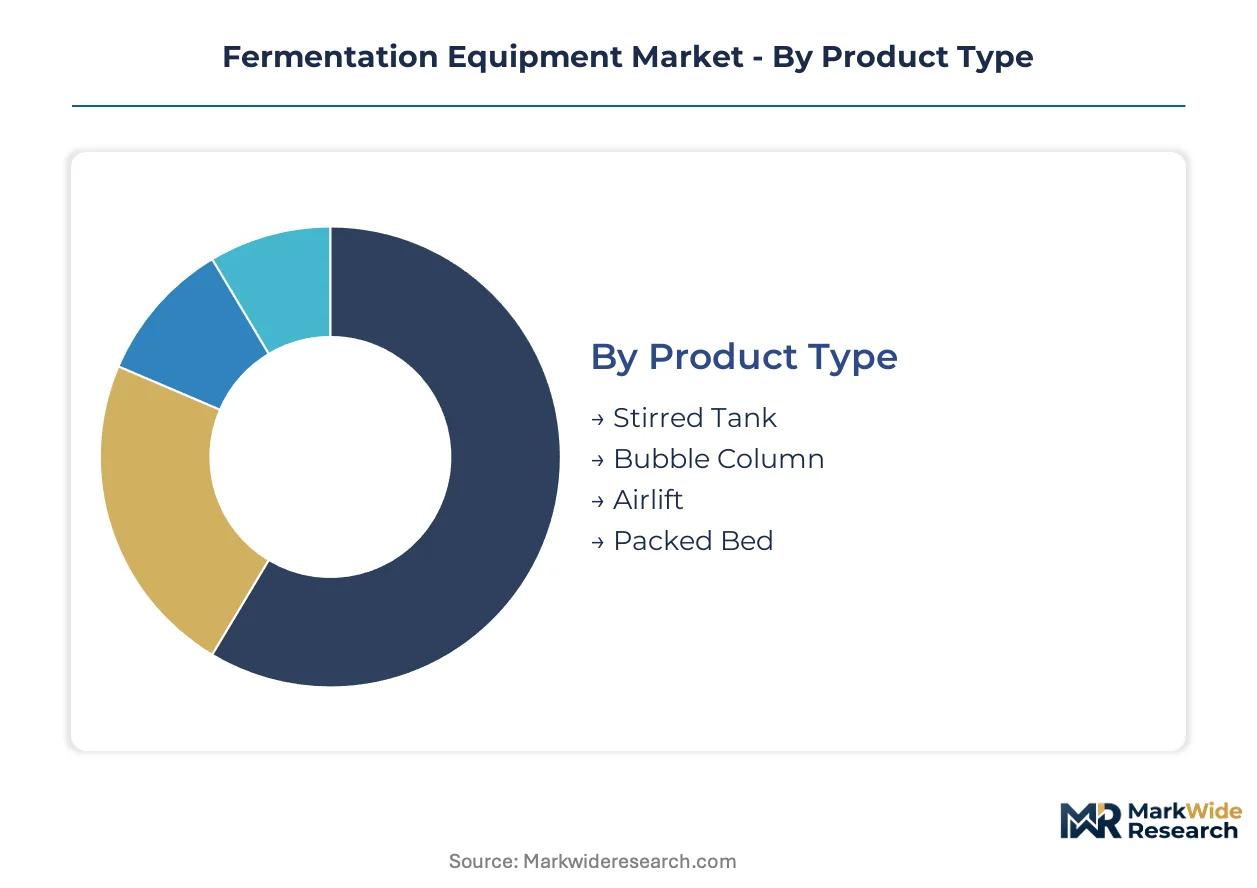
Fermentation equipment segmentation reveals divergent certification burdens across vessel geometries and operating modes. EMA Annex 1 sterile manufacturing requirements and FDA process validation guidance create tiered compliance costs that reshape procurement patterns among biopharmaceutical and industrial buyers.
Product Type:
EMA Annex 1 mandates for closed-system processing impose distinct validation documentation burdens on each vessel geometry, with sterilization-in-place complexity driving qualification cost differentials.
- Stirred Tank:Mechanical agitation systems with impeller configurations engineered for oxygen transfer rates up to 300 mmol/L/hr dominate mammalian cell-culture installations. Demand concentrates in German precision-engineering clusters supplying modular skid-mounted systems to CDMOs scaling monoclonal antibody capacity, with FDA 21 CFR Part 11 electronic records compliance adding software validation layers.
- Bubble Column:Pneumatically agitated vessels without moving parts reduce mechanical seal validation requirements for shear-sensitive microbial cultures. Shear-sensitive industrial enzyme producers in Basel-region facilities favor these systems for filamentous fungal fermentation, though EMA extractables testing protocols for polymer internals complicate single-use adaptations.
- Airlift:Circulation-driven mass transfer systems achieve lower capital intensity for bulk biochemical production.
- Packed Bed:Immobilized-cell configurations require specialized cleanability verification for multi-product pharmaceutical campaigns.
Leading the category by volume: Stirred Tank. Growing fastest: Bubble Column.
End User:
Cost tier stratification separates capital-intensive pharmaceutical validation from price-sensitive industrial applications, with compliance documentation burdens scaling nonlinearly across buyer categories.
- Pharmaceuticals:cGMP-compliant vessel trains for biologics manufacturing demand 316L stainless-steel construction with surface finishes below 0.8 micrometers Ra and comprehensive extractables-leachables documentation. Multi-product CDMOs in Hamburg and Basel precision clusters drive orders for hybrid stainless-steel and single-use platforms, with EMA Annex 1 revisions accelerating replacement cycles for legacy open-vessel systems.
- Food & Beverage:Clean-in-place protocols for cultured-food processing require novel vessel geometries distinct from pharmaceutical sterility standards. Precision fermentation startups developing alternative proteins represent underpenetrated demand requiring rapid product changeover capabilities, with REACH substance restrictions on gaskets shaping European equipment sourcing.
- Biofuels:Tonnage-scale continuous fermentation systems prioritize capital efficiency over validation documentation intensity.
- Wastewater Treatment:Anaerobic digestion vessels face minimal pharmaceutical-grade certification requirements.
Pharmaceuticals command premium pricing tiers. Food & Beverage applications are climbing the fastest as cultured-food scale-up accelerates.
Technology:
Operating mode selection directly determines process analytical technology integration complexity and real-time monitoring sensor placement requirements.
- Fed-Batch Fermentation:Substrate-limited operation controls byproduct formation in biologics manufacturing through controlled nutrient feeding strategies. Mammalian cell-culture facilities across German supplier networks rely on this dominant revenue-share technology for monoclonal antibody production, with FDA process analytical technology guidance driving embedded sensor retrofits into legacy vessel infrastructure.
- Continuous Fermentation:Steady-state operation reduces capital intensity per unit output for commodity biochemicals and biofuels. Industrial enzyme producers seeking tonnage-scale capacity favor this emerging model, though skilled bioprocess engineering scarcity extends commissioning timelines for advanced control architectures.
- Batch Fermentation:Complete-cycle operation remains standard for clinical-stage biologics requiring campaign isolation.
- Solid-State Fermentation:Low-moisture cultivation systems for fungal products demand specialized heat-transfer surface designs.
Fed-Batch Fermentation retains installed-base dominance. Continuous Fermentation shows steepest expansion trajectory among commodity biochemical producers.
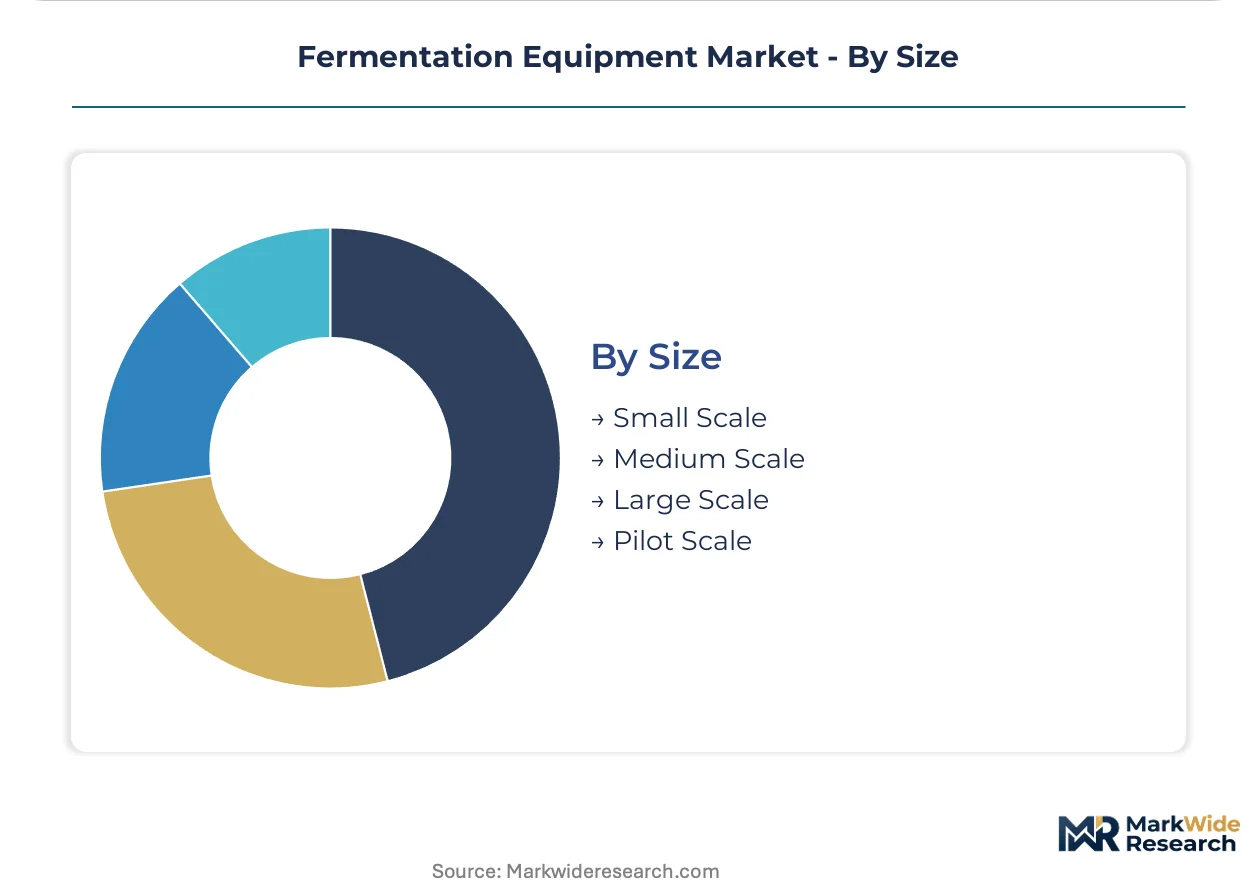
Size:
Volume scale determines equipment-as-a-service contracting viability and capital deployment patterns among emerging biotech developers with constrained balance sheets.
- Large Scale:Production vessels exceeding 10,000 liters for industrial enzyme and biofuel manufacturing depend on concentrated European and Asian 316L stainless-steel mill capacity. Tonnage-scale installations anchor GEA Group supply contracts, with specialized alloy sourcing concentration exposing buyers to input cost volatility and extended lead times.
- Pilot Scale:50L to 2,000L systems bridge process development and commercial manufacturing for gene therapy applications. Asia-Pacific startups increasingly procure through performance-guaranteed uptime arrangements rather than capital purchase, with single-use platforms collapsing traditional facility qualification timelines.
- Small Scale:Laboratory-scale systems serve early-stage strain development and media optimization.
- Medium Scale:Mid-tier CDMO multi-product facilities favor this range for flexible manufacturing networks.
Large Scale systems generate highest absolute revenue. Pilot Scale demand is expanding most quickly through equipment-as-a-service adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical contract manufacturers cluster their vessel procurement decisions around precision-engineering hubs in Germany, the United States, and Switzerland, with emerging capacity buildouts accelerating across China and India.
Germany
EMA Annex 1 sterile manufacturing revisions are accelerating replacement cycles for open-vessel fermentation trains across German biologics facilities. REACH substance restrictions shape material selection for gaskets and coatings in European-sourced equipment. The Basel-Hamburg precision-engineering corridor supplies modular skid-mounted systems to global CDMO buyers, with surface-finish capabilities below 0.8 micrometers Ra commanding premium positioning.
United States
FDA process validation guidance and 21 CFR Part 11 electronic records compliance are adding software validation layers to stirred-tank bioreactor procurement. Gene therapy applications are compressing process development timelines through integrated analytical workflows. The Greater Boston and San Francisco Bay Area biotech clusters are driving pilot-scale vessel orders across 50L to 2,000L scales for clinical-stage biologics manufacturing.
Switzerland
Swissmedic oversight of sterile manufacturing maintains alignment with EMA standards while preserving national certification autonomy. Precision fermentation for alternative proteins is creating novel vessel geometry demand distinct from pharmaceutical sterility protocols. The Basel-region industrial enzyme producers favor bubble column configurations for filamentous fungal fermentation, leveraging existing biochemical process engineering expertise.
China
NMPA biologics manufacturing guidelines are tightening vessel validation requirements for domestic monoclonal antibody production capacity. Dual carbon goals under MEE frameworks are shaping energy-efficiency specifications for heat-transfer surface designs. Yangtze River Delta biopharma parks are scaling mammalian cell-culture platforms, with local fabricators expanding stainless-steel vessel fabrication capabilities for tonnage-scale installations.
India
CDSCO good manufacturing practice enforcement is elevating documentation burdens for multi-product facility equipment qualification. PLI scheme incentives for active pharmaceutical ingredient manufacturing are stimulating fermentation capacity investment across contract manufacturing networks. Maharashtra and Gujarat pharmaceutical clusters are procuring hybrid stainless-steel and single-use platforms to enable rapid product changeover for export-oriented biologics production.
Fermentation Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue equipment-as-a-service contracting and continuous fermentation architectures. The supplier base fragments across German precision-engineering specialists, diversified life-science conglomerates, and regional stainless-steel fabricators. Three archetypes dominate: single-use platform specialists, large-scale stainless-steel incumbents, and integrated analytical workflow providers. Competitive intensity centers on hybrid platform development and performance-guaranteed uptime arrangements displacing traditional capital purchase models.
Among German-based precision-engineering specialists, DIOSNA Dierks & Söhne GmbH and Heinrich Frings GmbH & Co. KG occupy positions anchored in century-old fermentation equipment heritage, representing the traditional stainless-steel fabrication archetype. Sartorius AG exemplifies the single-use platform specialist tier, with its dominance in flexible manufacturing demand visible across Asia-Pacific and European installations. These three entities collectively illustrate the competitive tension between incumbent vessel construction expertise and modular, rapidly deployable bioproduction technologies reshaping procurement patterns among mid-tier CDMOs.
| Leading Market Players |
|---|
| DIOSNA Dierks & Söhne GmbH |
| Bioengineering AG |
| SYSBIOTECH GmbH |
| GEA Group |
| Thermo Fisher Scientific |
| Pierre Guerin SA |
| Sartorius AG |
| Heinrich Frings GmbH & Co. KG |
| Eppendorf North America |
| Others |
Supply Flow & Price Mechanics
EU Green Deal industrial emissions frameworks gate qualified supply and premium-tier pricing access, restricting gasket and coating material formulations to validated sustainable portfolios while elevating documentation costs for European-sourced equipment. Buyers seeking EMA Annex 1 compliant vessel trains must absorb these qualification premiums or accept longer lead times from non-European fabricators lacking pre-validated material libraries.
Pricing Analysis
Volume-scale stainless-steel bioreactors generate thin margins at high absolute revenue, while pilot-scale single-use platforms command premium pricing through rapid deployment value. Three-tier pricing structure across premium, standard, and economy levels separates cGMP pharmaceutical-grade systems with extractables documentation from industrial enzyme vessels with minimal validation. Pricing pressure stems from mid-tier CDMO procurement consolidation favoring hybrid platforms over pure stainless-steel or single-use alternatives. Biofuel producers exhibit highest price sensitivity, accepting extended lead times for commodity-grade fabrication, whereas gene therapy developers prioritize speed-to-qualification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with concentrated European and Asian mill capacity for premium 316L stainless steel plate and forgings. German precision-engineering clusters around Basel and Hamburg draw from Swedish and Finnish specialty steel producers, while Chinese fabricators rest on domestic Baosteel and Taiyuan Iron & Steel supply. REACH substance restrictions on fluoropolymer coatings and elastomer gaskets create regulatory friction for non-European suppliers seeking European biopharma contracts. Distribution runs through direct OEM relationships for large-scale installations, with modular skid-mounted systems increasingly delivered through CDMO-turnkey contracting arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA Annex 1 sterile manufacturing revisions are accelerating replacement cycles and forcing sub-scale fabricators without validation documentation capabilities toward exit or acquisition. Consolidation pressure concentrates among regional stainless-steel shops unable to fund extractables-leachables testing infrastructure.
For Market Incumbents: Deploy hybrid platform engineering to preserve installed-base relationships against pure single-use challengers. GEA Group and Sartorius AG must extend performance-guaranteed uptime contracting to counter equipment-as-a-service entrants targeting Asia-Pacific gene therapy startups. Backward integration into specialty alloy procurement reduces exposure to European mill pricing volatility. For New Entrants and Emerging Players: The premium-to-economy price gap in continuous fermentation systems for commodity biochemicals offers white-space entry below GEA Group's tonnage-scale positioning. Cultured-food processing vessels for alternative protein startups represent underpenetrated demand with distinct sterility protocols from pharmaceutical applications. Target precision fermentation startups through novel vessel geometries with rapid product changeover capabilities absent from incumbent catalogs. For Investors and Strategic Acquirers: CDMO adoption of equipment-as-a-service contracting is the leading indicator that recurring revenue models are displacing capital purchase cycles. Long-term viability favors suppliers with validated sustainable material portfolios under REACH frameworks. Acquisition targets should demonstrate pre-qualified extractables documentation and established relationships with German precision-engineering clusters. Watch for NMPA biologics manufacturing guideline tightening in China as signal of validation documentation demand migrating eastward.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Development | Preserves stainless-steel incumbent relevance against pure single-use challengers across mid-tier CDMO procurement. |
| Equipment-as-a-Service Contracting | Captures recurring revenue from Asia-Pacific gene therapy startups with constrained capital deployment capacity. |
| Sustainable Material Qualification | Secures EU Green Deal compliance advantage for gasket and coating formulations in European-sourced equipment. |
| Continuous Fermentation Scale-Up | Reduces capital intensity per unit output for biofuel and industrial enzyme producers seeking tonnage capacity. |
| Precision Fermentation Vessel Design | Addresses alternative protein processing geometries distinct from pharmaceutical sterility protocols. |
Methodological Framework
Multi-period observation of vessel order backlogs, CDMO capacity announcements, and regulatory guidance publication timelines anchored the trend analysis, supplemented by interviews with bioprocess engineering directors, fermentation equipment procurement managers, sterile manufacturing quality leads, and precision fermentation startup founders. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA Annex 1 revision drafts, REACH substance restriction updates, and SEC filings of publicly traded life-science conglomerates. Bottom-up triangulation across individual vessel transaction values and top-down reconciliation against aggregate biopharmaceutical capital expenditure disclosures ensured methodological consistency.
Segment-weighting across product type, end user, technology, and size dimensions structured the analytical framework, with fed-batch versus continuous operating mode treated as distinct demand drivers. CAGRs were derived from fitted growth curves across the projection horizon, calibrated against historical stainless-steel and single-use platform adoption patterns. Industry-specific inputs included monoclonal antibody pipeline stage distributions, gene therapy manufacturing facility buildout announcements, and industrial enzyme capacity expansion disclosures from European biochemical producers.
Underlying measurement precision varies by segment; pharmaceutical-grade vessel demand carries tighter precision than emerging cultured-food applications with unproven scale-up economics. Forecasts reflect assumptions regarding EMA Annex 1 implementation timelines, REACH substance restriction enforcement intensity, and CDMO consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global Cell Culture Sampling Device Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Lab Centrifuges Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
Laboratory Shakers Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Global Laboratory Centrifuge Market