
 Ultracentrifuges Market | 2026-2036
Ultracentrifuges Market Size, Share, and Industry Trends Forecast 2026-2036
Ultracentrifuges Market Analytics
High-speed specification tiers is unwinding legacy product configurations across the ultracentrifuges landscape. Beckman Coulter leverages its deep rotor portfolio to dominate premium analytical workflows. Thermo Fisher Scientific sustains broad channel control through integrated life sciences distribution. Eppendorf AG specializes in compact benchtop systems that anchor European academic procurement.
An ultracentrifuge is a laboratory instrument that generates rotational speeds exceeding 100,000 revolutions per minute to separate macromolecules, organelles, and nanoparticles based on density and sedimentation coefficient. Floor model ultracentrifuges command the highest capital allocation from pharmaceutical companies running continuous bioprocessing campaigns. Gradient ultracentrifuges are capturing expanded share in protein separation workflows where resolution requirements have tightened. Non-refrigerated variants retain cost advantages in clinical diagnostics settings with lower thermal sensitivity.
The FDA enforces equipment validation standards under current good manufacturing practice frameworks that govern ultracentrifuge deployment in commercial biologics production. ISO 13485 certification requirements shape supplier qualification pathways for manufacturers serving regulated end users. Stakeholders must monitor evolving rotor material specifications and energy efficiency benchmarks as procurement criteria harden across biotechnology firms and contract manufacturing organizations.
Market Dynamics
Pharmaceutical bioprocessing scale-up is compressing procurement cycles for high-specification separation equipment as gene therapy manufacturing capacity expands faster than supplier lead times can accommodate.
Growth Catalysts
- FDA cGMP framework tightening:Updated validation requirements for cell and gene therapy manufacturing are mandating redundant ultracentrifuge installations in commercial production suites.
- Continuous bioprocessing adoption:Pharmaceutical companies are integrating floor-model ultracentrifuges into 24-hour production campaigns to maximize batch yields.
- Vaccine purification infrastructure:United States biologics manufacturing clusters are expanding dedicated viral vector purification capacity.
Market Restraints
- Titanium alloy rotor supply concentration:Specialized aerospace-grade material sourcing concentrates among Japanese and German metallurgical suppliers.
- Refrigeration compressor input costs:Energy-efficient cooling system components face volatile pricing tied to rare earth magnet availability.
- ISO 13485 certification timeline:Medical device quality management system audits create 14-18 month supplier qualification delays.
Strategic Opportunities
- Contract manufacturing organization channel expansion:CDMOs are consolidating equipment procurement under multi-year service agreements with predictive maintenance bundles.
- India biologics manufacturing incentive:Production-linked incentive schemes for pharmaceutical manufacturing are attracting ultracentrifuge deployment in Hyderabad and Bengaluru clusters.
- Benchtop system academic penetration:European research institutions are replacing aging floor models with compact refrigerated units for shared core facility access.
Industry Challenges
- Rotor balancing technician scarcity:Specialized field service engineers with vacuum chamber and precision bearing expertise command premium compensation.
- Legacy system integration complexity:Pharmaceutical facilities face protocol revalidation costs when connecting new ultracentrifuges to existing building management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultracentrifuges Market |
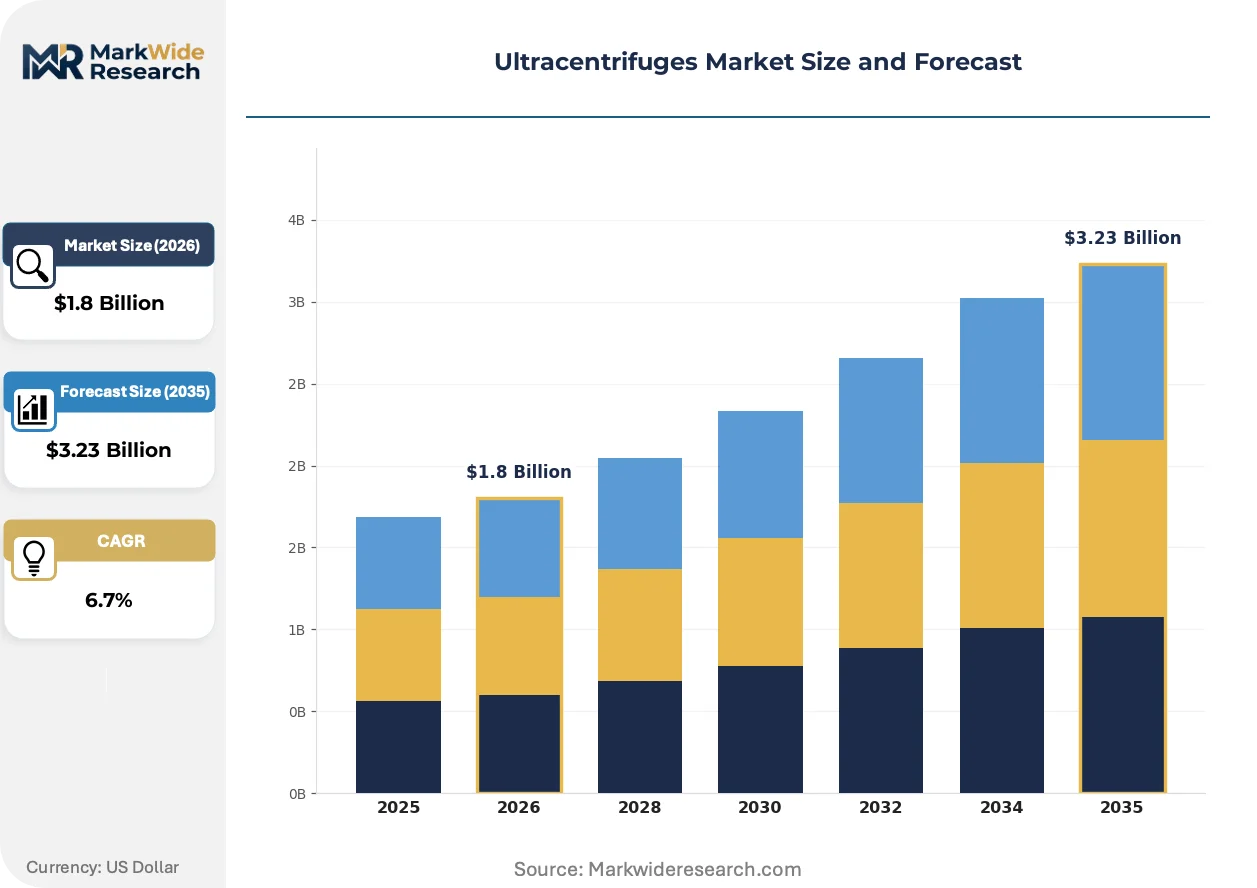
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Ultracentrifuges, Floor Model Ultracentrifuges, High-Speed Ultracentrifuges, Low-Speed Ultracentrifuges Application: Biological Research, Clinical Diagnostics, Protein Separation, Cell Culture End User: Academic Institutions, Research Laboratories, Pharmaceutical Companies, Biotechnology Firms Technology: Refrigerated Ultracentrifuges, Non-Refrigerated Ultracentrifuges, Gradient Ultracentrifuges, Continuous Flow Ultracentrifuges |
| Companies Covered | Beckman Coulter, Thermo Fisher Scientific, Eppendorf AG, Hettich Instruments, Sigma Laborzentrifugen, KUBOTA, Haier Biomedical, Hunan Xiangyi Laboratory Instrument Development, Hitachi Koki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultracentrifuges Market Evolving Landscape
Carbon fiber composite rotors are compressing maintenance intervals and enabling higher relative centrifugal force thresholds than traditional metal alloys permit.
Fixed-angle carbon fiber rotor technology is decomposing the historical trade-off between sample volume capacity and maximum achievable g-force. Gene therapy developers at CDMOs are specifying these rotors for adeno-associated virus purification workflows. The shift is decomposing legacy titanium rotor replacement cycles from annual to biennial intervals.
EMA's updated Annex 1 sterile manufacturing guidelines are mandating closed-system sampling interfaces for all aseptic processing equipment. Ultracentrifuge manufacturers must now integrate rapid transfer ports and isolator-compatible enclosures. European vaccine producers are retrofitting existing suites or specifying new equipment with these containment features.
Academic core facilities are unbundling capital acquisition from service contracts, purchasing instruments outright while negotiating rotor refresh programs separately. This procurement pattern disrupts traditional bundled financing models that dominated institutional sales channels. The behavior is most visible at United States research universities managing NIH-funded shared instrumentation grants.
Ultracentrifuges Market Segmentation
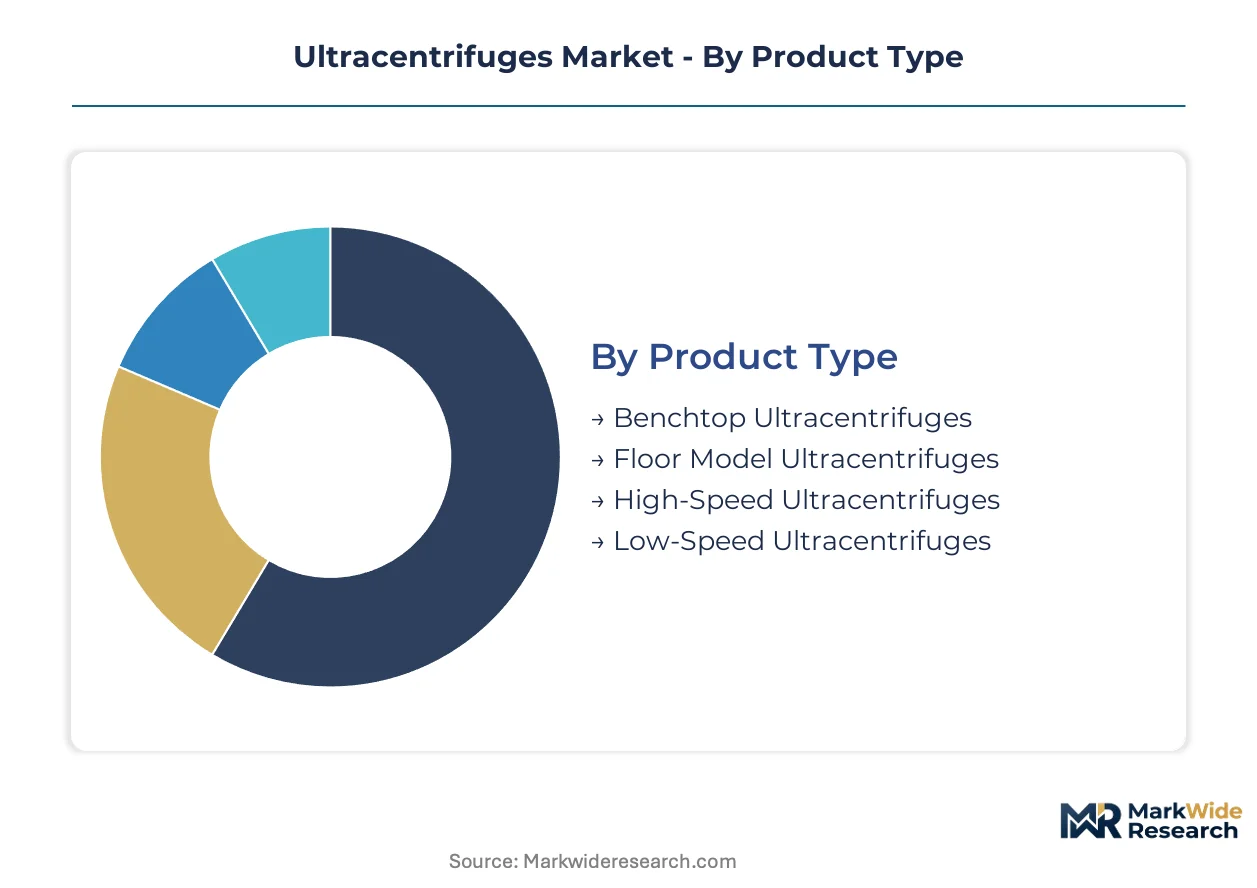
Ultracentrifuge procurement channels diverge sharply by specification tier. Pharmaceutical manufacturers negotiate multi-year service bundles for floor models while academic buyers prioritize capital-efficient benchtop configurations.
Product Type:
Floor models dominate direct sales channels serving bioprocessing facilities. Benchtop systems flow through laboratory distributors targeting academic and clinical accounts.
- Floor Model Ultracentrifuges:These instruments generate rotational speeds exceeding 100,000 RPM with vacuum-sealed drive systems and precision temperature control. Pharmaceutical companies in the United States deploy these for continuous viral vector purification campaigns. FDA cGMP validation requirements mandate redundant installations in commercial production suites.
- Benchtop Ultracentrifuges:Compact units occupy under-bench footprint with reduced noise signatures and simplified rotor exchange protocols. European academic institutions specify these for shared core facility access where space constraints limit floor model deployment. NIH-funded instrumentation grants accelerate replacement of aging floor models at United States research universities.
- High-Speed Ultracentrifuges:Intermediate specification tier balancing rotor capacity with maximum relative centrifugal force thresholds.
- Low-Speed Ultracentrifuges:Clinical diagnostics workhorses prioritizing sample throughput over extreme g-force generation.
By volume, benchtop systems lead. By growth pace, floor models are expanding most quickly.
Application:
Cost tier stratification separates premium protein separation workflows from standardized clinical diagnostics protocols.
- Protein Separation:Gradient ultracentrifugation achieves resolution thresholds essential for monoclonal antibody characterization and subcellular fractionation. Biotechnology firms in the United States concentrate procurement here as gene therapy manufacturing capacity expands faster than supplier lead times accommodate.
- Biological Research:Fundamental investigations into organelle isolation and macromolecular complex characterization drive specification diversity. Academic laboratories balance capital constraints against rotor portfolio breadth requirements.
- Clinical Diagnostics:Lipoprotein profiling and viral load quantification utilize standardized protocols with lower thermal sensitivity.
- Cell Culture:Harvesting and clarification workflows for mammalian cell lines.
Protein separation commands premium pricing. Clinical diagnostics generates highest unit volume.
End User:
Customer type determines margin structure and contract complexity across the value chain.
- Pharmaceutical Companies:Commercial biologics manufacturers negotiate predictive maintenance bundles and rotor refresh programs under multi-year agreements. These buyers impose ISO 13485 certification requirements that create 14-18 month supplier qualification timelines.
- Biotechnology Firms:Emerging developers prioritize flexible procurement terms accommodating rapid scale-up from research to clinical manufacturing.
- Academic Institutions:Budget-constrained buyers unbundling capital acquisition from service contracts.
- Research Laboratories:Government and private non-profit facilities with grant-dependent funding cycles.
Pharmaceutical companies anchor revenue concentration. Biotechnology firms are gaining share fastest.
Technology:
Supply concentration in refrigeration compressors and rare earth magnet sourcing shapes procurement risk profiles.
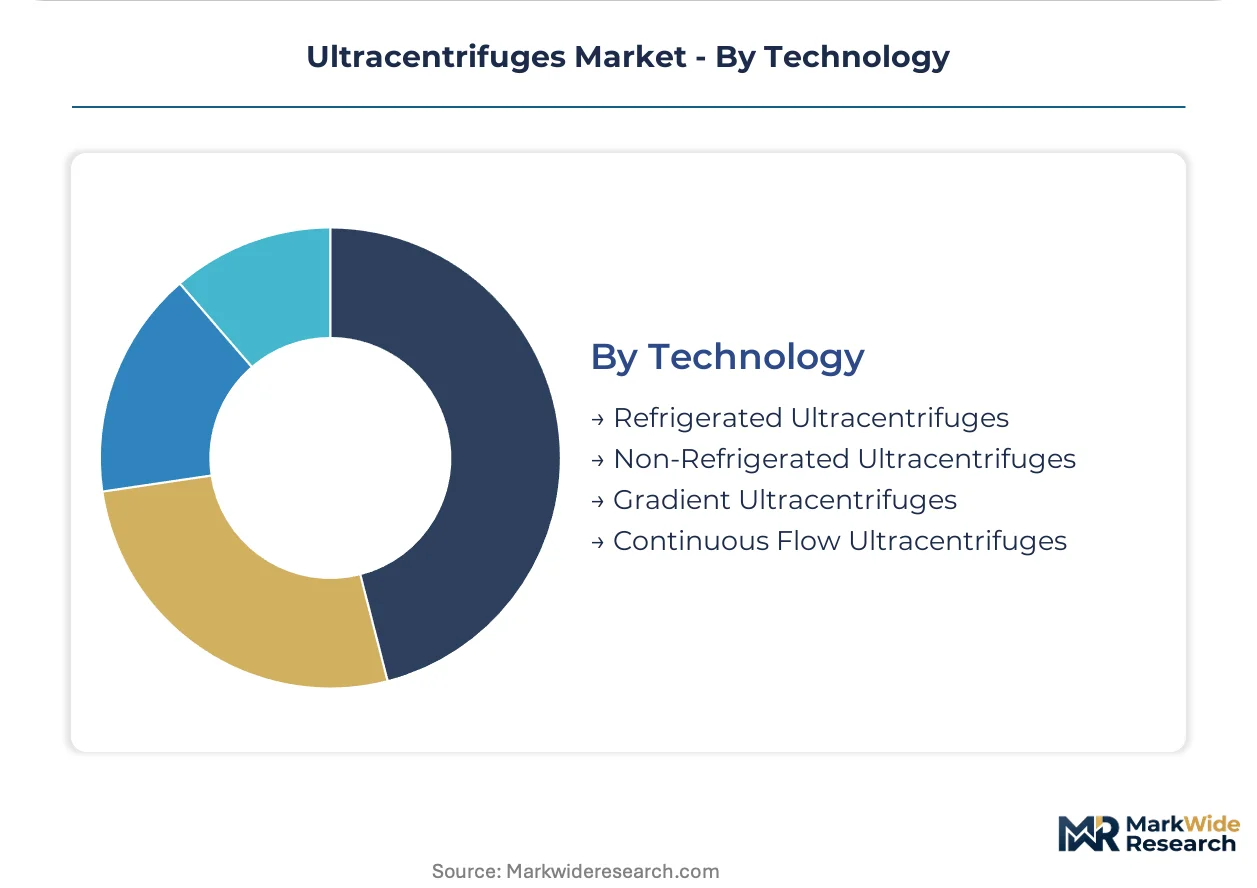
- Refrigerated Ultracentrifuges:Precision cooling systems maintain sample integrity across extended run times for sensitive biological materials. Gene therapy developers at CDMOs specify these for adeno-associated virus purification where thermal degradation risks compromise yield.
- Gradient Ultracentrifuges:Density gradient formation capabilities enable resolution of macromolecules with similar sedimentation coefficients.
- Non-Refrigerated Ultracentrifuges:Cost advantages retain relevance in clinical settings with rapid processing protocols.
- Continuous Flow Ultracentrifuges:Industrial-scale separation for vaccine purification infrastructure.
Refrigerated systems dominate value capture. Gradient technology shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace-grade titanium sourcing concentrates among Japanese and German metallurgical suppliers, creating procurement dependencies for rotor manufacturers serving pharmaceutical clusters worldwide. Equipment deployment patterns track biologics manufacturing capacity expansion and regulatory enforcement intensity across major markets.
United States
Gene therapy manufacturing capacity in Boston and San Diego is expanding faster than ultracentrifuge supplier lead times accommodate. FDA cGMP validation requirements mandate redundant floor-model installations in commercial production suites. Viral vector purification infrastructure concentrates in Research Triangle Park and the Bay Area.
Germany
EMA Annex 1 sterile manufacturing guidelines are mandating closed-system sampling interfaces for aseptic processing equipment. ISO 13485 certification requirements shape supplier qualification pathways for manufacturers serving regulated end users. Precision engineering capabilities in Baden-Württemberg anchor rotor fabrication supply chains.
China
NMPA good manufacturing practice frameworks are tightening equipment validation standards for commercial biologics production. Dual carbon goals are pressuring energy efficiency benchmarks in refrigeration compressor specifications. Biologics manufacturing clusters in Suzhou and Shanghai are expanding dedicated viral vector purification capacity.
India
Production-linked incentive schemes for pharmaceutical manufacturing are attracting ultracentrifuge deployment in Hyderabad and Bengaluru clusters. CDSCO equipment registration requirements create extended supplier qualification timelines for imported systems. Contract manufacturing organizations are consolidating procurement under multi-year service agreements.
Japan
METI industrial policy supports domestic precision manufacturing capabilities for specialized vacuum chamber and precision bearing components. PMDA quality management system audits enforce rigorous validation protocols for separation equipment in commercial production. Tokyo-Osaka industrial corridors concentrate field service engineering expertise.
Ultracentrifuges Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the ultracentrifuges landscape. Premium analytical workflows concentrate among established life sciences conglomerates with deep rotor portfolios. Compact benchtop configurations attract specialized laboratory equipment fabricators serving academic procurement channels. Competitive moves center on carbon fiber composite rotor development and predictive maintenance service bundling.
Within the premium-tier vector, Beckman Coulter and Thermo Fisher Scientific exemplify integrated life sciences conglomerates dominating direct sales channels for bioprocessing facilities. Eppendorf AG occupies a position representing European academic-focused specialists emphasizing compact refrigerated systems. These three anchors illustrate how geographic origin and corporate structure map to distinct procurement channel strategies across pharmaceutical and research end users.
| Leading Market Players |
|---|
| Beckman Coulter |
| Thermo Fisher Scientific |
| Eppendorf AG |
| Hettich Instruments |
| Sigma Laborzentrifugen |
| KUBOTA |
| Haier Biomedical |
| Hunan Xiangyi Laboratory Instrument Development |
| Hitachi Koki |
| Others |
Value Network & Pricing Analysis
ISO 13485 certification gates both supplier qualification timelines and pricing tier stratification across the ultracentrifuges landscape, compressing margins for uncertified entrants while enabling premium positioning for validated incumbents serving FDA-regulated pharmaceutical manufacturers.
Pricing Analysis
FDA cGMP framework dictates the pricing tier structure across refrigerated floor models, gradient systems, and compact benchtop configurations. Certification grade and rotor material specification drive price differentiation between titanium alloy and emerging carbon fiber composite variants. Cost compression in non-refrigerated clinical tiers is intensifying because Haier Biomedical and domestic Chinese suppliers are expanding production capacity. Academic institutions exhibit highest price sensitivity, while pharmaceutical companies prioritize predictive maintenance bundling over unit cost.
Supply Chain Analysis
Aerospace-grade titanium billet sourcing concentrates among Japanese and German metallurgical suppliers, creating single-source vulnerability for rotor manufacturers. Precision bearing fabrication and rare earth magnet procurement for refrigeration compressors draw from overlapping East Asian supply nodes. Tariff exposure runs through Sino-American trade corridors for vacuum chamber components. Distribution runs through integrated life sciences conglomerates for pharmaceutical accounts and specialized laboratory distributors for academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultracentrifuges market operates as a regulatory-moat arena where FDA and EMA validation entrenchment creates switching costs that pharmaceutical manufacturers cannot readily circumvent without triggering costly protocol revalidation.
For Market Incumbents: Consolidate rotor refresh program contracts under multi-year predictive maintenance bundles to lock out emerging carbon fiber specialists. Deepen backward integration into precision bearing supply through captive manufacturing partnerships in Baden-Württemberg engineering clusters. The threat of CDMO procurement consolidation demands channel control reinforcement before contract manufacturing organizations standardize on single-source agreements. For New Entrants and Emerging Players: Differentiate on carbon fiber composite rotor technology to decompose the annual replacement cycle economics that titanium incumbents depend upon. Target European academic core facilities unbundling capital acquisition from service contracts, where NIH-funded instrumentation grants accelerate benchtop system replacement cycles. A gene therapy CDMO pilot program offers the most penetrable entry vector for establishing FDA cGMP validation credentials. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across refrigerated floor model manufacturing as energy efficiency benchmarks harden under dual carbon goals. Acquisition candidates should display established ISO 13485 certification with active FDA master files and rotor portfolios spanning both titanium legacy and carbon fiber next-generation specifications. The signal to watch is CDMO consolidation velocity in United States viral vector purification clusters, where multi-year service agreement announcements indicate procurement rationalization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Rotor Portfolio Expansion | Carbon fiber composite technology decomposes legacy titanium replacement economics for gene therapy developers. |
| Predictive Maintenance Service Bundling | Multi-year agreements with rotor refresh programs lock pharmaceutical procurement under integrated life sciences distribution. |
| ISO 13485 Certification Acceleration | Compressed 14-18 month audit timelines enable faster supplier qualification for CDMO channel penetration. |
| Closed-System Sampling Interface Integration | EMA Annex 1 compliance mandates rapid transfer ports for European vaccine producer retrofit cycles. |
| Academic Core Facility Direct Sales | NIH-funded instrumentation grants at United States research universities accelerate benchtop replacement demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with bioprocessing executives, regulatory affairs leads at CDMOs, academic core facility directors, and rotor fabrication engineers; and secondary validation through FDA 483 inspection observations, EMA manufacturing authorization databases, NIH instrumentation grant disbursement records, and SEC 10-K filings from listed life sciences conglomerates. Bottom-up triangulation across equipment procurement volumes and top-down reconciliation against biologics manufacturing capacity expansion verified market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type tier, application workflow specificity, end-user procurement authority, and regional regulatory enforcement intensity. CAGRs were derived from equipment deployment rates against gene therapy manufacturing capacity buildout trajectories. Forecast inputs incorporated rotor material substitution elasticities and CDMO consolidation velocity indices without prescribing specific year-over-year progression.
The analysis sits within stated boundaries; outcomes outside sustained FDA cGMP enforcement intensity or accelerated carbon fiber rotor adoption curves would require recalibration. Practitioners should keep alternative scenarios live as titanium alloy supply concentration and rare earth magnet pricing volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
PCR Consumables Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Global Cell Culture Sampling Device Market
Biotechnology Equipment
Amino Acid Analyzer Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Cell Proliferation Kit Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Histology Equipment Market