
 Laboratory Andrology Equipment Market | 2026-2036
Laboratory Andrology Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Andrology Equipment Market Analysis
Consolidation among fertility clinic networks is repositioning purchasing power toward multi-site reproductive health systems. Hamilton Thorne Inc. leverages its specialization in computer-assisted sperm analysis to anchor North American distribution. Zeiss competes through optical precision in diagnostic microscopy for andrology workflows. Medical Electronic Systems, LLC differentiates via automated semen analysis platforms that reduce technician variability.
Laboratory andrology equipment encompasses instruments designed for quantitative and qualitative assessment of semen parameters, including sperm concentration, motility, morphology, and functional integrity, typically operating at magnifications of 200x to 600x with computer-assisted image capture. These systems serve fertility diagnostics, cryopreservation quality control, and research into male reproductive health. Semen analysis systems dominate installed bases due to their essential role in initial fertility workups, while digital image analysis technology captures expanding interest for standardizing subjective assessments. Sperm function testing devices occupy a narrower but higher-margin niche serving specialized diagnostic protocols.
FDA oversight of in vitro diagnostic and assisted reproductive technology devices shapes product development pathways and 510(k) clearance requirements for U.S. market access. ISO 13485 quality management standards and the EU Medical Device Regulation govern international commercialization trajectories, with CE marking demands intensifying post-MDR transition. Stakeholders must monitor how regulatory divergence between FDA predicate device pathways and European notified body consolidation reshapes competitive entry costs and timeline risk.
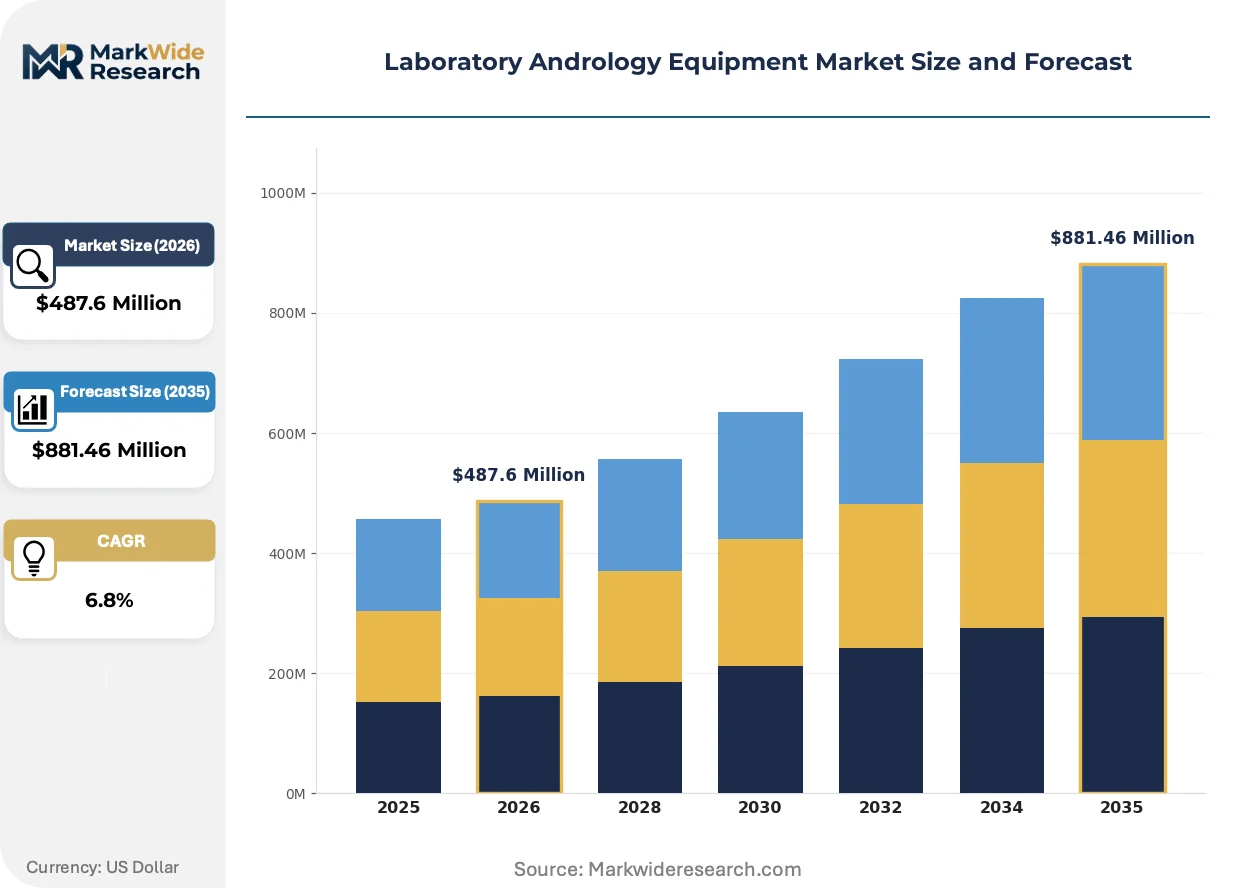
Market Dynamics
Centralization of fertility clinic procurement is compressing vendor margins while elevating technical performance requirements for computer-assisted sperm analysis systems. Large multi-site networks now demand interoperability standards that smaller manufacturers struggle to meet.
Growth Catalysts
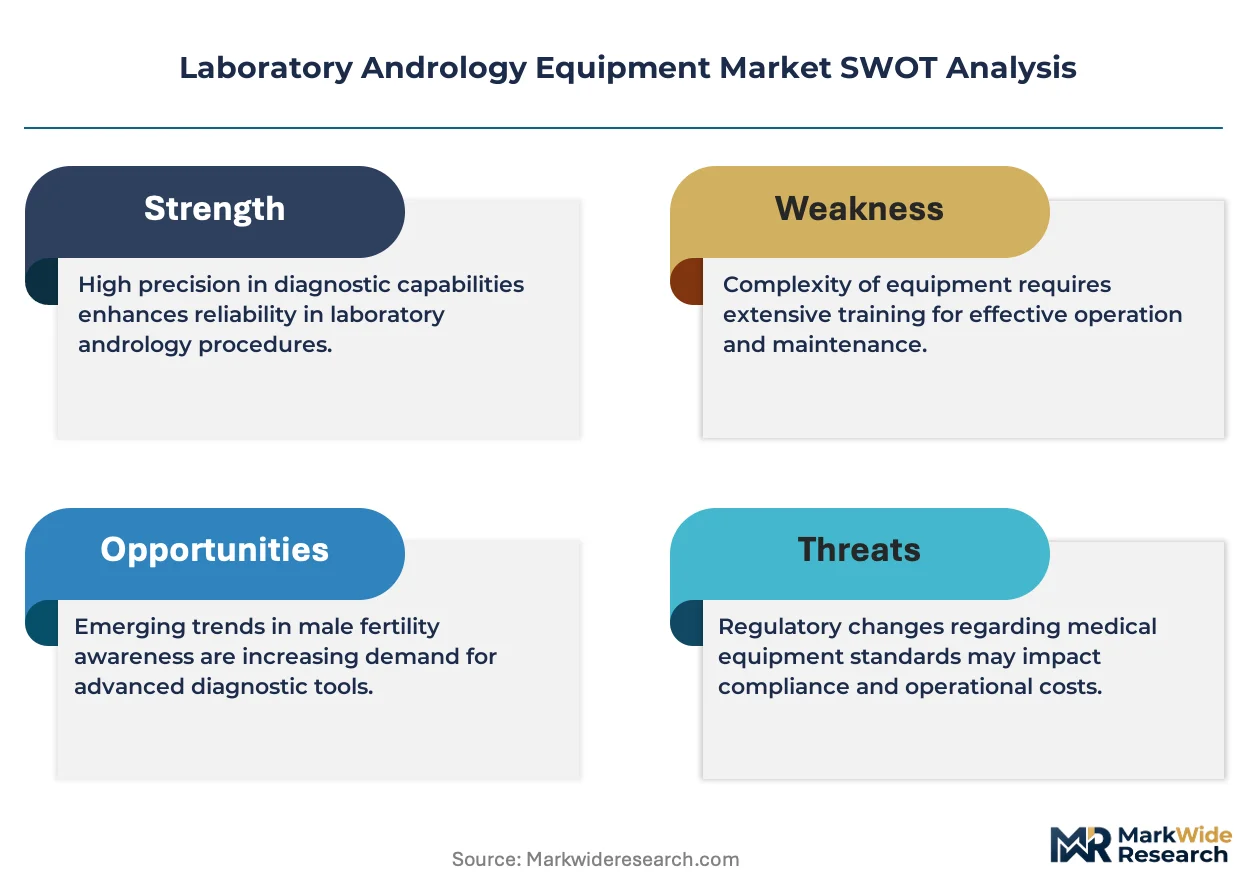
- EU Medical Device Regulation (MDR):Stricter CE marking requirements for in vitro diagnostic devices are filtering out marginal competitors and elevating quality benchmarks across the European market.
- Artificial intelligence integration:Machine learning algorithms for sperm morphology classification are reducing inter-technician variability and accelerating diagnostic throughput in high-volume fertility centers.
- United States:Consolidation of independent fertility practices into regional networks is creating concentrated demand for standardized laboratory platforms with centralized service contracts.
Market Restraints
- Optical component supply concentration:Precision microscopy lenses and sensors depend on specialized German and Japanese suppliers, exposing manufacturers to lead time volatility and currency risk.
- FDA 510(k) pathway complexity:Evolving predicate device requirements for assisted reproductive technology equipment are extending clearance timelines and inflating regulatory compliance costs for new entrants.
- Limited technician training infrastructure:Shortage of certified clinical laboratory scientists with andrology specialization constrains expansion of testing capacity regardless of equipment availability.
Strategic Opportunities
- India:Underdeveloped male fertility diagnostic infrastructure in tier-2 cities presents first-mover potential for automated semen analysis platforms with simplified operation protocols.
- At-home collection kits with laboratory integration:Remote specimen collection paired with centralized digital analysis is opening new patient acquisition channels outside traditional clinic-based workflows.
- ISO 13485 certification acceleration:Early alignment with harmonized quality management standards enables streamlined multi-jurisdiction market entry before MDR transition deadlines.
Industry Challenges
- Legacy system integration:New digital imaging platforms must interface with established laboratory information management systems, requiring costly custom middleware development.
- Technician certification bottlenecks:Extended training periods for computer-assisted sperm analysis operators delay revenue realization from installed equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Andrology Equipment Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semen Analysis Systems, Sperm Function Testing Devices, Microscopes, Incubators Application: Fertility Clinics, Research Laboratories, Hospitals, Diagnostic Centers Technology: Optical, Fluorescence, Electrophoresis, Digital Image Analysis End User: Clinicians, Biologists, Lab Technicians, Reproductive Specialists |
| Companies Covered | Hamilton Thorne Inc., Microptic, Medical Electronic Systems, LLC, Zeiss, Sony Electronics Inc., Synaptive Medical, Aesculap Inc., Bio-Rad Laboratories, True Digital Surgery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Andrology Equipment Market Emerging Trajectories
Digital image analysis technology is fundamentally restructuring how fertility laboratories validate diagnostic consistency. Automation is compressing the gap between specialized research equipment and routine clinical platforms.
Deep learning-based sperm morphology assessment is overtaking manual microscopy scoring in accredited fertility laboratories. High-volume clinics in the United States and Germany are adopting these systems to standardize subjective classifications. This compression of diagnostic variability is overtaking traditional technician-dependent workflows and enabling network-wide quality benchmarking.
The EU Medical Device Regulation's intensified clinical evidence requirements are reshaping product development cycles for European market access. Manufacturers must now generate prospective performance data rather than relying on predicate equivalence. In vitro diagnostic segments serving andrology applications are responding by front-loading clinical validation studies before design finalization.
Large clinic networks are consolidating vendor relationships around single-source laboratory platform contracts. Independent distributors and regional equipment resellers are losing access as procurement authority centralizes at network headquarters. This concentration is most visible across United States fertility systems with ten or more satellite locations.
Laboratory Andrology Equipment Market Segmentation
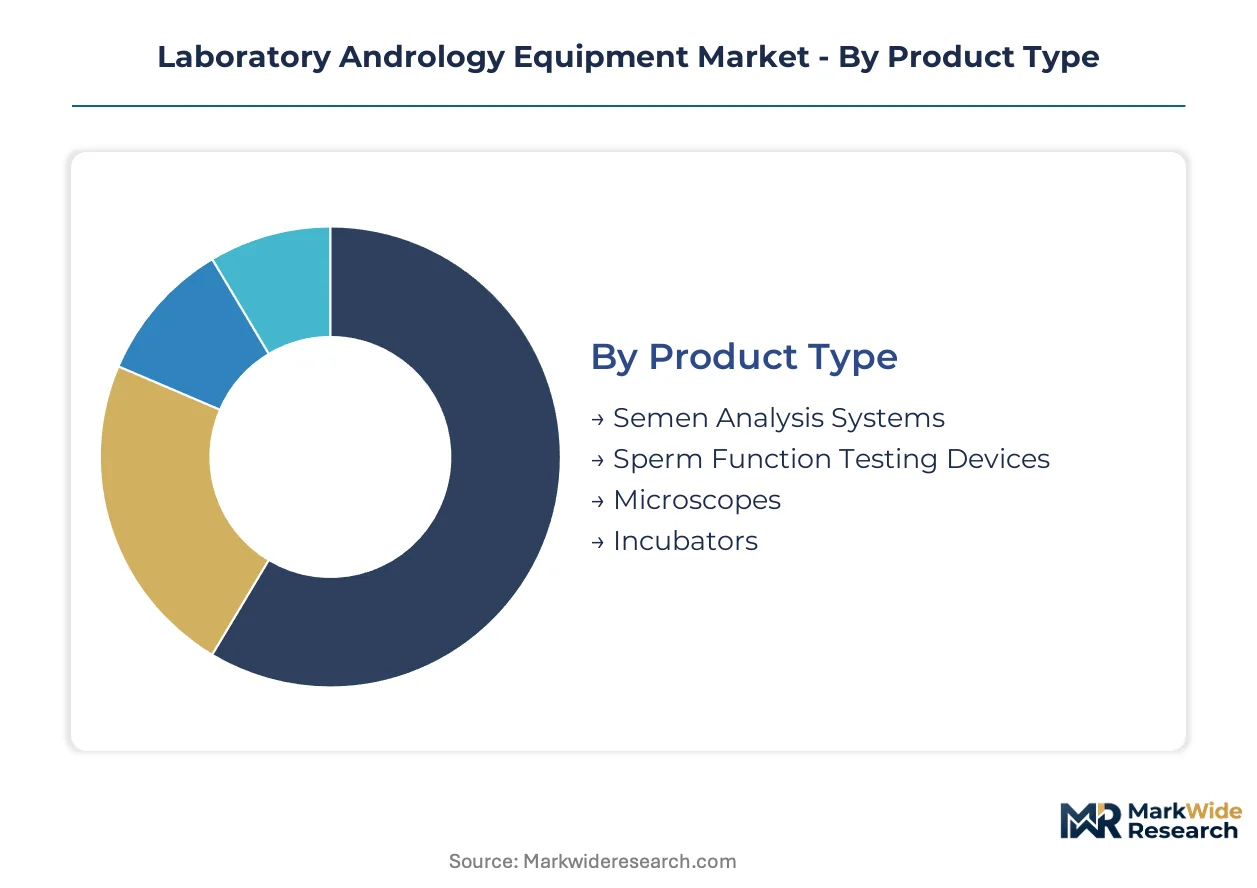
Equipment segmentation in laboratory andrology reveals how procurement authority concentrates around standardized platforms versus specialized devices. Fertility networks prioritize interoperability across their laboratory footprints, while academic centers demand configurable research-grade instrumentation.
Product Type:
Customization intensity spans from fully automated semen analysis platforms to manually operated incubators requiring protocol adaptation by site.
- Semen Analysis Systems:Computer-assisted sperm analysis platforms integrate optical microscopy with digital image capture at 200x-600x magnification for quantitative assessment of concentration, motility, and morphology. Demand concentrates in United States fertility clinic networks seeking standardized quality benchmarks across multi-site operations. FDA 510(k) clearance requirements shape competitive entry for these systems.
- Sperm Function Testing Devices:Specialized instruments assess acrosome reaction, DNA fragmentation, and membrane integrity through fluorescence or electrophoresis methods. Research laboratories in Germany and Japan drive adoption for advanced diagnostic protocols. EU MDR clinical evidence requirements are extending development timelines for new entrants in this higher-margin niche.
- Microscopes:Optical precision instruments from German and Japanese suppliers serve manual verification workflows in smaller diagnostic centers.
- Incubators:Temperature and gas-controlled chambers maintain specimen viability during processing intervals, with customization for specific culture media protocols.
Leading the category by volume: Semen Analysis Systems. Expanding most quickly: Sperm Function Testing Devices.
Application:
End-use concentration correlates with reimbursement structure and regulatory oversight intensity across clinical versus research settings.
- Fertility Clinics:Dedicated reproductive health facilities perform initial diagnostic workups and treatment monitoring through integrated laboratory workflows. Large United States networks centralize procurement around single-vendor contracts with standardized computer-assisted sperm analysis platforms. Consolidation among independent practices is compressing vendor margins while elevating technical performance requirements.
- Research Laboratories:Academic and institutional facilities investigate male reproductive biology through specialized sperm function assays and cryopreservation studies. Funding from NIH and European Research Council supports adoption of advanced digital image analysis systems. ISO 13485 certification enables streamlined equipment sourcing across multi-jurisdiction collaborations.
- Hospitals:General medical centers with reproductive endocrinology departments require andrology testing for pre-surgical fertility preservation and oncology patient management.
- Diagnostic Centers:Independent pathology and reference laboratories offer semen analysis as outsourced service with rapid turnaround requirements.
Procurement authority concentrates most heavily in: Fertility Clinics. Steepest expansion trajectory: Research Laboratories.
Technology:
Platform sophistication determines technician training burden and diagnostic standardization potential across laboratory workflows.
- Optical:Conventional brightfield and phase-contrast microscopy remains foundational for manual semen assessment in resource-constrained settings.
- Fluorescence:Excitation-emission-based detection enables specific staining protocols for viability and acrosomal status evaluation in research applications.
- Electrophoresis:Separation-based methods quantify sperm DNA fragmentation index with high reproducibility for specialized diagnostic referrals.
- Digital Image Analysis:Machine learning algorithms automate morphology classification and reduce inter-technician variability in high-volume fertility centers. United States and German clinics are adopting these systems to enable network-wide quality benchmarking. Deep learning integration is displacing manual microscopy scoring in accredited laboratories.
Dominant installed base: Optical. Gaining share fastest: Digital Image Analysis.
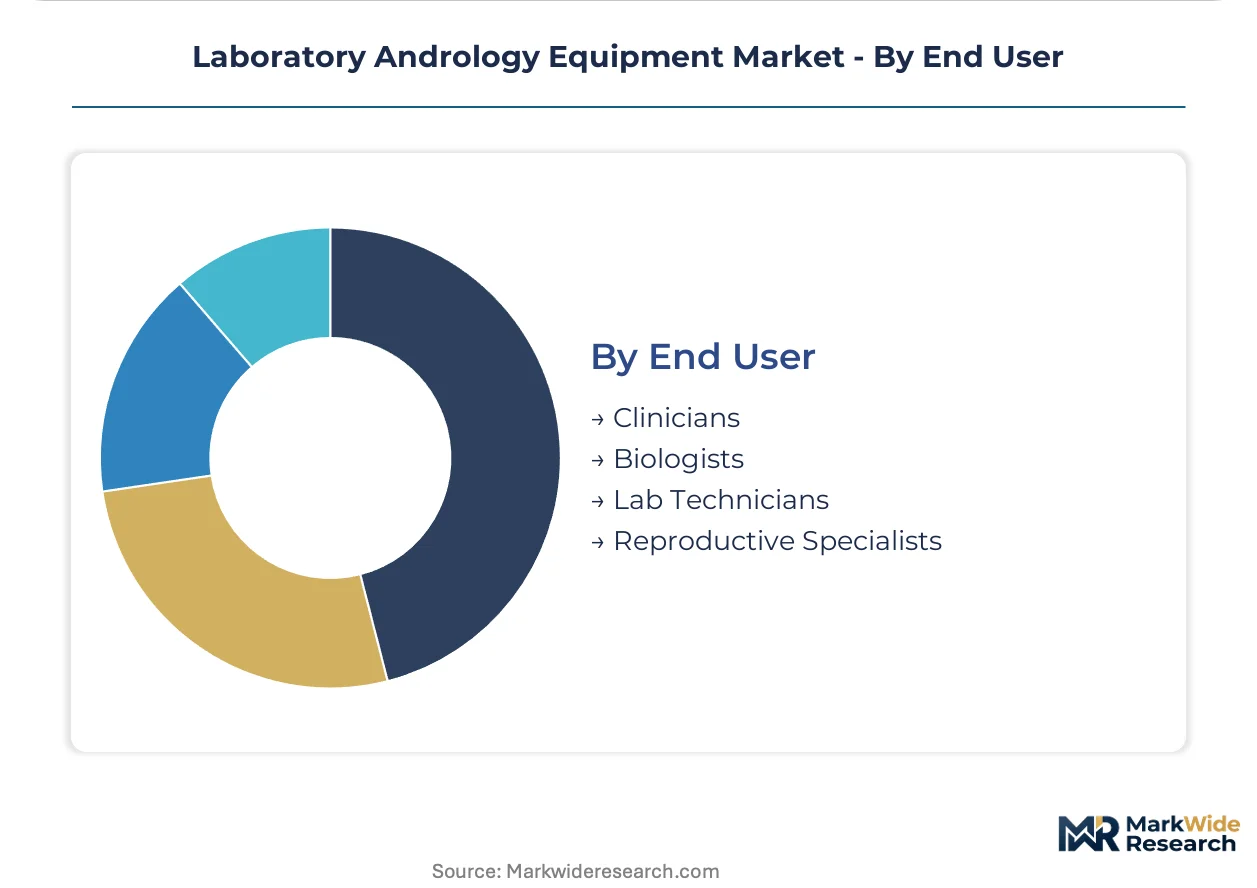
End User:
Operator specialization level shapes equipment interface design and training infrastructure requirements.
- Clinicians:Reproductive endocrinologists require integrated reporting systems linking laboratory results to treatment decision workflows.
- Biologists:Research scientists demand configurable protocols and raw data export for experimental reproducibility.
- Lab Technicians:Certified clinical laboratory scientists perform routine semen analysis with standardized operating procedures. Shortage of andrology-specialized technicians constrains testing capacity expansion regardless of equipment availability. Extended training periods for computer-assisted sperm analysis operators delay revenue realization from installed platforms.
- Reproductive Specialists:Andrologists and embryologists coordinate specimen processing with cryopreservation and assisted reproductive technology workflows.
Largest operator category by headcount: Lab Technicians. Fastest credentialing requirements: Reproductive Specialists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical component suppliers anchor the upstream precision lens supply chain for laboratory andrology equipment, with specialized manufacturing concentrated in the Jena and Oberkochen clusters. This feedstock locality shapes equipment availability and lead time dynamics across downstream markets.
United States
Large fertility clinic networks in California, Texas, and the Northeast corridor centralize procurement authority around standardized computer-assisted sperm analysis platforms. FDA 510(k) clearance requirements for assisted reproductive technology devices extend market entry timelines for new equipment vendors. The Boston-Cambridge biotech corridor drives adoption of AI-integrated digital image analysis systems for network-wide quality benchmarking.
Germany
Research laboratories in Baden-Württemberg and Bavaria demand configurable sperm function testing devices for advanced male reproductive biology studies. EU MDR intensified clinical evidence requirements filter marginal competitors from the European market. The Jena optical cluster supplies precision microscopy components that constrain equipment production capacity during demand surges.
Japan
Aging demographics and declining birth rates concentrate fertility diagnostic demand in Tokyo, Osaka, and Nagoya metropolitan areas. PMDA oversight of in vitro diagnostic devices aligns with international harmonization initiatives while maintaining distinct documentation requirements. The Kansai region hosts specialized manufacturers of fluorescence-based sperm viability assessment systems serving domestic research institutes.
India
Tier-2 cities in Maharashtra, Karnataka, and Tamil Nadu present underdeveloped male fertility diagnostic infrastructure with first-mover potential for automated platforms. CDSCO medical device registration requirements are tightening quality benchmarks for imported laboratory equipment. The Delhi-NCR corridor concentrates fertility clinic expansion activity as regional networks consolidate independent practices.
United Kingdom
London and Southeast England fertility centers prioritize interoperability standards for multi-site laboratory platform integration. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for equipment manufacturers. The Cambridge life sciences cluster drives research demand for high-precision sperm DNA fragmentation analysis systems.
Laboratory Andrology Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-augmented diagnostic workflows and remote specimen collection integrations. The vendor base stratifies between multi-product laboratory platform suppliers and specialized sperm analysis technology developers. Three archetypes dominate: optical precision specialists, automated semen analysis platform builders, and fertility workflow integrators. Competitive moves concentrate on strategic partnerships with large clinic networks and accelerated ISO 13485 certification timelines for MDR readiness.
Among North American equipment developers, Hamilton Thorne Inc. and Medical Electronic Systems, LLC occupy positions within the automated analysis tier, while Zeiss exemplifies the optical precision archetype rooted in German engineering heritage. These anchors represent contrasting strategic pathways—software-integrated automation versus foundational microscopy excellence—that shape procurement preferences across fertility clinic networks and research institutions.
| Leading Market Players |
|---|
| Hamilton Thorne Inc. |
| Microptic |
| Medical Electronic Systems, LLC |
| Zeiss |
| Sony Electronics Inc. |
| Synaptive Medical |
| Aesculap Inc. |
| Bio-Rad Laboratories |
| True Digital Surgery |
| Others |
Supply Flow & Price Mechanics
Certified clinical laboratory scientists in the United States command wage premiums that compress margins on entry-level semen analysis platforms while widening spreads between premium AI-integrated systems and economy-grade manual microscopy configurations. Labor-cost differentials between fertility network hubs and independent diagnostic centers directly stratify equipment pricing tiers across North American and European markets.
Pricing Analysis
Volume concentrates in mid-tier automated semen analysis platforms while margins accrue to specialized sperm function testing devices serving research protocols. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI-integrated systems from CE-marked automated platforms and uncertified manual microscopy configurations. Cost compression in the standard tier intensifies because large clinic networks centralize procurement around single-vendor contracts. Research laboratories exhibit lowest price sensitivity due to grant-funded capital budgets, while independent diagnostic centers in tier-2 Indian cities demonstrate acute price responsiveness.
Supply Chain Analysis
Single-source vulnerability sits with precision optical component suppliers concentrated in the Jena and Oberkochen clusters of Germany. German and Japanese manufacturers anchor the upstream feedstock for microscopy lenses, fluorescence sensors, and digital image capture modules that equipment assemblers in the United States and China draw from. Tariff exposure on precision optics imported into North American assembly facilities elevates landed costs during currency volatility periods. Distribution runs through authorized medical device distributors serving fertility clinic networks, with direct procurement relationships consolidating around large multi-site reproductive health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory andrology equipment functions as a vertical-integration race where control over optical component supply and AI algorithm development determines sustainable margin capture. Manufacturers pursuing backward integration into precision lens sourcing or forward integration into laboratory information management system interoperability gain durable positioning.
For Market Incumbents: Deepen ISO 13485 certification coverage across multiple notified bodies to preempt EU MDR transition bottlenecks that threaten market access continuity. Anchor North American distribution through exclusive service contracts with consolidating fertility networks in California, Texas, and the Northeast corridor, defending against emerging AI-native entrants offering cloud-based morphology classification. For New Entrants and Emerging Players: Begin with automated semen analysis platforms featuring simplified operation protocols targeting underdeveloped diagnostic infrastructure in Maharashtra, Karnataka, and Tamil Nadu tier-2 cities. Remote specimen collection paired with centralized digital analysis offers a direct-to-patient acquisition channel outside established clinic-based procurement workflows. For Investors and Strategic Acquirers: The window for entry favors automated platform developers with FDA 510(k) clearance momentum and established reimbursement pathways. Acquisition targets should demonstrate ISO 13485 quality management systems and installed bases within consolidating United States fertility networks. Watch for FDA guidance document releases on AI-integrated assisted reproductive technology devices as an inflection signal for regulatory pathway clarity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Streamlines multi-jurisdiction market entry before EU MDR transition deadlines intensify notified body congestion. |
| AI Algorithm Development Partnership | Reduces inter-technician variability in morphology classification for high-volume fertility center networks. |
| Optical Component Supply Agreement | Secures priority allocation from Jena and Oberkochen precision lens manufacturers during demand surges. |
| Hospital System Partnership | Integrates andrology testing into oncology fertility preservation workflows for pre-surgical patient management. |
| Remote Collection Kit Launch | Opens patient acquisition channels outside traditional clinic-based procurement through at-home specimen logistics. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance timelines, EU MDR notified body capacity, and fertility clinic network consolidation patterns anchored the trend analysis, supplemented by interviews with reproductive endocrinologists, clinical laboratory scientists, biomedical equipment procurement managers, and optical component supply specialists. Secondary validation drew from FDA device classification databases, EUDAMED registration records, hospital GPO contract filings, and SEC 10-K disclosures from publicly traded laboratory equipment manufacturers. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices mapped equipment unit demand to fertility clinic expansion rates, reimbursement policy shifts, and technician training pipeline capacity across geographic markets. Segmentation dimensions modeled include product type tiers, application settings, technology sophistication levels, and end-user operator categories. CAGRs were derived from regression analysis of historical procurement patterns against projected network consolidation trajectories. Forecast inputs incorporated PMDA harmonization initiatives and CDSCO medical device registration tightening timelines.
Underlying measurement precision varies by segment; digital image analysis technology and automated semen analysis systems carry tighter precision than manual microscopy and incubator categories due to standardized performance validation protocols. Forecasts reflect documented assumptions regarding regulatory pathway stability and fertility clinic network consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
North America Life Science Tools Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Global Laboratory Centrifuge Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market