
 Low Endotoxin Gelatin Market | 2026-2036
Low Endotoxin Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Low Endotoxin Gelatin Market Outlook
The gap between pharmaceutical-grade and food-grade specifications is shifting procurement standards as biopharma buyers enforce endotoxin thresholds below 10 EU per gram. Rousselot leverages its European extraction footprint to supply certified low-endotoxin material for injectable applications. Gelita AG anchors its position through backward integration into collagen sourcing and in-house pyrogen testing. Trobas Gelatine BV specializes in small-batch pharmaceutical grades for Dutch and Belgian contract manufacturers.
Low endotoxin gelatin denotes highly purified collagen hydrolysate with bacterial endotoxin content controlled to pharmacopeial limits, typically manufactured through alkaline or acid extraction followed by ultrafiltration and sterile filtration. Its primary purpose centers on serving as a stabilizer, encapsulant, and cell-culture matrix in parenteral and regenerative medicine applications where pyrogenic contamination risks patient safety. Pharmaceutical-grade material commands the dominant margin pool due to batch certification costs and dedicated clean-room processing, while biomedical engineering applications represent the fastest-expanding demand segment as tissue-scaffold formulations multiply. Powder form leads volume consumption for bulk drug manufacturing, though capsule form captures premium pricing from oral-dose biologics developers.
FDA enforces endotoxin limits through 21 CFR 211 and USP chapter Bacterial Endotoxins Test, compelling manufacturers to maintain validated Limulus amebocyte lysate assay protocols for each production lot. EMA's Annex 1 revision on sterile manufacturing and the EU's Medical Device Regulation tighten traceability and pyrogen-control documentation across the supply chain. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP endotoxin methodologies, as divergent testing standards threaten cross-border batch acceptance and inventory allocation decisions.
Market Dynamics
FDA endotoxin testing requirements and evolving USP standards are compressing supplier margins while pharmaceutical-grade certification costs concentrate procurement among vertically integrated gelatin processors.
Growth Catalysts
- Parenteral drug formulation expansion:Injectable biologics and vaccines require endotoxin-controlled stabilizers, pulling demand from oral-dose applications into higher-margin parenteral grades.
- EMA Annex 1 revision on sterile manufacturing:The updated guidance tightens pyrogen-control documentation, forcing contract manufacturers to source certified low-endotoxin material for EU-bound products.
- Tissue engineering scaffold proliferation:Regenerative medicine applications multiply demand for pharmaceutical-grade gelatin as a cell-culture matrix, displacing synthetic alternatives in 3D bioprinting formulations.
Market Restraints
- Porcine and bovine raw material cost volatility:Collagen feedstock prices swing with livestock supply cycles and religious dietary restrictions, compressing processor margins during input spikes.
- German gelatin purification cluster concentration:European biopharma supply chains depend heavily on southwest German processing hubs, creating geographic single-point-of-failure risk.
- Acid and alkaline extraction energy intensity:Thermal processing and ultrafiltration steps consume substantial power, exposing manufacturers to electricity price shocks and carbon border adjustment mechanisms.
Strategic Opportunities
- Indian biologics manufacturing scale-up:CDSCO's tightening standards for injectable products create first-mover advantage for certified suppliers establishing local pyrogen-testing partnerships.
- Plant-based collagen hydrolysate convergence:Recombinant microbial collagen expression combined with endotoxin removal chromatography opens non-animal sourcing for halal and kosher markets.
- Direct-to-biotech distribution platforms:Specialized e-procurement channels for small-batch pharmaceutical grades bypass traditional distributor markups for Dutch and Belgian contract manufacturers.
Industry Challenges
- Limulus amebocyte lysate assay validation backlog:Each production lot requires documented LAL protocol compliance, stretching quality-control timelines and working capital cycles.
- Clean-room processing capex intensity:Dedicated sterile filtration infrastructure demands substantial upfront investment, raising barriers for mid-scale entrants.
- Pharmacopeial harmonization delays:Divergent endotoxin unit definitions between USP, EP, and JP methodologies complicate cross-border batch acceptance and inventory allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Endotoxin Gelatin Market |
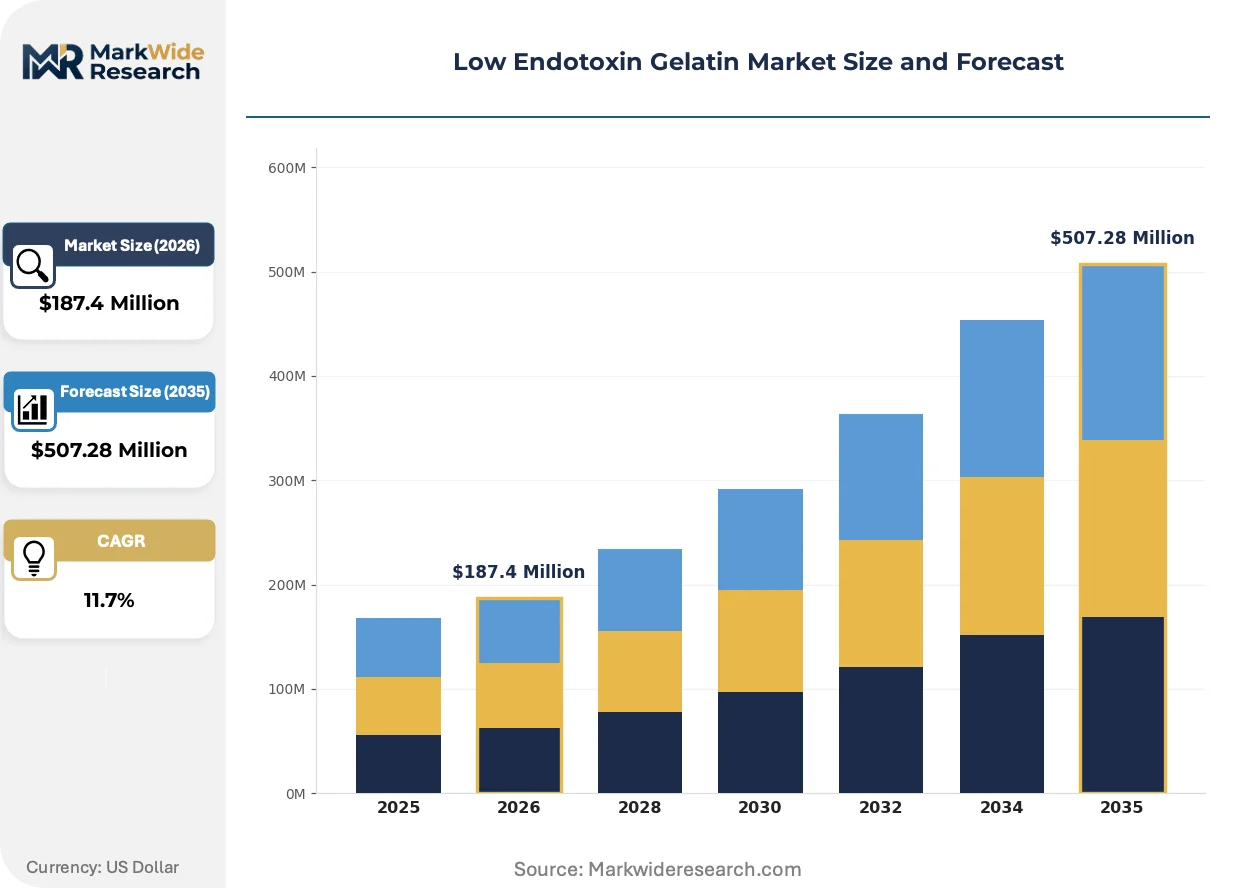
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Cosmetic Grade, Technical Grade Form: Powder, Sheet, Granule, Capsule Application: Drug Encapsulation, Biomedical Engineering, Nutraceuticals, Diagnostics End Use Industry: Pharmaceutical Manufacturers, Biomedical Firms, Cosmetic Companies, Diagnostic Laboratories |
| Companies Covered | Tessenderlo Group, Trobas Gelatine BV, Rousselot, Lapi Gelatine S.p.a., Ewald-Gelatine GmbH, Gelita AG, Weishardt Group, Junca Gelatines SL, Nitta Gelatin NA Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Endotoxin Gelatin Market Strategic Shifts
Single-use bioprocessing technologies and recombinant expression systems are restructuring how endotoxin-controlled materials reach pharmaceutical formulators. These shifts compress traditional supply relationships while opening alternative sourcing pathways.
Membrane-based endotoxin removal is consolidating as the dominant purification approach for high-value parenteral grades. Biologics manufacturers specify ultrafiltration-coupled sterile filtration for injectable stabilizers, displacing older chemical depyrogenation methods. This technology compression enables smaller batch sizes with faster turnaround, rewarding processors with modular clean-room footprints.
EMA's Medical Device Regulation tightened traceability requirements for materials contacting blood or tissue. Device manufacturers now demand batch-specific endotoxin certificates with full supply-chain documentation, forcing gelatin processors to invest in blockchain-enabled tracking systems. German and Swiss suppliers lead compliance adaptation, while smaller Dutch and Belgian processors lag in documentation infrastructure.
Biotech procurement teams now specify endotoxin thresholds below 10 EU per gram in master service agreements with contract manufacturers, bypassing traditional distributor quality guarantees. This specification compression shifts liability upstream to gelatin processors and concentrates volume among certified suppliers. The pattern is most visible in Netherlands-based cell-therapy developers, who source directly from Rousselot and Gelita AG rather than through regional distributors.
Low Endotoxin Gelatin Market Segmentation
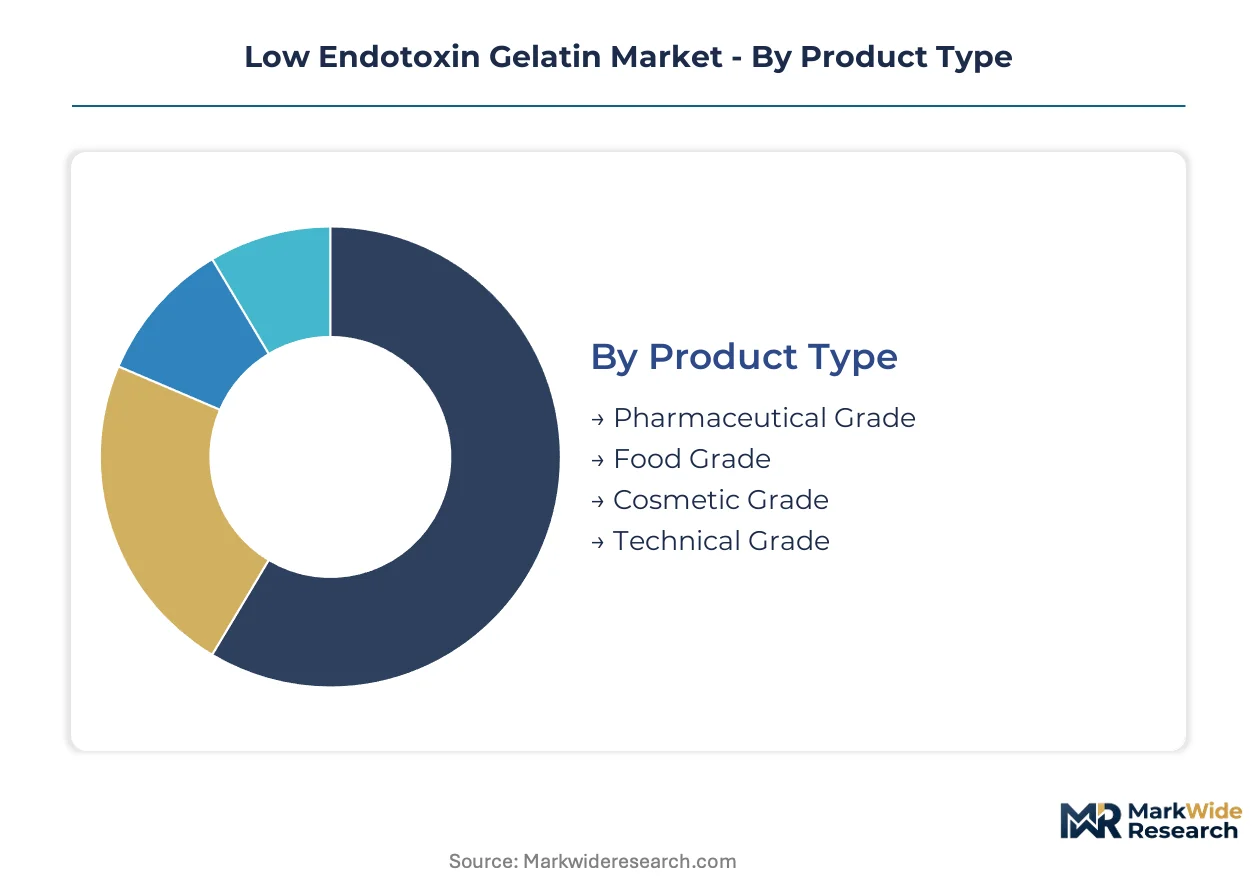
Endotoxin thresholds, processing complexity, and regulatory certification costs fragment procurement patterns across gelatin grades and forms. Buyers segment by validated pyrogen limits rather than nominal purity, concentrating volume among suppliers with documented LAL assay protocols.
Product Type:
Certification burden and batch-testing costs separate buyers into distinct procurement tiers.
- Pharmaceutical Grade:Highly purified collagen hydrolysate with endotoxin content controlled below 10 EU per gram through ultrafiltration and sterile filtration. Injectable biologics manufacturers in Germany and Switzerland enforce this specification in master service agreements, displacing food-grade alternatives from parenteral applications.
- Food Grade:Standard gelatin meeting basic purity specifications without validated endotoxin documentation. Nutraceutical formulators in the Netherlands and Belgium accept this grade for oral-dose products where pyrogenic risk is negligible, though tightening supplier audits are pushing some toward pharmaceutical-grade documentation.
- Cosmetic Grade:Intermediate purity tier for topical formulations requiring controlled microbial limits but not injectable-grade certification.
- Technical Grade:Unpurified gelatin for industrial applications with minimal biological testing requirements.
Pharmaceutical Grade leads volumes today; Cosmetic Grade is gaining share fastest as dermal filler applications multiply.
Form:
Processing flexibility and dissolution kinetics drive form selection across manufacturing scales.
- Powder:Dominant bulk format for drug manufacturing, enabling precise dosing and rapid hydration in aqueous systems. German parenteral drug facilities specify powder for large-scale stabilizer production, though dust containment adds clean-room infrastructure costs.
- Capsule:Pre-formed shells capturing premium pricing from oral-dose biologics developers in the Netherlands who require endotoxin-controlled encapsulation without in-house shell manufacturing. Two-piece hard capsules dominate over softgels for this specification tier.
- Sheet:Traditional format for photographic and specialty coating applications with declining pharmaceutical relevance.
- Granule:Intermediate particle size for controlled-release formulations and direct-compression tableting.
Powder maintains volume leadership; Capsule climbs the fastest as biologics outsourcing expands.
Application:
Regulatory scrutiny intensity and patient contact duration determine grade requirements across use cases.
- Drug Encapsulation:Primary revenue driver spanning hard capsules, softgels, and tablet binders. Swiss and German injectable manufacturers now require endotoxin documentation even for oral-dose excipients, elevating procurement standards across the category.
- Biomedical Engineering:Fastest-expanding demand segment as 3D bioprinting scaffolds and tissue-engineering matrices displace synthetic alternatives. Regenerative medicine startups in Belgium source pharmaceutical-grade gelatin for cell-culture substrates.
- Nutraceuticals:Dietary supplement applications with variable endotoxin requirements depending on delivery route.
- Diagnostics:Culture media and reagent stabilizers requiring controlled pyrogen levels for assay consistency.
Drug Encapsulation dominates current procurement; Biomedical Engineering shows steepest expansion trajectory.
End Use Industry:
Validation depth and supplier audit intensity distinguish procurement patterns across buyer categories.
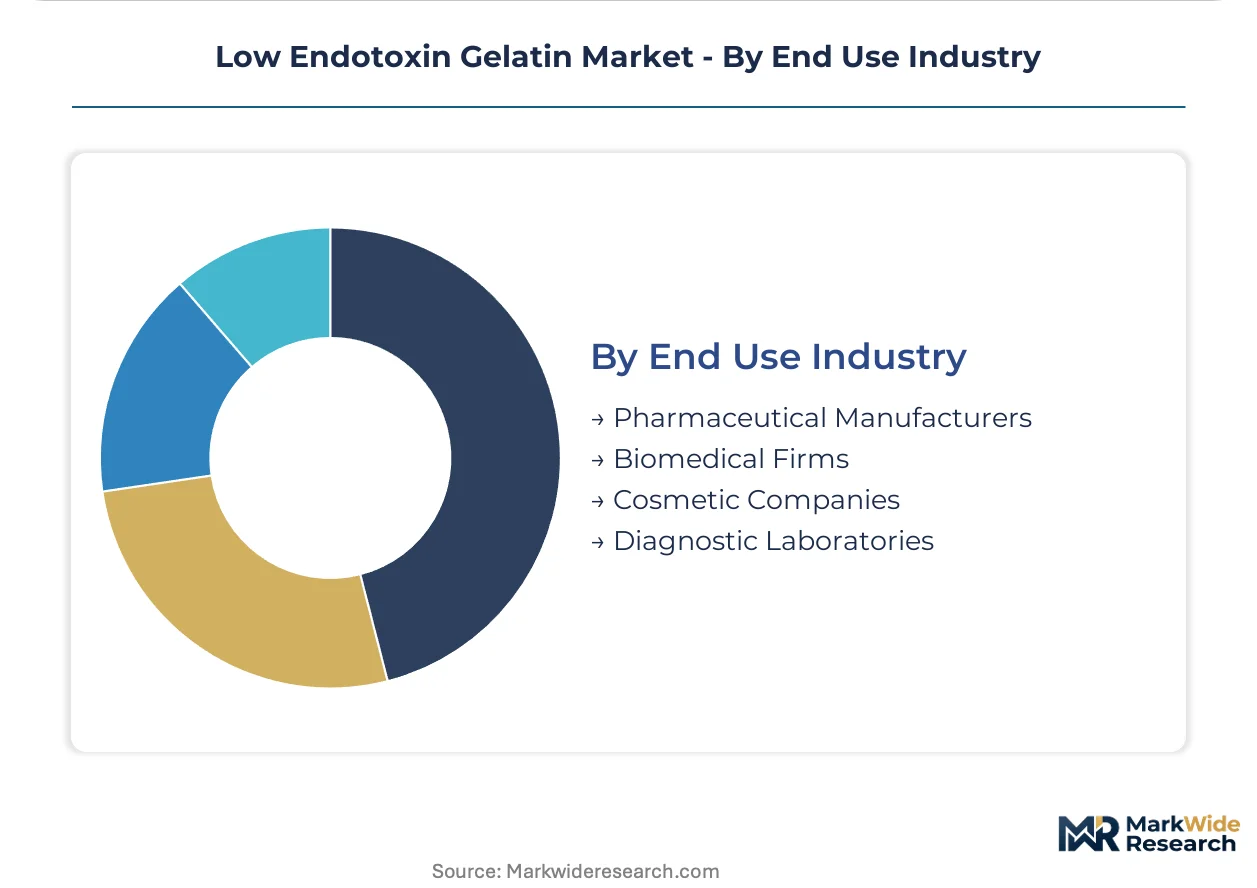
- Pharmaceutical Manufacturers:Most demanding buyer segment, requiring batch-specific endotoxin certificates, full supply-chain traceability, and documented LAL assay compliance. EMA Annex 1 revisions have tightened documentation requirements for EU-bound products.
- Biomedical Firms:Emerging high-growth segment with specialized needs for cell-culture matrices and implantable scaffolds. Device manufacturers now demand blockchain-enabled tracking systems under EU Medical Device Regulation.
- Cosmetic Companies:Intermediate tier with focus on topical safety rather than systemic pyrogen control.
- Diagnostic Laboratories:Quality-critical buyers for culture media and reagent components with assay-dependent specifications.
Pharmaceutical Manufacturers anchor current demand; Biomedical Firms are expanding most quickly as regenerative medicine scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled bioprocessing technicians cluster around southwest German purification hubs, while Belgian regenerative medicine startups and Dutch contract manufacturers anchor northwest European demand. Regulatory divergence between FDA, EMA, and national pharmacopeias shapes procurement patterns across major production centers.
Germany
Injectable biologics manufacturers in Baden-Württemberg and Bavaria drive pharmaceutical-grade consumption. EMA Annex 1 revisions on sterile manufacturing compel documented pyrogen-control protocols for every production lot. The Stuttgart-Mannheim corridor hosts concentrated gelatin purification clusters serving EU-wide biopharma supply chains.
United States
FDA 21 CFR 211 enforcement tightens endotoxin testing requirements for parenteral drug formulators. Boston and San Francisco biotech clusters specify endotoxin thresholds below 10 EU per gram in master service agreements. Massachusetts-based cell-therapy developers source directly from certified processors rather than traditional distributors.
Netherlands
CDMOs in Oss and Leiden expand demand for small-batch pharmaceutical grades. The Dutch national pharmaceutical regulator aligns with EMA guidance on traceability documentation for materials contacting blood or tissue. Rotterdam distribution hubs facilitate just-in-time delivery to Belgian and German contract manufacturers.
Belgium
Regenerative medicine startups in Flanders source pharmaceutical-grade gelatin for 3D bioprinting scaffolds and tissue-engineering matrices. EU Medical Device Regulation mandates blockchain-enabled tracking systems for implantable materials. The Leuven-Ghent corridor concentrates biomedical engineering R&D driving fastest-expanding demand segment.
India
CDSCO tightening standards for injectable products create procurement upgrade pressure across Mumbai and Hyderabad biologics facilities. The country's national pharmaceutical regulator enforces endotoxin documentation parity with USP and EP methodologies. Maharashtra and Telangana manufacturing scale-up attracts first-mover certified suppliers establishing local pyrogen-testing partnerships.
Low Endotoxin Gelatin Market Competitive Environment
Capital-heavy producers compete with asset-light specialty refiners across tiered certification levels. The supplier base concentrates among vertically integrated collagen processors with captive raw material sourcing and dedicated clean-room infrastructure. Three archetypes dominate: pan-European integrated processors with backward control over livestock supply chains, regional specialists serving national CDMO markets, and Asian-scale manufacturers competing on volume for oral-dose applications. Competitive dynamics center on pharmacopeial certification breadth and M&A-driven geographic expansion into emerging biologics manufacturing clusters.
Among European integrated processors, Rousselot and Gelita AG exemplify archetypes with extensive extraction footprints and in-house pyrogen testing capabilities. Trobas Gelatine BV occupies a position within the regional specialist tier, serving Dutch and Belgian contract manufacturers with small-batch pharmaceutical grades. These three entities represent distinct competitive positioning strategies: scale-driven certification breadth, upstream integration depth, and geographic-specialization focus respectively.
| Leading Market Players |
|---|
| Tessenderlo Group |
| Trobas Gelatine BV |
| Rousselot |
| Lapi Gelatine S.p.a. |
| Ewald-Gelatine GmbH |
| Gelita AG |
| Weishardt Group |
| Junca Gelatines SL |
| Nitta Gelatin NA Inc |
| Others |
Value Chain & Pricing Dynamics
Skilled bioprocessing technicians clustering around southwest German purification hubs command wage premiums that compress margins for mid-tier processors while widening spreads between pharmaceutical-grade and food-grade pricing tiers. Labor-cost differentials between certified clean-room facilities in Germany and standard processing plants in Eastern Europe drive a three-tier pricing structure across premium, standard, and economy levels, with buyers in Belgium and the Netherlands arbitraging these spreads through selective sourcing.
Pricing Analysis
Certified batch testing bundled with ultrafiltration and sterile filtration commands premium positioning against unbundled material-only supply. Price differentiation hinges on endotoxin documentation depth and validated LAL assay inclusion, with pharmaceutical-grade certifications capturing substantial markups over food-grade alternatives. Pricing pressure stems from EMA Annex 1 compliance costs transferring downstream to contract manufacturers. Large-volume parenteral drug facilities in Germany exhibit lowest price sensitivity, while Dutch nutraceutical formulators negotiate aggressively on oral-dose grades.
Supply Chain Analysis
Freight cost exposure concentrates around refrigerated transport of collagen feedstock from slaughterhouses to processing facilities, with fuel price volatility amplifying margin risk for non-integrated processors. Supply concentrates in Germany, the Netherlands, and Belgium, with raw material sourcing drawing from porcine and bovine byproduct streams across European livestock markets. Single-source vulnerability looms where southwest German hubs handle EU-wide pharmaceutical-grade output. Distribution runs through Rotterdam and Antwerp logistics nodes serving just-in-time biopharma manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in this market rests on membrane-based endotoxin removal technology driving down certification costs per batch while biologics manufacturers absorb premium-tier pricing for parenteral grades.
For Market Incumbents: Deepen backward integration into collagen sourcing to insulate margins from livestock feedstock volatility threatening Rousselot and Gelita AG. Expand clean-room capacity in the Stuttgart-Mannheim corridor to capture EMA Annex 1 compliance demand from Belgian and Dutch contract manufacturers. Prioritize blockchain-enabled traceability systems ahead of EU Medical Device Regulation enforcement timelines. For New Entrants and Emerging Players: A 40-60% price-point gap between pharmaceutical-grade and food-grade tiers opens white-space opportunity in certified small-batch supply for Netherlands-based cell-therapy developers. Target Indian biologics manufacturing scale-up in Maharashtra and Telangana where CDSCO tightening standards outpace local pyrogen-testing capacity. Pursue direct-to-biotech distribution partnerships bypassing traditional distributor markups. For Investors and Strategic Acquirers: Pharmaceutical CDMOs are the most active acquirer in this space, seeking captive gelatin supply to secure endotoxin-controlled material for injectable contract manufacturing. Long-term viability favors processors with modular clean-room footprints enabling rapid batch turnaround for tissue-engineering scaffold applications. Watch for CDSCO enforcement parity with USP and EP methodologies as the inflection signal for Indian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collagen Sourcing | Captive raw material supply insulates margins from porcine and bovine price cycles. |
| Modular Clean-Room Capacity Expansion | Flexible batch sizing captures small-volume regenerative medicine demand in Belgium. |
| Blockchain-Enabled Traceability Deployment | Full supply-chain documentation satisfies EU Medical Device Regulation for implantable scaffolds. |
| Direct-to-Biotech Distribution Platform | Bypasses traditional distributor markups for Dutch and Belgian contract manufacturers. |
| Local Pyrogen-Testing Partnership in India | CDSCO compliance capability unlocks first-mover position in Mumbai and Hyderabad biologics clusters. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gelatin processing plant managers, pharmaceutical procurement leads at German and Swiss parenteral drug facilities, regulatory affairs specialists at EMA-notified bodies, and biomedical engineering R&D directors at Belgian regenerative medicine startups. Secondary validation drew from FDA 21 CFR 211 guidance documents, EMA Annex 1 revision drafts, USP chapter Bacterial Endotoxins Test methodologies, and customs trade data for collagen hydrolysate imports. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates across the analysis window.
Historical reference periods anchored the forecast framework to pre-pandemic baseline demand patterns and post-2020 biologics manufacturing expansion trajectories. The analytical framework modeled segmentation across product grade tiers, application categories spanning drug encapsulation to biomedical engineering, end-use industry clusters, and regional regulatory environments. CAGRs derived from fitted growth curves incorporating parenteral drug formulation expansion rates and tissue-engineering scaffold proliferation trends. Forecast inputs included EMA Annex 1 implementation timelines and CDSCO enforcement intensity projections.
Caveats apply where pharmacopeial harmonization delays between USP, EP, and JP methodologies could materially shift the outlook for cross-border batch acceptance. Forecasts reflect assumptions around livestock supply cycle stability and electricity price trajectories affecting thermal processing economics. A model refresh is warranted upon material change in EMA Medical Device Regulation enforcement or CDSCO injectable standards parity timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Lab Centrifuges Market
Biotechnology Equipment
Automated Colony Picking Systems Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Airlift Bioreactors Market
Biotechnology Equipment
Automated Cell Counting Market